
 Digital Companion Diagnostics Market | 2026-2036
Digital Companion Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Companion Diagnostics Market Analysis
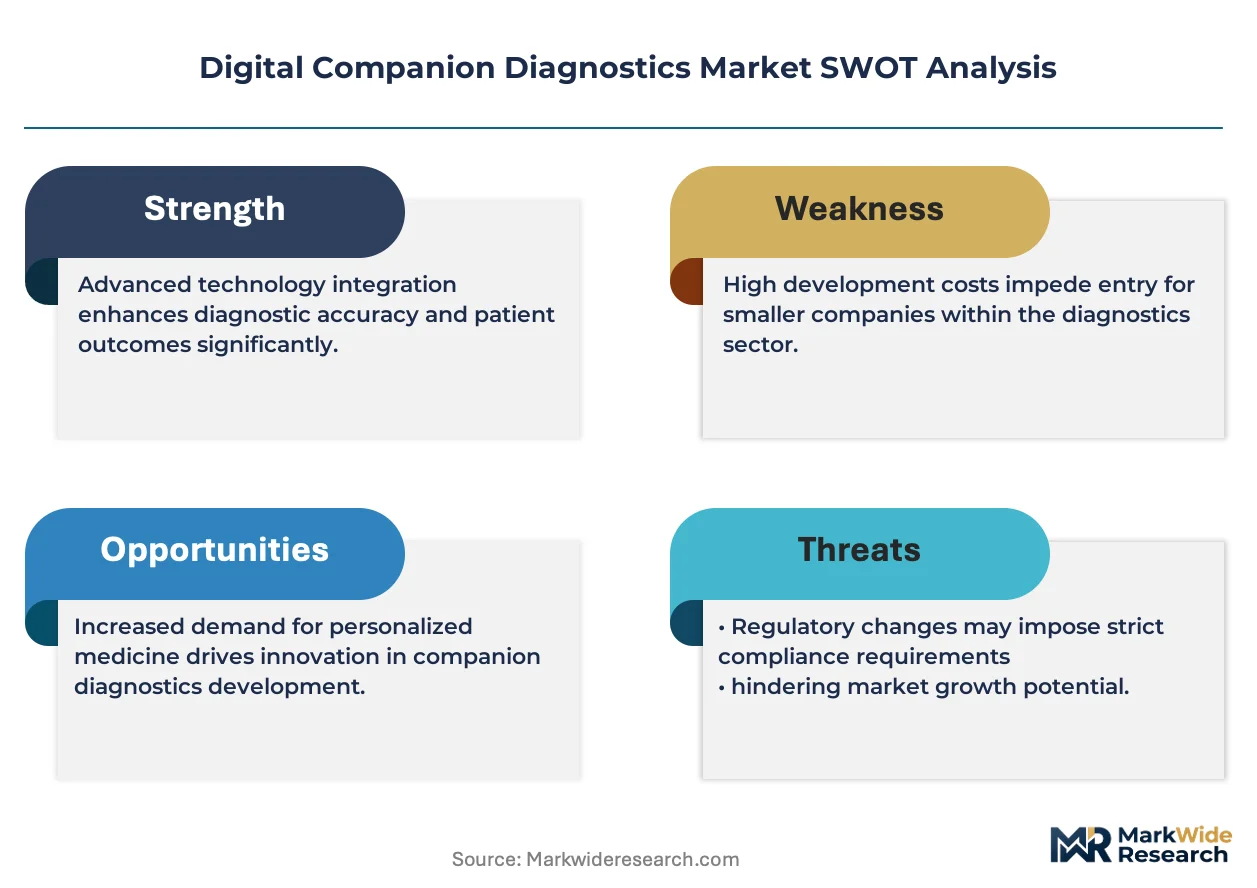
The EU AI Act is decoupling diagnostic algorithm approval from traditional device pathways, forcing developers to validate clinical decision support tools under new conformity frameworks. Thermo Fisher Scientific leverages its laboratory informatics infrastructure to anchor cloud-based companion diagnostic workflows across European oncology networks. Illumina competes by extending its sequencing platforms into integrated software solutions that link genomic data to therapy selection protocols. F. Hoffmann-La Roche Ltd dominates the European market through its established in-vitro diagnostic regulatory track record and companion test portfolio.
Digital companion diagnostics comprise software platforms, algorithms, and connected devices that analyze patient-specific biomolecular or clinical data to identify optimal therapeutic interventions, typically operating through real-time data integration with electronic health records and laboratory information management systems. Artificial Intelligence and Machine Learning segments lead technology adoption, as these modalities enable pattern recognition across multimodal patient datasets that rule-based systems cannot process, while Cloud Computing infrastructure sustains the fastest growth trajectory by enabling scalable deployment across distributed hospital networks without on-premise hardware investment. Decision Support Tools command the strongest margin pools among product types, given their integration into pharmaceutical co-development agreements and recurring licensing structures.
The FDA's Software as a Medical Device framework, the EU AI Act risk-classification system for clinical decision support, and HIPAA data interoperability standards collectively determine market access conditions, reimbursement eligibility, and cross-border deployment feasibility for digital companion platforms. EMA's evolving qualification pathway for novel methodologies further shapes how developers structure validation studies for algorithm-driven diagnostics seeking European market authorization. Stakeholders must monitor how divergent transatlantic regulatory timelines for AI-enabled diagnostics reshape partnership strategies between platform developers and pharmaceutical sponsors.
Market Dynamics
Algorithmic therapy selection tools are absorbing capital allocation from pharmaceutical sponsors as FDA's Software as a Medical Device framework clarifies reimbursement pathways for cloud-deployed diagnostics. This regulatory clarity compresses validation timelines and redirects R&D budgets toward multimodal biomarker platforms.
Growth Catalysts
- FDA Precision Medicine Guidance:The agency's algorithm-based diagnostic pathway accelerates market authorization for AI-enabled companion tools, reducing regulatory friction for developers seeking therapeutic co-labeling agreements.
- Cloud Infrastructure Penetration:Distributed hospital networks in the United States deploy scalable diagnostic platforms without on-premise hardware investment, lowering capital barriers for mid-sized oncology centers.
- Electronic Health Record Integration:Real-time data interoperability standards enable seamless biomarker-to-therapy matching workflows, embedding decision support tools into routine clinical practice.
Market Restraints
- EU AI Act Conformity Costs:Clinical decision support tools face decoupled approval pathways from traditional device frameworks, forcing developers to maintain parallel validation studies for transatlantic deployment.
- Biomolecular Data Silos:Laboratory information management systems operate on proprietary formats, fragmenting patient datasets across health systems and degrading algorithm training quality.
- Specialized Talent Scarcity:Computational pathology and regulatory science expertise concentrates in Boston and San Francisco clusters, inflating compensation costs for platform developers.
Strategic Opportunities
- Underpenetrated Community Oncology:Rural and suburban health systems in the United States lack integrated genomic-to-therapy workflows, creating whitespace for cloud-based diagnostic platforms with simplified deployment protocols.
- EMA Qualification Pathway:The agency's evolving novel methodologies framework offers first-mover advantages for developers structuring prospective validation studies for algorithm-driven diagnostics seeking European authorization.
- Pharmaceutical Co-Development:Biopharma sponsors increasingly license decision support tools alongside therapeutic candidates, embedding recurring revenue structures into companion diagnostic business models.
Industry Challenges
- Multimodal Data Harmonization:Integrating genomic, proteomic, and clinical data streams requires specialized bioinformatics pipelines that few health systems maintain in-house.
- HIPAA Interoperability Compliance:Cross-border patient data transfers face fragmented state-level privacy interpretations, complicating cloud deployment architectures for multinational diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Companion Diagnostics Market |
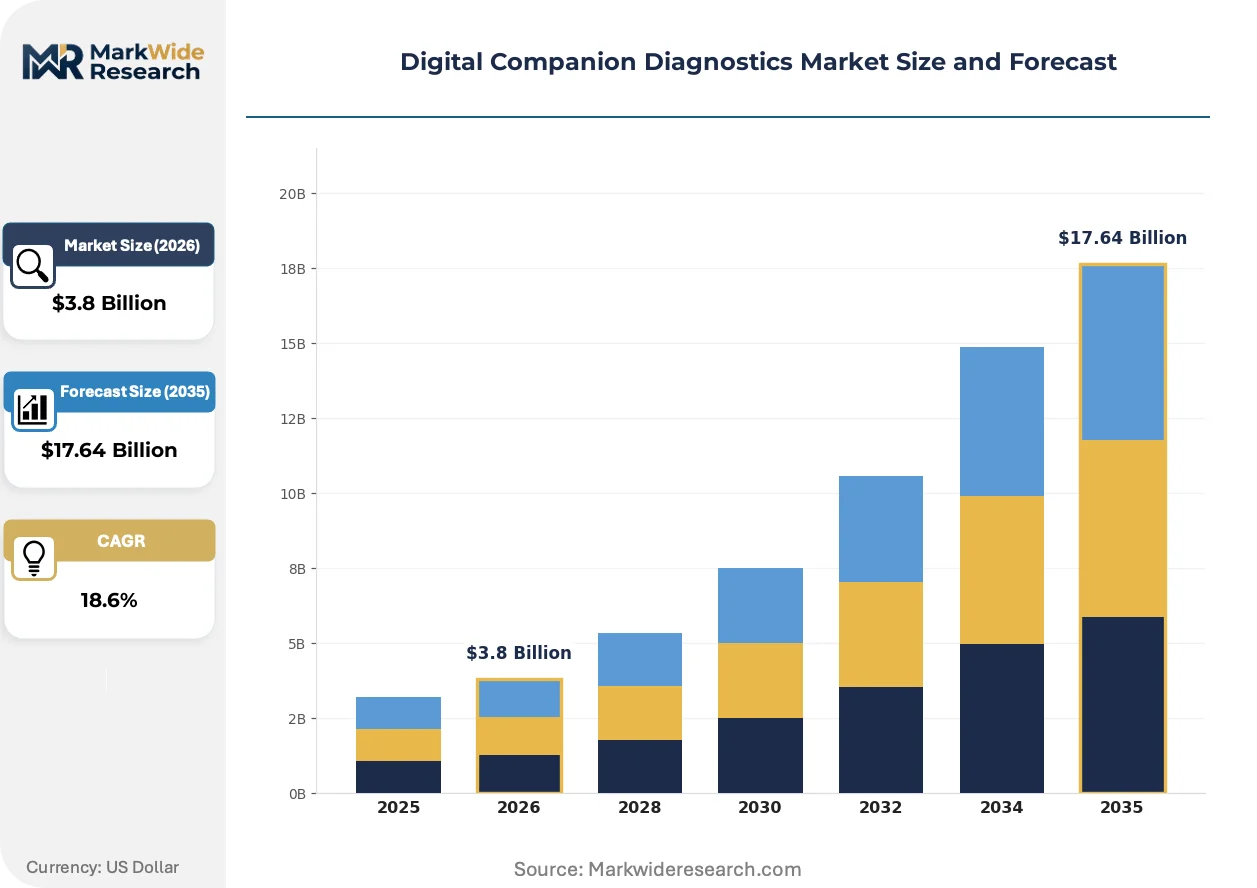
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Mobile Applications, Wearable Devices, Decision Support Tools End User: Clinics, Hospitals, Research Laboratories, Pharmaceutical Companies Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Data Analytics Application: Personalized Medicine, Disease Detection, Treatment Monitoring, Patient Management |
| Companies Covered | Thermo Fisher Scientific Inc., Myriad Genetics, Inc., F. Hoffmann-La Roche Ltd, NanoString Technologies, Inc., Foundation Medicine, Inc., Agilent Technologies, Inc., Illumina, Inc., Guardant Health, Inc., QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Companion Diagnostics Market Emerging Trajectories
Artificial intelligence architectures are absorbing functionality from rule-based diagnostic systems, compressing the competitive window for established biomarker interpretation workflows. This technological rotation demands continuous model retraining infrastructure and specialized hardware investments.
Machine learning pattern recognition is absorbing multimodal patient analysis tasks that deterministic algorithms cannot execute, enabling therapy selection across complex oncology indications. Academic medical centers in the United States deploy these platforms for prospective patient stratification, compressing clinical trial enrollment timelines for targeted therapeutics. The technology is absorbing market share from single-biomarker companion tests by delivering superior predictive accuracy across heterogeneous patient populations.
The EU AI Act risk-classification system restructures how clinical decision support tools achieve European market access, elevating conformity assessment requirements for high-risk diagnostic algorithms. Developers must now validate algorithmic transparency and human oversight protocols alongside clinical performance metrics. Oncology networks in Germany and France delay procurement decisions pending clarity on notified body designation timelines, compressing near-term revenue recognition for platform vendors.
Integrated health systems in the United States consolidate diagnostic procurement under centralized value-analysis committees, displacing decentralized purchasing by individual pathology departments. These committees prioritize platforms with demonstrated total cost-of-care reduction and pharmaceutical sponsorship alignment. Community hospital networks in Texas and Florida exhibit the fastest adoption velocity, driven by competitive pressure from academic referral centers.
Digital Companion Diagnostics Market Segmentation
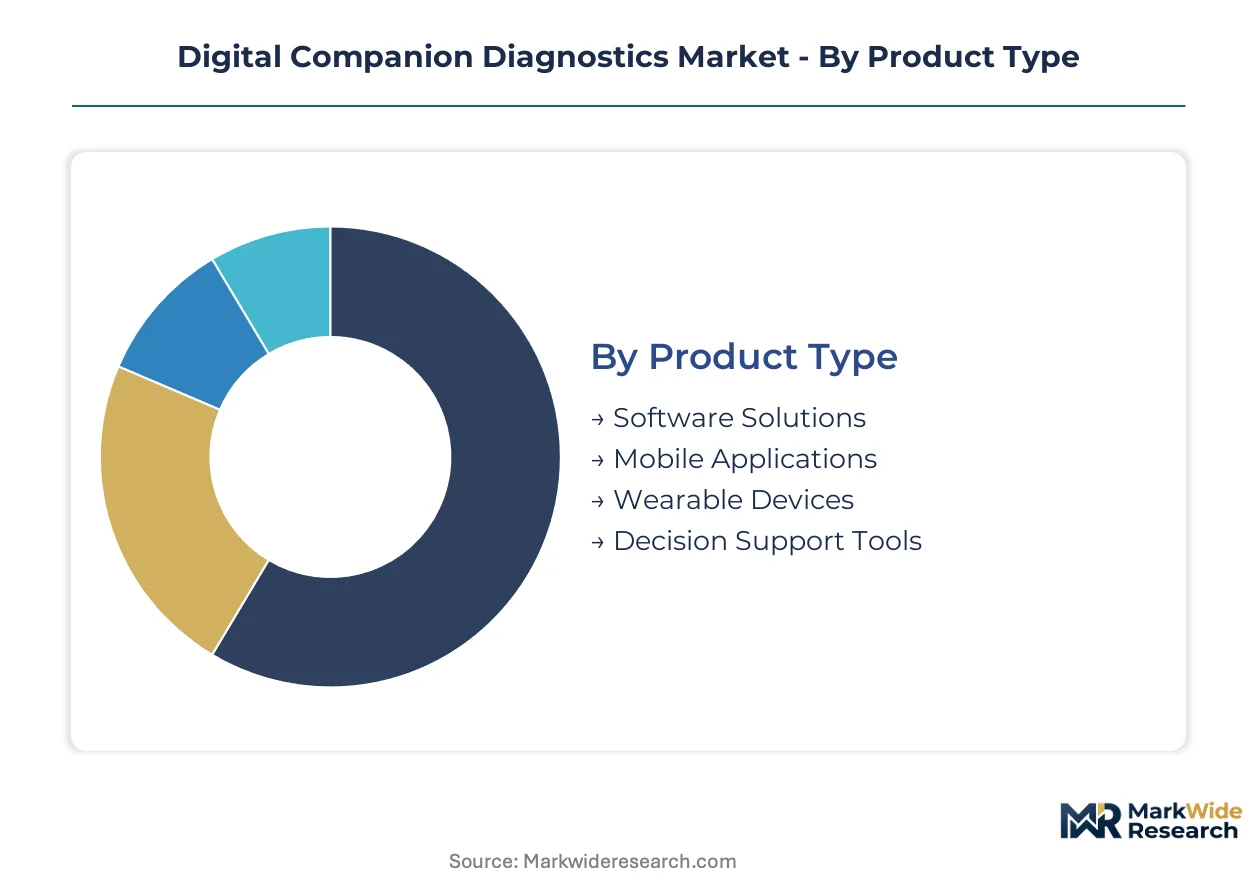
Segmentation reveals how procurement authority and technology architecture reshape vendor go-to-market strategies across the digital companion diagnostics value chain. Buyers prioritize integration depth, regulatory pre-certification, and pharmaceutical sponsorship alignment when selecting platform components.
Product Type:
Purchasing committees differentiate platforms by deployment complexity and recurring revenue potential rather than upfront licensing fees alone.
- Decision Support Tools:Clinical decision support platforms integrate directly into electronic health record workflows, embedding therapy selection algorithms at the point of care. Pharmaceutical sponsors in the United States license these tools alongside therapeutic candidates, creating recurring revenue structures that standalone software vendors cannot replicate.
- Software Solutions:Cloud-deployed diagnostic platforms analyze multimodal biomolecular data through proprietary algorithms, requiring continuous model retraining infrastructure. Academic medical centers in Boston and San Francisco deploy these systems for prospective patient stratification, compressing clinical trial enrollment timelines.
- Mobile Applications:Patient-facing therapy adherence and symptom reporting tools extend diagnostic workflows beyond clinical settings.
- Wearable Devices:Connected biosensors enable real-time therapeutic monitoring and pharmacodynamic response tracking.
Decision Support Tools lead volumes today; Software Solutions is gaining share fastest.
End User:
Site-of-care economics and data infrastructure maturity determine platform configuration requirements across customer types.
- Hospitals:Integrated health systems consolidate diagnostic procurement under centralized value-analysis committees, prioritizing platforms with demonstrated total cost-of-care reduction. Community hospital networks in Texas and Florida exhibit rapid adoption velocity as competitive pressure from academic referral centers intensifies.
- Pharmaceutical Companies:Biopharma sponsors absorb algorithmic therapy selection tools into co-development agreements, redirecting R&D budgets toward multimodal biomarker platforms. FDA's Software as a Medical Device framework clarifies reimbursement pathways, compressing validation timelines for cloud-deployed diagnostics.
- Clinics:Outpatient oncology practices require simplified deployment protocols for cloud-based diagnostic platforms.
- Research Laboratories:Academic and commercial labs focus on biomarker discovery and algorithm training dataset generation.
Hospitals dominate current procurement volumes; Pharmaceutical Companies are expanding platform partnerships most aggressively.
Technology:
Computational modality selection hinges on pattern recognition complexity and regulatory classification risk under FDA and EU AI Act frameworks.
- Artificial Intelligence:Deep learning architectures absorb functionality from rule-based diagnostic systems, executing therapy selection across complex oncology indications that deterministic algorithms cannot process. AI-enabled platforms deliver superior predictive accuracy across heterogeneous patient populations, displacing single-biomarker companion tests.
- Cloud Computing:Distributed infrastructure sustains scalable deployment across hospital networks without on-premise hardware investment, lowering capital barriers for mid-sized oncology centers. Germany and France delay procurement decisions pending EU AI Act notified body designation clarity.
- Machine Learning:Supervised learning models require structured training datasets from integrated laboratory information management systems.
- Data Analytics:Descriptive and predictive analytics tools process retrospective patient cohorts for biomarker validation.
Artificial Intelligence anchors current platform development; Cloud Computing is climbing the fastest as distributed deployment architectures mature.
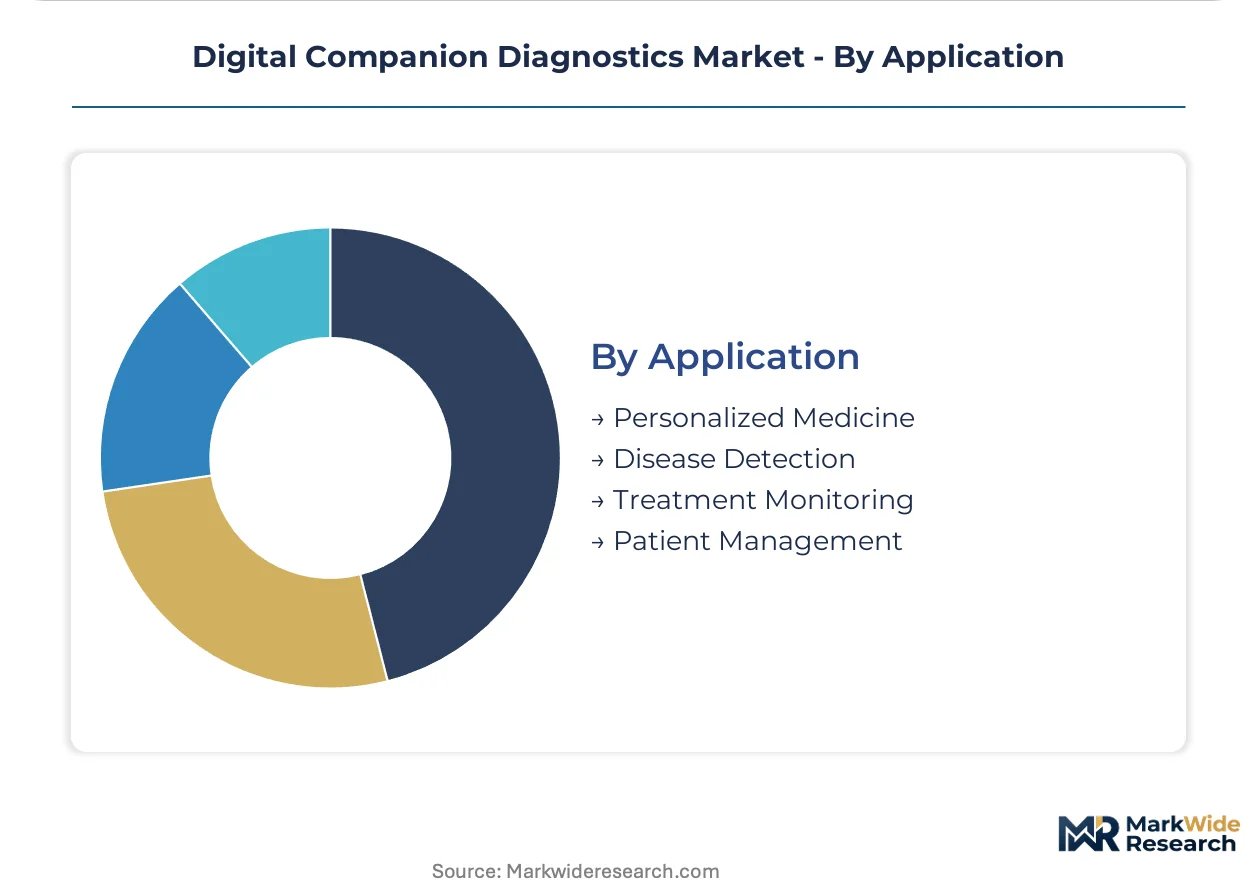
Application:
Clinical utility and reimbursement pathway certainty shape therapeutic area prioritization for diagnostic developers.
- Personalized Medicine:Biomarker-guided therapy selection protocols match patient molecular profiles to targeted therapeutic interventions, embedding decision support into routine oncology practice. FDA precision medicine guidance accelerates market authorization for algorithm-based companion tools.
- Treatment Monitoring:Real-time pharmacodynamic response assessment enables adaptive dosing protocols and early resistance detection. Cloud-based platforms integrate wearable biosensor streams with electronic health records for continuous therapeutic optimization.
- Disease Detection:Early-stage diagnostic algorithms identify molecular signatures preceding symptomatic presentation.
- Patient Management:Care coordination tools track adherence, adverse events, and quality-of-life metrics across treatment courses.
Personalized Medicine commands the largest addressable opportunity; Treatment Monitoring is expanding most quickly as continuous care models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital companion diagnostics industry originated in the United States during the early 2010s, when FDA began formalizing precision medicine guidance for algorithm-based therapy selection tools. Academic medical centers in Boston and San Francisco pioneered the first integrated genomic-to-clinical data workflows, establishing the regulatory and technical templates now diffusing across major healthcare markets.
United States
Integrated health systems in Texas and Florida deploy cloud-based diagnostic platforms at the fastest adoption velocity, driven by competitive pressure from academic referral centers. FDA's Software as a Medical Device framework clarifies reimbursement pathways for algorithm-enabled companion tools, compressing validation timelines for pharmaceutical co-development agreements. The Boston and San Francisco metropolitan clusters concentrate computational pathology talent and regulatory science expertise, inflating compensation costs for platform developers seeking specialized hires.
Germany
Oncology networks in Bavaria and North Rhine-Westphalia delay procurement decisions pending clarity on EU AI Act notified body designation timelines for high-risk diagnostic algorithms. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on parallel conformity assessment pathways that decouple software approval from traditional medical device frameworks. Munich and Heidelberg anchor Europe's densest concentration of laboratory informatics infrastructure, where Thermo Fisher Scientific deploys cloud-based companion diagnostic workflows.
United Kingdom
The Greater London health economy consolidates diagnostic procurement under centralized value-analysis committees that prioritize platforms with demonstrated total cost-of-care reduction. MHRA's post-Brexit regulatory framework diverges from EU AI Act risk-classification timelines, forcing developers to maintain separate validation studies for British market authorization. Cambridge and Oxford host academic-industry partnerships linking genomic data platforms to pharmaceutical sponsor networks.
France
Paris-based hospital networks integrate decision support tools into electronic health record workflows under ANSM oversight of clinical algorithm performance transparency requirements. The EU AI Act elevates conformity assessment burdens for AI-enabled therapy selection platforms, compressing near-term revenue recognition for vendors awaiting notified body clarity. Lyon and Strasbourg concentrate precision medicine research infrastructure where Illumina extends sequencing platforms into software solutions linking genomic data to therapy protocols.
Japan
PMDA's evolving qualification pathway for novel methodologies shapes how developers structure prospective validation studies for algorithm-driven diagnostics seeking Asian market authorization. Tokyo and Osaka metropolitan areas deploy machine learning pattern recognition platforms for prospective patient stratification in oncology clinical trials. Pharmaceutical sponsors in Japan absorb algorithmic therapy selection tools into co-development agreements, redirecting R&D budgets toward multimodal biomarker platforms compatible with domestic regulatory timelines.
Digital Companion Diagnostics Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the digital companion diagnostics value chain. Thermo Fisher Scientific and Illumina anchor the infrastructure-intensive tier with laboratory informatics and sequencing platform investments, while specialized software vendors operate without captive hardware manufacturing. The market structure fragments across three strategic archetypes: integrated diagnostic-platform conglomerates, pure-play algorithm developers, and pharmaceutical-captive tool builders. Dominant competitive moves include technology licensing agreements that embed decision support into electronic health record workflows, and strategic partnerships that secure pharmaceutical co-development sponsorship.
Within the integrated diagnostic-platform tier, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd occupy positions reflecting divergent geographic regulatory track records. Thermo Fisher leverages its laboratory informatics infrastructure to anchor cloud-based workflows across European oncology networks. Roche dominates European market access through its established in-vitro diagnostic regulatory history and companion test portfolio. Illumina, Inc. exemplifies the sequencing-to-software extension archetype, competing by linking genomic data platforms to therapy selection protocols rather than building clinical decision support from standalone codebases.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Myriad Genetics, Inc. |
| F. Hoffmann-La Roche Ltd |
| NanoString Technologies, Inc. |
| Foundation Medicine, Inc. |
| Agilent Technologies, Inc. |
| Illumina, Inc. |
| Guardant Health, Inc. |
| QIAGEN |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity requirements for high-risk clinical decision support algorithms gate qualified supply to European oncology networks and anchor premium-tier pricing for validated platforms. Developers absorbing parallel FDA and EMA validation costs pass these through to pharmaceutical sponsors, while cloud infrastructure providers compete on deployment scalability rather than algorithm performance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-captive platforms with co-development revenue from standalone software vendors and basic decision support modules. Price differentiation rests on FDA pre-certification status and EMA qualification pathway progress, with cloud computing infrastructure costs compressing margins at the economy tier. Pricing pressure stems from EU AI Act notified body designation delays freezing procurement decisions in Germany and France. Community hospital networks in Texas and Florida exhibit highest price sensitivity; integrated health systems with centralized value-analysis committees demonstrate lowest.
Supply Chain Analysis
Direct-to-pharmaceutical-sponsor channels handle co-development agreement demand, while cloud service provider partnerships reach mid-sized oncology centers lacking in-house infrastructure. Algorithm training data concentrates in the United States, Germany, and Japan, where academic medical centers generate prospective patient cohorts. Computational pathology expertise clusters in Boston and San Francisco, creating single-source vulnerability for specialized talent. Distribution runs through laboratory informatics vendors and electronic health record integration specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital companion diagnostics market compounds steadily as FDA precision medicine guidance clarifies reimbursement pathways for algorithm-based therapy selection tools. Pharmaceutical R&D budget reallocation toward multimodal biomarker platforms sustains platform vendor revenue visibility.
For Market Incumbents: Deploy laboratory informatics infrastructure as the anchor lever to defend against sequencing-platform competitors extending into software solutions. Thermo Fisher Scientific's cloud-based workflow anchoring across European oncology networks exemplifies this defensive positioning. Capture pharmaceutical co-development agreements before FDA Software as a Medical Device framework fully matures and commoditizes validation timelines. For New Entrants and Emerging Players: Machine learning pattern recognition for multimodal patient analysis offers entry into underpenetrated community oncology networks in rural and suburban United States health systems. These sites lack integrated genomic-to-therapy workflows and face competitive pressure from academic referral centers. Pursue simplified deployment protocols with minimal on-premise hardware requirements as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized algorithm developers because EMA's evolving novel methodologies pathway fragments European market access and rewards scale in regulatory science capabilities. Target pure-play computational pathology firms with FDA pre-submission meeting history and cloud-native architectures. Watch EU AI Act notified body designation timelines as the signal for European revenue recognition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Co-Development Agreement | FDA's Software as a Medical Device framework clarifies reimbursement pathways for cloud-deployed diagnostics. |
| EMA Qualification Pathway Submission | Novel methodologies framework offers first-mover advantages for algorithm-driven diagnostics seeking European authorization. |
| Electronic Health Record Integration Partnership | Real-time data interoperability standards embed decision support tools into routine clinical practice workflows. |
| Cloud Infrastructure Expansion | Distributed hospital networks deploy scalable diagnostic platforms without on-premise hardware investment barriers. |
| Computational Pathology Talent Acquisition | Boston and San Francisco clusters concentrate specialized expertise, inflating compensation costs for platform developers. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, France, and Japan, with primary inputs from each regional cluster combining executive interviews with regulatory affairs leads, hospital procurement managers, and pharmaceutical development executives. Secondary validation draws from FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov records, and hospital GPO contract databases. Bottom-up platform deployment counts triangulate against top-down pharmaceutical R&D budget allocation estimates.
Granularity-level modeling segments by product type, end user, technology, and application dimensions across the projection horizon. Deployment velocity curves for cloud computing infrastructure and AI-enabled platforms inform technology segment trajectories. CAGRs derive from pharmaceutical co-development agreement flow analysis and health system procurement pipeline tracking. Patient stratification algorithm performance benchmarks and regulatory pathway timeline distributions anchor forecast confidence intervals.
The model holds under continued FDA precision medicine guidance implementation and stable pharmaceutical R&D spending; deviation in EU AI Act notified body designation timelines or HIPAA interoperability standard fragmentation would shift European revenue recognition patterns. Periodic stress-testing of base assumptions is recommended given regulatory science expertise concentration risk and cross-border data transfer policy evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Liver Function Tests Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Immunoassay Market