
 Middle East and Africa Lung Cancer Diagnostics Market | 2026-2036
Middle East and Africa Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lung Cancer Diagnostics Market Foresight
Equipment leasing and pay-per-test contracting is fragmenting competitive dynamics across the Middle East and Africa lung cancer diagnostics landscape. F. Hoffmann-La Roche Ltd. leverages its centralized diagnostics platform to anchor high-throughput biomarker workflows in tertiary hospitals. Thermo Fisher Scientific Inc. competes through distributed reagent supply agreements that reduce capital barriers for mid-size laboratories. Abbott sustains point-of-care molecular testing penetration via instrument placement programs tied to consumable minimums.
Lung cancer diagnostics encompasses imaging modalities, tissue acquisition techniques, and molecular characterization methods used to detect, subtype, and stage pulmonary malignancies; CT scanning delivers spatial resolution below one millimeter to identify subsolid nodules, while next-generation sequencing of circulating tumor DNA enables genotyping without invasive biopsy. Biomarker testing represents the fastest-expanding segment as EGFR, ALK, and PD-L1 companion diagnostics become prerequisites for targeted therapy selection across the region's growing oncology programs. Imaging maintains the largest installed base but faces margin compression as reimbursement shifts toward molecularly-informed treatment pathways.
South Africa's Health Products Regulatory Authority, Egypt's Drug Authority, and Saudi Arabia's SFDA each maintain distinct in-vitro diagnostic registration frameworks that shape product launch sequencing and clinical evidence requirements for manufacturers. SFDA's alignment with FDA breakthrough device pathways accelerates market access for novel liquid biopsy platforms, while Egypt's localization incentives redirect supply chain investments toward regional manufacturing partnerships. Stakeholders must monitor evolving reimbursement policies for precision oncology tests as national health insurance schemes across the region weigh cost-effectiveness against expanded access mandates.
Market Dynamics
Equipment leasing and pay-per-test contracting are fragmenting competitive dynamics across the Middle East and Africa lung cancer diagnostics landscape, as manufacturers reposition from capital sales to recurring revenue models anchored by consumable minimums and instrument placement programs.
Growth Catalysts
- Streamlined IVD Registration:South Africa's Health Products Regulatory Authority has accelerated biomarker assay approvals, reducing time-to-market for companion diagnostics.
- Liquid Biopsy Platforms:Saudi Arabia's SFDA alignment with FDA breakthrough device pathways enables rapid adoption of circulating tumor DNA testing without invasive tissue acquisition.
- Hospital Infrastructure Investment:Egypt, Nigeria, and South Africa are expanding CT-guided biopsy capacity through public-private oncology partnerships.
Market Restraints
- Reagent Import Dependency:Most molecular testing consumables originate from European and North American suppliers, exposing laboratories to currency volatility and shipping delays.
- Pathologist Shortage:Sub-Saharan Africa faces critical deficits in trained thoracic pathologists capable of interpreting complex immunohistochemistry panels.
- Reimbursement Fragmentation:National health insurance schemes across the region apply inconsistent coverage criteria for precision oncology tests, creating payment uncertainty.
Strategic Opportunities
- Regional Manufacturing Partnerships:Egypt's localization incentives redirect supply chain investments toward domestic reagent production and kit assembly.
- Point-of-Care Molecular Testing:Instrument placement programs tied to minimum consumable commitments open mid-size laboratories previously excluded from high-complexity testing.
- AI-Assisted Imaging:Integration of machine learning algorithms with existing CT infrastructure addresses radiologist scarcity in secondary hospitals.
Industry Challenges
- Biomarker Profiling Expertise Gap:Laboratory technologists require specialized training in next-generation sequencing workflows and variant interpretation standards.
- Legacy System Integration:Tertiary hospitals struggle to connect new molecular diagnostics platforms with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lung Cancer Diagnostics Market |
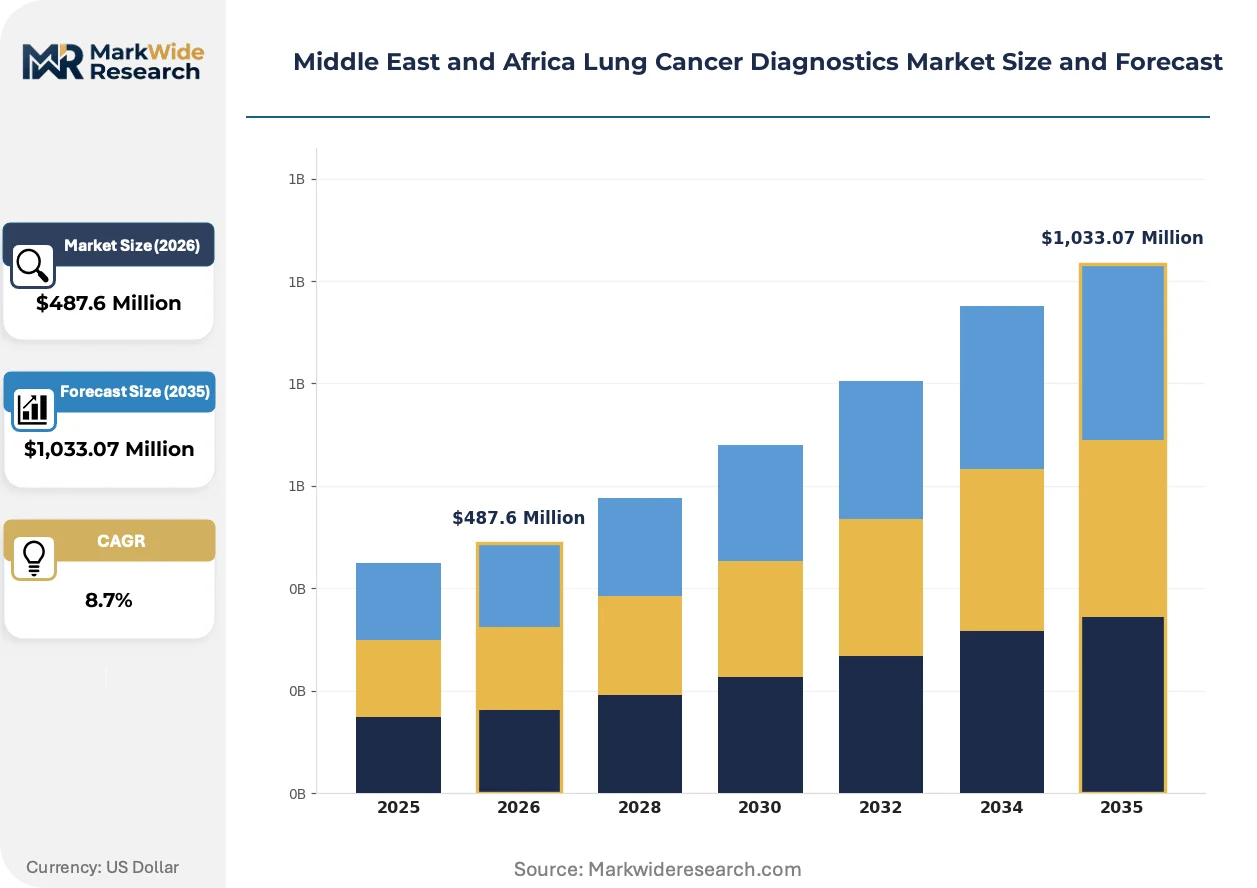
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biomarkers, Biopsy, Molecular Testing Technology: CT Scan, MRI, PET Scan, Bronchoscopy End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutes Delivery Mode: Laboratory Services, Point-of-Care, Home Care, Telehealth |
| Companies Covered | F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Abbott, QIAGEN N.V., Agilent Technologies, Bio-Rad Laboratories, Inc., Illumina Inc., bioMérieux, Exact Sciences Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lung Cancer Diagnostics Market Shifts & Advancements
Artificial intelligence and decentralized testing architectures are actively reshaping how pulmonary malignancies are detected and characterized across the Middle East and Africa, compressing diagnostic timelines while expanding access beyond tertiary centers.
Digital pathology platforms are digitizing histopathological review workflows, enabling remote consultation between African laboratories and subspecialist pathologists in South Africa and Europe. Regional cancer centers in Cairo and Lagos are deploying whole-slide imaging systems to reduce turnaround times for complex cases. This digitization is compressing the traditional referral pathway and enabling same-day multidisciplinary tumor board decisions.
Saudi Arabia's SFDA has implemented streamlined registration pathways for breakthrough liquid biopsy technologies, reducing clinical evidence requirements for circulating tumor DNA platforms. Manufacturers are responding by prioritizing the kingdom for product launches ahead of other regional markets. Egyptian and South African regulators are observing this framework for potential harmonization.
Pay-per-test contracting is displacing traditional capital equipment purchases across mid-size diagnostic laboratories in Nigeria and Kenya. Service providers now bundle instrument maintenance, reagent supply, and quality assurance into per-sample fees that align costs with patient volumes. This model is most visible in private laboratory chains serving medical tourism and insured populations.
Middle East and Africa Lung Cancer Diagnostics Market Segmentation
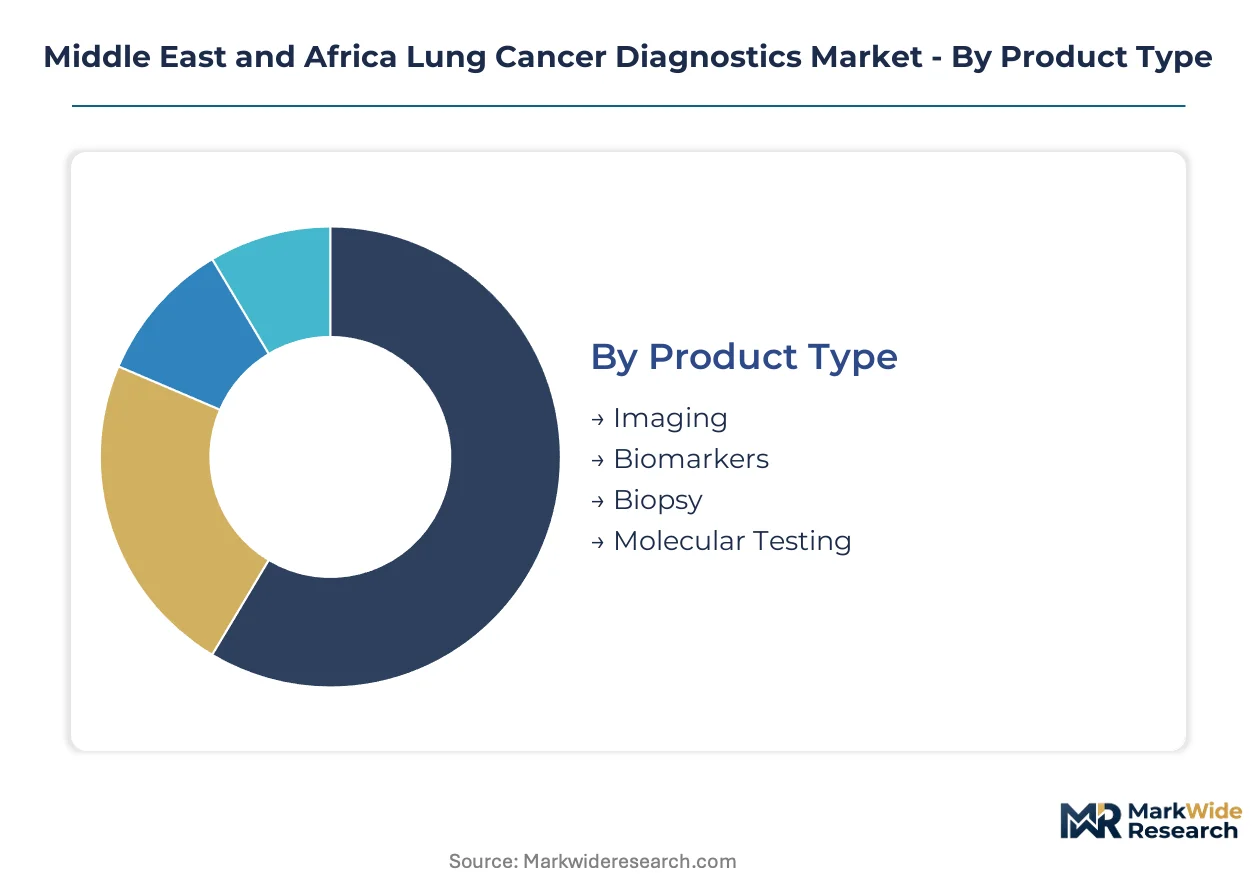
Lung cancer diagnostics in the Middle East and Africa stratify across four critical dimensions that determine capital deployment cycles and revenue recognition patterns. Product type and technology segments exhibit divergent replacement timelines, while end user and delivery mode categories reflect infrastructure maturity gaps between South Africa, Egypt, and Nigeria versus frontier markets.
Product Type:
Imaging systems operate on seven-to-ten year depreciation schedules, while molecular testing consumables turn over monthly, creating fundamentally different cash flow profiles for manufacturers and service providers.
- Imaging:CT scanners, MRI systems, and PET-CT platforms deliver sub-millimeter spatial resolution for nodule detection. Demand concentrates in Cairo and Johannesburg tertiary centers where public-private oncology partnerships fund equipment upgrades. Radiologist scarcity in secondary hospitals limits throughput expansion despite installed base growth.
- Biomarkers:EGFR, ALK, PD-L1, and emerging ctDNA assays guide targeted therapy selection. South African diagnostic laboratories and Saudi tertiary hospitals drive volume as companion diagnostics become prerequisites for immunotherapy and tyrosine kinase inhibitor protocols.
- Biopsy:CT-guided transthoracic and bronchoscopic tissue acquisition techniques enable histopathological confirmation. Egyptian cancer centers deploy these services through centralized referral networks serving the Nile Delta region.
- Molecular Testing:Next-generation sequencing and PCR-based genotyping platforms characterize tumor mutational profiles. Nigerian private laboratory chains adopt these technologies through reagent rental arrangements that reduce capital barriers.
Imaging anchors the volume base while molecular testing gains share at the steepest rate.
Technology:
Capital intensity and reimbursement pathways separate high-field modalities from accessible screening tools, with cost tier determining hospital tier penetration.
- CT Scan:Multi-detector computed tomography delivers the primary screening and staging modality across the region. South Africa's hospital infrastructure investments prioritize 128-slice and above systems for oncology programs in Cape Town and Durban.
- MRI:Magnetic resonance imaging provides superior soft tissue contrast for mediastinal and chest wall invasion assessment. Deployment concentrates in Saudi Arabia's SFDA-regated tertiary centers and select South African academic medical centers.
- PET Scan:Positron emission tomography combined with CT enables metabolic staging and treatment response monitoring. Limited availability in Egypt and Nigeria restricts access to insured populations and medical tourism corridors.
- Bronchoscopy:Electromagnetic navigation and radial probe endobronchial ultrasound facilitate peripheral nodule sampling. Kenyan and Moroccan pulmonology units adopt these platforms through equipment leasing programs.
CT scan anchors the volume base while PET scan climbs the fastest as reimbursement frameworks mature for metabolic staging protocols.
End User:
Customer type determines purchasing authority complexity, with centralized procurement in government hospital systems contrasting fragmented decision-making in private laboratory networks.
- Hospitals:Tertiary oncology centers in Riyadh, Cairo, and Johannesburg integrate multidisciplinary tumor boards with diagnostic workflows. SFDA and Egypt's Drug Authority registration requirements shape vendor selection criteria for these high-volume accounts.
- Diagnostic Laboratories:Independent and hospital-affiliated labs process referred specimens from regional catchment areas. South Africa's expanding molecular testing capacity serves rising oncology referrals through centralized hubs.
- Clinics:Pulmonology and oncology outpatient facilities provide initial assessment and referral coordination. Point-of-care molecular testing penetration targets these settings through Abbott's instrument placement programs.
- Research Institutes:Academic medical centers and cancer biology units drive biomarker discovery and clinical trial enrollment. Partnerships with European and North American institutions accelerate technology transfer.
Hospitals anchor the volume base while diagnostic laboratories expand most quickly as referral networks consolidate testing away from fragmented clinic settings.
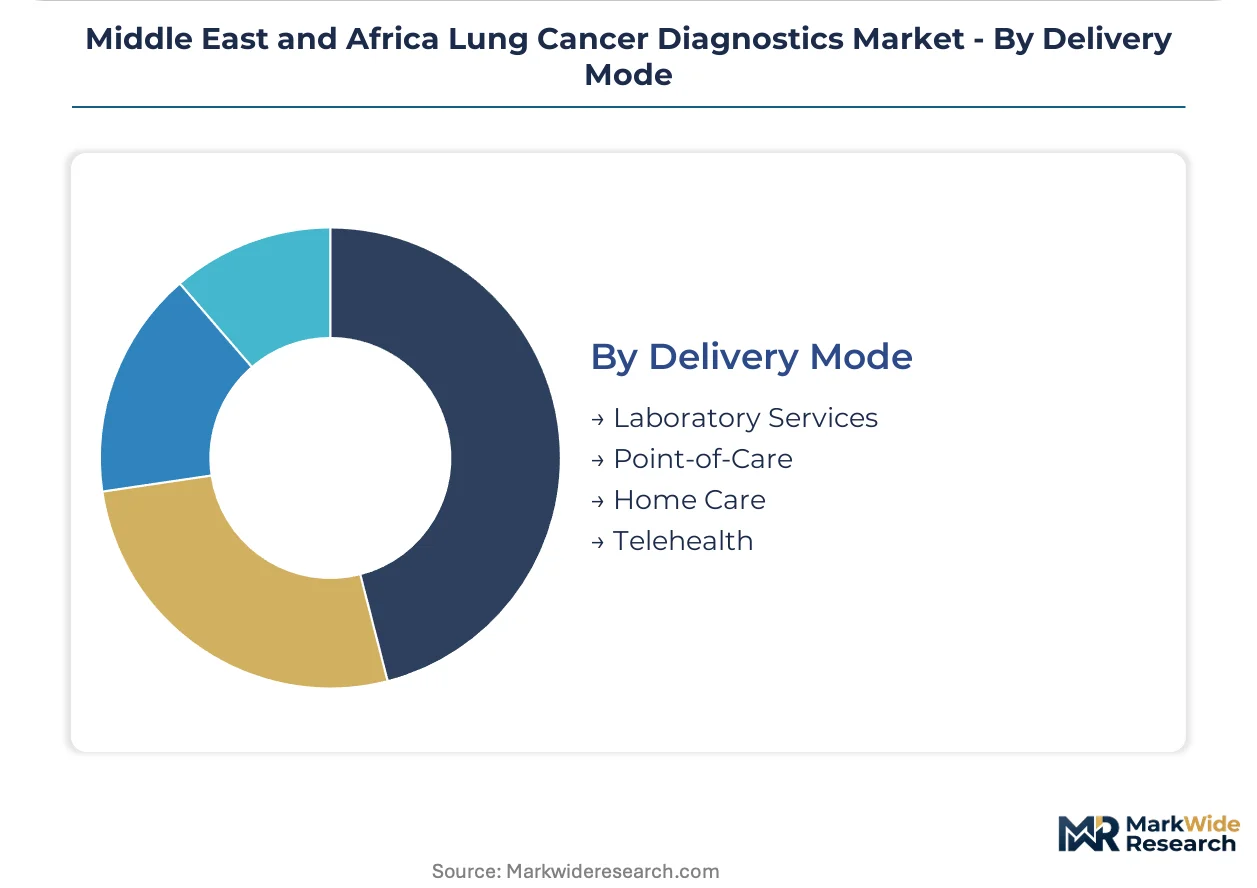
Delivery Mode:
Physical infrastructure requirements and regulatory oversight intensity create distinct margin profiles, with centralized laboratory services commanding scale efficiencies versus distributed point-of-care models.
- Laboratory Services:Centralized high-complexity testing hubs process samples from broad geographic catchments. Thermo Fisher Scientific's distributed reagent supply agreements support mid-size laboratories across Nigeria and Kenya.
- Point-of-Care:Decentralized molecular testing at or near patient encounter sites reduces turnaround times. F. Hoffmann-La Roche Ltd.'s centralized diagnostics platform anchors biomarker workflows in select tertiary hospitals.
- Home Care:Liquid biopsy sample collection and remote monitoring applications remain nascent. Regulatory frameworks for at-home specimen collection vary across South Africa, Egypt, and Saudi Arabia.
- Telehealth:Digital pathology consultation and remote imaging interpretation address specialist scarcity. Whole-slide imaging systems in Lagos and Cairo enable same-day multidisciplinary decisions.
Laboratory services anchor the volume base while point-of-care shows the steepest expansion trajectory as instrument placement programs penetrate mid-tier facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Localization incentives and streamlined regulatory pathways are redirecting supply chain investments toward domestic manufacturing partnerships across the Middle East and Africa. National health insurance schemes in key markets are weighing cost-effectiveness against expanded access mandates for precision oncology tests. Hospital infrastructure investments are accelerating access to advanced diagnostic services in major metropolitan centers.
Saudi Arabia
SFDA alignment with FDA breakthrough device pathways enables rapid adoption of circulating tumor DNA testing platforms. The kingdom's regulatory framework reduces clinical evidence requirements for novel liquid biopsy technologies, positioning Riyadh as a priority launch market for international manufacturers. Tertiary oncology centers in the capital integrate multidisciplinary tumor boards with high-throughput biomarker workflows.
South Africa
Health Products Regulatory Authority streamlining of in-vitro diagnostic registration accelerates biomarker assay approvals and reduces time-to-market for companion diagnostics. Diagnostic laboratories across Cape Town and Durban are expanding molecular testing capacity to serve rising oncology referrals from regional catchment areas. Johannesburg anchors the region's largest installed base of CT-guided biopsy services through public-private oncology partnerships.
Egypt
Egypt's Drug Authority maintains distinct registration frameworks that shape product launch sequencing for manufacturers entering North African markets. Localization incentives redirect supply chain investments toward domestic reagent production and kit assembly partnerships. Cairo-based cancer centers deploy whole-slide imaging systems to reduce turnaround times for complex cases referred from the Nile Delta region.
Nigeria
Private laboratory chains in Lagos are adopting next-generation sequencing technologies through reagent rental arrangements that reduce capital barriers for mid-size facilities. Pay-per-test contracting models bundle instrument maintenance and quality assurance into per-sample fees aligned with patient volumes. These service providers target medical tourism corridors and insured populations seeking molecular characterization services.
United Arab Emirates
MOHAP regulatory oversight supports the integration of AI-assisted imaging algorithms with existing CT infrastructure in Dubai and Abu Dhabi tertiary hospitals. Federal healthcare procurement frameworks enable centralized purchasing of high-field diagnostic modalities for metabolic staging protocols. The emirates serve as a logistics hub for reagent distribution into sub-Saharan African markets.
Middle East and Africa Lung Cancer Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument placement, reagent supply, and centralized diagnostics platform segments. The vendor base stratifies into three tiers: multinational conglomerates with integrated workflow solutions, mid-size reagent suppliers with distributed supply agreements, and point-of-care specialists with consumable-tied instrument programs. Dominant competitive moves include equipment leasing arrangements that convert capital sales into recurring revenue streams, and strategic partnerships with regional distributors to navigate fragmented procurement frameworks.
Within the centralized diagnostics tier, F. Hoffmann-La Roche Ltd. and Thermo Fisher Scientific Inc. exemplify contrasting approaches to market access. The Swiss conglomerate anchors high-throughput biomarker workflows in tertiary hospitals through platform-centric contracting, while the American supplier competes via distributed reagent supply agreements that reduce capital barriers for mid-size laboratories. Abbott occupies a position in point-of-care molecular testing penetration through instrument placement programs tied to consumable minimums. These three entities collectively represent the strategic archetypes reshaping competitive dynamics across the region's lung cancer diagnostics landscape.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Abbott |
| QIAGEN N.V. |
| Agilent Technologies |
| Bio-Rad Laboratories, Inc. |
| Illumina Inc. |
| bioMérieux |
| Exact Sciences Corporation |
| Others |
Supply & Pricing Matrix
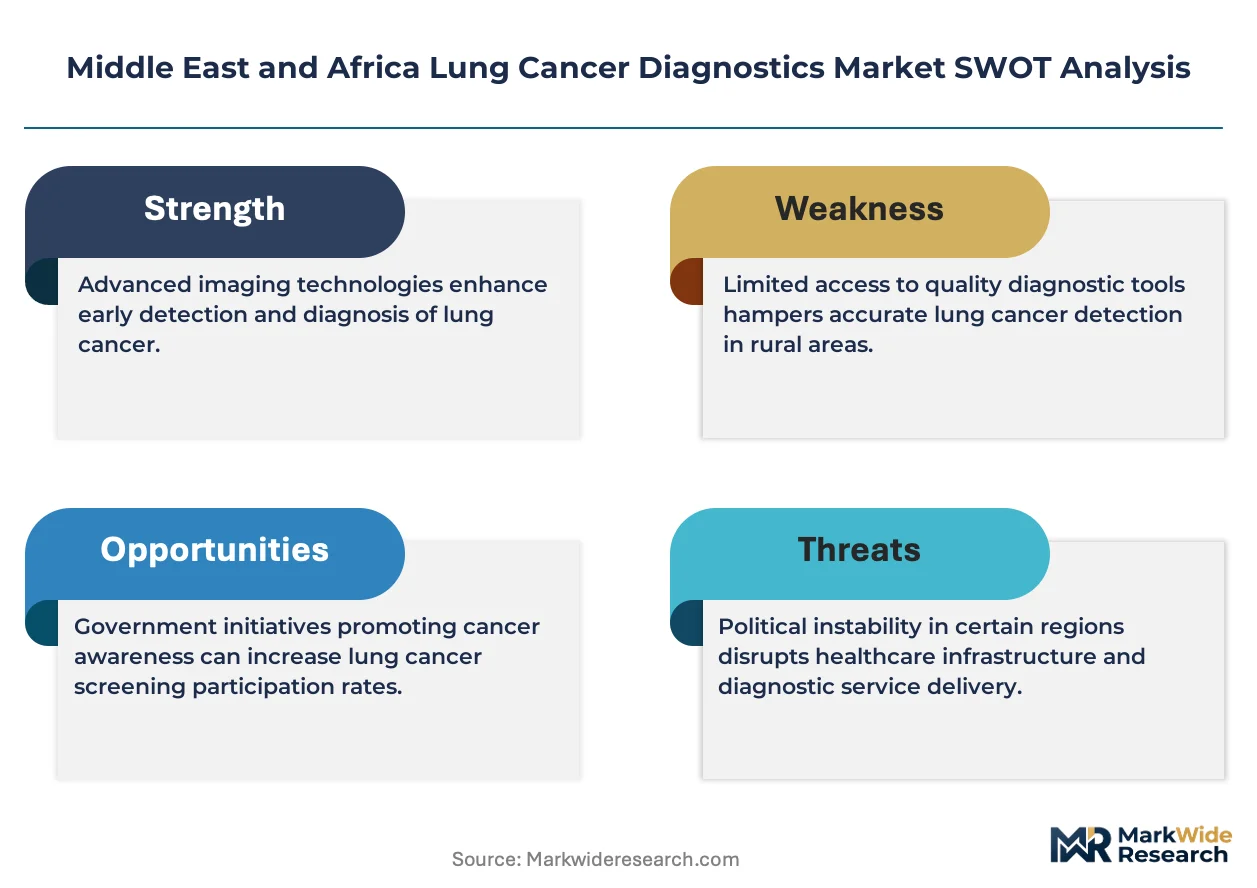
Reagent import dependency on European and North American suppliers exposes Middle East and Africa diagnostic laboratories to currency volatility and shipping delays, compressing margin structures across premium-certified and standard-grade testing tiers while forcing procurement consolidation toward regional distribution hubs.
Pricing Analysis
Certification level (SFDA/FDA-breakthrough versus standard CE-IVD) creates the primary spread between premium liquid biopsy platforms and economy PCR-based assays. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and reagent rental arrangements that convert capital sales into recurring revenue. Cost compression in the standard tier is intensifying because mid-size laboratories in Nigeria and Kenya negotiate per-sample fees tied to minimum volume commitments. Public hospital procurement committees exhibit highest price sensitivity, while private laboratory chains serving medical tourism demonstrate lowest sensitivity to upfront instrument costs.
Supply Chain Analysis
Tariff exposure between Egypt and European reagent manufacturers dominates supply chain risk calculations for North African diagnostic networks. Molecular testing consumables draw from Germany, the United States, and Singapore, with fluorophore-labeled probes and sequencing flow cells representing critical input dependencies. Single-source vulnerability in next-generation sequencing instrument platforms creates procurement chokepoints for South African tertiary centers. Distribution runs through Dubai and Johannesburg logistics hubs that consolidate reagent shipments for sub-Saharan laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instrument placement programs with consumable minimums represent a service-attach opportunity expanding faster than hardware sales, as pay-per-test contracting displaces capital purchases across mid-tier diagnostic facilities.
For Market Incumbents: Entrench platform-centric contracting in Saudi tertiary hospitals by deepening reagent supply exclusivity and embedding field application scientists within multidisciplinary tumor boards. Defend against Thermo Fisher Scientific's distributed supply agreements by securing long-term service contracts with South African diagnostic laboratory chains. Prioritize certification investment in SFDA breakthrough device pathways to accelerate product launch sequencing ahead of regional competitors. For New Entrants and Emerging Players: Pathologist scarcity in sub-Saharan secondary hospitals offers white-space entry through AI-assisted digital pathology platforms that enable remote consultation with South African subspecialists. Target Egyptian cancer centers in the Nile Delta region with whole-slide imaging systems that reduce complex case turnaround times. Pursue joint venture structures with local distributors to navigate Egypt's Drug Authority localization incentives and domestic kit assembly requirements. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors vertically integrated diagnostics conglomerates with recurring revenue moats. Five-to-ten year viability hinges on consumable pull-through rates rather than instrument placement volumes. Monitor SFDA regulatory harmonization signals with FDA breakthrough pathways as the inflection indicator for accelerated liquid biopsy adoption across Gulf Cooperation Council markets.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Arrangement Expansion | Reduces capital barriers for Nigerian private laboratory chains adopting next-generation sequencing platforms. |
| SFDA Breakthrough Device Pathway Alignment | Accelerates circulating tumor DNA platform registration in Saudi Arabia ahead of other regional markets. |
| Regional Manufacturing Partnership | Egypt's localization incentives redirect supply chain investments toward domestic reagent production. |
| Digital Pathology Platform Deployment | Cairo and Lagos cancer centers deploy whole-slide imaging to compress complex case turnaround times. |
| AI-Assisted CT Imaging Integration | Addresses radiologist scarcity in secondary hospitals across Kenya and Morocco through machine learning algorithms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors at South African diagnostic hubs, biomedical engineers managing CT-guided biopsy services in Egyptian cancer centers, procurement officers at Saudi tertiary hospitals, and regulatory affairs specialists navigating SFDA registration pathways. Secondary validation drew from SFDA breakthrough device filings, Egypt's Drug Authority localization policy documents, South African Health Products Regulatory Authority registration databases, and GPO contract disclosures. Bottom-up testing volume estimates were triangulated against top-down market size calculations.
Calibration across the analysis window employed segmented modeling of imaging systems, biomarker assays, biopsy techniques, and molecular testing platforms, with technology tiers further disaggregated by CT, MRI, PET, and bronchoscopy modalities. CAGRs were derived from trend extrapolation of oncology referral growth, hospital infrastructure investment pipelines, and precision oncology reimbursement policy trajectories. Forecast inputs incorporated pathologist workforce projections, currency volatility assumptions for reagent import markets, and regulatory harmonization scenarios between regional authorities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese diagnostics manufacturers with cost-disadvantaged reagent supply would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
DNA and RNA Probes Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Anatomic Pathology Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Semen Analysis Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Poultry Diagnostics Market