
 GCC in-Vitro Diagnostics Market | 2026-2036
GCC in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC in-Vitro Diagnostics Market Analysis
CE-IVD certification tier is redrawing procurement criteria across Gulf health systems. Abbott Laboratories leverages its immunoassay installed base to sustain long-term reagent contracts in Saudi Arabia. Roche Diagnostics anchors molecular diagnostics expansion through centralized lab partnerships in the UAE. Siemens Healthineers differentiates its imaging-integrated pathology workflow across Qatar's national health system.
In-vitro diagnostics encompasses analytical testing performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, optical detection systems, and automated sample processing to generate quantitative or qualitative diagnostic results. These systems serve clinical decision-making across disease screening, therapeutic monitoring, and infectious disease management. Reagent consumption dominates recurring revenue pools as test volumes scale, while molecular diagnostics captures premium positioning amid precision medicine expansion. Hospitals absorb the largest end-user spend through emergency and inpatient testing workflows, though independent laboratories compete on specialized genetic and oncology panels.
SFDA, MOHAP, and Saudi Central Board for Accreditation of Healthcare Institutions collectively shape product standards, laboratory accreditation, and import licensing across the Gulf. Saudi Arabia's mandatory IVD registration pathway now requires local stability data, extending time-to-market for multinational manufacturers. Stakeholders must monitor regulatory divergence between Riyadh and Abu Dhabi as each authority builds independent conformity assessment capabilities.
Market Dynamics
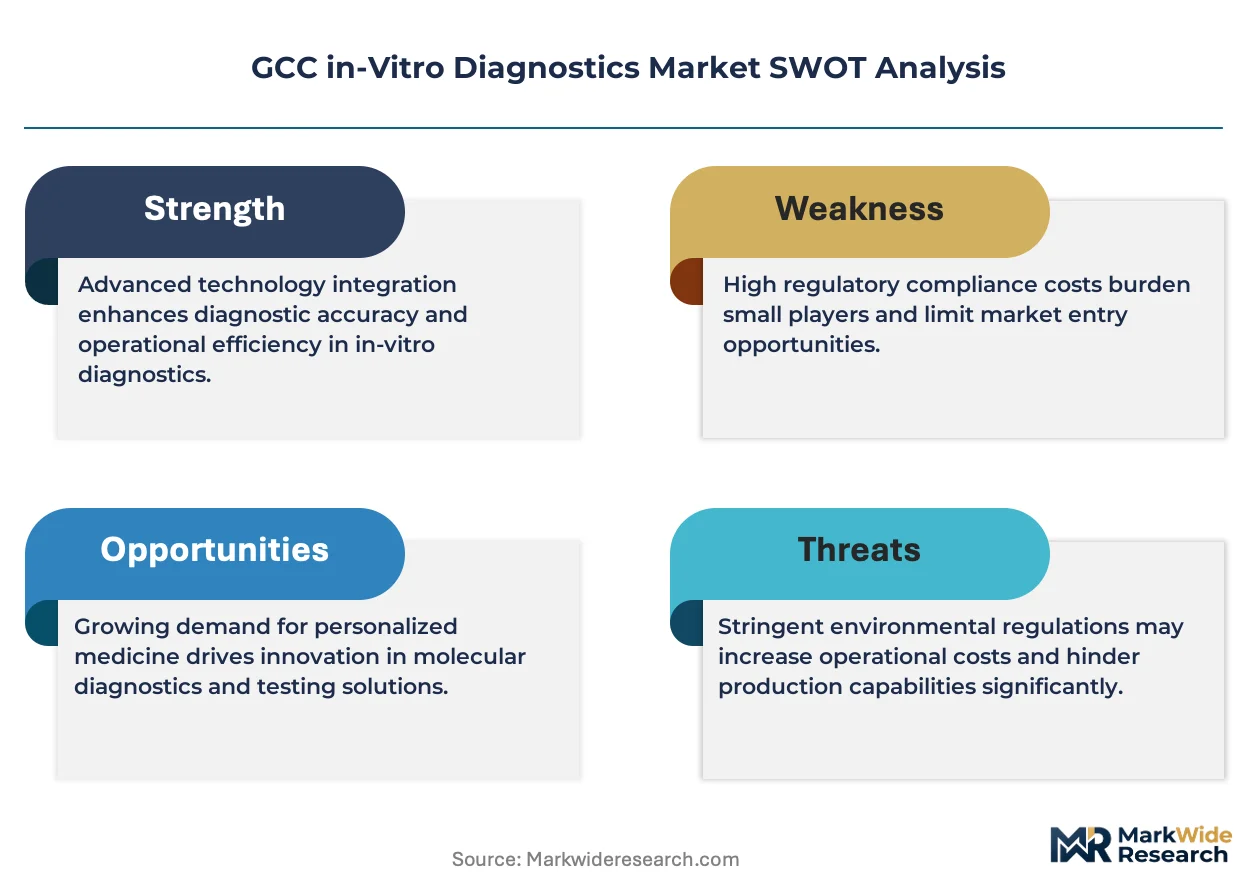
CE-IVD certification requirements are compressing vendor eligibility across Saudi Arabia, the UAE, and Qatar, forcing multinational manufacturers to restructure registration strategies and local partnership terms to maintain hospital laboratory access.
Growth Catalysts
- SFDA Stability Mandate:Saudi Arabia's local stability data requirement accelerates in-country manufacturing investment, deepening supply chain roots and shortening replenishment cycles for registered reagent kits.
- Hospital Automation Waves:Centralized hospital networks in Riyadh and Dammam deploy high-throughput immunoassay analyzers, generating locked-in reagent consumption streams that compound annually with test volume growth.
- Precision Medicine Expansion:Molecular diagnostics platforms capture oncology and genetic screening workflows, commanding premium positioning as clinicians integrate biomarker data into therapeutic protocols.
Market Restraints
- Reagent Import Dependency:Cold-chain logistics for temperature-sensitive diagnostic consumables concentrate through Dubai's Jebel Ali port, creating single-point vulnerability for UAE and Qatar laboratory supply security.
- Registration Timeline Friction:SFDA's extended conformity assessment pathway stretches product launch intervals to 18-24 months, deferring revenue recognition for novel assay introductions.
- Technical Skill Scarcity:Certified clinical laboratory scientists capable of operating multiplex molecular platforms remain concentrated in Saudi Arabia's tertiary medical cities, constraining platform deployment in secondary facilities.
Strategic Opportunities
- Kuwait Penetration Gap:Underdeveloped independent laboratory infrastructure in Kuwait City creates first-mover positioning for specialized genetic testing providers with MOH licensing pathways.
- POCT Channel Expansion:Point-of-care testing devices bypass centralized lab bottlenecks in emergency departments, capturing time-critical cardiac and infectious disease diagnostics at the bedside.
- MOHAP Harmonization:Abu Dhabi's regulatory alignment with CE-IVD standards streamlines multi-emirate product registration, reducing duplicate compliance expenditure for UAE-wide distribution.
Industry Challenges
- Interoperability Fragmentation:Laboratory information systems across Qatar's Hamad Medical Corporation network lack standardized data exchange protocols, complicating multi-site workflow integration.
- Capex Recovery Pressure:Automated analyzer procurement in Saudi Arabia's Ministry of Health facilities requires 7-year depreciation cycles, stretching vendor financing terms and compressing upfront margin structures.
- Biorepository Cold-Chain Complexity:Sample integrity requirements for molecular diagnostics necessitate continuous temperature monitoring infrastructure that secondary hospitals in Oman struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC in-Vitro Diagnostics Market |
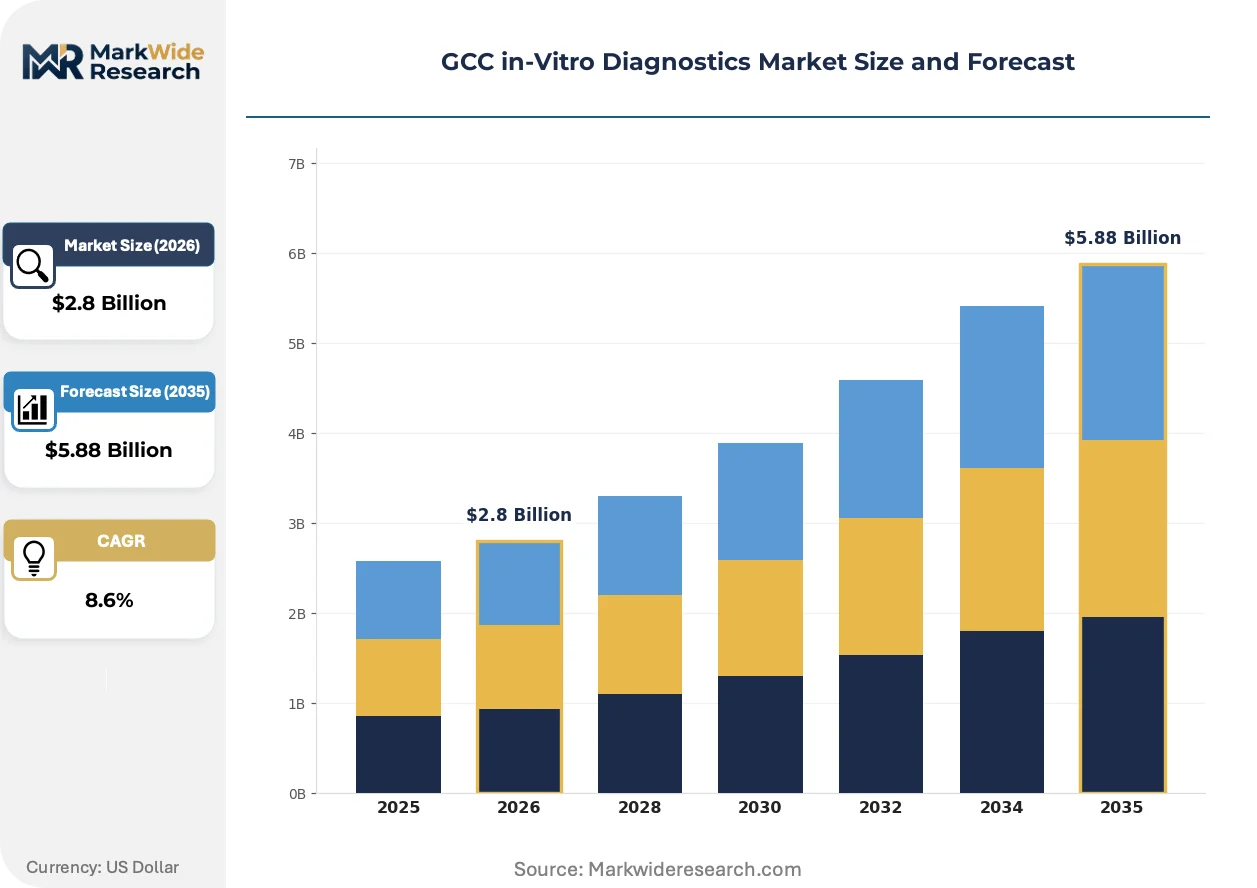
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software Technology: Molecular Diagnostics, Immunoassays, Microbiology, Hematology End User: Hospitals, Laboratories, Clinics, Research Institutions Application: Disease Diagnostics, Blood Testing, Genetic Testing, Infectious Diseases |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, Danaher Corporation, Sysmex Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories, Al-Borg Diagnostics, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC in-Vitro Diagnostics Market Emerging Trajectories
Digital pathology integration and decentralized testing architectures are redrawing equipment deployment patterns across Gulf health systems, compressing the traditional boundary between centralized laboratory hubs and point-of-care nodes.
Artificial intelligence-assisted image analysis is decomposing conventional histopathology workflows in Dubai's Sheikh Mohammed Bin Rashid Academic Medical Center, where pathologists now validate algorithmic tissue classifications rather than performing primary reads. Diagnostic confidence intervals narrow while case throughput expands. This capability compression enables regional reference laboratories to absorb overflow from understaffed facilities in northern Emirates.
MOHAP's 2023 technical guideline revision mandates traceable calibration standards for quantitative immunoassays, forcing Dubai and northern Emirates laboratories to retire uncertified reagent lots. Compliance expenditure concentrates in independent laboratories lacking corporate quality infrastructure. Hospital networks with embedded metrology capabilities capture accreditation advantages that translate into preferred payer contracts.
Consolidated procurement through Saudi Arabia's National Unified Procurement Company is displacing fragmented hospital-level tendering, compressing vendor negotiation leverage and standardizing equipment specifications across the Kingdom's 20 medical clusters. Multinational manufacturers now structure Gulf commercial organizations around Riyadh-centric account management rather than distributed emirate-level representation. This concentration reshapes service delivery models, with technical field forces repositioning from Dubai to Riyadh operational hubs.
GCC in-Vitro Diagnostics Market Segmentation
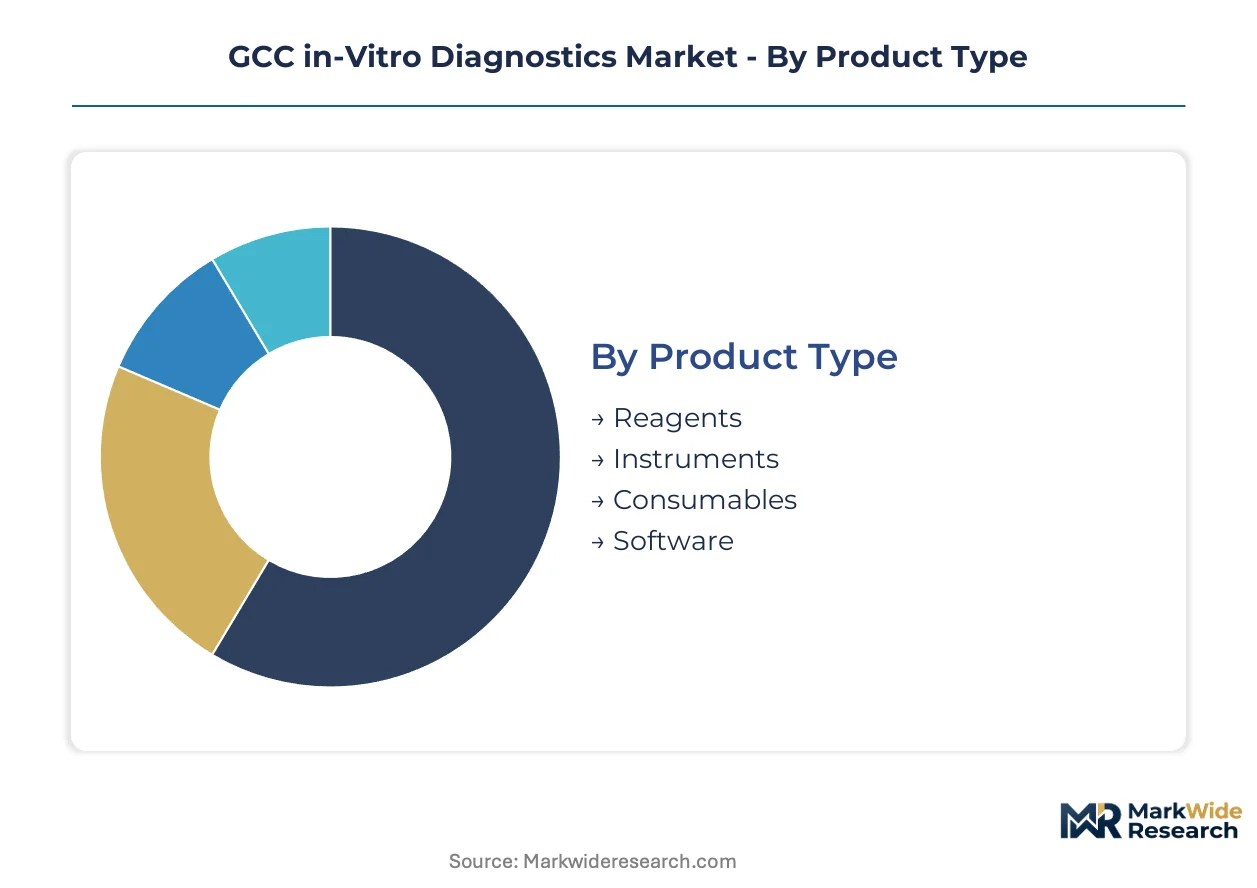
Segmentation in the GCC in-vitro diagnostics market reveals how procurement authority, testing workflow, and regulatory compliance intersect differently across product categories. Channel configuration varies sharply between centralized hospital networks and independent laboratory operators.
Product Type:
Reagent kits flow through long-term supply contracts with Saudi Arabia's NUPCO and UAE hospital procurement consortia, while instruments and software concentrate in competitive tenders led by tertiary medical cities.
- Reagents:Chemical and biological reactive substances drive recurring revenue through immunoassay and molecular testing workflows. Saudi Arabia's 20 medical clusters absorb the largest volumes through centralized procurement, with SFDA stability mandates deepening local manufacturing partnerships to shorten replenishment cycles.
- Instruments:Automated analyzers, sample processors, and detection systems anchor capital expenditure budgets across Riyadh and Dubai hospital networks. Seven-year depreciation requirements in Saudi Ministry of Health facilities stretch vendor financing terms and compress upfront margins.
- Consumables:Pipette tips, reaction vessels, and collection containers support daily testing operations. Cold-chain logistics through Jebel Ali port create supply security vulnerabilities for temperature-sensitive shipments.
- Software:Laboratory information systems and data management platforms enable workflow integration. Interoperability fragmentation across Qatar's Hamad Medical Corporation network complicates multi-site deployment.
By volume, Reagents leads. By growth pace, Software is gaining share fastest as digital pathology and AI-assisted analysis reshape laboratory workflows.
Technology:
Cost tier stratification separates premium molecular platforms from standardized immunoassay installations, with microbiology and hematology occupying mid-tier positioning across Gulf health systems.
- Molecular Diagnostics:Nucleic acid amplification, sequencing, and hybridization technologies detect genetic markers and infectious agents with high specificity. Oncology and precision medicine applications in Dubai's Sheikh Mohammed Bin Rashid Academic Medical Center command premium pricing as clinicians integrate biomarker data into therapeutic protocols.
- Immunoassays:Antibody-antigen binding reactions quantify hormones, tumor markers, and cardiac proteins through chemiluminescence and ELISA methods. High-throughput analyzer deployment in Riyadh and Dammam hospitals generates locked-in reagent consumption streams.
- Microbiology:Culture-based and rapid pathogen identification systems support antimicrobial stewardship programs. Secondary facilities in Oman struggle with biorepository cold-chain maintenance for sample integrity.
- Hematology:Automated cell counting and coagulation analysis platforms process routine blood panels. Standardized specifications from Saudi NUPCO procurement limit vendor differentiation.
By installed base, Immunoassays dominates. By expansion trajectory, Molecular Diagnostics climbs the fastest amid precision medicine adoption.
End User:
Customer type determines contract structure, with hospitals locking in multi-year reagent agreements while independent laboratories compete on specialized test menus and turnaround speed.
- Hospitals:Emergency departments and inpatient wards generate continuous testing demand through automated core laboratories. Centralized networks in Saudi Arabia absorb the largest end-user spend through integrated procurement.
- Laboratories:Independent diagnostic facilities and reference laboratories specialize in genetic panels and esoteric testing. Kuwait City's underdeveloped infrastructure creates first-mover positioning for specialized providers with MOH licensing pathways.
- Clinics:Outpatient facilities and primary care centers deploy point-of-care testing for time-critical diagnostics. Cardiac and infectious disease applications at the bedside bypass centralized lab bottlenecks.
- Research Institutions:Academic medical centers and biotechnology facilities advance biomarker discovery and clinical trial support. Collaboration frameworks with Qatar's national health system concentrate capability in Doha.
By revenue concentration, Hospitals leads. By margin structure, Laboratories is expanding most quickly through specialized genetic and oncology panels.
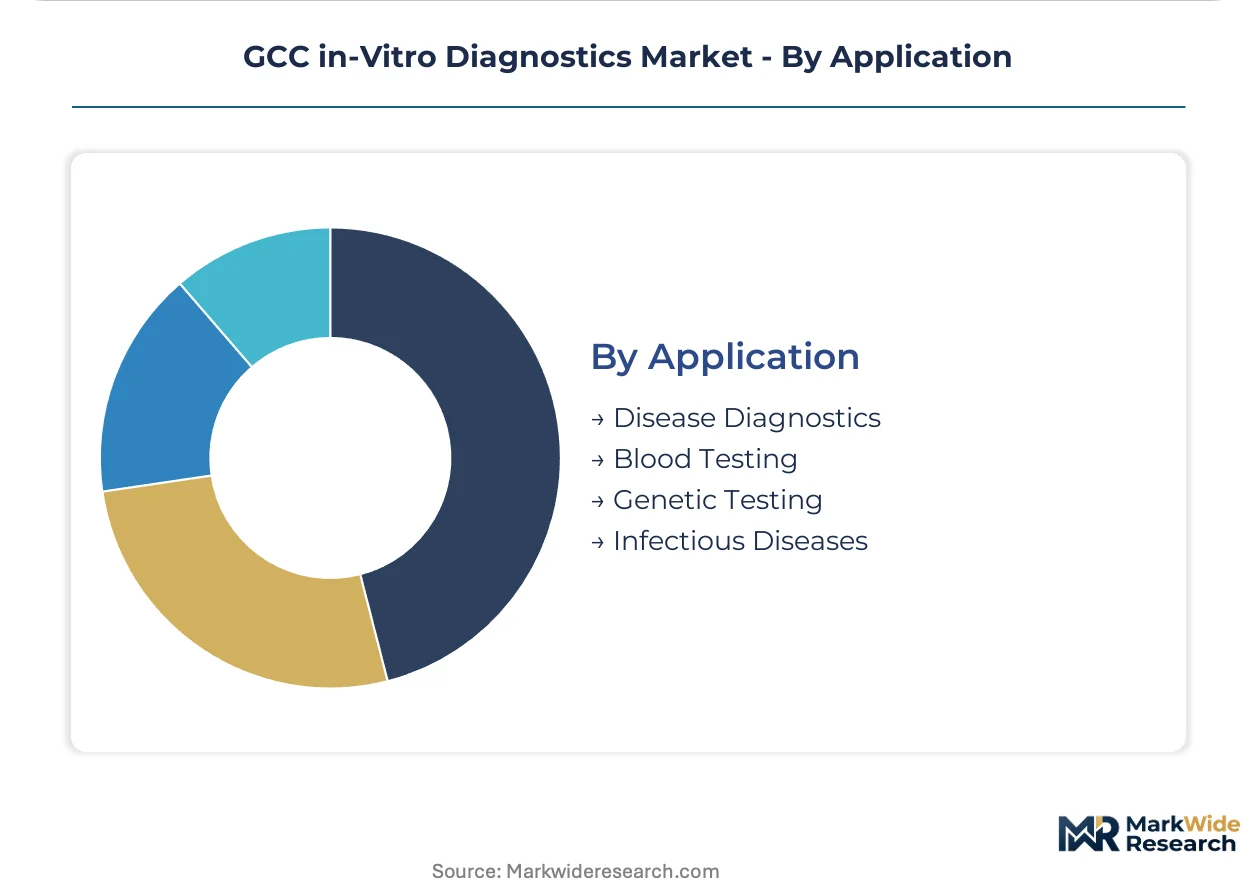
Application:
Maturity gradient separates established disease diagnostics and blood testing from emerging genetic and infectious disease applications, with regulatory pathways varying by clinical validation requirements.
- Disease Diagnostics:Chronic disease monitoring and general health screening form the baseline testing volume across Gulf health systems. Standardized immunoassay menus dominate routine clinical decision-making.
- Blood Testing:Complete blood count, coagulation profiles, and transfusion medicine support surgical and emergency workflows. Hematology analyzer standardization through NUPCO procurement limits equipment diversity.
- Genetic Testing:Hereditary disease screening, pharmacogenomics, and prenatal diagnostics leverage molecular platforms. Technical skill scarcity for multiplex platform operation constrains deployment beyond Saudi Arabia's tertiary medical cities.
- Infectious Diseases:Pathogen detection for tuberculosis, hepatitis, and respiratory panels integrates with public health surveillance. MOHAP traceable calibration mandates for quantitative assays force retirement of uncertified reagent lots in Dubai laboratories.
By test volume, Disease Diagnostics leads. By platform investment, Genetic Testing shows the steepest expansion trajectory as precision medicine protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic supply chains concentrate through Dubai's Jebel Ali port and Riyadh's emerging manufacturing zones, with regulatory divergence between Saudi Arabia and the UAE reshaping vendor registration strategies.
Saudi Arabia
Centralized hospital networks in Riyadh and Dammam drive automated analyzer deployment through the National Unified Procurement Company. SFDA stability data mandates extend registration timelines to 18-24 months while deepening local reagent manufacturing partnerships. King Faisal Specialist Hospital anchors molecular diagnostics capability in the capital's tertiary medical cluster.
United Arab Emirates
MOHAP's 2023 traceable calibration standards force Dubai laboratories to retire uncertified immunoassay reagents. Sheikh Mohammed Bin Rashid Academic Medical Center integrates AI-assisted pathology validation into clinical workflows. Abu Dhabi's regulatory alignment with CE-IVD standards streamlines multi-emirate product distribution.
Qatar
Hamad Medical Corporation's national laboratory network struggles with interoperability fragmentation across multi-site information systems. The country's biorepository infrastructure concentrates specialized genetic testing capability in Doha. Secondary facilities face cold-chain maintenance constraints for molecular sample integrity.
Kuwait
Underdeveloped independent laboratory infrastructure in Kuwait City creates positioning opportunities for specialized genetic testing providers. MOH licensing pathways remain less standardized than Saudi or Emirati frameworks. Procurement fragmentation across Ministry of Health facilities delays centralized automation adoption.
Oman
Secondary hospitals in Muscat and Salalah struggle with continuous temperature monitoring for molecular diagnostics sample integrity. Technical skill scarcity constrains multiplex platform operation outside tertiary referral centers. Import dependency through UAE logistics hubs creates supply security vulnerabilities for temperature-sensitive consumables.
GCC in-Vitro Diagnostics Market Vendor Landscape
Concentration sits with multinational conglomerates possessing immunoassay installed bases and long-term reagent contracts. Three strategic archetypes dominate: diversified life sciences conglomerates with Gulf commercial organizations, specialized diagnostics pure-plays with molecular platform expertise, and regional distributors with MOH licensing relationships. Competitive moves center on Riyadh-centric account management restructuring and Dubai-to-Riyadh field force repositioning.
Among Swiss-headquartered conglomerates, Roche Diagnostics exemplifies the molecular diagnostics expansion archetype through centralized laboratory partnerships. Abbott Laboratories represents the immunoassay installed base model with locked-in reagent consumption streams across Saudi medical clusters. Siemens Healthineers occupies the imaging-integrated pathology workflow position within Qatar's national health system.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter |
| Danaher Corporation |
| Sysmex Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| Al-Borg Diagnostics |
| Others |
Supply Flow & Price Mechanics
High-throughput analyzer scale economies in Riyadh and Dammam medical clusters compress per-test reagent costs while concentrating procurement leverage through Saudi Arabia's National Unified Procurement Company. This scale concentration simultaneously anchors price floors for mid-tier equipment vendors and elevates switching costs for hospital networks locked into long-term consumable contracts.
Pricing Analysis
CE-IVD certification dictates the pricing tier structure across Gulf health systems, separating premium molecular platforms from standardized immunoassay installations. Pricing stratifies across certified-premium, validated-standard, and uncertified-economy tiers based on regulatory tier and after-sales service bundling. Cost compression in the standard tier is intensifying because MOHAP's 2023 traceable calibration mandates force Dubai laboratories to retire non-compliant reagent lots. Independent laboratories exhibit the highest price sensitivity due to fragmented procurement scale, while tertiary medical cities with embedded quality infrastructure absorb premium positioning.
Supply Chain Analysis
Jebel Ali port chokepoint concentration underwrites regional distribution security for temperature-sensitive diagnostic consumables entering the UAE and Qatar. Manufacturing capacity concentrates in Germany, Switzerland, and the United States for high-precision analyzers, while reagent production draws from Singapore and Ireland for cold-chain efficiency. Single-source vulnerability runs through Dubai's customs clearance bottlenecks for time-critical shipments. Distribution feeds from centralized NUPCO warehousing in Riyadh to Saudi Arabia's 20 medical clusters, with emergency replenishment routed through direct manufacturer air freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC in-vitro diagnostics market functions as a defensive-moat arena where regulatory entrenchment through SFDA and MOHAP certification pathways creates durable incumbent advantages. Switching costs for hospital networks locked into seven-year analyzer depreciation cycles and consumable contracts compound this structural protection.
For Market Incumbents: Shield installed-base positions by deepening local reagent manufacturing partnerships in Saudi Arabia to satisfy SFDA stability mandates, while extending technical service capabilities from Riyadh operational hubs to capture secondary facility maintenance contracts. Emerging molecular diagnostics pure-plays threaten immunoassay volume retention in oncology workflows. Certification investment in MOHAP-aligned traceable calibration standards anchors preferred vendor status across UAE hospital procurement consortia. For New Entrants and Emerging Players: Lead with specialized genetic testing capabilities targeting Kuwait City's underdeveloped independent laboratory infrastructure, where MOH licensing pathways remain less standardized than Saudi or Emirati frameworks. Point-of-care testing devices for emergency department cardiac and infectious disease diagnostics represent the most penetrable white-space segment. A go-to-market angle emphasizing bedside workflow bypass of centralized lab bottlenecks differentiates against established core laboratory vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among immunoassay reagent suppliers with long-term NUPCO contracts and locked-in consumption streams across Saudi medical clusters. Long-term viability over the projection horizon favors diversified life sciences conglomerates with Gulf commercial organizations capable of navigating regulatory divergence between Riyadh and Abu Dhabi. The signal to monitor is MOHAP-SFDA harmonization progress, which would compress multi-emirate registration expenditure and reshape competitive economics for regional distributors.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Stability Data Localization | Local manufacturing investment shortens replenishment cycles for registered reagent kits in Saudi Arabia. |
| MOHAP CE-IVD Harmonization | Regulatory alignment streamlines multi-emirate product registration across UAE health systems. |
| AI-Assisted Pathology Integration | Algorithmic tissue classification validation expands case throughput at Dubai's Sheikh Mohammed Bin Rashid Academic Medical Center. |
| Point-of-Care Testing Channel Expansion | Bedside cardiac and infectious disease diagnostics bypass centralized laboratory bottlenecks in emergency departments. |
| Consolidated Procurement Positioning | NUPCO-centric account management restructuring captures Saudi Arabia's 20 medical cluster standardization. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SFDA registration databases, MOHAP technical guidelines, hospital procurement records, and multinational manufacturer Gulf commercial organization disclosures. Primary interviews engaged regulatory affairs managers at diagnostic manufacturers, laboratory directors at Saudi tertiary medical cities, biomedical engineers at UAE hospital networks, and procurement officers at Qatar's Hamad Medical Corporation. Secondary validation drew from SFDA product registration filings, MOHAP 2023 calibration standard revisions, NUPCO tender documentation, and CE-IVD certification records. Bottom-up test volume modeling and top-down healthcare expenditure allocation triangulate market sizing across the analysis window.
Segmentation dimensions modeled include product type, technology platform, end-user category, and application area across the projection horizon. Analytical frameworks incorporate installed base depreciation cycles, reagent consumption velocity per analyzer, and regulatory pathway timelines to derive expansion trajectories. CAGRs emerge from test volume growth assumptions calibrated against hospital automation deployment schedules and precision medicine protocol adoption curves. Forecast inputs include SFDA registration timeline elasticity and cold-chain logistics capacity at Jebel Ali port.
The analysis sits within stated boundaries; outcomes outside sustained regulatory stability and cold-chain infrastructure investment would require recalibration. Forecasts reflect assumptions regarding NUPCO procurement centralization continuity and MOHAP-SFDA harmonization progress. Practitioners should keep alternative scenarios live as regulatory divergence and logistics chokepoint vulnerabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Global Phytopathological Disease Diagnostics Market