
 Cognitive Diagnostics Market | 2026-2036
Cognitive Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Diagnostics Market Outlook
North American AI compute infrastructure is restructuring access patterns for cognitive diagnostic developers. NVIDIA Clara AI leverages its GPU cloud partnerships to sustain training pipelines for neuroimaging models. Cambridge Cognition Ltd. anchors its position in digital cognitive assessment through regulatory-aligned software architectures. IBM Watson Health competes by extending enterprise data integration tools into multi-site dementia research networks.
Cognitive diagnostics encompass instrument-based and algorithmic methods for detecting, quantifying, and tracking neural function decline, typically incorporating neuroimaging resolution thresholds, biomarker sensitivity cutoffs, or standardized psychometric scoring protocols to enable reproducible clinical decision-making. These systems serve pharmaceutical trial endpoints, early disease identification, and longitudinal patient monitoring in neurology and psychiatric practice. Neuroimaging platforms currently occupy the largest revenue share due to capital-intensive scanner deployment and radiologist workflow integration, while automated screening solutions represent the fastest-expanding delivery mode as remote patient access protocols mature. Biomarker testing concentrates margin pools in reference laboratory channels, whereas cognitive assessments spread across software licensing models with lower per-test economics.
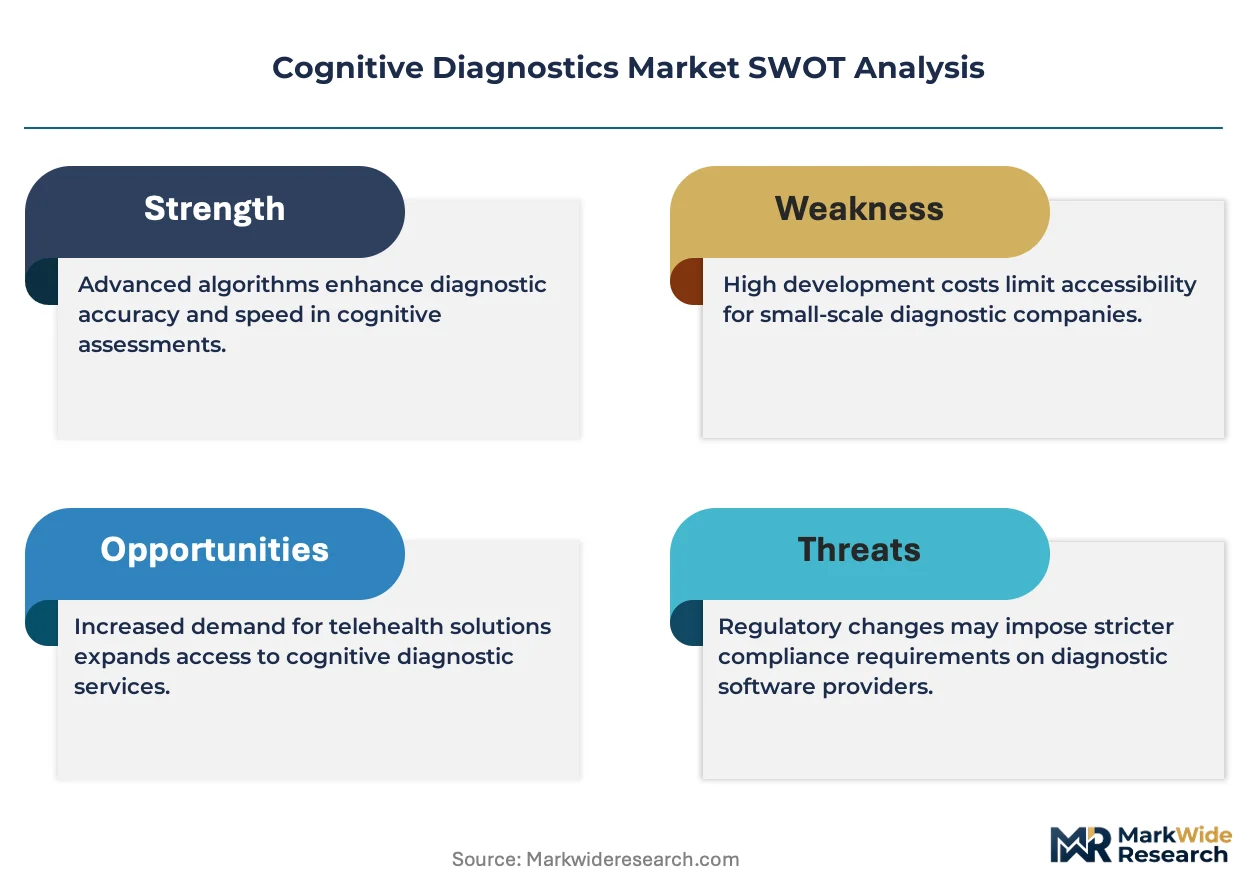
FDA breakthrough device designations and HIPAA data governance requirements shape product development timelines and commercialization pathways for US-market cognitive diagnostic platforms. The EU AI Act and MDR framework impose conformity assessment burdens on algorithmic diagnostic tools seeking European market access, favoring vendors with established quality management systems. Stakeholders must monitor evolving reimbursement codes for remote cognitive monitoring as payors recalibrate coverage policies for decentralized neurological care.
Market Dynamics
Pharmaceutical trial complexity is restructuring procurement priorities for cognitive assessment tools, as sponsors demand biomarker-linked endpoints that compress validation timelines and force vendors to integrate scanner hardware with cloud-based analytics pipelines.
Growth Catalysts
- Breakthrough Device Pathway:The FDA's accelerated clearance mechanism reduces neuroimaging platform approval cycles, enabling earlier revenue recognition for developers targeting Alzheimer's drug trial endpoints.
- Remote Patient Access Protocols:Telehealth reimbursement expansions in the United States are pulling automated cognitive screening into primary care workflows previously reserved for specialist referral.
- GPU Cloud Partnerships:NVIDIA Clara AI infrastructure sustains training pipelines for neuroimaging models, lowering capital barriers for algorithm developers entering the cognitive diagnostics space.
Market Restraints
- Radiologist Workflow Integration Costs:Capital-intensive scanner deployment requires PACS system overhauls that strain hospital IT budgets and extend sales cycles.
- EU Conformity Assessment Burdens:The MDR framework and EU AI Act impose quality management system requirements that favor established vendors and delay market entry for smaller algorithm developers.
- Biomarker Reference Laboratory Concentration:Margin pools concentrate in centralized lab channels, compressing per-test economics for distributed cognitive assessment software.
Strategic Opportunities
- Decentralized Neurological Care:Payer recalibration of remote cognitive monitoring reimbursement codes in the United States creates white space for home-based assessment platforms.
- Digital-Pharma Convergence:CROs are integrating Cambridge Cognition's regulatory-aligned software architectures into multi-site dementia trial networks, opening enterprise licensing channels.
- Academic Medical Center Validation Networks:Clinical validation partnerships with Johns Hopkins, Mayo Clinic, and UCSF anchor credibility for novel neuroimaging platforms seeking FDA clearance.
Industry Challenges
- HIPAA Data Governance Complexity:Cloud-based neuroimaging model training requires cross-site data sharing protocols that fragment across state-level privacy regulations.
- Neuroimaging-Radiology Certification Timelines:Radiologist credentialing for AI-assisted cognitive assessment tools varies by hospital system, delaying clinical adoption.
- Legacy EHR Integration Friction:Cognitive assessment software must map standardized psychometric scores into unstructured electronic health record fields, requiring custom API development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Diagnostics Market |
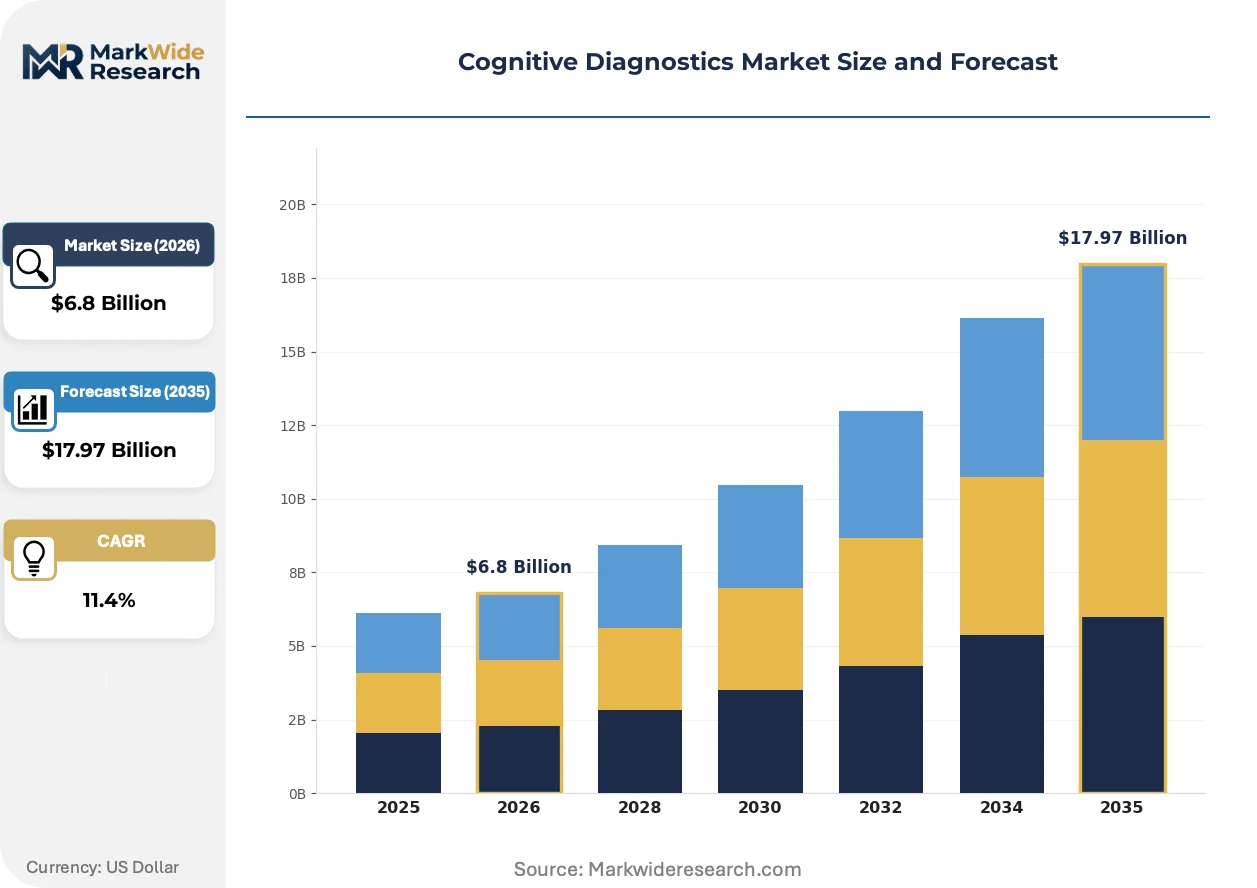
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuroimaging, Biomarkers, Genetic Testing, Cognitive Assessments Therapy Area: Alzheimer's Disease, Mild Cognitive Impairment, Frontal Lobe Disorders, ADHD Delivery Mode: In-Hospital Testing, Home Testing, Remote Monitoring, Automated Screening End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Diagnostics Laboratories |
| Companies Covered | IBM Watson Health, Google Health (DeepMind), Microsoft (Nuance Communications), NVIDIA (Clara AI), Cognetivity Neurosciences, Cambridge Cognition Ltd., Cogstate Ltd., Cognivue, Inc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Diagnostics Market Strategic Shifts
Algorithmic detection methods are displacing traditional pen-and-paper cognitive batteries, while regulatory frameworks on both sides of the Atlantic force architectural decisions that separate market winners from stranded assets.
Functional near-infrared spectroscopy (fNIRS) is expanding into bedside cognitive monitoring applications previously dominated by MRI scanners. Community hospitals and skilled nursing facilities in the United States are piloting portable fNIRS units for delirium detection. The technology is expanding into point-of-care neurological assessment by eliminating scanner suite infrastructure requirements and enabling same-day cognitive triage decisions.
The EU AI Act's risk classification system imposes conformity assessment obligations on algorithmic diagnostic tools seeking CE marking. High-risk cognitive assessment algorithms must demonstrate clinical validation across representative patient populations before market authorization. European vendors with established ISO 13485 quality management systems are capturing market share from developers facing first-time MDR compliance burdens.
Buyers in pharmaceutical trial operations are unbundling cognitive endpoint services from full-service CRO contracts. Sponsors now license digital assessment platforms directly and integrate them across multiple investigative sites through centralized data capture protocols. This procurement pattern is most visible in Alzheimer's and Parkinson's drug development programs where standardized cognitive batteries must deploy consistently across North American and European trial locations.
Cognitive Diagnostics Market Segmentation
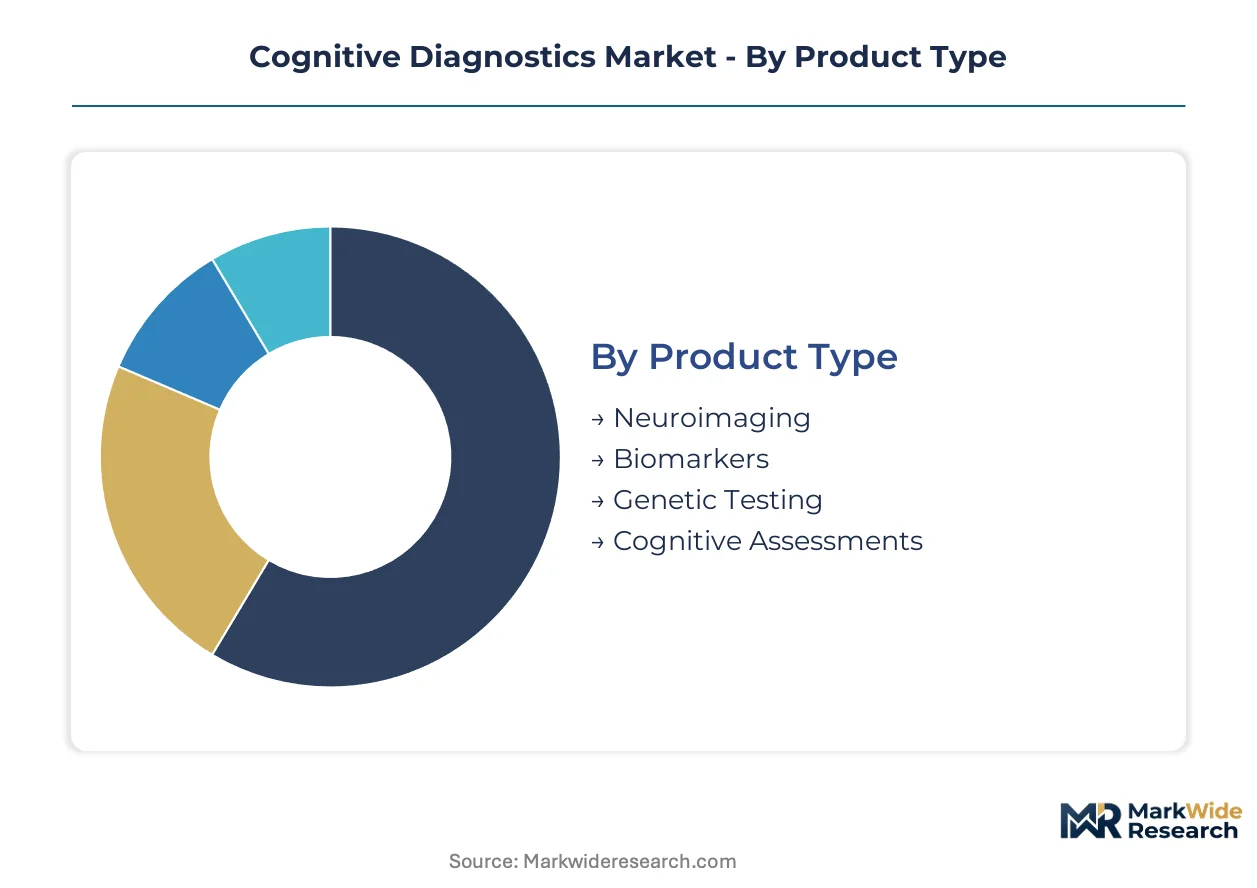
Cognitive diagnostics vendors configure product portfolios around capital intensity, reimbursement pathways, and integration complexity. Buyers select across these dimensions based on trial endpoint requirements, clinical workflow constraints, and patient access protocols.
Product Type:
Capital deployment thresholds and regulatory validation timelines separate buyer segments, with hospital systems weighing scanner infrastructure against software licensing economics.
- Neuroimaging:MRI and PET scanner platforms deliver structural and metabolic brain mapping at submillimeter resolution. Academic medical centers in the United States anchor procurement volumes for Alzheimer's drug trial imaging cores, though radiologist workflow integration costs strain community hospital budgets.
- Biomarkers:Cerebrospinal fluid and blood-based assays quantify amyloid, tau, and neurofilament light chain concentrations with picogram sensitivity. Reference laboratories in Germany and the United States concentrate margin pools as pharmaceutical sponsors mandate biomarker-linked endpoints for regulatory submissions.
- Genetic Testing:APOE genotyping and polygenic risk scores stratify patient populations for trial enrollment.
- Cognitive Assessments:Digitized neuropsychological batteries replace pen-and-paper protocols for remote patient access.
Volume sits with neuroimaging platforms; growth tilts toward automated cognitive assessments.
Therapy Area:
Trial pipeline concentration and payer coverage policies shape segment economics, with sponsors directing procurement toward indications with validated regulatory pathways.
- Alzheimer's Disease:Amyloid-targeting drug approvals have expanded reimbursement for diagnostic confirmation procedures. The FDA's breakthrough device pathway accelerates clearance for novel PET tracers and blood-based assays, concentrating demand in United States trial networks.
- Mild Cognitive Impairment:Prodromal stage identification drives longitudinal monitoring contracts with memory clinics. Germany's dementia care infrastructure and Japan's aging population clusters generate concentrated demand for early detection protocols that stratify progression risk.
- Frontal Lobe Disorders:Behavioral variant frontotemporal dementia and executive dysfunction assessments serve specialized neurology practices.
- ADHD:Pediatric and adult attention deficit protocols expand into primary care through digital screening tools.
Revenue concentrates in Alzheimer's disease; mild cognitive impairment is climbing the fastest.
Delivery Mode:
Patient access protocols and reimbursement code availability determine deployment feasibility across care settings.
- In-Hospital Testing:Scanner suite operations and specialist-administered neuropsychological batteries require physical infrastructure and credentialed personnel. Mayo Clinic and Johns Hopkins anchor validation networks that credential novel platforms for FDA submission packages.
- Remote Monitoring:Telehealth reimbursement expansions in the United States pull continuous cognitive assessment into home-based dementia care. Medicare Advantage plans in Florida and California pilot remote monitoring codes that reduce emergency department utilization for behavioral disturbances.
- Home Testing:Self-administered digital batteries and finger-prick blood collection kits bypass clinical visits.
- Automated Screening:Algorithmic triage tools integrate into primary care EHR workflows.
Clinical volume remains with in-hospital testing; automated screening gains share fastest.
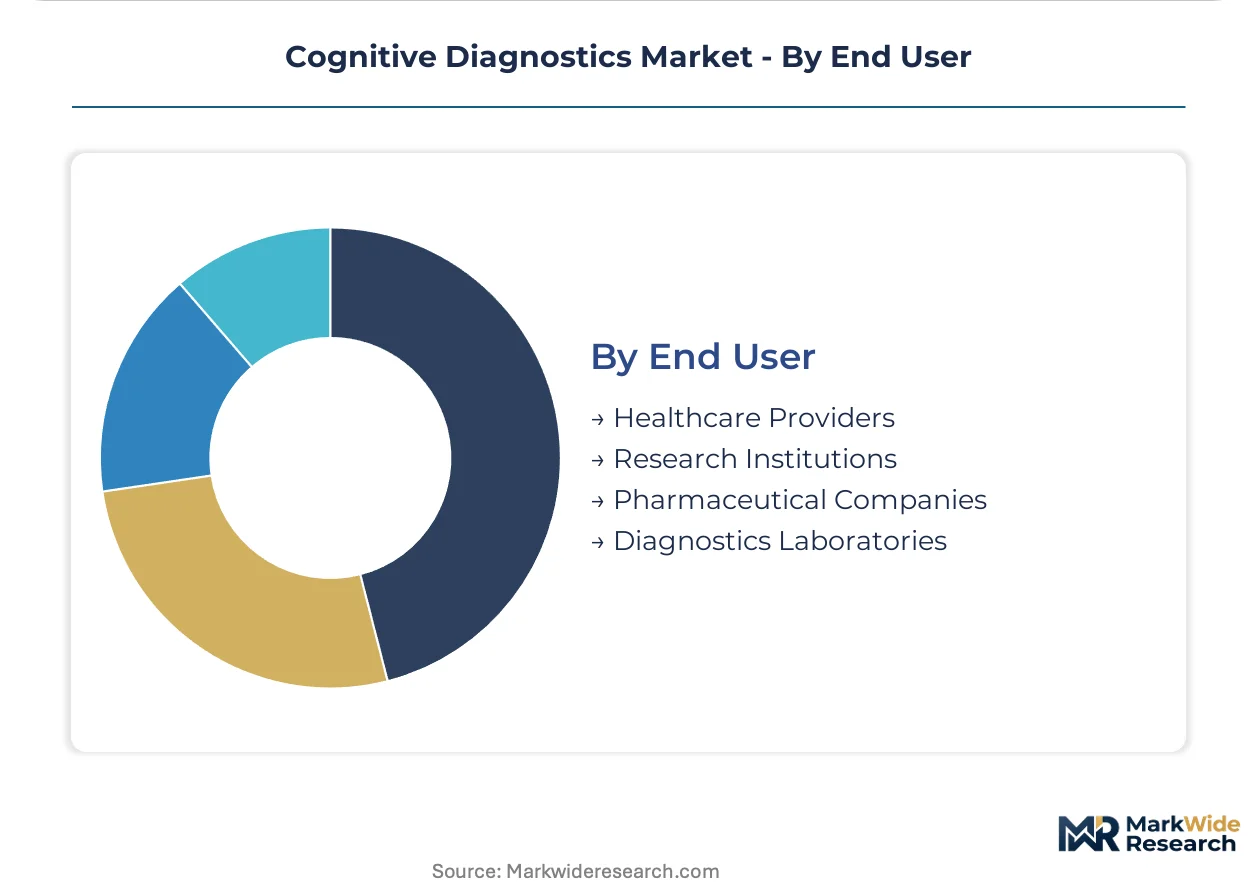
End User:
Procurement authority and data integration requirements fragment the buyer landscape across research and clinical channels.
- Healthcare Providers:Neurology departments and memory clinics purchase integrated diagnostic workflows. The United Kingdom's NHS dementia strategy and France's national Alzheimer plan channel public reimbursement toward validated cognitive assessment protocols.
- Pharmaceutical Companies:Sponsors license digital endpoints directly and deploy them across multi-site trial networks. Biogen and Eli Lilly procurement teams unbundle cognitive assessment services from full-service CRO contracts to standardize data capture across North American and European investigative sites.
- Research Institutions:Academic medical centers anchor validation studies for novel biomarker platforms.
- Diagnostics Laboratories:Quest Diagnostics and LabCorp scale reference testing for blood-based amyloid assays.
Spend concentrates with healthcare providers; pharmaceutical company procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's GPU cloud infrastructure anchors neuroimaging model training pipelines for cognitive diagnostic developers. Academic medical centers in Boston, Baltimore, and Rochester anchor clinical validation networks that credential novel platforms for regulatory submissions. Regulatory frameworks in the United States, Germany, China, Japan, and the United Kingdom shape product development timelines and commercialization pathways.
United States
Johns Hopkins, Mayo Clinic, and UCSF anchor clinical validation networks for FDA breakthrough device designations. HIPAA data governance requirements fragment cloud-based neuroimaging model training across state-level privacy regulations. Medicare Advantage plans in Florida and California pilot remote cognitive monitoring reimbursement codes that reduce emergency department utilization.
Germany
Reference laboratories in Munich and Heidelberg concentrate biomarker testing margin pools for Alzheimer's drug trial endpoints. The EU AI Act and MDR framework impose conformity assessment burdens on algorithmic diagnostic tools seeking CE marking. Siemens Healthineers anchors neuroimaging platform deployment across academic medical centers in Bavaria and Baden-Württemberg.
China
NMPA regulatory pathways accelerate clearance for blood-based amyloid assays targeting the country's aging population clusters. Shanghai and Beijing anchor multi-site dementia trial networks that deploy standardized cognitive batteries across investigative sites. Domestic algorithm developers leverage GPU cloud infrastructure from local technology conglomerates to train neuroimaging models.
Japan
PMDA consultation procedures streamline biomarker-linked endpoint validation for Alzheimer's drug development programs. METI funding programs support point-of-care neurological assessment technologies including portable fNIRS units. Tokyo and Osaka anchor memory clinic networks that drive longitudinal monitoring contracts for mild cognitive impairment protocols.
United Kingdom
The NHS dementia strategy channels public reimbursement toward validated cognitive assessment protocols in memory clinics. DeepMind's London-based research operations anchor AI-assisted neuroimaging model development for clinical deployment. Cambridge anchors digital cognitive assessment software architectures that CROs integrate into multi-site trial networks.
Cognitive Diagnostics Market Competitive Environment
Global majors compete with regional champions across regulatory-aligned software architectures and GPU-accelerated neuroimaging platforms. The vendor base separates into three tiers: technology conglomerates with cloud infrastructure, specialized cognitive assessment developers with regulatory expertise, and imaging equipment manufacturers with scanner deployment capabilities. Dominant competitive moves include strategic partnerships between algorithm developers and academic medical centers, plus portfolio diversification into remote patient access protocols.
Within the technology conglomerate tier, IBM Watson Health, Google Health, and NVIDIA occupy positions that exemplify divergent strategic vectors. IBM Watson Health represents enterprise data integration into multi-site dementia research networks. Google Health anchors AI-assisted neuroimaging model development through DeepMind's London-based research operations. NVIDIA exemplifies GPU cloud infrastructure provision that sustains training pipelines for neuroimaging models. Cambridge Cognition Ltd. and Cogstate Ltd. sit within the specialized tier, representing regulatory-aligned software architectures that CROs deploy across pharmaceutical trial networks.
| Leading Market Players |
|---|
| IBM Watson Health |
| Google Health (DeepMind) |
| Microsoft (Nuance Communications) |
| NVIDIA (Clara AI) |
| Cognetivity Neurosciences |
| Cambridge Cognition Ltd. |
| Cogstate Ltd. |
| Cognivue, Inc. |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up reference laboratory chains in the United States and Germany anchor supply concentration for biomarker testing, translating scanner hardware scarcity into premium pricing for neuroimaging platforms while compressing per-test margins for distributed cognitive assessment software.
Pricing Analysis
Warranty and service bundling separates premium neuroimaging platforms from unbundled software licensing models, with Siemens Healthineers and GE Healthcare including radiologist training and PACS integration in capital contracts while Cambridge Cognition and Cogstate sell seat-based subscriptions without implementation support. Price differentiation hinges on FDA breakthrough device designation tier and enterprise deployment scale, with pharmaceutical sponsors showing lowest price sensitivity for multi-site trial standardization while community hospitals face acute budget constraints. Cost compression in automated screening tiers is intensifying because Medicare Advantage plans are piloting remote monitoring codes that prioritize per-test economics over upfront licensing. Memory clinics and primary care networks exhibit highest price sensitivity, whereas CRO procurement teams prioritize regulatory alignment over cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical sponsors mandate multi-supplier qualification for biomarker assays, forcing reference laboratories to qualify backup vendors for amyloid and tau testing alongside primary relationships with Roche Diagnostics and Fujirebio. Geographic supply concentration centers on Germany, the United States, and Japan for high-sensitivity immunoassay platforms, while GPU cloud infrastructure for neuroimaging model training draws from NVIDIA's Silicon Valley partnerships and domestic alternatives in China. Rare earth magnet supply for MRI scanners rests on Chinese processing capabilities, creating tariff exposure for OEMs assembling systems in the United States. Distribution runs through direct sales forces for capital equipment, contrasted with software-as-a-service platforms deploying through channel partnerships with EHR vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into biomarker assay development and cloud-based analytics pipelines is accelerating as vendors seek to capture margin pools currently concentrated in reference laboratory channels and GPU infrastructure providers.
For Market Incumbents: Anticipate unbundling pressure from pharmaceutical sponsors demanding direct platform licensing rather than full-service CRO contracts, and respond by deepening regulatory affairs capabilities for FDA breakthrough device submissions while securing exclusive validation partnerships with Johns Hopkins and Mayo Clinic networks to lock out emerging algorithm developers. For New Entrants and Emerging Players: Community hospitals in the United States represent an underserved buyer archetype priced out of academic medical center scanner deployments, offering white-space entry through portable fNIRS units for delirium detection and automated cognitive screening tools that bypass radiologist workflow integration requirements, with go-to-market traction through group purchasing organizations serving non-urban health systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cognitive assessment developers with ISO 13485 quality management systems and existing CE marking in Germany, as EU AI Act compliance burdens strand smaller algorithm vendors lacking regulatory infrastructure. Long-term viability hinges on reimbursement code capture for remote monitoring, with Medicare Advantage pilot expansions in Florida and California serving as the critical inflection signal for home-based assessment platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated clearance timelines compress revenue recognition cycles for Alzheimer's trial endpoint developers. |
| Academic Medical Center Partnership | Johns Hopkins and Mayo Clinic validation networks credential novel platforms for regulatory submissions. |
| Biomarker Assay Integration | Blood-based amyloid testing captures margin pools shifting from reference laboratories to platform vendors. |
| Remote Monitoring Reimbursement Strategy | Medicare Advantage pilot codes in Florida reduce emergency department utilization for behavioral disturbances. |
| GPU Cloud Infrastructure Partnership | NVIDIA Clara AI sustains neuroimaging model training pipelines lowering capital barriers for algorithm developers. |
Study Parameters
Multi-period observation of FDA breakthrough device designations, CE marking timelines, and remote monitoring reimbursement code expansions anchored the trend analysis, supplemented by interviews with regulatory affairs leads at cognitive diagnostic developers, hospital procurement managers at academic medical centers, CRO clinical operations directors, and payer access specialists at Medicare Advantage plans. Secondary validation drew from FDA 510(k) and De Novo filings, EMA medical device registrations, ClinicalTrials.gov protocol specifications, and CMS Medicare coverage determinations. Bottom-up triangulation across product-level revenue estimates and top-down cross-checks against pharmaceutical trial spending patterns ensured segmentation integrity.
Input-output matrix framing connected biomarker sensitivity thresholds, neuroimaging resolution specifications, and software licensing economics to endpoint demand across Alzheimer's drug development programs. Segmentation dimensions modeled encompassed product type, therapy area concentration, delivery mode feasibility, and end-user procurement authority. CAGRs were derived from regression analysis of historical clearance timelines and sponsor spending patterns across the projection horizon. Forecast inputs included PMDA consultation procedure durations in Japan and NMPA pathway accelerations in China.
Revisions become necessary when FDA reimbursement code expansions for remote cognitive monitoring stall, EU AI Act enforcement timelines accelerate, or radiologist credentialing requirements fragment across state-level regulations. Deviation in pharmaceutical trial pipeline prioritization away from amyloid-targeting mechanisms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Inflammatory Markers Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Diabetic Assays Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Liver Function Tests Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market