
 Frozen Bakery Additives Market | 2026-2036
Frozen Bakery Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Bakery Additives Market Analysis
Clean-label specification tiers is rotating demand away from synthetic preservatives toward enzyme-based and fermented solutions. Cargill, Incorporated leverages its North American supply chain to anchor distribution for modified starch alternatives. Kerry Group differentiates through integrated taste-and-nutrition platforms that span emulsifiers and flavor systems. Corbion specializes in fermentation-derived ingredients, sustaining technical credibility with industrial bakery clients.
Frozen bakery additives comprise functional ingredients—emulsifiers, stabilizers, enzymes, oxidizing agents, and reducing agents—dosed at 0.1% to 5% by flour weight to control dough rheology, extend shelf life, and standardize finished product texture under freeze-thaw cycles. Their primary commercial purpose is to reconcile the structural degradation of gluten networks and starch retrogradation that occurs during frozen storage of unbaked or par-baked goods. Bread improvers command the deepest margin pools due to formulation complexity and technical support bundling, while emulsifiers represent the fastest-growing product type as clean-label mono- and diglyceride replacements gain traction. Application concentration in breads reflects volume scale, though pastries generate premium pricing through specialized fat-stabilization requirements.
The FDA governs GRAS determinations for enzyme additives in the United States, while the EU Green Deal and F-Gas Regulation restrict synthetic refrigerants and chemical preservatives across European frozen bakery supply chains. EFSA evaluations of novel enzymes directly shape market access timelines for biotech-derived improvers. Stakeholders must monitor regulatory divergence between enzymatic approval pathways in North America and Europe, as dual-registration requirements will determine which additive portfolios achieve scalable cross-border supply.
Market Dynamics
Enzyme-based reformulation is compressing synthetic additive margins as Europe's F-Gas Regulation and clean-label procurement mandates in North America force simultaneous technical and supply-chain recalibration across frozen bakery ingredient portfolios.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon refrigerants is compelling frozen bakery producers to adopt enzyme-based shelf-life extenders that perform under modified cold-chain temperatures.
- Clean-label procurement mandates:US food service operators are specifying fermented wheat gluten and ascorbic acid replacements in frozen dough contracts, pulling formulation demand toward natural oxidation control systems.
- Industrial baking corridor concentration:Germany's Rhineland-Palatinate and Lower Saxony clusters are consolidating par-baked production, creating volume anchors for specialized stabilizer and emulsifier supply.
Market Restraints
- Raw material volatility:Wheat starch and vegetable oil feedstock costs fluctuate with Black Sea supply disruptions, compressing margin visibility for modified starch producers.
- Enzyme approval timelines:EFSA novel food consultations average 18-24 months, delaying market access for biotech-derived dough conditioners relative to GRAS pathways in the United States.
- Substitution pressure:High-pressure processing and modified atmosphere packaging technologies are encroaching on chemical preservative applications in premium frozen pastry segments.
Strategic Opportunities
- Underpenetrated artisan channel:Small-batch frozen bakery operators in France and Italy lack access to scaled enzyme dosing systems, creating white space for precision-blend service models.
- Dual-technology platforms:Convergence of fermentation science and precision enzyme engineering enables single-ingredient solutions replacing multi-additive stacks in clean-label bread improvers.
- Carbon border adjustment leverage:The EU Carbon Border Adjustment Mechanism incentivizes domestic enzyme production over imported synthetic alternatives, favoring regional fermentation capacity expansion.
Industry Challenges
- Formulation talent scarcity:Industrial bakeries struggle to hire enzymologists capable of optimizing dose-response curves across variable flour protein profiles.
- Freeze-thaw validation bottlenecks:Accelerated shelf-life testing protocols lack standardization between North American and European laboratory methodologies, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Bakery Additives Market |
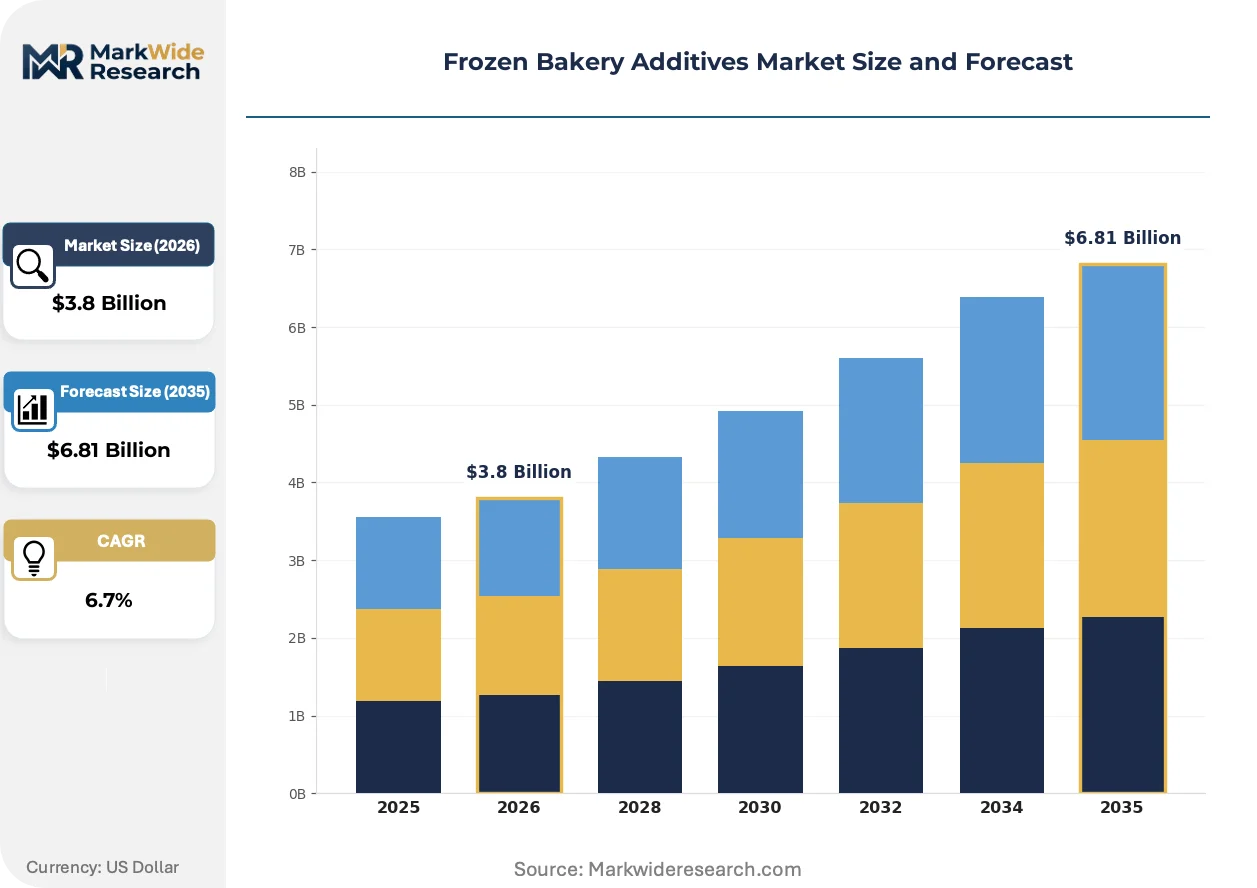
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread Improvers, Mixes, Stabilizers, Emulsifiers Application: Breads, Pastries, Cookies, Cakes End User: Food Service, Retail, Industrial Bakeries, Home Baking Distribution Channel: Online, Direct Sales, Wholesalers, Supermarkets |
| Companies Covered | International Flavors & Fragrances Inc., Cargill, Incorporated, Kerry Group, Corbion, Puratos, Archer Daniels Midland Company, Associated British Foods Plc, Lesaffre, Ab Nordbakels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Bakery Additives Market Emerging Trajectories
Bioprocess engineering and regulatory chemistry are converging to redefine frozen bakery additive specifications, with enzymatic solutions capturing formulation share previously held by petrochemical-derived ingredients.
Transglutaminase-crosslinked protein networks are displacing traditional gluten-strengthening agents in frozen dough applications. Industrial pizza and croissant manufacturers in Italy and Austria are adopting these enzyme systems at pilot scale. The displacement of azodicarbonamide and potassium bromate is compressing the addressable market for oxidizing agent specialists.
The EU Green Deal's Farm to Fork strategy is tightening residue limits for synthetic preservatives in frozen bakery supply chains. EFSA is evaluating novel enzyme classes for expanded food contact approvals, with industrial bread improvers facing the steepest compliance recalibration. German and Dutch producers are pre-registering fermentation-derived alternatives to secure uninterrupted market access.
Consolidated procurement by pan-European food service distributors is compressing additive supplier margins and elongating payment terms. Regional ingredient blenders in Belgium and the Netherlands are losing shelf space to integrated taste-and-texture platforms. This concentration is most visible in the quick-service restaurant frozen bakery supply channel, where three distributors control specification gatekeeping for par-baked roll programs.
Frozen Bakery Additives Market Segmentation
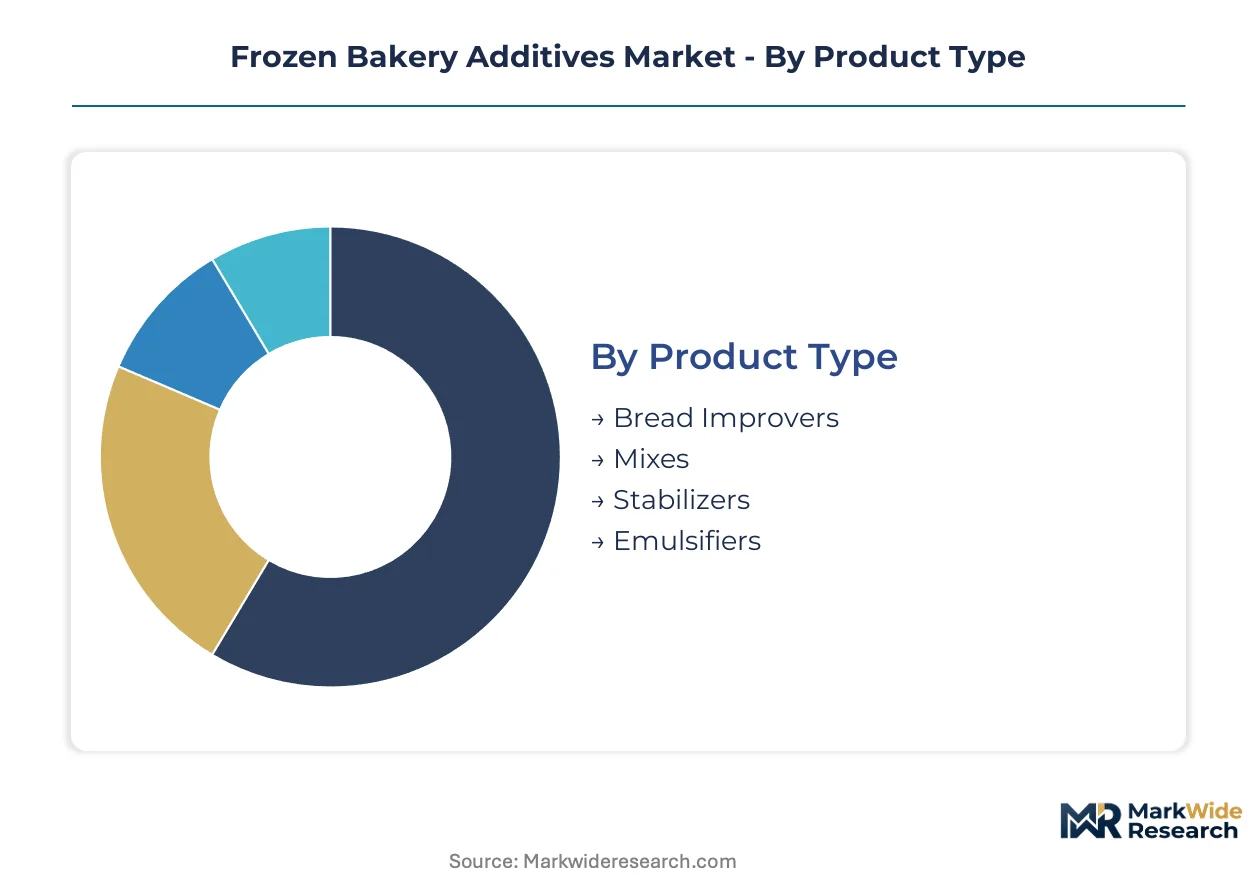
Segmentation in frozen bakery additives reveals how formulation complexity and cold-chain requirements create divergent margin profiles across product categories. Technical specifications for freeze-thaw stability and clean-label compliance fragment demand patterns across end-use channels.
Product Type:
Enzyme-based alternatives are displacing synthetic chemistry most aggressively in segments with direct food-contact exposure and visible ingredient declarations.
- Bread Improvers:Complex multi-functional blends combining enzymes, emulsifiers, and oxidizing agents dosed at 0.5% to 3% flour weight. Germany's industrial baking corridor in Rhineland-Palatinate concentrates procurement for par-baked roll programs, though EFSA novel enzyme consultations create 18-24 month approval bottlenecks for biotech-derived formulations.
- Emulsifiers:Mono- and diglyceride replacements and clean-label lecithin alternatives control fat-stabilization in laminated doughs. North American food service operators specify these in frozen croissant and Danish contracts as they phase out synthetic DATEM and SSL.
- Stabilizers:Modified starches and hydrocolloids manage moisture migration during freeze-thaw cycles.
- Mixes:Pre-blended additive systems targeting small-batch artisan bakers lacking in-house formulation capability.
Bread Improvers anchors the volume base while Emulsifiers gains share at the steepest rate.
Application:
Margin tiers separate high-volume commoditized categories from precision-formulation segments where technical service bundling commands premium pricing.
- Breads:Par-baked and frozen dough applications dominate tonnage, with gluten-network preservation and crust-quality maintenance driving additive selection. Industrial pizza manufacturers in Italy and Austria pilot transglutaminase-crosslinked protein systems at scale.
- Pastries:Laminated doughs require specialized fat-stabilization and oxidative stability under extended frozen storage. Premium pricing reflects layer-definition specifications and butter-flavor retention demands in viennoiserie applications.
- Cookies:Spread control and moisture management formulations for frozen cookie dough retail programs.
- Cakes:Aeration stability and crumb-structure preservation in frozen layer cake and muffin batters.
Breads generates the deepest volume concentration while Pastries captures the widest margin spreads.
End User:
Procurement sophistication divides segments between specification-driven contract manufacturers and price-sensitive spot buyers.
- Industrial Bakeries:High-volume par-baked and frozen dough producers with dedicated enzymologists optimizing dose-response curves. Germany's Lower Saxony cluster consolidates demand for standardized improver supply with integrated technical support.
- Food Service:Quick-service restaurant chains and contract foodservice operators with clean-label mandates specifying fermented wheat gluten and ascorbic acid replacements.
- Retail:Private-label frozen bakery programs with cost-optimized additive specifications.
- Home Baking:Consumer-facing frozen dough and batter products with simplified ingredient declarations.
Industrial Bakeries commands the largest contract values while Food Service is expanding specifications most rapidly.
Distribution Channel:
Channel concentration shapes payment terms and technical service intensity across customer tiers.
- Direct Sales:Dedicated technical service relationships with industrial bakery accounts requiring customized formulation development and freeze-thaw validation support.
- Wholesalers:Pan-European food service distributors consolidating procurement and compressing supplier margins through specification gatekeeping.
- Online:Emerging channel for precision-blend service models targeting underpenetrated artisan operators in France and Italy.
- Supermarkets:Retail private-label program supply with standardized product-mix requirements.
Direct Sales retains the deepest technical engagement while Wholesalers concentrates procurement leverage most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in frozen bakery additives tilt toward net-import dependence in Asia-Pacific markets while European producers leverage fermentation-derived ingredient trade surpluses. Cold-chain infrastructure gaps in emerging economies constrain additive efficacy, forcing reformulation for ambient-tolerant distribution. Regulatory divergence between FDA GRAS pathways and EFSA novel enzyme consultations fragments cross-border product registration strategies.
United States
Food service operators across quick-service restaurant chains are mandating clean-label frozen dough specifications that exclude synthetic preservatives. The FDA governs GRAS determinations for enzyme additives, with approval timelines averaging 12-18 months versus European counterparts. Chicago and Minneapolis industrial baking clusters concentrate par-baked production capacity, driving concentrated demand for emulsifier and stabilizer supply with integrated technical support.
Germany
The Rhineland-Palatinate and Lower Saxony industrial baking corridors consolidate European par-baked output, creating volume anchors for specialized improver formulations. The EU F-Gas Regulation accelerates reformulation toward enzyme-based shelf-life extenders compatible with modified cold-chain temperatures. Mannheim and Hanover host the continent's densest concentrations of industrial bakery R&D facilities, where enzymologists optimize dose-response curves for variable wheat protein profiles.
France
Artisan frozen bakery operators in Provence and the Loire Valley lack access to scaled enzyme dosing systems, creating service model opportunities for precision-blend suppliers. The EU Green Deal's Farm to Fork strategy tightens residue limits for synthetic preservatives across frozen supply chains. Lille and Lyon industrial zones concentrate croissant and viennoiserie par-baked production, where laminated dough applications command premium pricing for fat-stabilization additives.
Italy
Industrial pizza manufacturers in Emilia-Romagna and Lombardy pilot transglutaminase-crosslinked protein systems at commercial scale. EFSA evaluations of novel enzyme classes directly shape market access timelines for biotech-derived dough conditioners. Milan and Bologna clusters drive demand for gluten-network preservation solutions in frozen dough applications, with technical validation protocols varying from North American laboratory methodologies.
Netherlands
Pan-European food service distributors headquartered in Rotterdam and Utrecht consolidate procurement leverage, compressing additive supplier margins through specification gatekeeping. REACH compliance requirements for chemical additives push reformulation toward fermentation-derived alternatives. The Eindhoven region anchors precision fermentation capacity expansion, with domestic enzyme production favored under the EU Carbon Border Adjustment Mechanism.
Frozen Bakery Additives Market Vendor Landscape
Concentration sits with integrated taste-and-texture platforms and fermentation-derived specialists that span multiple additive categories. The vendor base separates into three tiers: multinational ingredient conglomerates with North American supply chain anchoring, European fermentation science specialists with industrial bakery technical credibility, and regional blenders losing shelf space to consolidated procurement. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with industrial baking R&D facilities.
Within the integrated platform tier, Cargill, Incorporated and Kerry Group exemplify scale-driven positioning that combines emulsifier, flavor, and nutrition systems. Corbion occupies a specialist position as a fermentation-derived ingredient provider, sustaining technical relationships with industrial bakery clients. These three companies represent contrasting archetypes: supply-chain anchoring, integrated taste-and-nutrition bundling, and fermentation science credibility.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Cargill, Incorporated |
| Kerry Group |
| Corbion |
| Puratos |
| Archer Daniels Midland Company |
| Associated British Foods Plc |
| Lesaffre |
| Ab Nordbakels |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85% in Germany's Rhineland-Palatinate enzyme fermentation facilities compress margin flexibility for regional producers while anchoring price floors for specialized bread improver formulations. This scale concentration simultaneously limits spot-market availability and elevates contract premiums for buyers requiring EFSA-compliant documentation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered rebates scaling across annual flour-weight commitments. Price differentiation separates fermentation-derived enzyme grades from synthetic preservative alternatives, with certification to EU Green Deal residue standards commanding substantial premiums. Cost compression in standard-grade emulsifiers is intensifying because pan-European food service distributors consolidate procurement leverage. Small-batch artisan operators in France exhibit the highest price sensitivity, while Germany's industrial baking corridor demonstrates lowest sensitivity due to technical service bundling requirements.
Supply Chain Analysis
Container availability constraints on Rotterdam-Antwerp trade lanes elevate inbound logistics costs for modified starch feedstocks sourced from Black Sea wheat processing facilities. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for fermentation-derived enzyme production, with secondary sourcing from North American modified starch processors. Raw material dependencies rest on wheat starch, vegetable oil derivatives, and precision fermentation substrates. Single-source vulnerability persists in transglutaminase enzyme supply where three producers control commercial-scale capacity. Distribution runs through pan-European food service distributors with specification gatekeeping authority over par-baked roll programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-based alternatives are displacing synthetic chemistry across frozen bakery supply chains, forcing incumbents to defend formulation portfolios against high-pressure processing and modified atmosphere packaging substitutes in premium pastry segments.
For Market Incumbents: Fortify fermentation capacity in the Eindhoven region to secure carbon border adjustment advantages under EU trade mechanisms. Deepen technical service relationships with industrial bakery R&D facilities in Mannheim and Hanover to embed dose-response optimization capabilities. These moves defend against regional blenders losing shelf space to consolidated procurement platforms. For New Entrants and Emerging Players: Precision-blend service gaps for artisan operators in Provence and the Loire Valley represent immediate white-space opportunity. Target France's underpenetrated small-batch frozen bakery channel with enzyme dosing system leasing models. Deploy direct online distribution to bypass wholesaler margin compression and establish technical credibility before scaling to industrial accounts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation science specialists with EFSA pre-registration pipelines over commodity synthetic producers. Long-term viability hinges on regulatory chemistry capabilities spanning dual-continent approval pathways. Monitor EFSA novel enzyme consultation timelines as inflection indicator for biotech-derived improver market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures margin pool from enzyme substrates while securing supply under EU Carbon Border Adjustment Mechanism. |
| EFSA Pre-Registration Pipeline Investment | Accelerates market access timelines for biotech-derived dough conditioners relative to 18-24 month standard consultations. |
| Technical Service Partnership with Industrial R&D Facilities | Embeds formulation expertise within Germany's Lower Saxony baking corridor for recurring improver contracts. |
| Precision-Blend Service Model for Artisan Channel | Addresses dosing system gaps in France and Italy where small-batch operators lack in-house enzymology capability. |
| Clean-Label Certification Investment | Qualifies supply for North American food service operator mandates excluding synthetic preservatives from frozen dough specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with industrial bakery procurement directors, enzymology R&D leads, food service distributor category managers, and fermentation facility plant managers. Secondary validation drew from EFSA novel food consultation databases, EU F-Gas Regulation implementation reports, customs trade data for modified starch imports, and SEC filings of listed ingredient conglomerates. Bottom-up volume triangulation across end-use segments was cross-checked against top-down value estimates from supply-side capacity assessments.
Across the analysis window, the forecasting framework modeled product type segments, application categories, end-user procurement tiers, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating enzyme substitution rates and clean-label procurement mandate penetration curves. Industry-specific inputs included EFSA approval timeline distributions and industrial baking corridor capacity utilization trends.
Material uncertainties — Black Sea supply disruptions, EFSA consultation delays, and high-pressure processing technology cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory chemistry convergence and fermentation scale-up economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Soft Biscuit Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
South America Ice Cream Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Global Bakery Product Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Baking Molds and Trays Market