
 Low Calorie Bread Market | 2026-2036
Low Calorie Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Bread Market Foresight
Asset-light co-manufacturing and contract baking arrangements is rewriting competitive entry economics for low-calorie bread brands. Dave's Killer Bread leverages its organic supply chain infrastructure to sustain premium positioning in the alternative flour segment. Sara Lee competes through mainstream supermarket distribution density, while Franz Bakery anchors regional production scale across the Pacific Northwest.
Low calorie bread denotes baked goods formulated with reduced caloric density through modified carbohydrate profiles, typically substituting refined wheat with whole wheat, almond flour, or psyllium husk to achieve sub-90 kcal per standard slice. Manufacturers employ enzymatic processing and extended fermentation to preserve structural integrity while lowering glycemic load. Sliced bread occupies the dominant volume position given its breakfast and sandwich utility, though rolls and bagels command higher per-unit margins in foodservice channels. Almond flour and psyllium husk formulations represent the fastest-expanding ingredient category as ketogenic and diabetic consumer segments deepen their bakery purchases.
The FDA governs nutrient content claims and serving-size definitions that determine whether products qualify for "low calorie" or "light" labeling on retail packaging. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that influence shelf placement and price positioning. Stakeholders must monitor evolving fiber definition standards and added-sugar disclosure requirements that will determine which ingredient portfolios retain compliant label claims.
Market Dynamics
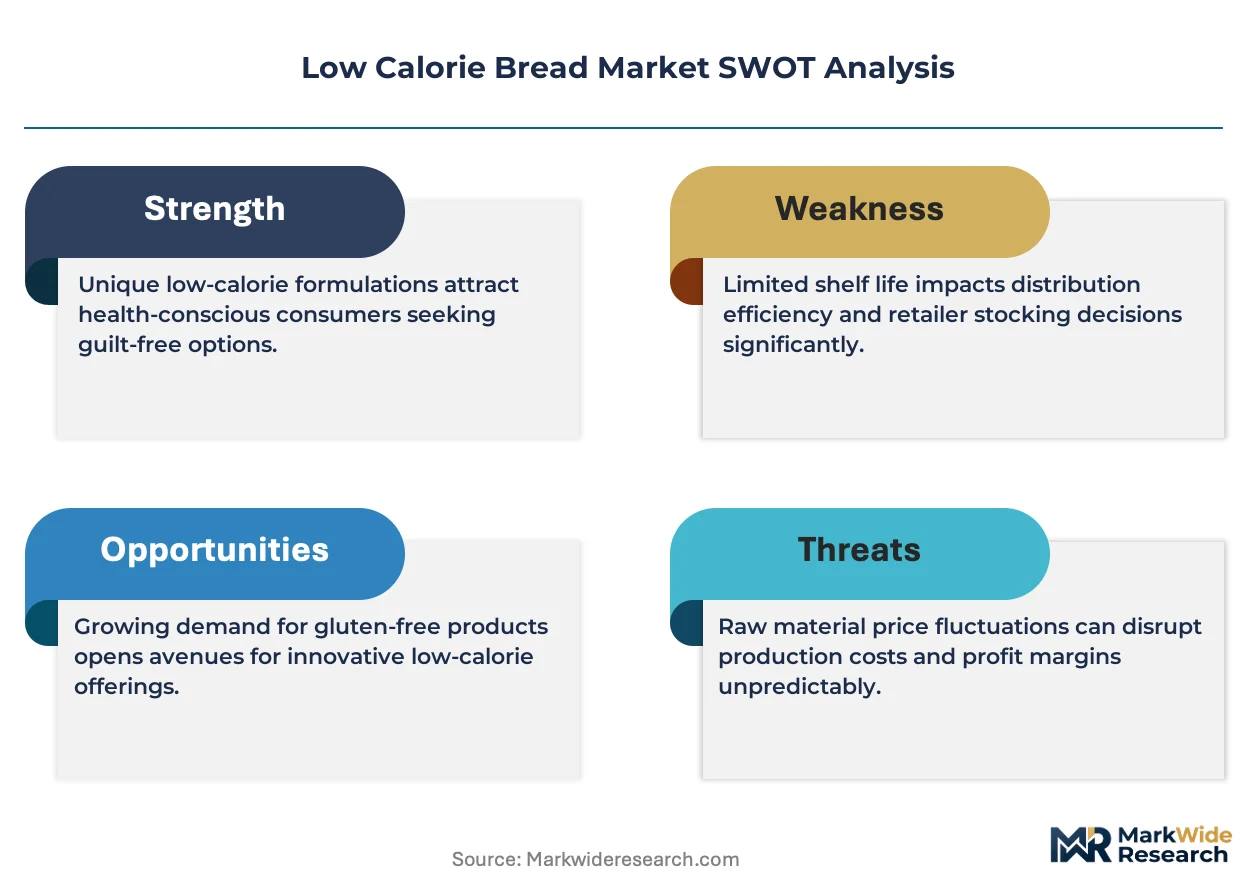
Reformulation pressure from updated FDA labeling requirements for added sugars and fiber disclosure is forcing manufacturers to rebuild ingredient portfolios around alternative flours and soluble fiber enrichment, compressing traditional wheat-based margins while opening premium positioning for compliant brands.
Growth Catalysts
- Urban Millennial Demand:Health-conscious consumers in metropolitan United States grocery markets drive bakery aisle traffic toward reduced-calorie options with clean-label credentials.
- USDA Organic Certification:Tiered market access thresholds from organic and Non-GMO Project verification accelerate shelf placement in premium health-food retail channels.
- Enzymatic Processing:Advanced fermentation techniques preserve structural integrity in sub-90 kcal formulations, enabling manufacturers to meet texture expectations without caloric density.
Market Restraints
- Almond Flour Input Volatility:California almond crop sensitivity to drought conditions creates price instability for ketogenic-formulation feedstocks.
- Pacific Northwest Production Concentration:Regional baking scale dominance by established contract manufacturers limits co-manufacturing capacity for new entrants.
- FDA Fiber Definition Uncertainty:Evolving standards for isolated fiber compliance threaten existing label claims and require continuous reformulation investment.
Strategic Opportunities
- Foodservice Roll Expansion:Higher-margin bagel and roll formats in commercial dining channels remain underpenetrated by dedicated low-calorie specialists.
- Diabetic Consumer Segment:Glycemic-load-focused formulations for insulin-resistant populations represent unmet white space beyond weight-management positioning.
- Supermarket Perimeter Growth:Fresh bakery section expansion in United States grocery chains creates visibility opportunities distinct from center-store commoditization.
Industry Challenges
- Co-manufacturing Quality Consistency:Asset-light production models struggle to maintain enzymatic process control across multiple contract baking partners.
- Dual Certification Timelines:Simultaneous USDA organic and Non-GMO Project verification creates extended product launch cycles that delay revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Bread Market |
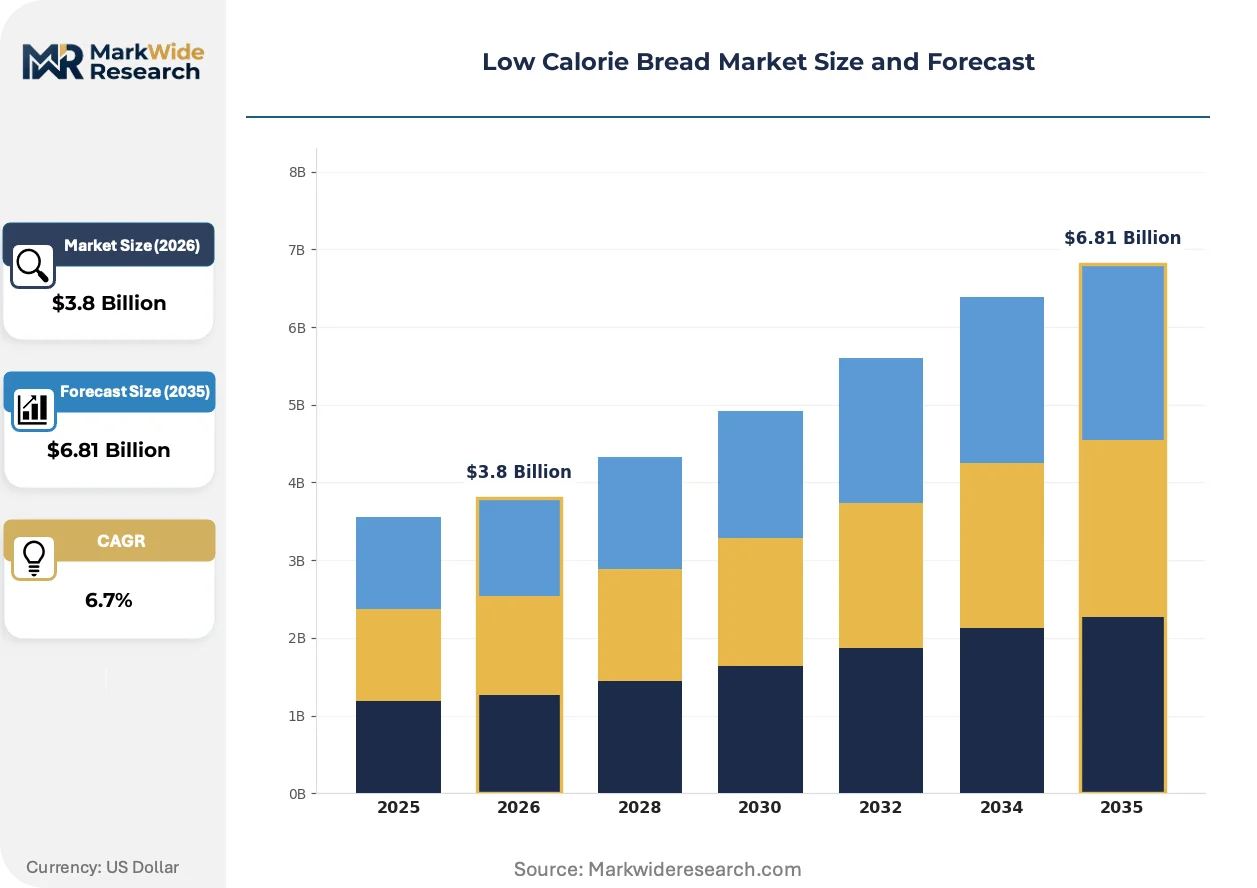
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliced Bread, Loaf, Rolls, Bagels Ingredient: Whole Wheat, Almond Flour, Oats, Psyllium Husk Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Target Consumer: Fitness Enthusiasts, Diabetics, Weight Watchers, Health-Conscious Individuals |
| Companies Covered | Dave’s Killer Bread, Sara Lee, Franz Bakery, Oroweat, Julian Bakery, L’oven Fresh, Silver Hills, Alvarado Street Bakery, Ezekiel 4:9, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Bread Market Shifts & Advancements
Active ingredient substitution and processing technology advancement are compressing the performance gap between reduced-calorie and conventional bread, while regulatory disclosure requirements and channel fragmentation reshape how manufacturers build brand equity.
Soluble fiber enrichment systems are migrating from isolated inulin and resistant starch toward psyllium husk and oat beta-glucan complexes that deliver both digestive health claims and moisture retention. Diabetic and ketogenic consumer segments in United States metropolitan markets are accelerating adoption of these formulations. The technology is migrating from niche health-food positioning into mainstream supermarket perimeter placement as texture parity improves.
The FDA's updated Nutrition Facts label mandate for added sugars disclosure is compressing formulation flexibility for manufacturers relying on honey, molasses, or fruit juice concentrates for browning and flavor. Brands must now source alternative browning agents or accept higher sugar line-item visibility that damages clean-label positioning. Sliced bread breakfast utility products face the steepest reformulation burden given their volume concentration in the category.
Direct-to-subscription bakery models are fragmenting traditional grocery channel dependence as urban consumers prioritize convenience and personalization over aisle browsing. Meal-kit integrations and diabetic-focused subscription boxes are capturing recurring revenue streams that supermarkets struggle to replicate. This behavioral shift concentrates in coastal United States cities where delivery infrastructure and health-conscious demographics overlap most densely.
Low Calorie Bread Market Segmentation
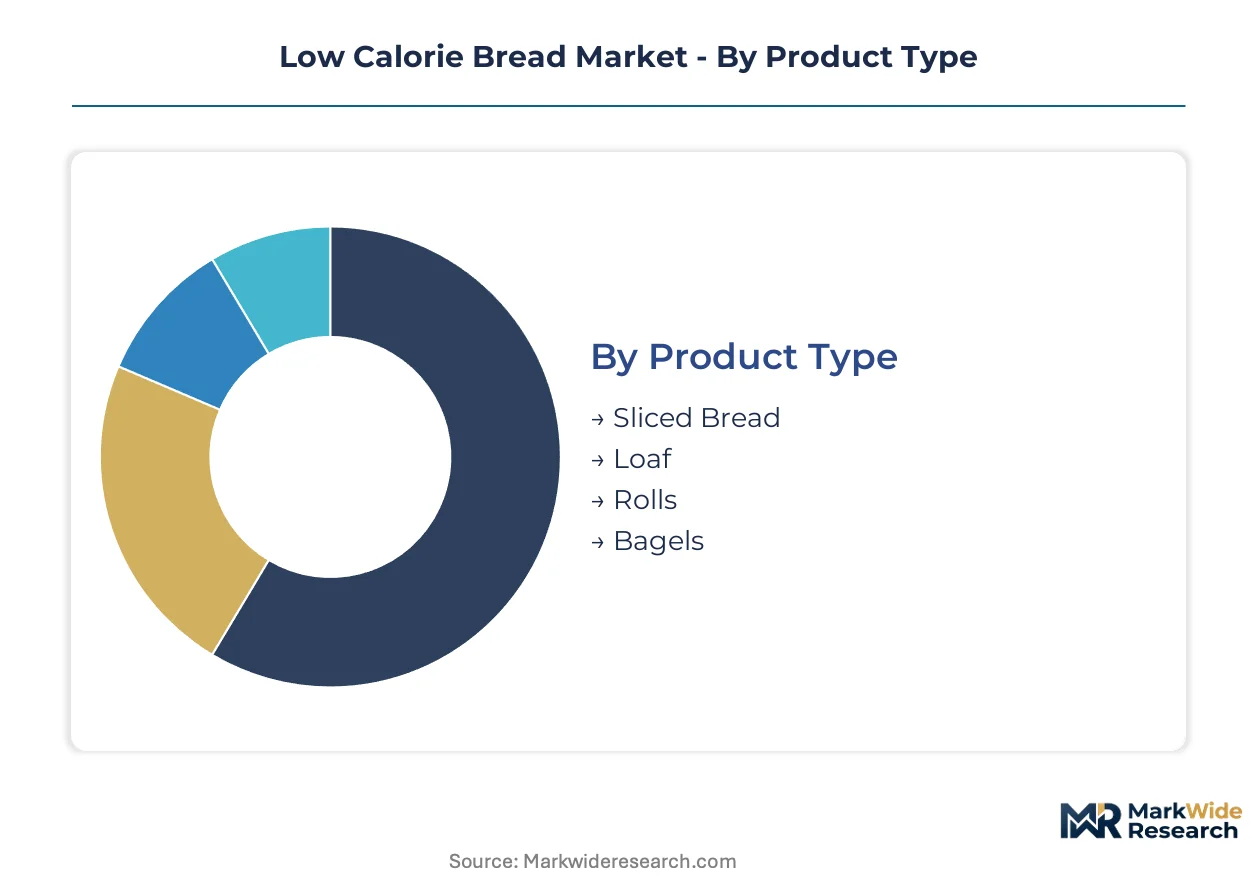
Low-calorie bread manufacturers must align formulation complexity, certification requirements, and channel economics against sharply divergent consumer priorities. Segmentation reveals where enzymatic processing investments recover premium pricing and where commodity positioning risks margin compression.
Product Type:
Cost tier determines whether manufacturers absorb enzymatic processing overhead or pass it through to price-sensitive breakfast and sandwich occasions.
- Sliced Bread:Standardized 20-24 slice formats dominate household breakfast and lunchbox preparation, with sub-90 kcal per slice specifications now baseline for metropolitan United States grocery placement. Reformulation pressure from FDA added-sugar disclosure rules concentrates investment here given volume exposure.
- Loaf:Unsliced artisan formats command premium positioning in health-food retail channels where consumers accept higher per-ounce pricing for customizable portion control and extended shelf-life claims.
- Rolls:Foodservice channels in United States urban centers drive demand for dinner-roll and slider formats, though portion-standardization challenges complicate caloric density labeling compliance.
- Bagels:Dense carbohydrate structure requires aggressive fiber enrichment and modified protein matrices to achieve reduced-calorie claims without texture collapse.
Sliced bread commands the established base. The steepest expansion runs through bagel formats as ketogenic and diabetic consumer segments deepen breakfast protein-fiber combinations.
Ingredient:
Application-specific functional requirements dictate whether alternative flours deliver structural integrity or merely nutritional window-dressing.
- Whole Wheat:Bran and germ retention provides 3-4g fiber per serving with established supply chain scale across North American grain belts, though glycemic load remains elevated for diabetic-positioned products.
- Almond Flour:Ketogenic and paleo consumer segments in California and New York metropolitan markets absorb price volatility from drought-sensitive Central Valley production, with formulations achieving sub-50 kcal per slice through fat-protein matrix restructuring.
- Oats:Beta-glucan soluble fiber delivers FDA-recognized cholesterol reduction claims, anchoring heart-health positioning in mainstream United States supermarket channels.
- Psyllium Husk:Bulk-forming fiber enables extreme caloric reduction with moisture-binding properties that preserve crumb structure in gluten-free formulations.
Whole wheat anchors volume production. Almond flour is climbing the fastest as ketogenic dietary adherence expands beyond clinical weight management into mainstream preventive health.
Distribution Channel:
Customer type concentration varies sharply by channel, with subscription-native demographics diverging from traditional grocery loyalty patterns.
- Supermarkets:Perimeter bakery expansion and center-store health-aisle placement in United States chains like Kroger and Albertsons drive visibility, though slotting fees compress margins for emerging brands without scale.
- Online Retail:Direct-to-subscription models capture recurring revenue from coastal urban consumers prioritizing convenience over aisle browsing, with diabetic-focused subscription boxes building predictable demand.
- Health Food Stores:Whole Foods and Sprouts placement requires simultaneous USDA organic and Non-GMO Project verification, creating tiered access thresholds that filter out commodity suppliers.
- Convenience Stores:Grab-and-go single-serve formats target impulse purchase occasions with limited SKUs and compressed shelf-life requirements.
Supermarkets retain the volume foundation. Online retail is gaining share fastest as fulfillment infrastructure and health-conscious demographics concentrate in United States coastal cities.
Target Consumer:
Maturity of dietary adherence determines price elasticity and reformulation tolerance for texture compromise.
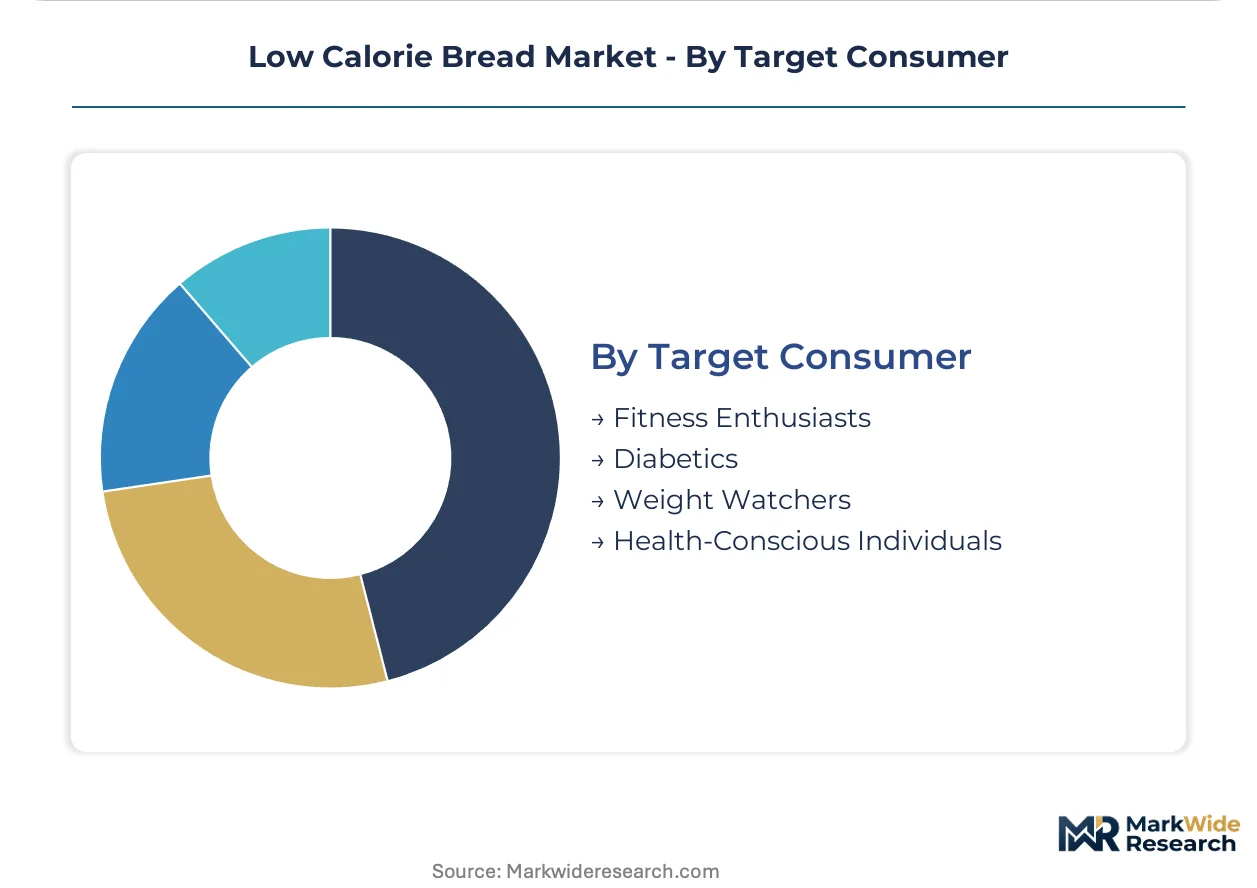
- Fitness Enthusiasts:Macro-tracking precision demands drive acceptance of protein-enriched and fiber-dense formulations with explicit per-slice nutritional disclosure.
- Diabetics:Glycemic load management requires resistant starch and soluble fiber matrices that slow glucose absorption, with clinical validation increasingly influencing purchase decisions.
- Weight Watchers:Points-system compatibility and portion-controlled packaging align with structured program adherence, though brand loyalty shifts with program methodology changes.
- Health-Conscious Individuals:Clean-label preference and reduced-calorie perception drive trial without strict dietary constraint, making this segment most vulnerable to taste-forgiveness limitations.
Health-conscious individuals provide the broadest addressable base. Diabetics show the steepest expansion trajectory as insulin resistance prevalence and clinical nutrition guidance converge on low-glycemic carbohydrate alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in low-calorie bread formulation technology, exporting enzymatic processing expertise and alternative flour supply chains while importing specialty grains from Canada and psyllium husk from India. Trade flows concentrate in metropolitan grocery corridors where FDA labeling compliance creates non-tariff barriers for foreign entrants.
United States
Urban millennial demand in New York, Los Angeles, and Chicago drives bakery aisle traffic toward sub-90 kcal sliced formats with clean-label credentials. The FDA's updated Nutrition Facts requirements for added sugars and fiber disclosure force continuous reformulation investment. Pacific Northwest production clusters around Portland and Seattle anchor contract baking capacity for emerging brands seeking asset-light entry.
Germany
Whole-grain consumption traditions align with reduced-calorie positioning as EFSA fiber health claims enable differentiated shelf placement. The country's national food regulator enforces strict additive thresholds that favor extended fermentation techniques over enzymatic shortcuts. Bavarian baking clusters supply reformulation expertise to private-label programs across Central European retail chains.
United Kingdom
Diabetic consumer segments in Greater London and Manchester accelerate demand for glycemic-load-focused formulations. The country's departure from EU harmonized food standards creates parallel compliance tracks for fiber definition and sugar disclosure. Midlands-based industrial bakeries scale production for discount supermarket chains competing on per-slice calorie transparency.
Japan
Aging demographics and metabolic disease prevalence expand the addressable base for functional bread with resistant starch matrices. The national pharmaceutical and food regulator maintains distinct approval pathways for foods with specified health uses that exceed standard nutrient content claims. Tokyo-Osaka corridor convenience stores drive single-serve format innovation with compressed shelf-life requirements.
Australia
Fitness enthusiast demand in Sydney and Melbourne sustains premium pricing for protein-enriched and ketogenic-positioned alternatives. The national therapeutic goods regulator monitors crossover products at the boundary of food and supplement classifications. Victorian grain belt supply chains provide oat beta-glucan feedstocks for cholesterol-reduction claim formulations.
Low Calorie Bread Market Competitive Landscape
On the supply side, the industry is moderately concentrated with tiered competitive dynamics separating national-scale baking conglomerates from regional contract manufacturers and specialty health-food operators. Strategic archetypes include organic supply chain integrators, mainstream distribution density builders, and ketogenic formulation specialists. Dominant competitive moves encompass co-manufacturing partnership expansion and simultaneous USDA organic plus Non-GMO Project dual certification pursuit.
Within the organic supply chain tier, Dave's Killer Bread exemplifies vertical integration into ingredient sourcing and Pacific Northwest production scale. Sara Lee occupies a position representing mainstream supermarket distribution density across conventional retail channels. Franz Bakery anchors regional contract manufacturing capacity that emerging brands access through asset-light entry arrangements.
| Leading Market Players |
|---|
| Dave's Killer Bread |
| Sara Lee |
| Franz Bakery |
| Oroweat |
| Julian Bakery |
| L'oven Fresh |
| Silver Hills |
| Alvarado Street Bakery |
| Ezekiel 4:9 |
| Others |
Supply & Pricing Matrix
Portland and Seattle production clusters anchor contract baking capacity for emerging low-calorie bread brands, with enzymatic processing specialization creating downstream pricing power for compliant manufacturers against commodity wheat-based competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the low-calorie bread market. Price differentiation rests on USDA organic certification grade and FDA fiber definition compliance tier, with dual-certified products commanding shelf placement premiums. Pricing pressure stems from almond flour input volatility driven by California drought cycles, compressing ketogenic formulation margins. Health-conscious urban millennials show lowest price sensitivity, while conventional supermarket shoppers in center-store channels exhibit highest elasticity.
Supply Chain Analysis
Franz Bakery and Pacific Northwest contract manufacturers hold concentrated enzymatic processing capacity for low-calorie bread production. Geographic supply concentrates in the United States, Canada, and India, with psyllium husk feedstocks drawing from Indian agricultural regions and specialty grains from Canadian prairie provinces. Raw material dependencies center on almond flour, oat beta-glucan, and resistant starch matrices. Single-source vulnerability runs through California almond crop concentration exposed to water allocation restrictions. Distribution runs through supermarket perimeter bakery expansion and direct-to-subscription channels in coastal metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie bread market operates as a defensive-moat story where FDA fiber definition compliance creates regulatory entrenchment, locking in compliant incumbents while forcing continuous reformulation investment from challengers.
For Market Incumbents: Insulate market position through captive supply chain control over Pacific Northwest enzymatic processing capacity and accelerated dual USDA organic plus Non-GMO Project certification timelines. Emerging asset-light co-manufacturing entrants threaten quality consistency advantages, making in-house fermentation expertise the critical defensive lever against private-label commoditization. For New Entrants and Emerging Players: Establish a beachhead in diabetic-focused subscription box channels where glycemic-load positioning commands recurring revenue predictability. Foodservice roll and bagel formats in urban United States commercial dining remain underpenetrated white space, accessible through enzymatic processing partnerships with established contract bakers rather than greenfield production investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors organic supply chain integrators with backward control over alternative flour sourcing and Pacific Northwest production scale. Long-term viability concentrates on brands with clinical validation partnerships for diabetic nutrition claims. The signal to watch is FDA fiber definition rulemaking, which will determine which ingredient portfolios retain compliant label claims and premium pricing access.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Acceleration | Simultaneous USDA organic and Non-GMO Project verification unlocks Whole Foods and Sprouts shelf placement. |
| Enzymatic Processing Scale-Up | Contract baking capacity expansion in Portland and Seattle clusters reduces asset-light entrant quality risks. |
| Diabetic Subscription Channel Launch | Direct-to-consumer recurring revenue models bypass supermarket slotting fee compression in coastal cities. |
| Alternative Flour Backward Integration | In-house almond flour and psyllium husk sourcing mitigates California drought-driven input volatility. |
| Foodservice Format Extension | Bagel and roll penetration into commercial dining captures higher-margin breakfast protein-fiber occasions. |
Research Methodology
Cross-validation between primary interviews with bakery operations directors, enzymatic processing engineers, supermarket category buyers, and health-food retail procurement managers anchors the qualitative findings against secondary validation from FDA labeling guidance documents, USDA organic certification databases, and Nielsen retail audit data. Bottom-up demand modeling from consumer segment adoption patterns triangulates with top-down market sizing from trade flow analysis and production capacity estimates.
Calibration against historical volume trajectories and elasticity parameters derived from price-point testing informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient matrix, distribution channel, and target consumer dietary adherence maturity. CAGRs were synthesized from segment-level growth rate distributions and cross-elasticity matrices, with enzymatic processing adoption curves and FDA compliance timeline assumptions as category-specific forecast inputs.
Sensitivities concentrate around almond crop yield volatility, evolving fiber definition standards, and subscription channel churn rates in coastal metropolitan markets. Quarterly review of FDA rulemaking dockets, California water allocation announcements, and health-food retail placement trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Bread Mix Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Specula Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Marzipan Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Ice Cream Market
Bakery Products
Sourdough Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Lentil Bread Market
Bakery Products
Pie Shells Market
Bakery Products
Pastries Market
Bakery Products
Bread Improver Market
Bakery Products
Malted Rye Flour Market