
 Low Calorie Rice Cake Market | 2026-2036
Low Calorie Rice Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Rice Cake Market Analytics
The weight management consumer segment is rebalancing toward everyday snacking occasions as calorie tracking apps normalize portion-controlled foods. Quaker Oats Company leverages its breakfast aisle dominance to cross-merchandise rice cakes into conventional grocery sets. Lundberg Family Farms anchors the organic sub-category with certified regenerative sourcing. Element Snacks competes through premium chocolate-coated positioning that commands shelf-space in specialty channels.
Low calorie rice cakes are puffed or extruded whole-grain discs typically manufactured from brown or white rice under high temperature and pressure, yielding a crispy texture with caloric density below 35 kcal per cake for use as a bread substitute or standalone snack. Organic and gluten-free product types capture margin pools through certification premiums and allergen-free positioning that justifies price separation from plain variants. Flavored rice cakes sustain faster velocity in online retail channels where direct-to-consumer sampling reduces trial barriers for novel taste profiles.
The FDA governs nutrition labeling accuracy and health claim substantiation for rice cake products sold in the United States, while the EMA and EFSA frameworks in Europe enforce additive restrictions and organic certification integrity that filter market entrants. Health Canada and PMRA oversight on pesticide residue limits in imported rice inputs shapes sourcing decisions for North American manufacturers. Stakeholders must monitor evolving front-of-package warning label requirements across multiple jurisdictions as sugar and sodium disclosure rules tighten.
Market Dynamics
Clean-label ingredient mandates from the FDA and EFSA are compressing formulation flexibility for rice cake manufacturers, forcing rapid supplier audits and alternative sourcing across the brown rice supply chain.
Growth Catalysts
- EU Organic Certification Integrity:EFSA enforcement of additive restrictions creates barrier-to-entry protection for compliant domestic producers, concentrating margin pools among certified operators.
- Fitness Tracking App Normalization:Calorie-counting platforms embed portion-controlled foods into daily routines, expanding addressable occasions beyond traditional diet segments.
- Extrusion Technology Advancement:High-pressure puffing systems reduce caloric density below 35 kcal per cake while preserving structural integrity for flavor coating adhesion.
Market Restraints
- Input Cost Volatility:Drought cycles in California and Arkansas rice belts create unpredictable brown rice pricing that compresses gross margins for organic sub-category producers.
- Supply Concentration Risk:Regenerative sourcing requirements limit viable rice suppliers to certified farms in the Sacramento Valley and Mississippi Delta regions.
- Substitution Threat:Cauliflower-based crispbreads and seaweed snacks capture shelf-space in specialty channels through lower carbohydrate positioning.
Strategic Opportunities
- Direct-to-Consumer Sampling:Online retail channels reduce trial barriers for novel flavor profiles through subscription box placement and micro-influencer partnerships.
- Regenerative Agriculture Incentives:USDA conservation programs and EU Green Deal farm subsidies offset certification costs for transition-period rice growers.
- Functional Ingredient Convergence:Protein fortification and probiotic coating technologies merge snacking occasions with sports nutrition and gut health categories.
Industry Challenges
- Clean-Label Reformulation Timeline:EFSA additive restrictions force 12-18 month ingredient trials to maintain texture without emulsifiers or artificial preservatives.
- Cross-Contamination Certification:Gluten-free facility audits require dedicated extrusion lines that strain capex budgets for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Rice Cake Market |
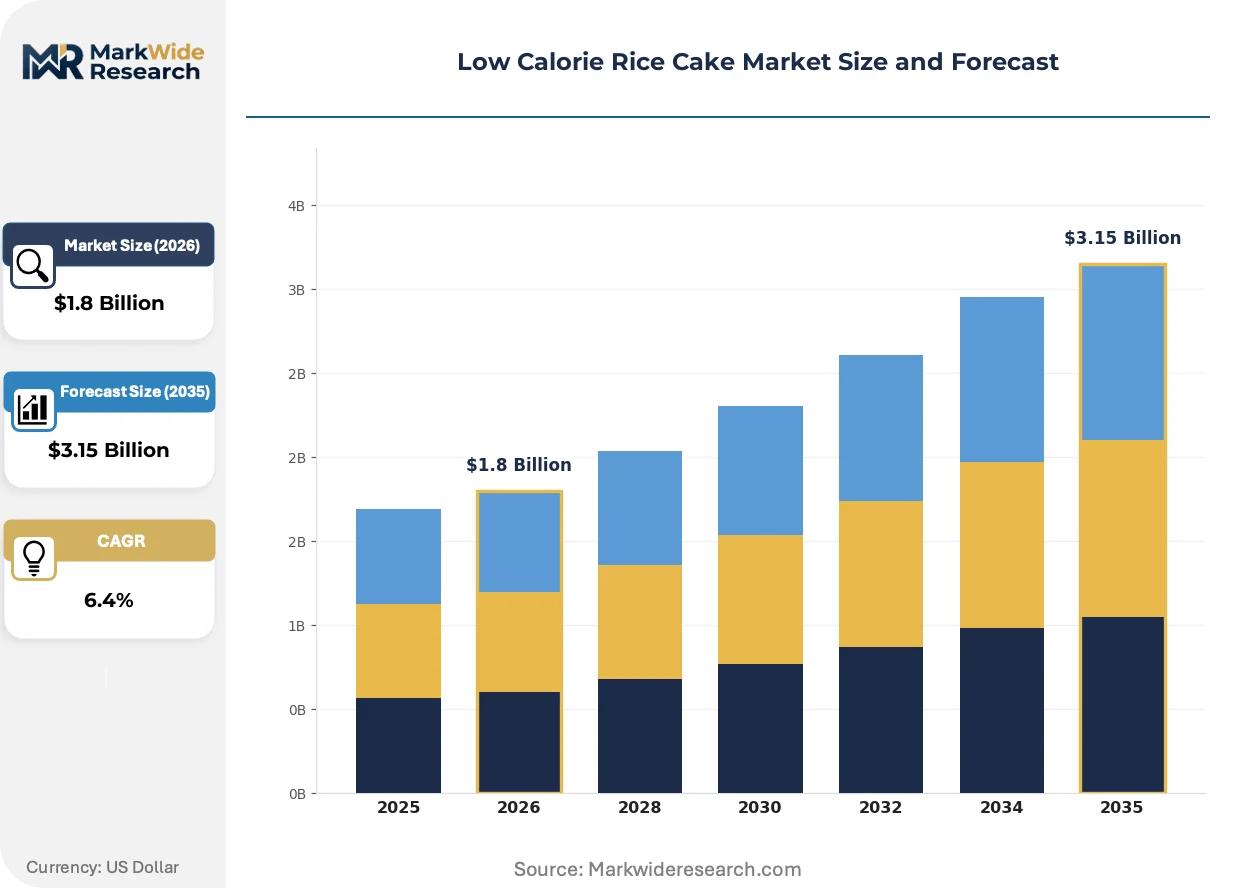
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Gluten-Free End User: Health-Conscious Consumers, Weight Watchers, Athletes, Families Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Serving Size: Individual Packs, Multi-Packs, Family Packs, Bulk Options |
| Companies Covered | Quaker Oats Company, Lundberg Family Farms, Wasa, Lotus Foods, Nature's Path, Kallo Foods, Element Snacks, Mars, Riso Gallo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Rice Cake Market Evolving Landscape
Extrusion and coating technologies are absorbing capital allocation as manufacturers compete on texture differentiation and flavor delivery systems rather than base commodity positioning.
High-pressure puffing systems are absorbing process innovation investment across rice cake manufacturing. Brown rice processors deploy these units to achieve uniform cell structure that withstands chocolate and yogurt coatings without breakage. Fitness-oriented buyers are absorbing the output as meal-replacement substrates, compressing demand for plain uncoated variants in conventional grocery.
REACH chemical registration requirements and EU front-of-package warning label proposals are tightening formulation disclosure standards. Manufacturers must submit full additive safety dossiers to ECHA for novel coating ingredients. The flavored sub-category faces the steepest compliance burden as natural flavor masking alternatives replace synthetic compounds.
Subscription-based snack boxes are absorbing trial-driven purchasing patterns from traditional retail sampling. Direct-to-consumer platforms bundle rice cake variety packs with fitness app partnerships, displacing single-flavor bulk purchases in conventional channels. Germany and Japan exhibit the strongest channel migration as urban consumers prioritize convenience over price per unit.
Low Calorie Rice Cake Market Segmentation
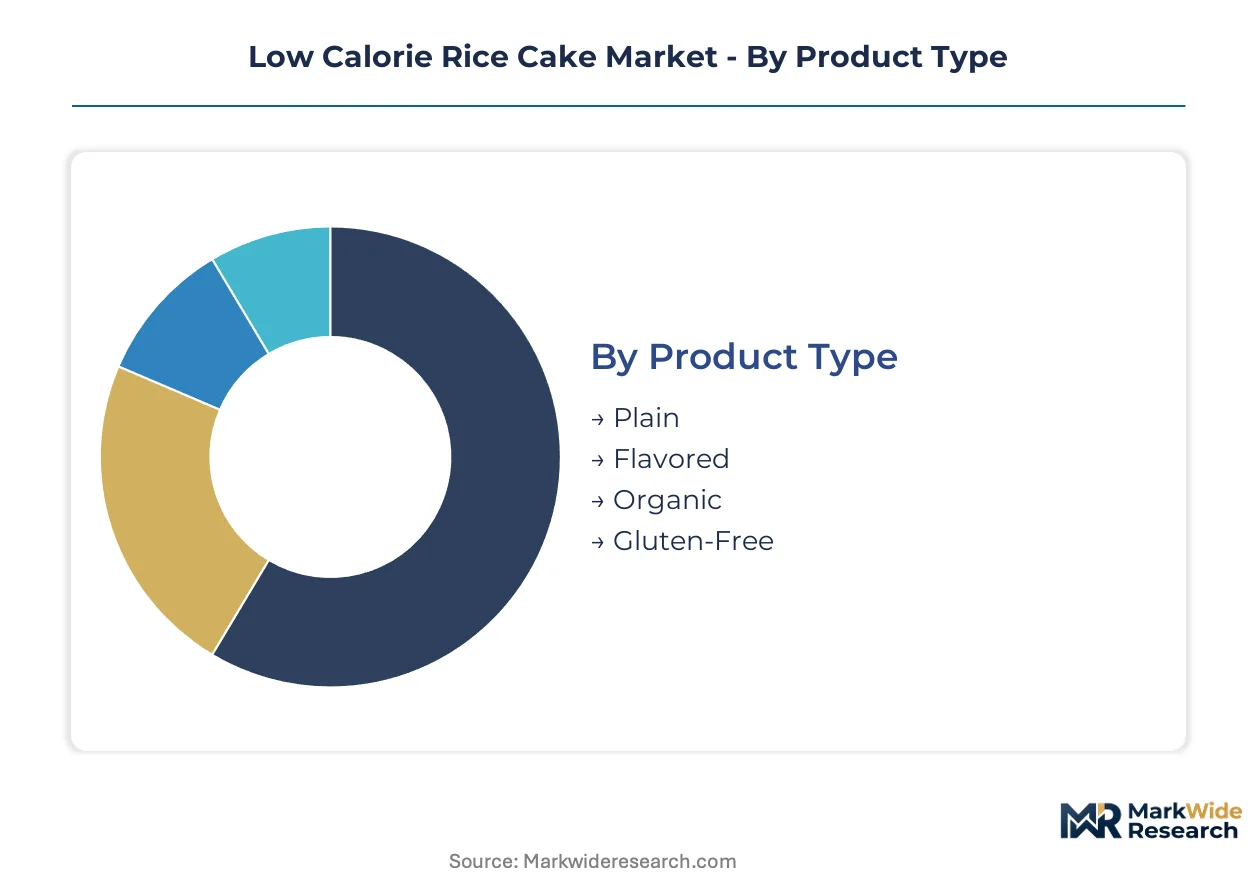
Segmentation in the Low Calorie Rice Cake Market reveals how formulation choices, consumption occasions, and channel strategies fragment demand across distinct buyer profiles. Manufacturers configure production lines and certification investments around these divides.
Product Type:
Standalone snacking formats dominate conventional grocery placement, while embedded nutritional substrates penetrate fitness and meal-replacement channels.
- Plain:Unflavored brown or white rice discs serve as bread substitutes and base ingredients for home customization. Demand concentrates in conventional supermarkets across Germany and Japan where price-sensitive households prioritize volume purchasing over taste variety.
- Flavored:Coated or seasoned variants—cheddar, caramel, chocolate—deploy extrusion-compatible flavor delivery systems. Online retail channels in the United States absorb the fastest velocity here, as direct-to-consumer sampling reduces trial barriers for novel taste profiles.
- Organic:Certified regenerative sourcing commands shelf-space premiums through EFSA-compliant additive restrictions.
- Gluten-Free:Dedicated facility production meets allergen-free positioning requirements in specialty channels.
Plain leads volumes today; Flavored is gaining share fastest.
End User:
Cost tier segmentation separates premium positioning for specialized nutrition from mass-market accessibility for everyday households.
- Health-Conscious Consumers:Fitness-oriented buyers integrate portion-controlled rice cakes into daily routines through calorie-tracking app normalization. This segment absorbs functional ingredient convergence—protein fortification and probiotic coatings—merging snacking with sports nutrition categories.
- Weight Watchers:Calorie-density discipline below 35 kcal per cake drives repeat purchase frequency. Demand concentrates in subscription-based snack boxes where portion-controlled packaging aligns with behavioral tracking tools.
- Athletes:Pre- and post-workout carbohydrate loading favors high-pressure puffed structural integrity for portable fuel.
- Families:Multi-pack configurations prioritize convenience and child-friendly flavor profiles in conventional retail.
Health-Conscious Consumers anchor revenue today; Athletes show the steepest expansion trajectory.
Distribution Channel:
Volume concentration varies sharply by geography, with urban convenience preferences reshaping channel migration patterns.
- Online Retail:Direct-to-consumer platforms bundle variety packs with fitness app partnerships. Germany and Japan exhibit the strongest channel migration as urban consumers prioritize convenience over price per unit.
- Supermarkets:Cross-merchandising from breakfast aisles into conventional grocery sets leverages existing brand recognition. The United States concentrates volume here through Quaker Oats Company shelf-space dominance.
- Health Food Stores:Certified organic and gluten-free positioning justifies premium pricing in specialty retail.
- Specialty Stores:Premium chocolate-coated variants command placement through Lundberg Family Farms regenerative sourcing credentials.
Supermarkets lead volumes today; Online Retail is climbing the fastest.
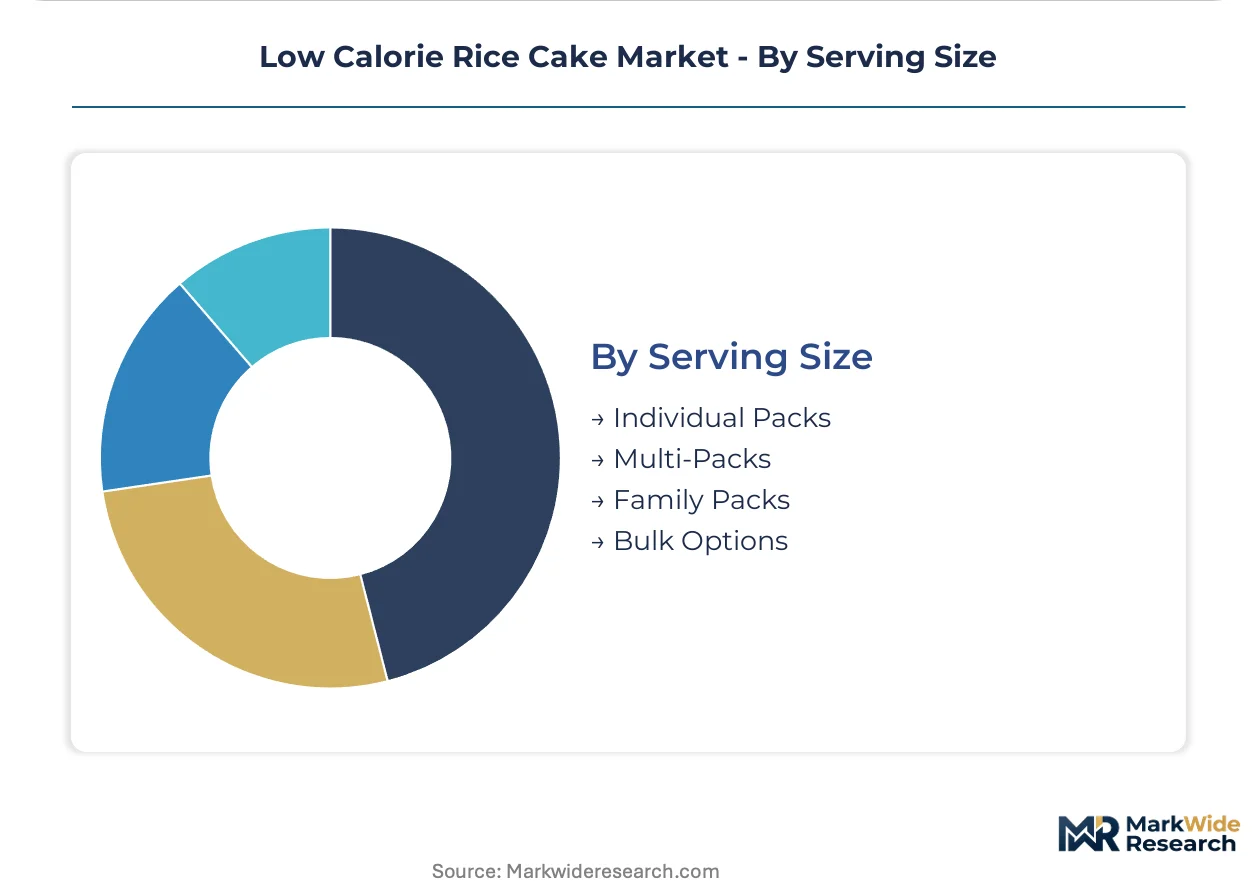
Serving Size:
Packaging configuration directly determines occasion targeting and procurement economics across buyer types.
- Individual Packs:Single-serve portions embed into fitness and workplace snacking routines. Calorie-tracking app users in Japan absorb these for precise portion control without measurement burden.
- Multi-Packs:Variety assortments reduce trial barriers for novel flavors in online subscription channels.
- Family Packs:Larger formats prioritize household pantry stocking in conventional supermarkets.
- Bulk Options:Foodservice and institutional procurement favors unpackaged or large-format supply for cost efficiency.
Family Packs lead volumes today; Individual Packs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sacramento Valley rice belt anchors global low-calorie rice cake production through regenerative sourcing clusters that supply certified organic inputs to North American and European manufacturers.
United States
Fitness-tracking app normalization drives portion-controlled snacking adoption across urban coastal markets. The FDA enforces nutrition labeling accuracy and health claim substantiation under 21 CFR regulations. The Arkansas-Mississippi Delta corridor concentrates brown rice milling capacity where regenerative certification programs expand acreage.
Germany
Clean-label ingredient mandates reshape formulation standards for conventional grocery placement. EFSA additive restrictions and EU Green Deal farm subsidies filter market entrants and offset transition costs for organic rice growers. The Hamburg-Bremen port cluster handles bulk organic rice imports from certified Asian suppliers.
Japan
Calorie-density discipline below 35 kcal per cake embeds rice cakes into workplace and fitness snacking routines. METI oversight on food additive safety and front-of-package labeling drives reformulation timelines. The Kanto region around Tokyo concentrates direct-to-consumer subscription channel growth for individual-pack configurations.
Canada
Health-conscious consumers in British Columbia and Ontario prioritize gluten-free and organic certifications in specialty retail channels. Health Canada and PMRA pesticide residue limits on imported rice inputs shape sourcing decisions for domestic manufacturers. The Prairie Provinces supply limited organic rice acreage, forcing reliance on U.S. and Asian certified suppliers.
United Kingdom
Subscription-based snack boxes absorb trial-driven purchasing patterns from conventional retail sampling. EFSA-aligned additive restrictions post-Brexit maintain barrier-to-entry protection for compliant producers. The London metropolitan area drives online retail channel velocity for flavored and premium-coated variants.
Low Calorie Rice Cake Market Competitive Landscape
Portfolio diversification dominates the current competitive landscape as manufacturers expand beyond base commodity positioning into functional ingredient convergence. The vendor base separates into three tiers: multinational breakfast conglomerates with cross-merchandising leverage, certified organic specialists with regenerative sourcing credentials, and premium chocolate-coated challengers with direct-to-consumer channel focus. Strategic archetypes include scale-driven mass-market suppliers, certification-anchored organic operators, and innovation-focused specialty entrants. M&A activity and extrusion technology licensing represent the dominant competitive moves reshaping production capabilities.
Within the multinational conglomerate tier, Quaker Oats Company and Mars exemplify scale-driven positioning that leverages existing breakfast aisle dominance for grocery shelf-space capture. Among certified organic specialists, Lundberg Family Farms anchors the regenerative sourcing archetype through Sacramento Valley supply chain control. Element Snacks occupies the premium specialty position with chocolate-coated variants that command placement in fitness-oriented direct-to-consumer channels. These three company types represent the structural fault lines dividing mass-market accessibility from certification-premium positioning and flavor-innovation differentiation.
| Leading Market Players |
|---|
| Quaker Oats Company |
| Lundberg Family Farms |
| Wasa |
| Lotus Foods |
| Nature's Path |
| Kallo Foods |
| Element Snacks |
| Mars |
| Riso Gallo |
| Others |
Value Network & Pricing Analysis
Brown rice futures volatility in the Chicago Board of Trade cascades through three-tier pricing structure across premium, standard, and economy levels, compressing margins for organic sub-category producers while concentrating margin pools among certified operators with captive Sacramento Valley supply.
Pricing Analysis
Input-cost pass-through from drought-cycle brown rice pricing creates asymmetric pressure across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant organic from conventional plain variants, with regenerative sourcing credentials commanding shelf-space premiums. Price differentiation stems from certification grade and volume scale, with cost compression in the standard tier intensifying because of Arkansas-Mississippi Delta supply volatility. Health-conscious consumers in fitness channels show least price sensitivity; price-sensitive households in German and Japanese conventional supermarkets absorb the most volume at lowest per-unit economics.
Supply Chain Analysis
USDA conservation program local-content requirements and EU Green Deal farm subsidies are reshaping sourcing toward certified domestic acreage in the Sacramento Valley and Mississippi Delta. Geographic supply concentration centers on the United States, Thailand, and Vietnam for brown rice inputs. Raw material dependencies rest on certified organic brown rice, high-pressure extrusion equipment, and natural flavor masking compounds. Single-source vulnerability runs through the Arkansas-Mississippi Delta corridor where regenerative certification limits viable suppliers. Distribution runs through direct-to-consumer platforms bundling variety packs with fitness app partnerships, displacing conventional grocery bulk purchasing in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage exists between EFSA additive restriction compliance costs in Europe and USDA conservation program subsidies in the United States, creating margin expansion opportunities for operators with cross-continental sourcing flexibility.
For Market Incumbents: Lock in regenerative sourcing contracts across the Sacramento Valley before transition-period acreage saturates. Cross-merchandise from breakfast aisle dominance into conventional grocery sets to defend against cauliflower-based crispbread substitution threats. Prioritize certification investment in EFSA-compliant additive-free formulations to maintain barrier-to-entry protection against mid-scale challengers. For New Entrants and Emerging Players: Capture direct-to-consumer subscription channel velocity in Germany and Japan where urban consumers prioritize convenience over price per unit. White-space targets include protein-fortified functional variants merging snacking with sports nutrition, and micro-influencer partnerships reducing trial barriers for novel flavor profiles. Go-to-market angle: embed into calorie-tracking app ecosystems as portion-controlled meal-replacement substrates. For Investors and Strategic Acquirers: Asymmetric upside sits with certified organic specialists with Sacramento Valley supply chain control and established EFSA compliance dossiers. Long-term viability over the projection horizon favors operators with backward integration into regenerative rice milling capacity. Acquisition target archetype: mid-scale manufacturers with dedicated gluten-free extrusion lines and existing Health Canada pesticide residue compliance. Signal to watch: front-of-package warning label finalization across multiple jurisdictions tightening sugar and sodium disclosure rules.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Sourcing Certification | USDA conservation programs offset transition costs for Sacramento Valley organic rice growers. |
| Direct-to-Consumer Platform Launch | Germany and Japan urban consumers absorb subscription box velocity for individual-pack configurations. |
| Functional Ingredient Convergence | Protein fortification merges rice cake snacking occasions with sports nutrition category expansion. |
| EFSA Compliance Dossier Investment | Additive-free formulation trials protect margin pools against regulatory barrier-to-entry erosion. |
| High-Pressure Extrusion Technology Licensing | Uniform cell structure preservation enables chocolate and yogurt coating adhesion without breakage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at retailers, supply planners, and extrusion technology specialists alongside secondary validation. Secondary sources included Nielsen retail audit data, customs records for brown rice imports, FDA nutrition labeling filings, and EFSA additive restriction guidance documents. Bottom-up volume triangulation across product type, end user, and distribution channel segments converged with top-down market sizing.
Segment-weighting approach distributed value across plain, flavored, organic, and gluten-free product types, with health-conscious consumers, weight watchers, athletes, and families as end-user dimensions, and online retail, supermarkets, health food stores, and specialty stores as channel configurations. CAGRs derived from historical trajectory analysis adjusted for EFSA regulatory timeline impacts and fitness app normalization penetration curves. Forecast inputs incorporated extrusion technology adoption rates and regenerative certification acreage expansion.
Drought cycle severity in California and Arkansas rice belts, EFSA front-of-package warning label finalization timelines, and cauliflower-based crispbread shelf-space capture velocity are the dominant revision risks. Forecasts reflect documented assumptions on consumer calorie-tracking app integration and organic certification integrity maintenance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Bakery Emulsions Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Packaged Bread Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
North America Bakery Products Market
Bakery Products
Frozen Bakery Market
Bakery Products
Specula Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Waffle Market
Bakery Products
United States Bread Market
Bakery Products
Global Cake Mix Market