
 Low Calorie Cake Market | 2026-2036
Low Calorie Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Cake Market Foresight
Fitness enthusiasts and diabetic consumers are bifurcating the traditional dessert shopper base, pulling volume away from conventional indulgence buyers. Grupo Bimbo S.A.B. de C.V. leverages its Latin American manufacturing footprint to supply low-calorie formats at scale. Mondelez International Inc. competes through R&D intensity in sugar-reduction technologies. Nestlé S.A. anchors European distribution with reformulated classic flavors.
Low calorie cake denotes bakery products engineered with reduced caloric density through alternative sweeteners, modified flour matrices, or fat replacers, typically achieving caloric reductions while maintaining structural integrity and mouthfeel. Chocolate cake variants lead current volume, while stevia-based formulations represent the fastest-growing ingredient segment due to clean-label preferences. Pouch packaging for single-serve slices captures margin pools in convenience channels, whereas whole wheat flour formulations occupy mature positions in European retail.
FDA labeling requirements and EU Nutrition and Health Claims Regulation shape permissible marketing language for reduced-calorie claims, directly influencing product development cycles. EFSA evaluations of novel sweeteners determine ingredient approval timelines across European markets. Stakeholders must monitor evolving WHO sugar reduction guidelines and adapt formulation roadmaps to preempt regulatory tightening in core demand centers.
Market Dynamics
Reformulation technologies centered on stevia and almond flour are compressing traditional ingredient supply chains while forcing legacy bakeries to rebuild R&D capabilities or exit reduced-calorie segments entirely.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:The framework's clarified permissible marketing language for reduced-calorie claims accelerates product development cycles and reduces regulatory uncertainty for reformulated launches.
- Fitness enthusiast demand:This segment pulls volume from conventional indulgence buyers, creating dedicated shelf space for protein-enriched and macro-balanced cake formats in specialty retail channels.
- Stevia extraction advances:Bioprocessing improvements reduce bitter aftertaste profiles, enabling cleaner-label positioning that resonates with millennial and Gen Z purchasing criteria.
Market Restraints
- Almond flour cost volatility:California drought cycles and water allocation disputes create input price instability that compresses margins on gluten-free, low-calorie formulations.
- EFSA novel sweetener timelines:Extended safety evaluation periods delay ingredient approvals across European markets, freezing formulation roadmaps for 18-24 month windows.
- Conventional cake substitution:Home baking resurgence during economic uncertainty pulls trial buyers back to full-calorie scratch alternatives, particularly in mature North American markets.
Strategic Opportunities
- Urban India penetration:Tier-1 metropolitan centers show emerging traction for Western-format reduced-sugar bakery, with modern trade expansion creating first-mover positioning for adapted flavor profiles.
- Single-serve pouch formats:Convenience channel margin pools remain underexploited relative to whole cake offerings, particularly in grab-and-go retail and foodservice.
- WHO sugar reduction guidelines:Anticipatory reformulation to preempt regulatory tightening creates competitive insulation as national health frameworks tighten permissible sugar thresholds.
Industry Challenges
- Texture engineering expertise scarcity:Reformulation chemists capable of balancing caloric reduction with structural integrity and mouthfeel command premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Dual certification complexity:Simultaneous FDA and EFSA compliance for transatlantic product lines extends go-to-market timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Cake Market |
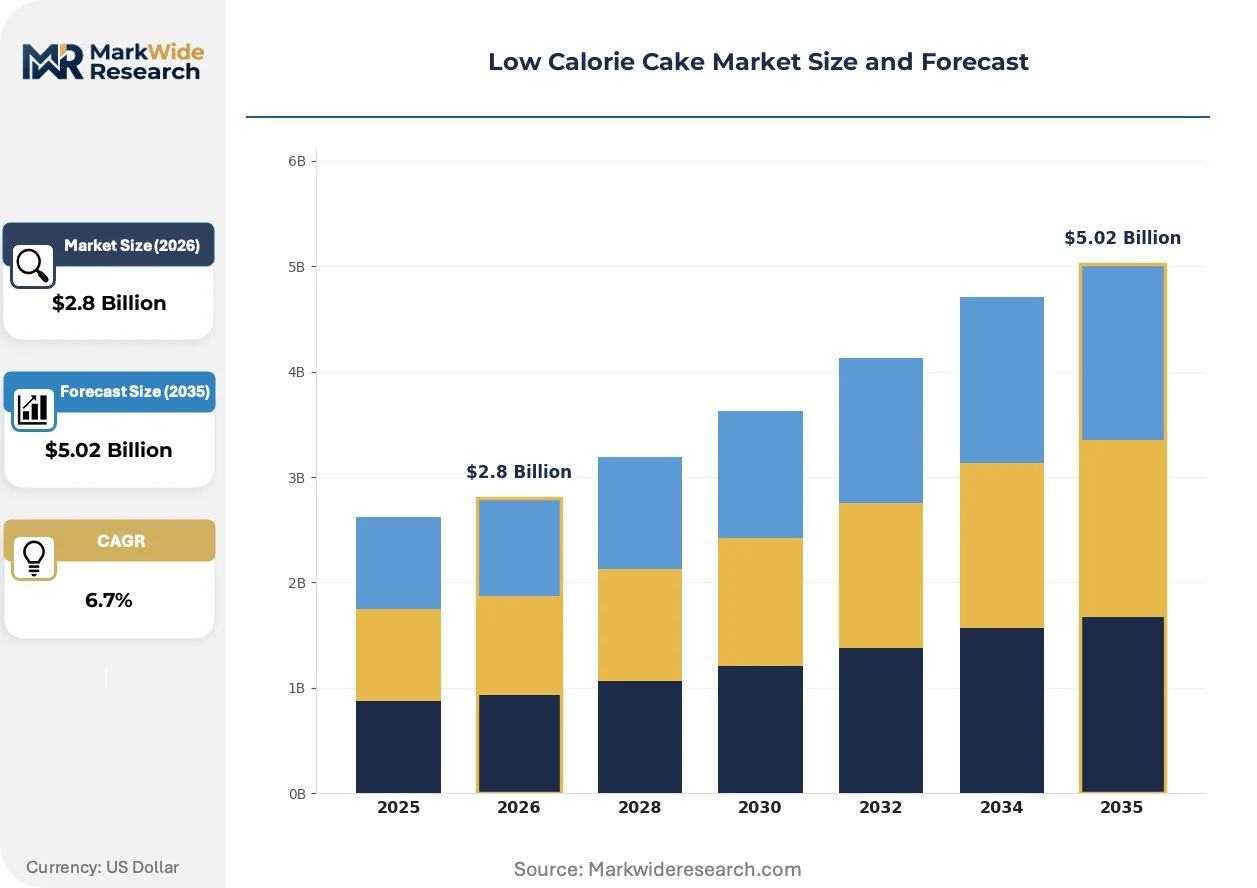
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cake, Vanilla Cake, Red Velvet Cake, Carrot Cake Ingredient: Almond Flour, Coconut Sugar, Stevia, Whole Wheat Flour Packaging Type: Boxes, Pouches, Tubs, Slices End User: Fitness Enthusiasts, Diabetic Consumers, Weight Watchers, Health-Conscious Individuals |
| Companies Covered | Grupo Bimbo S.A.B. de C.V., Danone S.A., Nestlé S.A., Pepperidge Farm Inc., Kraft Heinz Company, Unilever PLC, Mondelez International Inc., Sara Lee Corporation, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Cake Market Shifts & Advancements
Clean-label ingredient sourcing and precision fermentation are converging to redefine what constitutes acceptable sweetness and structure in reduced-calorie bakery, compressing the gap between health claims and sensory performance.
Precision fermentation-derived sweetener platforms is fragmenting incumbent stevia and monk fruit supply relationships by offering batch-to-batch consistency that plantation-extracted alternatives cannot match. Mid-tier bakeries in Germany and the Netherlands are piloting these inputs at commercial scale. The technology is fragmenting traditional botanical supply chains and forcing commodity traders to develop synthetic biology hedging strategies.
FDA guidance on added sugar disclosure is tightening label transparency requirements, compelling manufacturers to reformulate or face competitive disadvantage on shelf appeal. The industrial consequence is accelerated R&D spend on bulking agents that maintain volume without caloric load. Chocolate cake variants in US retail are most affected, with private label brands responding faster than heritage portfolios.
Subscription-based direct-to-consumer cake delivery is displacing conventional grocery trial purchases among diabetic and fitness-focused households. The channel disruption concentrates in coastal US metropolitan markets and London commuter belts, where convenience prioritization overrides price sensitivity. E-commerce fulfillment networks are adapting cold-chain capabilities to accommodate shorter shelf-life reformulated products.
Low Calorie Cake Market Segmentation
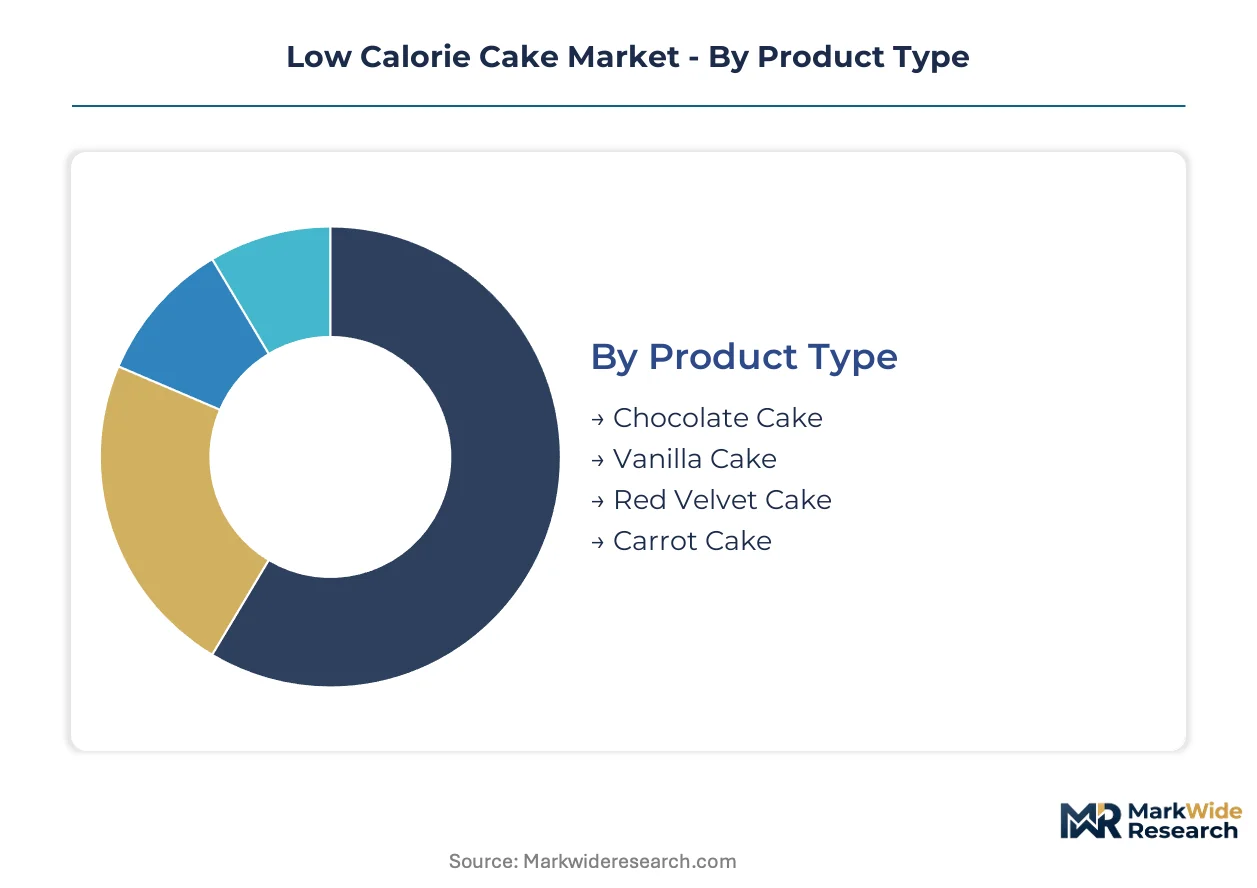
Segmentation in low calorie cake markets reveals how reformulation priorities diverge across consumer motivation clusters. Manufacturers align R&D spend and channel strategy to specific ingredient-platform and packaging-format combinations that command price premiums.
Product Type:
Margin pools concentrate in chocolate variants where cocoa masking properties enable cleaner stevia integration without bitter aftertaste compromise.
- Chocolate Cake:Cocoa solids provide effective masking for alternative sweetener off-notes, enabling higher stevia concentrations without sensory penalty. Demand clusters in US coastal metropolitan markets among diabetic consumers seeking permissible indulgence formats.
- Vanilla Cake:Neutral flavor profiles expose reformulation defects more readily, requiring premium texture engineering to maintain consumer acceptance. European retail channels show strongest volume for vanilla-based formats targeting clean-label preferences.
- Red Velvet Cake:Beet-derived coloring and cream cheese frosting adaptations create formulation complexity that limits mass-market penetration.
- Carrot Cake:Natural vegetable sweetness reduces required alternative sweetener load, appealing to whole-food-oriented weight management segments.
The dominant share belongs to Chocolate Cake, while Carrot Cake is closing the gap fastest among wellness-focused urban consumers.
Ingredient:
Cost tier stratification separates plantation-extracted botanicals from precision fermentation platforms still scaling commercial viability.
- Stevia:Bioprocessing advances have reduced bitter receptor activation, enabling clean-label positioning that resonates with millennial purchasing criteria. German and Dutch mid-tier bakeries are piloting next-generation glycoside profiles at commercial scale.
- Almond Flour:Gluten-free positioning commands shelf price premiums, though California drought cycles introduce margin volatility that compresses profitability on gluten-free formulations.
- Coconut Sugar:Lower glycemic index positioning appeals to diabetic consumer segments without full artificial sweetener avoidance.
- Whole Wheat Flour:Mature positioning in European retail channels where fiber-forward health claims carry established regulatory acceptance.
Stevia holds the dominant formulation share, with precision fermentation alternatives expanding most quickly as batch consistency improves.
Packaging Type:
Convenience channel penetration drives innovation in single-serve formats that capture margin pools unavailable to bulk offerings.
- Pouches:Flexible barrier films extend shelf life for preservative-free reformulations while enabling grab-and-go retail placement. Coastal US metropolitan markets and London commuter belts show strongest adoption where convenience prioritization overrides price sensitivity.
- Slices:Individually wrapped portions reduce trial barriers for first-time reduced-calorie buyers and support subscription-based direct-to-consumer delivery models.
- Boxes:Traditional multi-serve formats retain strength in family-oriented retail channels and club store environments.
- Tubs:Refrigerated formats support fresher positioning in specialty retail and foodservice applications with shorter distribution windows.
Pouches lead convenience channel penetration, while Slices are gaining share fastest through e-commerce subscription fulfillment networks.
End User:
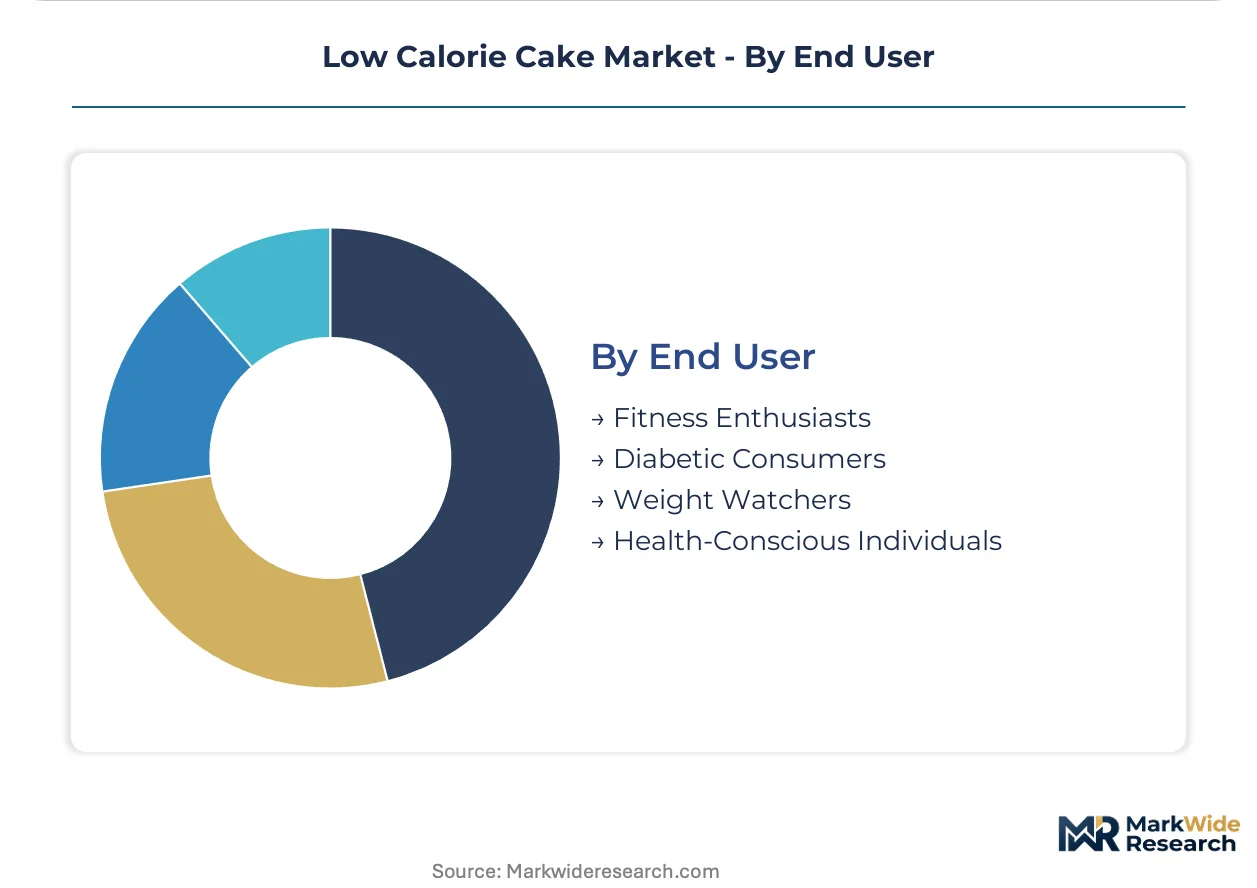
Application-specific need states fragment the traditional dessert shopper base into distinct purchasing behaviors with incompatible product requirements.
- Diabetic Consumers:Glycemic control requirements demand precise carbohydrate disclosure and sugar alcohol tolerance labeling. This segment drives highest willingness-to-pay for clinically validated formulations and pulls volume toward subscription delivery models.
- Fitness Enthusiasts:Macro-tracking requirements create demand for protein-enriched formats with disclosed amino acid profiles. Specialty retail channels dedicate shelf space to these products in urban India tier-1 centers and Western European gym-adjacent retail.
- Weight Watchers:Points-system compatibility requires transparent caloric density disclosure and portion-controlled serving architectures.
- Health-Conscious Individuals:Broad wellness positioning without specific clinical need state supports clean-label marketing and natural ingredient storytelling.
Diabetic Consumers anchor premium pricing tiers, with Fitness Enthusiasts climbing fastest as gym culture penetration deepens in emerging urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican manufacturing clusters export reformulated bakery formats to US coastal metropolitan markets, establishing cross-border supply corridors that anchor North American low-calorie cake distribution.
United States
FDA labeling requirements for added sugar disclosure tighten shelf transparency standards, compelling reformulation investments. Diabetic consumers in coastal metropolitan markets drive subscription-based direct-to-consumer delivery models. Cold-chain fulfillment networks in California and New York Metro adapt to shorter shelf-life preservative-free products.
Germany
EFSA novel sweetener evaluations determine ingredient approval timelines across European markets. Mid-tier bakeries in Bavaria and North Rhine-Westphalia pilot precision fermentation-derived sweetener platforms at commercial scale. Clean-label positioning resonates with millennial purchasing criteria in Berlin-Brandenburg retail channels.
United Kingdom
Fitness enthusiast demand creates dedicated shelf space for protein-enriched formats in London commuter belt specialty retail. EU Nutrition and Health Claims Regulation clarifies permissible marketing language for reduced-calorie claims. Urban India penetration strategies often route through UK-based distribution partnerships for modern trade expansion.
India
FSSAI standards govern permissible food additive usage in reformulated bakery products. Tier-1 metropolitan centers in Maharashtra and Karnataka show emerging traction for Western-format reduced-sugar bakery. Modern trade expansion in Delhi-NCR creates first-mover positioning for adapted flavor profiles targeting health-conscious millennials.
Netherlands
Stevia extraction bioprocessing advances reduce bitter aftertaste profiles through Dutch agrotech innovation. Randstad logistics hubs coordinate EU-wide distribution of clean-label reformulated products. Eindhoven Region food technology clusters accelerate commercialization of next-generation glycoside profiles.
Low Calorie Cake Market Competitive Landscape
Player mix skews toward multinational conglomerates with diversified bakery portfolios. The competitive structure concentrates around three tiers: heritage baked goods manufacturers, diversified nutrition conglomerates, and private-label specialists. Strategic archetypes include scale-driven commodity players, premium health-positioning specialists, and convenience-channel innovators. Dominant competitive moves center on sugar-reduction R&D licensing and geographic manufacturing footprint expansion.
Within the heritage multinational tier, Grupo Bimbo S.A.B. de C.V., Nestlé S.A., and Mondelez International Inc. exemplify divergent strategic positioning. Grupo Bimbo represents Latin American manufacturing scale advantages. Nestlé anchors European distribution infrastructure for reformulated classic flavors. Mondelez occupies the R&D-intensive vector in sugar-reduction technology development. These three entities collectively illustrate how geographic manufacturing footprints, established retail relationships, and formulation capabilities create differentiated competitive insulation in reduced-calorie bakery segments.
| Leading Market Players |
|---|
| Grupo Bimbo S.A.B. de C.V. |
| Danone S.A. |
| Nestlé S.A. |
| Pepperidge Farm Inc. |
| Kraft Heinz Company |
| Unilever PLC |
| Mondelez International Inc. |
| Sara Lee Corporation |
| General Mills Inc. |
| Others |
Supply & Pricing Matrix
FDA and EFSA dual certification requirements gate both supplier qualification and price tier differentiation simultaneously, compressing mid-tier manufacturers between compliance costs and private-label pricing pressure while rewarding heritage portfolios with established regulatory dossiers.
Pricing Analysis
Next-generation precision fermentation sweeteners command 40-60% premiums over plantation-extracted stevia, while legacy sugar alcohol formulations trade at commodity parity. Three-tier pricing structure across premium clean-label, standard reformulated, and economy private-label levels stratifies the market. Cost compression in mid-tier stevia formulations is intensifying because California almond flour volatility forces margin recapture through ingredient substitution. Diabetic consumers in subscription channels show lowest price sensitivity; conventional grocery trial buyers exhibit highest elasticity.
Supply Chain Analysis
California almond flour processing and Dutch stevia extraction bioprocessing create dual chokepoints that constrain global clean-label output expansion. Manufacturing concentrates in Mexico, Germany, and the Netherlands for cross-border efficiency. Formulation depends on stevia glycosides, almond flour, and precision fermentation platforms as core inputs. Single-source vulnerability in California nut processing exposes margins to drought-driven allocation disputes. Distribution runs through modern trade retail, direct-to-consumer cold-chain networks, and foodservice specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation breakthroughs are compressing botanical supply timelines from 18-month plantation cycles to 4-week bioreactor batches, creating a high-growth disruption window for first-movers with synthetic biology partnerships.
For Market Incumbents: Secure exclusive offtake agreements with precision fermentation startups before glycoside platforms achieve commodity scale. Anchor manufacturing capacity in Mexico to leverage USMCA tariff advantages against Asian sweetener imports. Defensive consolidation around stevia extraction expertise protects margin pools as bioprocessing substitutes emerge.
For New Entrants and Emerging Players: Lead with single-serve pouch formats in urban India tier-1 centers where modern trade expansion outpaces incumbent distribution buildout. Target fitness enthusiast segments with protein-enriched macro-balanced formulations that command subscription pricing. Establish direct-to-consumer cold-chain capabilities before heritage brands adapt legacy logistics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation ingredient platforms as batch consistency improves and capex per liter declines. Five-to-ten-year viability favors acquirers of mid-tier bakeries with established EFSA dossiers and underutilized European manufacturing footprints. Monitor WHO sugar reduction guideline revisions as the critical inflection signal for anticipatory reformulation demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Grants batch-to-batch consistency that plantation-extracted stevia cannot match, fragmenting incumbent supply relationships. |
| Single-Serve Pouch Launch | Captures convenience channel margin pools in coastal US metropolitan markets and London commuter belts. |
| EFSA Novel Sweetener Dossier | Accelerates 18-24 month approval timelines and reduces regulatory uncertainty for European reformulated launches. |
| Mexico Manufacturing Expansion | Leverages Latin American production scale for duty-efficient supply into US coastal metropolitan demand centers. |
| Direct-to-Consumer Cold-Chain Buildout | Enables subscription delivery models targeting diabetic households with shorter shelf-life preservative-free products. |
Research Methodology
Operator-level perspectives from R&D directors at multinational bakeries, procurement leads at almond flour processors, regulatory affairs specialists navigating EFSA novel food approvals, and category buyers at modern trade retailers anchored the qualitative base. Secondary validation drew from FDA GRAS notifications, EFSA scientific opinions on steviol glycosides, FSSAI food additive standards, and customs trade data on alternative sweetener imports. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit databases.
Sensitivity analysis tested demand elasticity across diabetic consumer, fitness enthusiast, and weight management segments over the projection horizon. Segmentation dimensions modeled included product type, ingredient platform, packaging format, and end-user motivation cluster. CAGRs derived from historical volume trajectories adjusted for regulatory approval timelines and technology substitution curves. Forecast inputs incorporated stevia extraction yield improvements and precision fermentation scale-up curves.
Forecasts assume regulatory continuity in FDA labeling requirements and EFSA novel sweetener evaluation frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as WHO sugar reduction guidelines and California water allocation disputes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Calorie Muffins Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Dough Whitener Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Banana Bread Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Bakery Fillings Market