
 Global Bakery Product Market | 2026-2036
Global Bakery Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bakery Product Market Analysis
Market Context
Single-serve and grab-and-go bundling is broadening buyer choice across convenience channels and food service counters. Grupo Bimbo leverages its continental manufacturing footprint to dominate North American bread aisles while extending into Latin American snack cakes. Associated British Foods anchors European market positions through its Allied Bakeries division and Tate & Lyle ingredient supply chain. Mondelez International specializes in premium biscuit and cracker portfolios that command shelf space across multiple retail tiers.
Technical Definition and Structural Segments
Bakery products comprise wheat-based or alternative-flour doughs and batters that undergo thermal processing through baking, yielding breads, pastries, cookies, and cakes with moisture contents typically ranging from 15% to 45% and water activity levels managed for shelf stability. These items serve as carbohydrate staples, indulgence occasions, and meal accompaniments across household, retail, and food service channels. Breads retain the largest volume share among product types due to daily consumption frequency, though cookies and pastries capture disproportionate margin pools through premiumization and gifting applications. Supermarkets and convenience stores collectively control the dominant sales channel flow, while online routes expand fastest in urban China and South Korea where cold-chain last-mile capabilities mature.
Regulatory Frame and Outlook
FDA nutrition labeling rules and EU F-Gas Regulation compliance costs reshape North American and European production economics, while China's SAMR enforces GB standards for food additives and labeling that condition market access. WHO sodium-reduction targets and national trans-fat bans in countries including India and Brazil pressure reformulation investments across multinational portfolios. Stakeholders must monitor divergence between regional clean-label thresholds and cost-optimized export formulations.
Market Dynamics
Clean-label reformulation mandates and sodium-reduction targets under FDA guidance and EU regulations are forcing manufacturers to rebuild formulation pipelines while maintaining cost structures, compressing margin recovery timelines across multinational portfolios.
Growth Catalysts
- Par-baked procurement surge:Food service operators across the United States and Germany are expanding cold-chain distribution of pre-baked items to reduce labor costs and shrinkage at store level.
- Urban on-the-go consumption:Commuter corridors in Shanghai, Seoul, and São Paulo are driving single-serve bundling innovation at convenience retail counters.
- F-Gas Regulation compliance:EU industrial bakeries are retrofitting thermal processing lines with lower-global-warming-potential refrigerants, opening equipment upgrade cycles.
Market Restraints
- Wheat price volatility:Black Sea supply disruptions and drought cycles in Australia and Argentina are compressing flour input cost predictability for margin-stretched producers.
- Clean-label cost premium:Natural preservative systems and alternative leavening agents carry 15-40% formulation cost premiums that resist downstream price pass-through in discount retail channels.
- Trans-fat ban cascade:India's FSSAI and Brazil's ANVISA enforcement timelines are forcing accelerated reformulation of legacy shortening-dependent product lines.
Strategic Opportunities
- Indian organized retail penetration:Modern trade expansion in Mumbai, Bangalore, and Delhi NCR is creating shelf-space allocation for branded packaged bread at the expense of loose-format traditional bakeries.
- Precision fermentation leavening:Convergence of biotechnology and thermal processing is enabling bio-derived flavor and texture modulators that bypass chemical additive labeling triggers.
- Direct-to-institution channels:Corporate cafeteria and university food service contracts in Germany and the Netherlands are bypassing traditional retail distribution markups.
Industry Challenges
- Reformulation talent scarcity:Food science expertise in enzyme systems and hydrocolloid stabilization is concentrating at ingredient suppliers, creating recruitment bottlenecks for mid-tier manufacturers.
- Dual certification timelines:Simultaneous EU organic and FDA GRAS clearance processes are extending new product launch windows by 8-14 months.
- Legacy equipment integration:Retrofitting continuous mixing and proofing lines with IoT-enabled moisture control sensors is generating unplanned downtime during commissioning phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bakery Product Market |
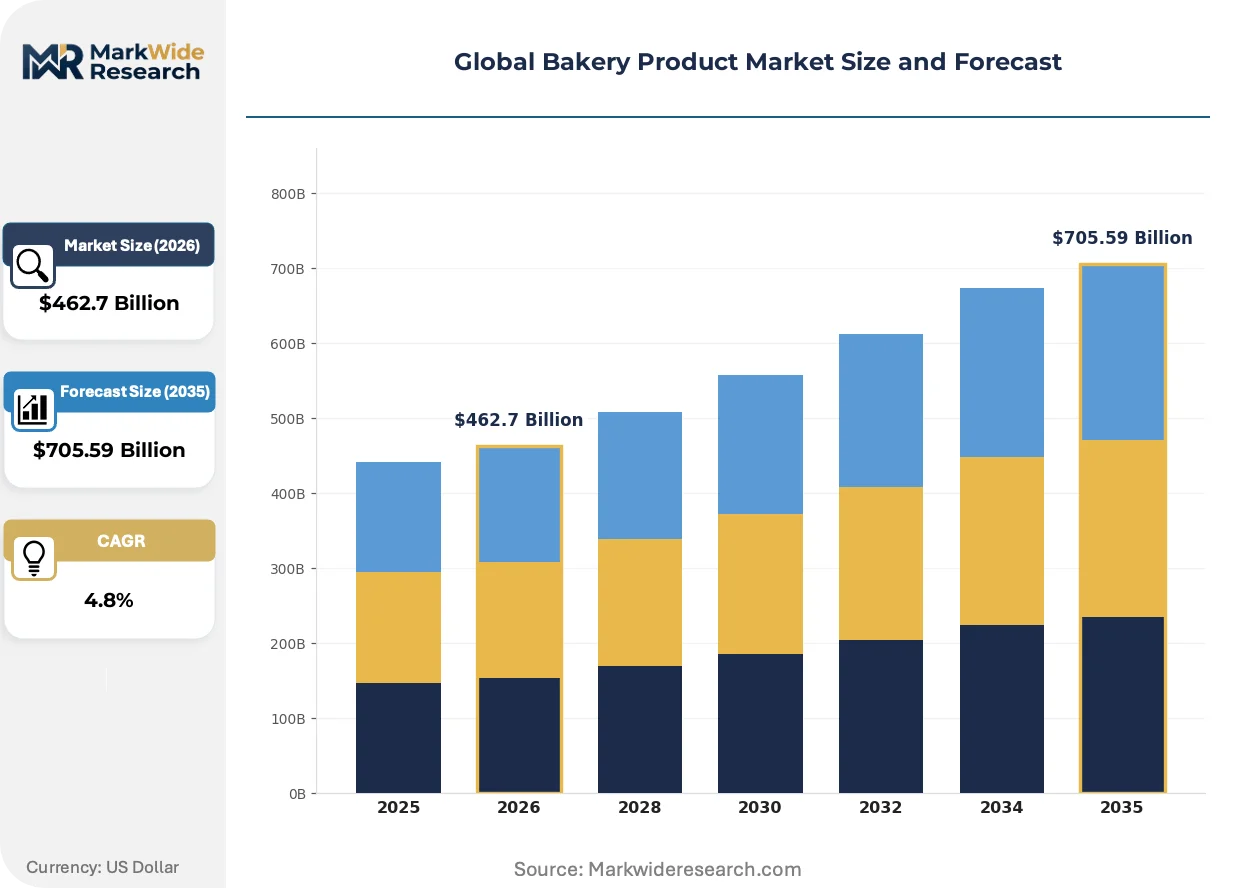
| Market Size in 2026 | $462.7 Billion |
| Market Size in 2035 | $705.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cookies, Cakes Ingredient Type: Flour, Sweeteners, Fats, Leavening Agents End User: Households, Retailers, Food Service, Bakeries Sales Channel: Online, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Yamazaki Baking, Associated British Foods, Grupo Bimbo, Pladis, The Kellogg Company, Mondelez International, Flowers Foods, Aryzta, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bakery Product Market Emerging Trajectories
Thermal processing automation, regulatory chemistry restrictions, and channel fragmentation are compressing traditional production economics while opening white-space positioning for technology-forward manufacturers.
Enzymatic flour modification is rewriting dough rheology standards in high-speed industrial lines. North American and European plant bakeries are adopting fungal amylase and lipase systems at accelerated replacement cycles for chemical oxidizers. This enzyme shift is compressing additive label length while demanding tighter temperature control infrastructure.
China's SAMR enforcement of GB 2760 food additive standards is restricting benzoate and sorbate usage thresholds in yeast-leavened products. Domestic manufacturers are reformulating toward cultured wheat flour and fermented dairy derivatives as shelf-life extenders. Premium biscuit and cake segments in tier-one Chinese cities are absorbing these input cost increases through packaging-driven premium positioning.
Dark-store fulfillment models are fragmenting last-mile distribution for ambient bakery items. Quick-commerce platforms in São Paulo, Mexico City, and Jakarta are bypassing traditional wholesale bakery routes with 15-minute delivery promises. Urban convenience channels in these metropolitan clusters are renegotiating supplier terms to accommodate micro-fulfillment inventory turns.
Global Bakery Product Market Segmentation
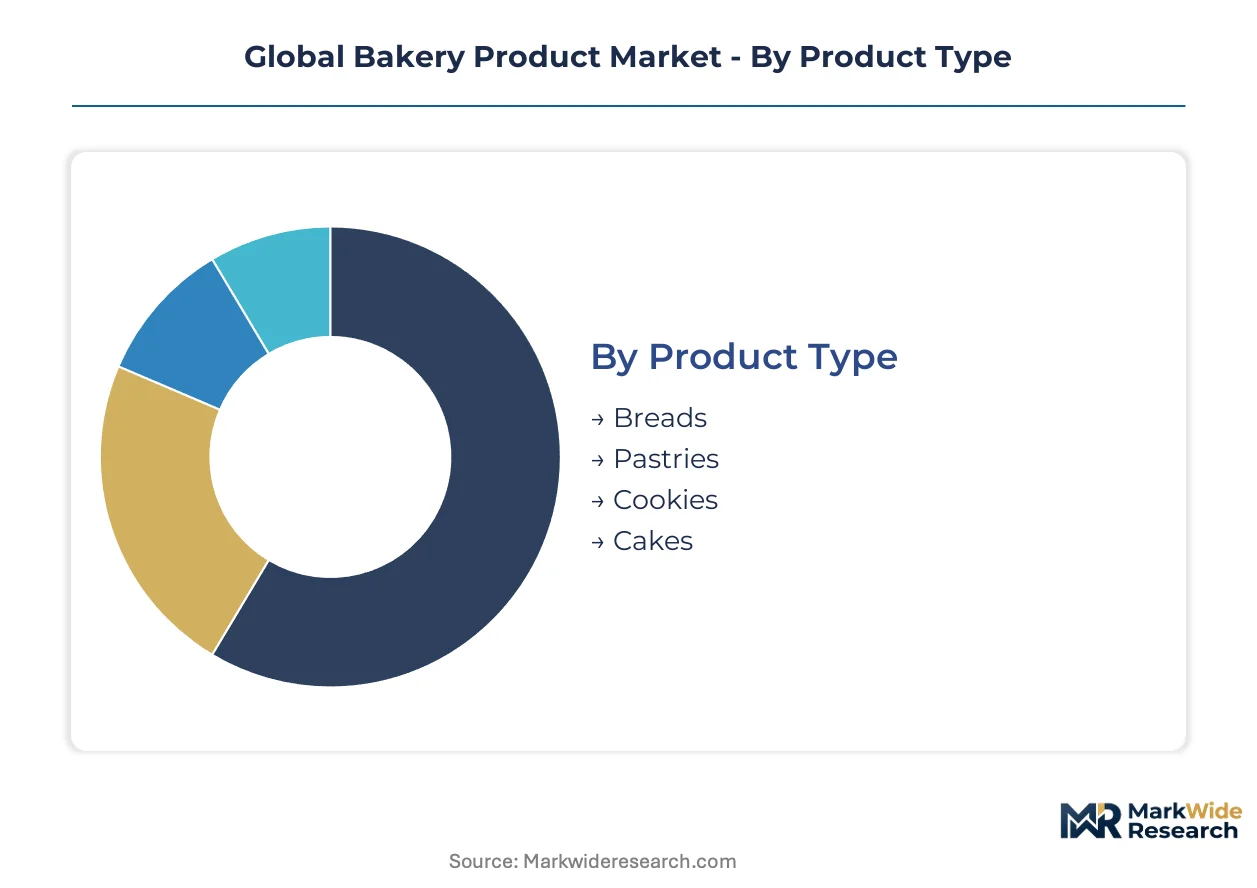
Bakery product segmentation reveals divergent capital requirements across thermal processing formats, ingredient handling systems, and cold-chain distribution infrastructure. Each dimension carries distinct equipment intensity thresholds that reshape manufacturer entry barriers and margin architecture.
Product Type:
Continuous mixing and high-tunnel oven configurations demand the steepest upfront investment, with artisan-scale proofing rooms representing the lowest capital barrier to entry.
- Breads:High-volume continuous mixers and tunnel ovens require multimillion-dollar thermal processing lines optimized for 15,000+ units per hour. Daily consumption frequency in Germany, the United States, and China sustains capacity utilization rates that amortize equipment costs across massive throughput bases.
- Pastries:Lamination sheeters and precision temperature-controlled proofing chambers enable layered dough structures with butter or shortening inclusions. Premium positioning in French and Japanese retail channels absorbs higher per-unit equipment depreciation through gift-box and café-applications pricing.
- Cookies:Rotary molders and wire-cut depositors handle stiff doughs with precision weight control for mass-market SKUs.
- Cakes:Aerated batter depositors and spiral cooling towers manage delicate foam structures post-thermal processing.
Most installed capacity flows through Breads. Expansion is steepest in Pastries.
Ingredient Type:
Handling infrastructure scales from pneumatic flour silos and automated dosing systems down to manual additive weighing stations.
- Flour:Pneumatic bulk handling and tempering systems dominate wheat-protein management in industrial bakeries across the United States and Germany. Black Sea supply disruptions and drought cycles in Australia and Argentina are compressing input cost predictability for margin-stretched producers.
- Sweeteners:Liquid sucrose and high-fructose corn syrup require heated storage tanks and viscosity-controlled pumping infrastructure. Reformulation toward reduced-sugar profiles under FDA guidance and EU regulations is forcing enzyme-based sweetness enhancement investments that bypass clean-label thresholds.
- Fats:Shortening and butter handling demands temperature-controlled storage and metering systems.
- Leavening Agents:Chemical and biological raising systems require precise humidity-controlled activation timing.
Volume concentration sits with Flour. Margin expansion is climbing the fastest in Sweeteners.
End User:
Contract specifications range from institutional procurement compliance systems to household impulse-purchase packaging formats.
- Food Service:Par-baked and frozen-dough supply contracts demand HACCP-certified production lines with lot-traceability documentation. Cold-chain distribution partnerships with Aramark, Compass Group, and Sodexo in Germany and the Netherlands are bypassing traditional retail markups through direct-to-institution channels.
- Retailers:Private-label manufacturing requires rapid changeover capabilities and shelf-life extension technologies. Walmart and Carrefour volume commitments in the United States and France justify dedicated production lines with customized packaging formats.
- Households:Packaged goods consumption drives supermarket and convenience store procurement.
- Bakeries:Ingredient supply and semi-finished goods support artisan and in-store production.
Contract value concentrates in Food Service. Share gains are accelerating in Retailers.
Sales Channel:
Last-mile infrastructure spans dark-store micro-fulfillment centers to traditional wholesale bakery routes.
- Supermarkets:Slotting fees and promotional calendar coordination require dedicated account management infrastructure. Grupo Bimbo and Associated British Foods maintain continental distribution networks that secure permanent shelf positioning across North American and European retail tiers.
- Online:Quick-commerce platforms in São Paulo, Mexico City, and Jakarta are fragmenting ambient bakery distribution with 15-minute delivery promises. Urban convenience channels in these metropolitan clusters are renegotiating supplier terms to accommodate micro-fulfillment inventory turns.
- Convenience Stores:Single-serve bundling and grab-and-go formats dominate commuter corridor placement.
- Specialty Shops:Premium positioning and gifting applications support artisan and regional brand distribution.
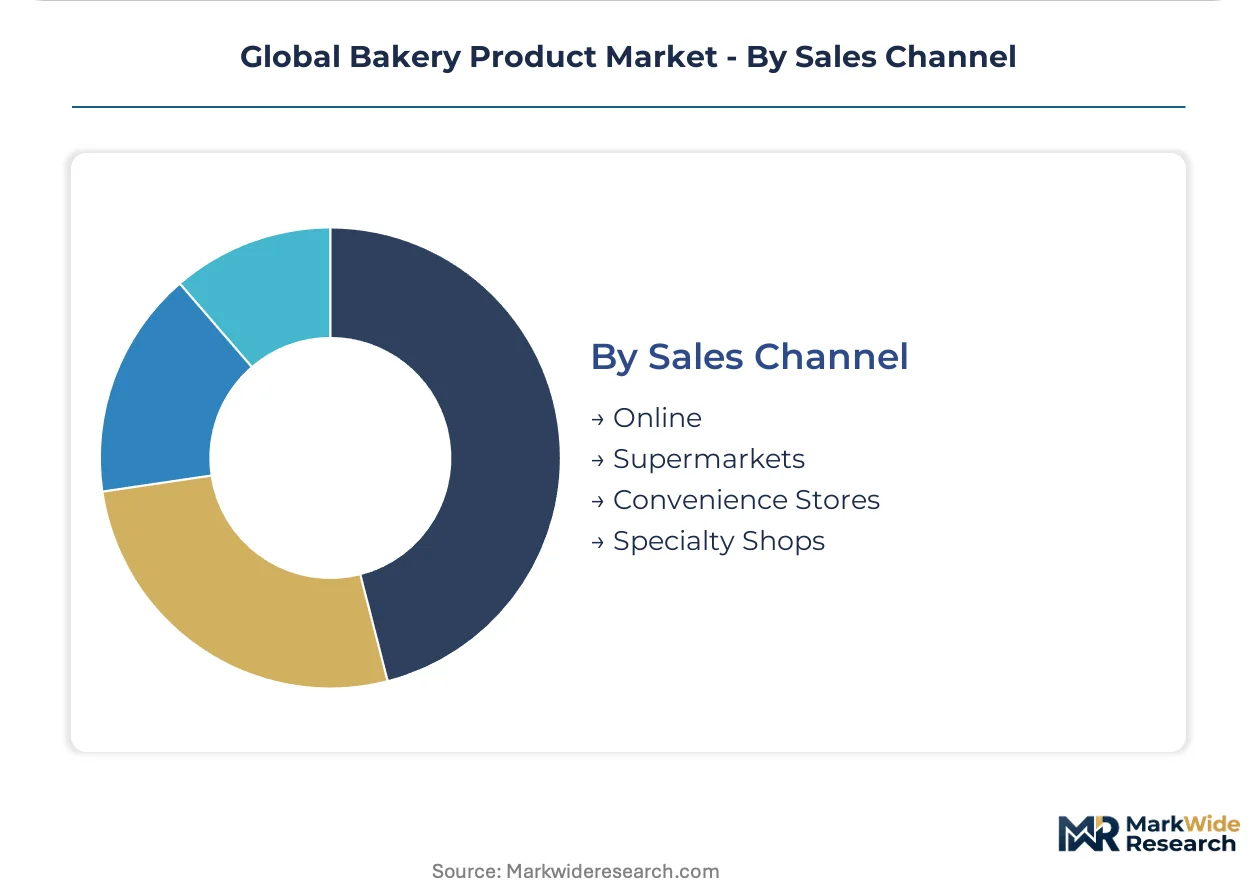
Foot traffic flows predominantly through Supermarkets. Channel expansion is gaining share fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale baking emerged in Germany and the United States during the late nineteenth century, with mechanized bread production spreading through urban centers and establishing the capital-intensive plant bakery model that now dominates developed markets. This historical foundation shapes contemporary competitive dynamics across major producing nations.
United States
Convenience retail and food service procurement sustain volume throughput across high-speed tunnel oven installations. FDA nutrition labeling rules and sodium-reduction guidance are forcing reformulation of legacy white bread portfolios. Chicago and Atlanta metropolitan clusters host automated frozen dough facilities supplying par-baked products to institutional channels.
Germany
Discounter retail consolidation and artisan heritage coexist, creating bifurcated demand across price tiers. EU F-Gas Regulation compliance costs are accelerating thermal processing line retrofits with lower-global-warming-potential refrigerants. Munich and Hamburg industrial zones concentrate automated pretzel and roll production for export into neighboring markets.
China
Urban on-the-go consumption in Shanghai and Beijing is driving single-serve bundling innovation at convenience retail counters. SAMR enforcement of GB 2760 food additive standards is restricting benzoate and sorbate usage thresholds in yeast-leavened products. Yangtze River Delta manufacturing clusters are scaling enzymatic flour modification systems for high-speed industrial lines.
India
Modern trade expansion in Mumbai, Bangalore, and Delhi NCR is creating shelf-space allocation for branded packaged bread at the expense of loose-format traditional bakeries. FSSAI trans-fat enforcement timelines are forcing accelerated reformulation of legacy shortening-dependent product lines. Maharashtra and Gujarat host the largest automated bread plants serving organized retail channels.
Brazil
Quick-commerce platforms in São Paulo are fragmenting ambient bakery distribution with 15-minute delivery promises. ANVISA trans-fat regulations are pressuring reformulation investments across multinational portfolios. São Paulo state concentrates industrial capacity for panettone and sweet bread exports across Latin American markets.
Global Bakery Product Market Vendor Landscape
The competitive structure tilts toward continental-scale diversified food conglomerates with integrated ingredient supply chains. Plant bakeries requiring multimillion-dollar thermal processing lines create steep entry barriers that concentrate volume share among capital-rich operators. Three archetypes dominate: diversified multinational food groups, regional bakery specialists with frozen-distribution expertise, and private-label manufacturers serving retail consolidation. Competitive moves center on geographic expansion through acquisition and portfolio diversification into gluten-free and clean-label segments.
Among diversified multinational food groups, Associated British Foods and Grupo Bimbo occupy positions exemplifying continental manufacturing footprint strategies. Mondelez International represents the premium biscuit and cracker specialization archetype. These three entities anchor the competitive landscape across North American and European retail tiers.
| Leading Market Players |
|---|
| Yamazaki Baking |
| Associated British Foods |
| Grupo Bimbo |
| Pladis |
| The Kellogg Company |
| Mondelez International |
| Flowers Foods |
| Aryzta |
| General Mills |
| Others |
Supply Flow & Price Mechanics
Chicago Board of Trade wheat futures volatility cascades through flour milling contracts into three distinct bakery pricing tiers, compressing margin buffers for industrial producers while amplifying procurement leverage for continental-scale buyers with captive milling operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments bakery portfolios by ingredient certification grade and volume scale. Premium tiers absorb EU organic and FDA GRAS compliance costs through packaging-driven positioning, while economy tiers face intense price sensitivity from discount retail channels in Germany and the United States. Pricing pressure stems from clean-label reformulation premiums that resist downstream pass-through. Food service operators exhibit lowest price sensitivity due to labor-cost substitution value, while household retail segments demand aggressive promotional pricing.
Supply Chain Analysis
Dual-sourcing requirements for wheat flour now dominate procurement protocols at multinational manufacturers, mandating qualification of milling partners across at least two origin zones. Supply concentration sits with the United States, Germany, and China as primary milling hubs. Raw material dependencies center on Black Sea wheat, Australian durum, and Argentine milling-grade soft wheat. Single-source vulnerability from Black Sea supply disruptions threatens input cost predictability. Distribution runs through continental-scale plant bakeries with frozen-dough cold-chain extensions into food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bakery Product Market functions as a stable compounder anchored by daily consumption frequency that sustains volume throughput across economic cycles.
For Market Incumbents: Lock in enzyme system partnerships with Tate & Lyle and other ingredient suppliers to secure reformulation capacity ahead of tightening EU and FDA additive restrictions. Expand captive flour milling in the United States and Germany to hedge wheat price volatility exposure. Prioritize direct-to-institution channel control in Germany and the Netherlands where Aramark and Compass Group contracts bypass retail markups. For New Entrants and Emerging Players: Launch via quick-commerce dark-store partnerships in São Paulo, Mexico City, and Jakarta where 15-minute delivery promises fragment traditional wholesale routes. Target India's modern trade expansion in Mumbai and Delhi NCR where branded packaged bread displaces loose-format traditional bakeries. Pursue precision fermentation leavening as a clean-label positioning angle that bypasses chemical additive labeling triggers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional bakery specialists possessing frozen-distribution expertise and established food service contracts. Long-term viability hinges on reformulation agility across sodium-reduction and trans-fat ban compliance timelines. Monitor FSSAI and ANVISA enforcement acceleration in India and Brazil as inflection indicators for portfolio-wide reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Flour Modification Scale-Up | Fungal amylase systems replace chemical oxidizers to compress additive labels while tightening temperature control infrastructure. |
| Cold-Chain Par-Baked Expansion | Frozen-dough facilities in Chicago and Atlanta supply institutional channels with HACCP-certified production and lot-traceability documentation. |
| Quick-Commerce Distribution Partnership | Dark-store fulfillment models in São Paulo and Jakarta bypass traditional wholesale routes with micro-fulfillment inventory turns. |
| Precision Fermentation Leavening Investment | Bio-derived flavor modulators bypass chemical additive labeling triggers under China's SAMR GB 2760 enforcement. |
| Dual-Certification Product Development | Simultaneous EU organic and FDA GRAS clearance extends launch windows but secures shelf access across North American and European retail tiers. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant bakery operations directors, retail category buyers at Walmart and Carrefour, food service procurement leads at Aramark and Compass Group, and enzyme systems technical directors at ingredient suppliers. Secondary validation draws from FDA GRAS filings, EU F-Gas Regulation compliance disclosures, SAMR GB standards documentation, and customs trade data on wheat flour movements. Bottom-up capacity modeling and top-down consumption surveys triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, ingredient handling infrastructure, end-user contract specifications, and sales channel format. CAGRs derive from installed capacity utilization trends and per-capita consumption elasticity assumptions. Industry-specific inputs incorporate wheat futures price correlation coefficients and cold-chain logistics cost indices.
Several conditions sit outside the modeled scope, including extreme weather events disrupting Australian and Argentine wheat harvests, sudden EU F-Gas Regulation enforcement acceleration, and geopolitical trade restrictions on Black Sea grain flows. Deviation in regulatory enforcement timelines or commodity price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pizza Crust Market
Bakery Products
Flour Mixes Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Toasted Flour Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Cookies Market
Bakery Products
Baking Mats Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Specula Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Sourdough Market
Bakery Products
Specialty Bakery Market
Bakery Products
Frozen Bakery Additives Market