
 Bakery Conditioner Market | 2026-2036
Bakery Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Conditioner Market Outlook
The EU Green Deal is repositioning bakery conditioner procurement across European industrial bakeries, forcing reformulation away from synthetic additives toward enzyme-based and plant-derived alternatives. Corbion leverages its biotechnology portfolio to supply clean-label emulsifiers that meet tightening carbon-footprint thresholds. Puratos Group anchors European distribution through its sourdough and conditioner innovation centers in Belgium and Italy. Lesaffre Group competes on fermentation-derived solutions that reduce chemical additive dependency in high-volume bread production.
Bakery conditioners comprise functional ingredient blends—typically incorporating emulsifiers such as DATEM or SSL, hydrolytic enzymes like amylase and xylanase, redox agents, and hydrocolloid stabilizers—that modify dough rheology, gas retention, and crumb structure during mechanical processing and thermal baking. These formulations serve industrial bakeries seeking to standardize product quality across variable flour batches and automated production lines. Enzyme-based conditioners command expanding share as bakers replace bromate and azodicarbonamide in response to retailer clean-label mandates. Dough conditioners sustain premium positioning where artisan and par-baked segments require extended freeze-thaw stability. Bread applications dominate volume consumption, though pastries represent the fastest-growing application as laminated dough complexity drives specialized conditioner demand.
EMA food additive evaluations, EU Green Deal sustainability benchmarks, and REACH chemical registration requirements collectively determine which conditioner chemistries achieve market access across Europe. EFSA positive opinions on novel enzymes directly enable product launches, while REACH compliance costs filter out smaller importers of Asian-manufactured emulsifiers. Stakeholders must monitor pending EU enzyme regulation revisions and traceability mandates that will reshape supplier qualification criteria before the forecast horizon closes.
Market Dynamics
The EU Green Deal is forcing industrial bakeries across Europe to abandon synthetic emulsifiers and reformulate around enzyme-based and plant-derived conditioner systems, compressing formulation timelines and supplier qualification windows.
Growth Catalysts
- Clean-label mandates from major retailers:Supermarket chains in Germany and France now require bromate-free and azodicarbonamide-free bread formulations, accelerating enzyme conditioner adoption in industrial baking facilities.
- REACH compliance barriers for Asian imports:Registration costs and chemical safety documentation requirements are filtering out low-cost emulsifier suppliers, creating protected market space for EU-qualified conditioner manufacturers.
- Artisan bread segment expansion:Premium bakeries in Italy and Belgium are integrating specialized conditioners for extended freeze-thaw stability in par-baked products, opening high-margin application channels.
Market Restraints
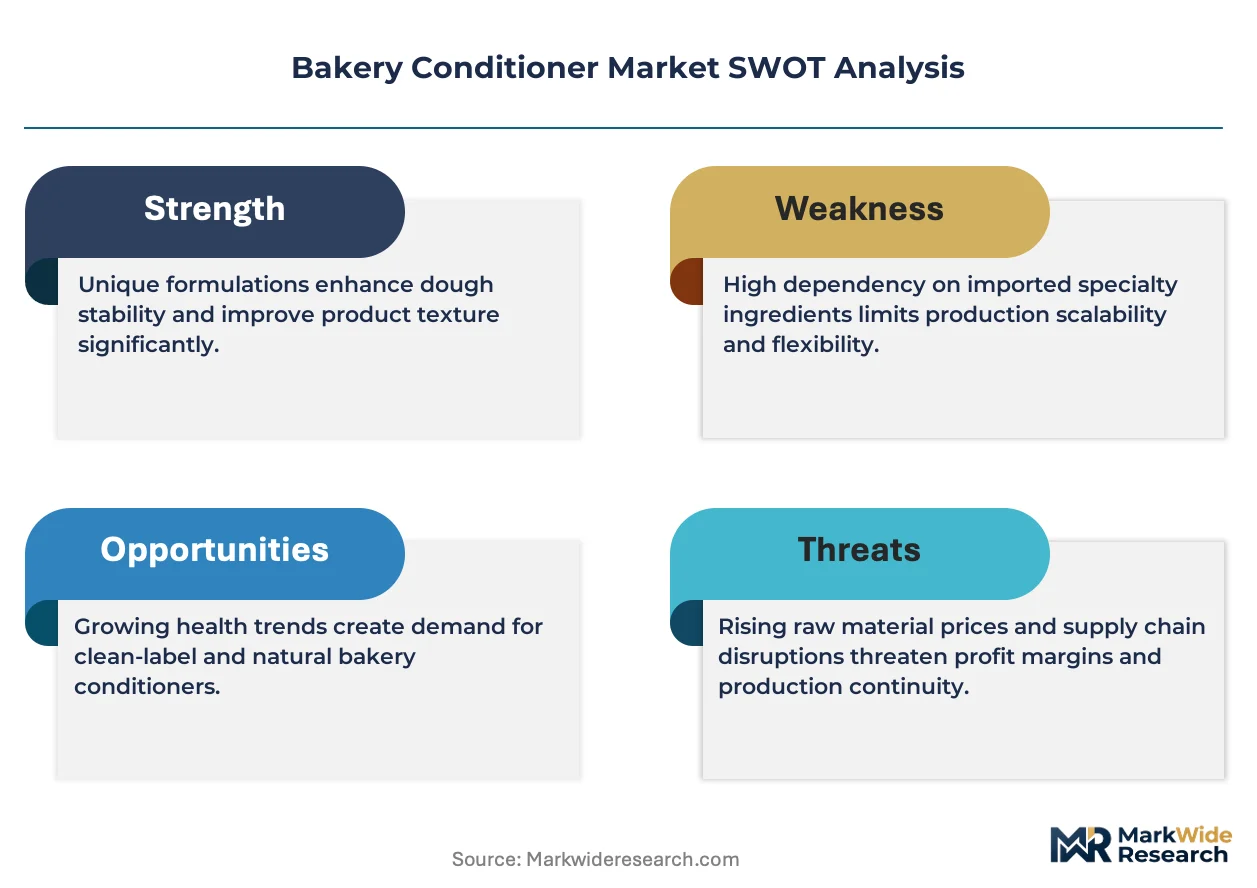
- Wheat and palm oil price volatility:Input cost swings for hydrocolloid stabilizers and plant-derived emulsifiers compress margins for mid-size conditioner blenders without captive raw material sourcing.
- EFSA enzyme approval timelines:Novel enzyme submissions face 18-24 month evaluation periods, delaying product launches and freezing R&D pipelines for biotechnology-dependent suppliers.
- Substitution by in-house fermentation:Large industrial bakeries in France are developing proprietary sourdough cultures that reduce external conditioner dependency for dough rheology control.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania industrial baking sectors remain below Western European conditioner penetration rates, presenting volume expansion potential for standardized enzyme blends.
- EU CSRD sustainability reporting:Mandatory carbon footprint disclosure is creating demand for conditioners with verified supply chain emissions data, enabling premium positioning for transparent suppliers.
- Convergence of enzyme engineering and precision fermentation:Biotechnology platforms that combine CRISPR-optimized amylases with microbial production systems can deliver tailored functionality for specific flour protein profiles.
Industry Challenges
- Specialized enzymology talent scarcity:Industrial bakeries struggle to recruit formulation scientists capable of optimizing multi-enzyme conditioner systems across variable wheat harvests.
- Legacy equipment compatibility:Automated production lines designed for chemical-based conditioners require costly retrofitting to handle temperature-sensitive enzyme formulations without activity loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Conditioner Market |
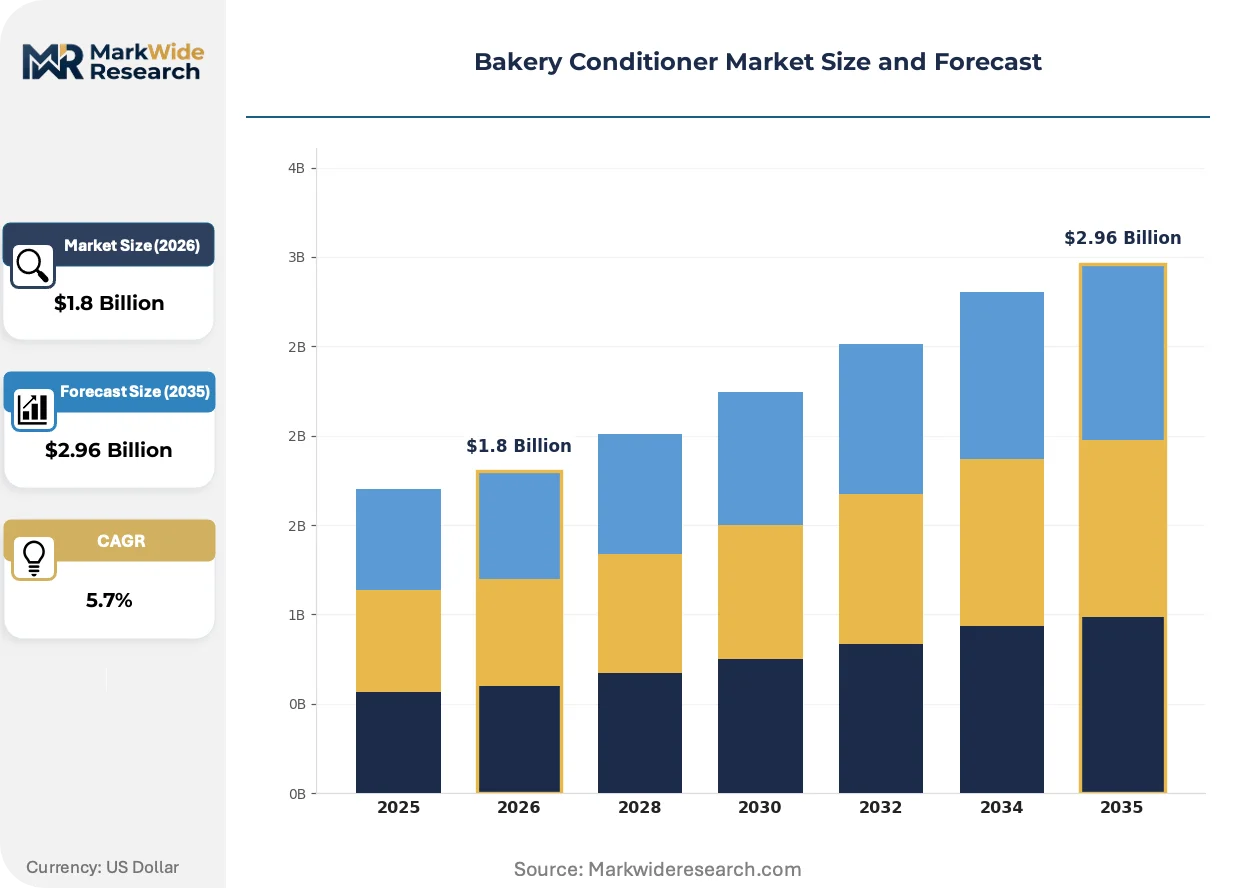
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Enzymes, Dough Conditioners, Stabilizers Application: Bread, Pastries, Cakes, Cookies End User: Bakeries, Restaurants, Retail Stores, Home Bakers Distribution Channel: Online, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Corbion, Puratos Group, Lesaffre Group, Archer Daniels Midland Company, Lallemand Inc., DSM-Firmenich, Kerry Group, AB Enzymes GmbH, Watson Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Conditioner Market Strategic Shifts
Biotechnology-enabled formulation is absorbing capital and technical attention across the European bakery conditioner supply base, compressing development cycles for clean-label alternatives while regulatory pressure accelerates displacement of legacy chemistries.
Transglutaminase and lipase enzyme systems are absorbing market share from DATEM and SSL emulsifiers in laminated dough applications. Industrial pastry manufacturers in Belgium and the Netherlands are adopting these biocatalysts at pace to meet retailer clean-label requirements. The technology is absorbing reformulation investment that previously flowed toward chemical emulsifier optimization, restructuring supplier R&D priorities.
The EU Green Deal's Farm to Fork Strategy is tightening carbon footprint thresholds for food ingredient production. Industrial bakeries must now document Scope 3 emissions from conditioner supply chains, forcing procurement teams to disqualify suppliers without verified lifecycle data. High-volume bread producers in Germany are responding by consolidating supplier bases around biotechnology firms with transparent fermentation-based production.
Direct technical service relationships are displacing traditional distributor intermediaries in conditioner procurement. Large industrial bakeries in France and Italy now expect on-site enzymologists and formulation support from suppliers, unbundling product sales from application expertise. This pattern concentrates in the artisan-par-baked segment where dough complexity demands customized conditioner blends rather than standard catalog offerings.
Bakery Conditioner Market Segmentation
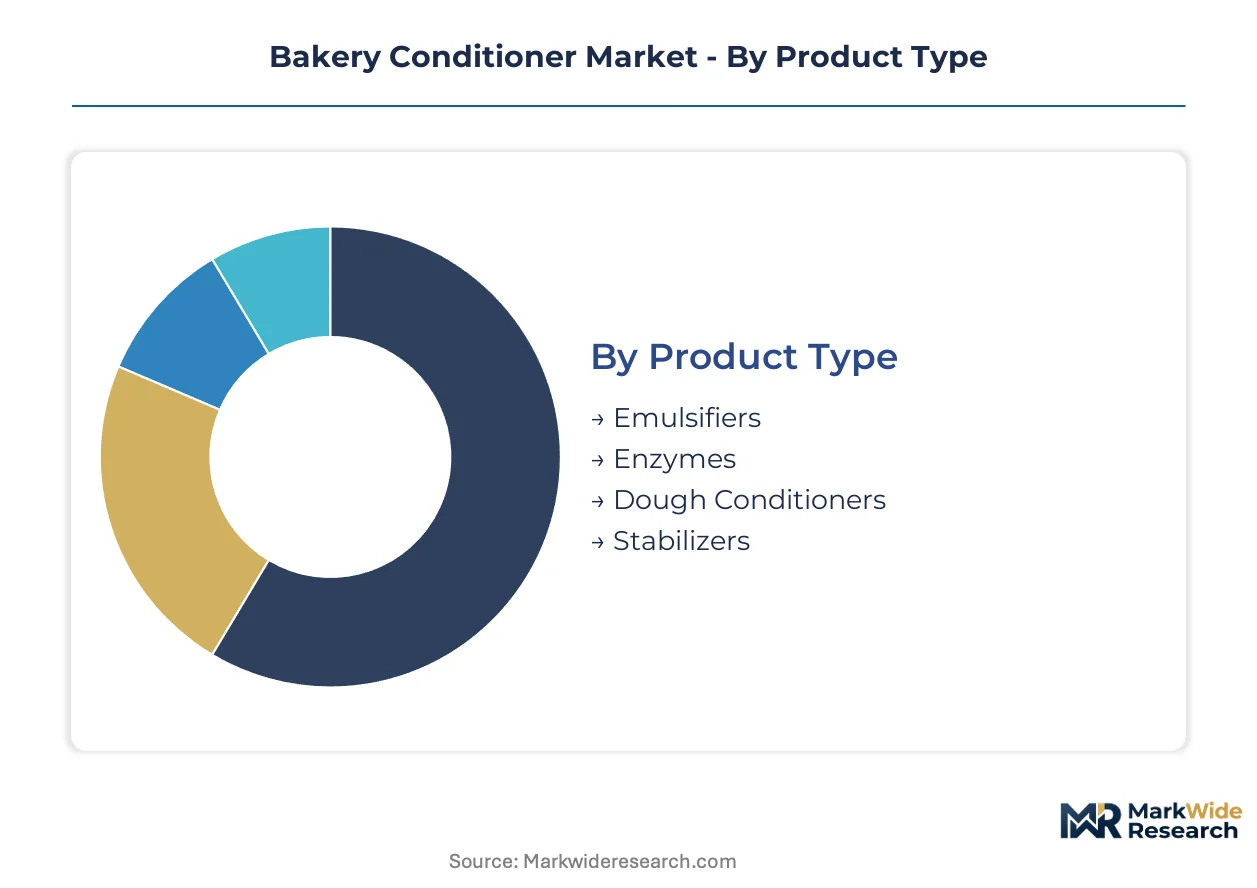
Bakery conditioner procurement patterns diverge sharply across product chemistry, application complexity, and customer scale. Industrial buyers prioritize enzyme systems for clean-label compliance while artisan segments drive demand for specialized stabilizers in frozen dough applications.
Product Type:
Supply concentration in European biotechnology clusters favors enzyme manufacturers with captive fermentation capacity over commodity emulsifier importers facing REACH registration barriers.
- Emulsifiers:DATEM and SSL formulations still dominate high-volume bread production in Germany and France, though EFSA evaluations of novel alternatives are compressing reformulation timelines for industrial bakeries.
- Enzymes:Amylase and xylanase systems are displacing chemical conditioners in clean-label mandates from German retail chains; biotechnology suppliers with transparent carbon footprints capture premium positioning under EU CSRD requirements.
- Dough Conditioners:Redox agent blends serve automated production lines requiring standardized dough rheology across variable wheat harvests.
- Stabilizers:Hydrocolloid systems anchor freeze-thaw stability for par-baked products in Italian artisan channels.
Today's leader: Emulsifiers. Tomorrow's challenger: Enzymes.
Application:
Application-driven demand splits between commodity bread volumes and technical complexity in laminated doughs, with margin structures favoring specialized pastry conditioners.
- Bread:Industrial facilities in Germany consume standardized enzyme blends for high-output loaves; clean-label mandates from Aldi and Lidl are accelerating bromate replacement programs.
- Pastries:Laminated dough complexity in Belgian and Dutch industrial bakeries drives specialized lipase and transglutaminase adoption, with technical service relationships displacing traditional distributor channels.
- Cakes:Aeration stability requirements favor emulsifier-stabilizer combinations in automated layer cake production.
- Cookies:Spread control and texture standardization dominate conditioner specification in high-speed rotary molding operations.
Bread commands volume. Pastries capture margin expansion.
End User:
Customer scale determines procurement modality, with industrial bakeries consolidating supplier bases while fragmented home baker segments sustain distributor intermediaries.
- Bakeries:Industrial facilities in France and Italy demand on-site enzymologist support; artisan operations in Belgium prioritize freeze-thaw stability for par-baked distribution.
- Restaurants:Foodservice operators in Germany source conditioners through wholesale channels for in-house bread programs.
- Retail Stores:Supermarket in-store bakeries in France adopt clean-label conditioners to meet corporate sustainability commitments.
- Home Bakers:Small-format enzyme blends reach this segment through online channels and specialty ingredient retailers.
Industrial bakeries anchor revenue. Foodservice channels offer expansion velocity.
Distribution Channel:
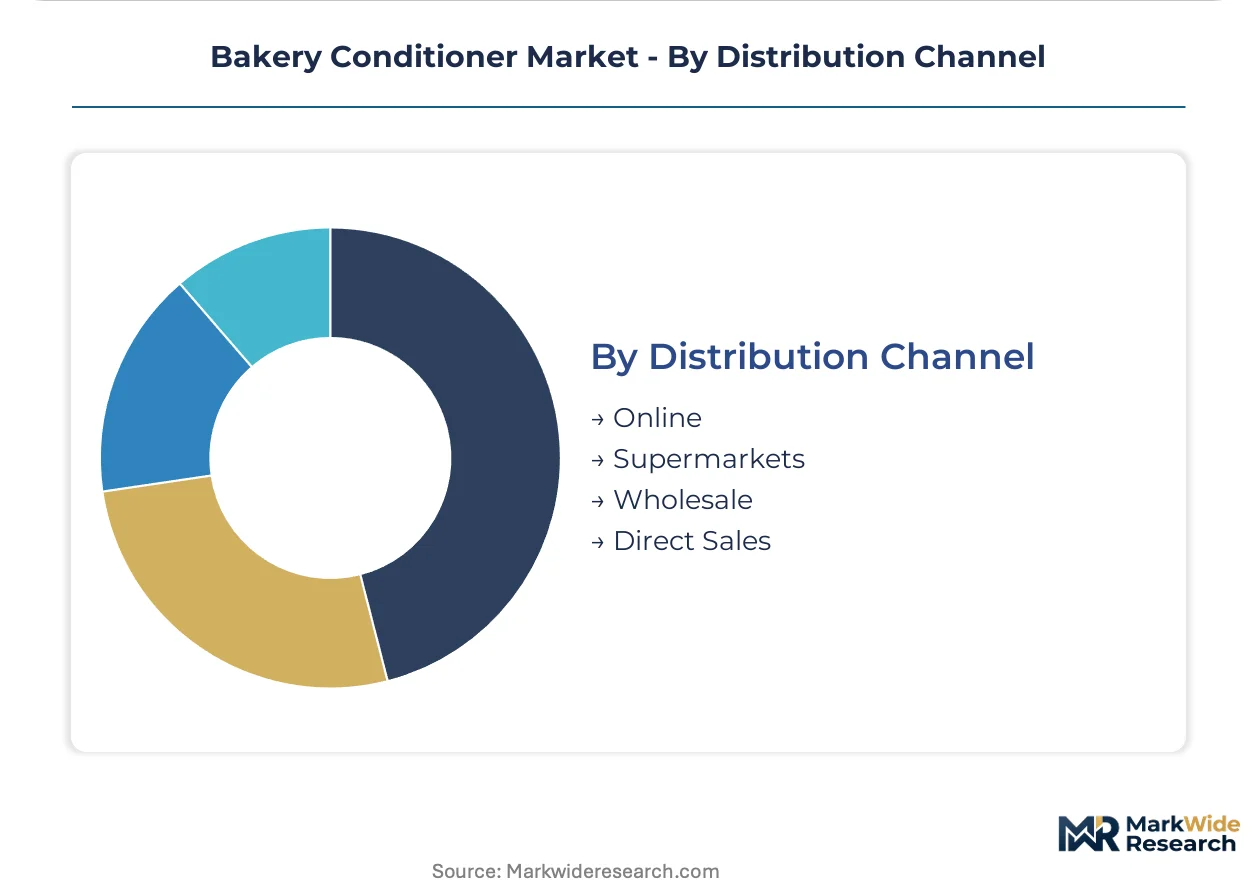
Channel structure reflects technical complexity, with direct sales penetrating formulation-intensive accounts while standardized products flow through wholesale intermediaries.
- Online:Small-scale enzyme and stabilizer formats serve home bakers and micro-artisans through specialized ingredient platforms.
- Supermarkets:Mass-market conditioner blends reach retail store bakeries through centralized procurement functions.
- Wholesale:Broad-line distributors serve mid-size independent bakeries across France and Italy with catalog-based emulsifier and enzyme offerings.
- Direct Sales:Large industrial accounts in Germany negotiate technical service contracts with biotechnology suppliers, unbundling product from application expertise.
Direct sales secure strategic accounts. Wholesale maintains volume penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery conditioner production originated in European milling centers during the post-war automation wave, with German and Dutch chemical firms pioneering emulsifier synthesis for standardized bread manufacturing. This heritage established quality benchmarks and regulatory frameworks that now govern global trade flows.
Germany
Industrial bakeries in North Rhine-Westphalia and Bavaria consume enzyme-based conditioners at scale to meet Aldi and Lidl clean-label mandates. REACH compliance requirements filter Asian emulsifier imports, protecting domestic biotechnology suppliers. The Frankfurt-Rhine-Main corridor hosts formulation R&D clusters serving automated high-output bread lines.
France
Artisan par-baked segments in Île-de-France and Auvergne-Rhône-Alpes drive demand for freeze-thaw stabilizers in premium distribution channels. ANSM food additive evaluations align with EFSA timelines for novel enzyme approvals. Lesaffre Group anchors fermentation-derived solutions from its Lille metropolitan base.
Italy
Lombardy and Emilia-Romagna industrial bakeries specialize in laminated dough conditioners for frozen pastry exports. EU Green Deal carbon footprint thresholds reshape procurement toward transparent supply chains. Milan-based technical service teams displace traditional distributors in direct supplier relationships.
Belgium
Puratos Group operates innovation centers in Brussels and Ghent, supplying sourdough-integrated conditioners across Benelux industrial channels. EMA food additive evaluations determine market access for imported enzyme systems. The Flanders region concentrates biotechnology fermentation capacity for plant-derived emulsifier production.
Poland
Warsaw and Łódź industrial baking sectors remain below Western European conditioner penetration rates, presenting volume expansion potential. National food safety authority alignments with EU regulatory frameworks accelerate market formalization. Poznań distribution hubs channel standardized enzyme blends into underpenetrated Central European markets.
Bakery Conditioner Market Competitive Environment
Capital-heavy fermentation producers compete with asset-light enzyme formulation specialists for positioning in bakery conditioner supply chains. The European market structure concentrates around biotechnology clusters with captive manufacturing capacity, while North American players compete through diversified ingredient portfolios. Three archetypes dominate: integrated fermentation biotech firms, diversified global ingredient conglomerates, and specialized enzyme engineering boutiques. Consolidation through strategic acquisitions and capacity expansion in enzyme manufacturing represent the primary competitive vectors reshaping supplier rankings.
Among biotechnology-anchored specialists, Corbion and Lesaffre Group occupy positions exemplifying fermentation-derived competitive positioning, while Puratos Group represents the integrated innovation-center archetype with Belgian operational roots. These three firms anchor distinct strategic approaches to clean-label conditioner development across European industrial bakery procurement channels.
| Leading Market Players |
|---|
| Corbion |
| Puratos Group |
| Lesaffre Group |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| DSM-Firmenich |
| Kerry Group |
| AB Enzymes GmbH |
| Watson Inc. |
| Others |
Value Chain & Pricing Dynamics
Clean-label mandates from German and French retail chains are compressing procurement timelines for enzyme-based conditioners, forcing suppliers to absorb reformulation costs and reposition pricing around carbon-footprint transparency rather than commodity volume discounts.
Pricing Analysis
Three-tier pricing structure across premium enzyme blends, standard emulsifier formulations, and economy chemical conditioners dominates European procurement. Price differentiation hinges on EU CSRD-compliant carbon disclosure and REACH registration status. Cost compression in mid-tier emulsifiers is intensifying because Asian imports face documentation barriers. Industrial bakeries in Germany exhibit lowest price sensitivity due to consolidated supplier relationships, while Polish mid-size facilities remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Belgium, the Netherlands, and Germany anchor hub-and-spoke patterns serving industrial bakeries across Western Europe. Fermentation capacity concentrates in Flanders biotechnology clusters, with hydrocolloid stabilizers drawing from palm oil supply chains in Southeast Asia. Single-source vulnerability in amylase enzyme production creates exposure to EFSA approval delays. Distribution runs through direct technical service teams for large accounts and wholesale intermediaries for fragmented artisan channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the EU Green Deal's Farm to Fork Strategy creating successive reformulation cycles that extend supplier lock-in duration.
For Market Incumbents: Lock in long-term technical service contracts with French and Italian industrial bakeries before EFSA enzyme approval timelines compress further. Deepen backward integration into fermentation capacity to offset margin pressure from wheat and palm oil volatility. Prioritize CRISPR-optimized enzyme platforms to defend against proprietary sourdough substitution programs at large French bakery groups.
For New Entrants and Emerging Players: Capture volume expansion in Poland and Romania where conditioner penetration trails Western European benchmarks. Target artisan par-baked segments in Belgium with freeze-thaw stability specializations that command technical service premiums. Enter through precision fermentation partnerships that bypass capital-intensive captive manufacturing requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology boutiques holding novel enzyme pipelines awaiting EFSA positive opinions. Five-to-ten year viability favors firms combining transparent carbon-footprint data with direct sales relationships at top-ten European industrial bakeries. Monitor EFSA enzyme regulation revision announcements as the critical inflection signal for supplier qualification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Enables CRISPR-optimized amylase production tailored to specific wheat protein profiles for German industrial bakeries. |
| Direct Technical Service Team Deployment | Displaces wholesale distributors in French and Italian accounts where dough complexity demands on-site enzymologist support. |
| EU CSRD Carbon Disclosure Certification | Qualifies suppliers for premium procurement tiers under German retailer sustainability mandates. |
| Novel Enzyme EFSA Submission Acceleration | Compresses 18-24 month approval timelines to capture clean-label reformulation windows before competitors. |
| Eastern European Distribution Hub Establishment | Channels standardized enzyme blends into underpenetrated Polish and Romanian industrial baking sectors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered bakery R&D directors, procurement leads at industrial baking groups, enzyme formulation scientists, and wholesale distribution managers. Secondary validation drew from EFSA additive opinions, ECHA REACH registration databases, EU trade statistics, and Cefic chemical industry reports. Bottom-up volume modeling triangulated against top-down value estimates across product chemistry, application, and end-user segments.
Historical reference periods anchored the forecast window to pre-pandemic baseline activity and post-regulatory-shift demand patterns. The analytical framework modeled enzyme versus emulsifier substitution rates, artisan versus industrial end-user growth differentials, and direct versus distributor channel evolution. CAGRs derived from segment-level volume trajectories normalized against flour consumption indices and industrial bakery automation investment cycles.
EFSA enzyme approval delays, wheat commodity price spikes, and REACH registration cost inflation are the dominant revision risks. Forecasts reflect assumptions about regulatory timeline adherence and clean-label mandate enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Calorie Cake Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Bread Crumbs Market
Bakery Products
Frozen Bakery Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Bakery Mixes Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Bread Improver Market
Bakery Products
Specula Market
Bakery Products
Dough Conveyor Market
Bakery Products
South America Bakery Products Market
Bakery Products
Soft Biscuit Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Organic Bread Flour Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Pastries Market