
 Asia-Pacific Frozen Bakery Market | 2026-2036
Asia-Pacific Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Frozen Bakery Market Outlook
Subscription-based replenishment programs for food service operators is realigning how frozen bakery volumes move through the channel. Aryzta AG leverages its centralized production hubs to anchor supply consistency across Southeast Asian markets. Lantmannen Unibake competes through specialized par-baked portfolios tailored to European-style cafe concepts expanding in Australia and Japan.
Frozen bakery comprises flour-based products subjected to blast freezing after partial or full baking, preserved at temperatures below minus eighteen degrees Celsius to arrest starch retrogradation and extend shelf life to six-twelve months. The category serves commercial food preparation by reducing labor, waste, and proof-to-serve time. Breads and pastries command the largest volume positions, though pizza bases capture disproportionate margin in food service channels due to customization premiums. Direct shipping and retail distribution together dominate delivery mode flows, while vacuum-sealed packaging expands fastest as operators prioritize thaw consistency and display shelf appeal.
FSSAI standards in India mandate additive disclosures and cold chain integrity documentation, while China's SAMR enforces GB labeling rules that shape import eligibility for frozen dough. Japan's METI energy-efficiency guidelines for refrigeration equipment indirectly filter which processing technologies enter the market. Stakeholders must track how Australia's TGA-equivalent food safety audits and evolving ASEAN harmonization protocols will reshape cross-border qualification costs.
Market Dynamics
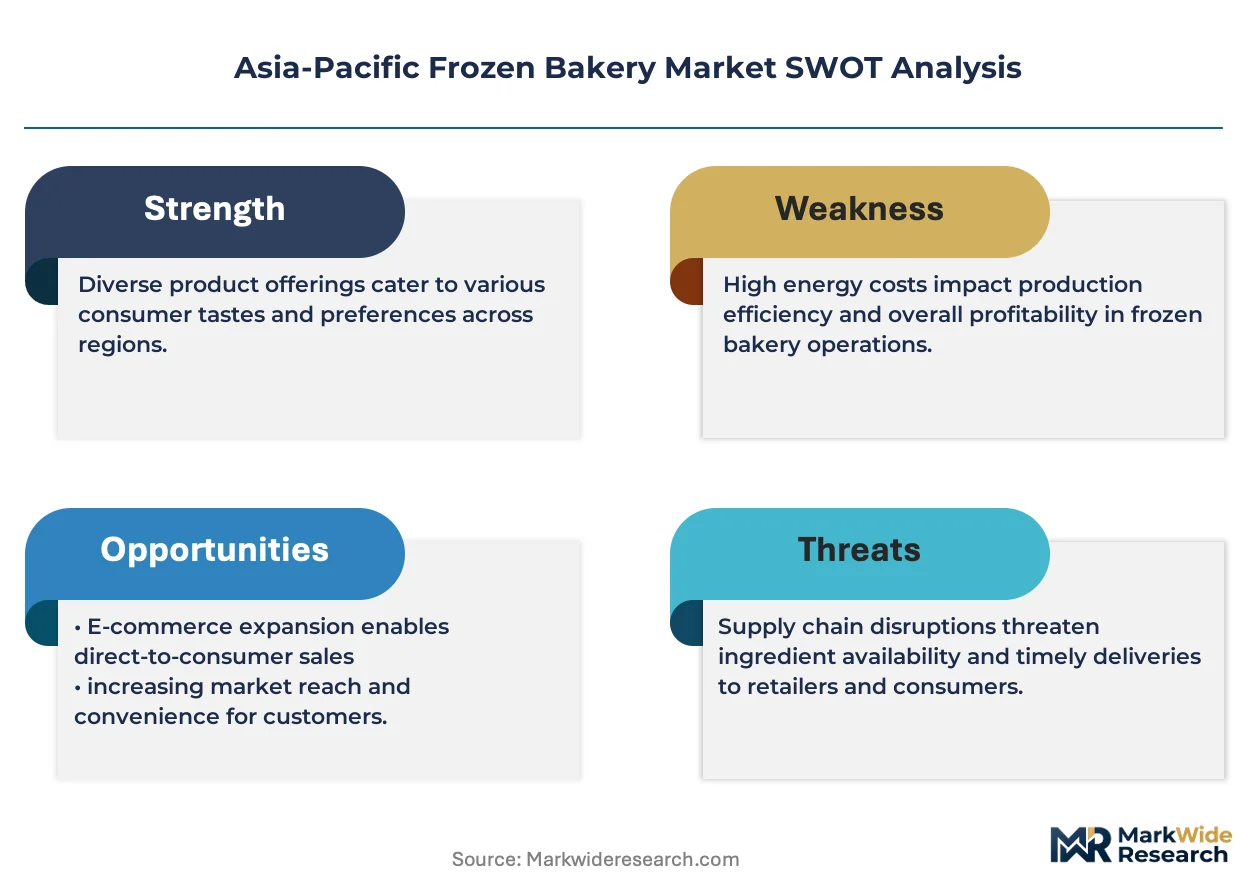
Energy-efficiency mandates under China's dual carbon goals are forcing frozen bakery manufacturers to retool blast-freezing and cold-chain infrastructure, compressing capital cycles and favoring operators with centralized production scale.
Growth Catalysts
- Quick-service restaurant expansion:Convenience-seeking food service operators across Southeast Asian urban corridors are standardizing frozen par-baked inputs to compress proof-to-serve windows and reduce on-site labor.
- FSSAI cold-chain documentation:India's mandatory additive disclosure and temperature-integrity protocols are professionalizing distributor compliance, raising barriers for informal suppliers and consolidating volume toward qualified players.
- Blast-freezing equipment upgrades:Cryogenic and mechanical freezing technologies with real-time monitoring are extending shelf-life consistency, enabling longer-haul distribution from centralized hubs to secondary cities.
Market Restraints
- Wheat and butter price volatility:Input cost swings in Australian and Black Sea grain markets compress margin predictability for margin-thin bread and pastry categories.
- Cold-chain infrastructure gaps:Last-mile refrigeration deficits in Indian tier-2 and tier-3 urban corridors limit penetration of temperature-sensitive laminated dough and cream-filled products.
- SAMR GB labeling friction:China's import eligibility rules for frozen dough create documentation bottlenecks for European and North American suppliers seeking market access.
Strategic Opportunities
- Vietnam and Philippines food service corridors:Underpenetrated quick-service and bakery-cafe channels in Ho Chi Minh City and Metro Manila offer first-mover positioning for par-baked pizza base and croissant suppliers.
- Subscription replenishment models:Direct-to-operator inventory programs are displacing spot procurement in Australian and Japanese cafe chains, locking in volume commitments and reducing demand volatility.
- ASEAN harmonization protocols:Emerging cross-border qualification standards will reduce duplicate certification costs for manufacturers operating across Thailand, Malaysia, and Indonesia.
Industry Challenges
- Refrigeration technician scarcity:Specialized maintenance skills for ultra-low-temperature blast freezers are concentrated in Shanghai, Tokyo, and Sydney, inflating service costs and downtime risk in secondary markets.
- Legacy ERP integration:Temperature-monitoring IoT systems require costly retrofitting of inventory management platforms at mid-scale food service distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Frozen Bakery Market |
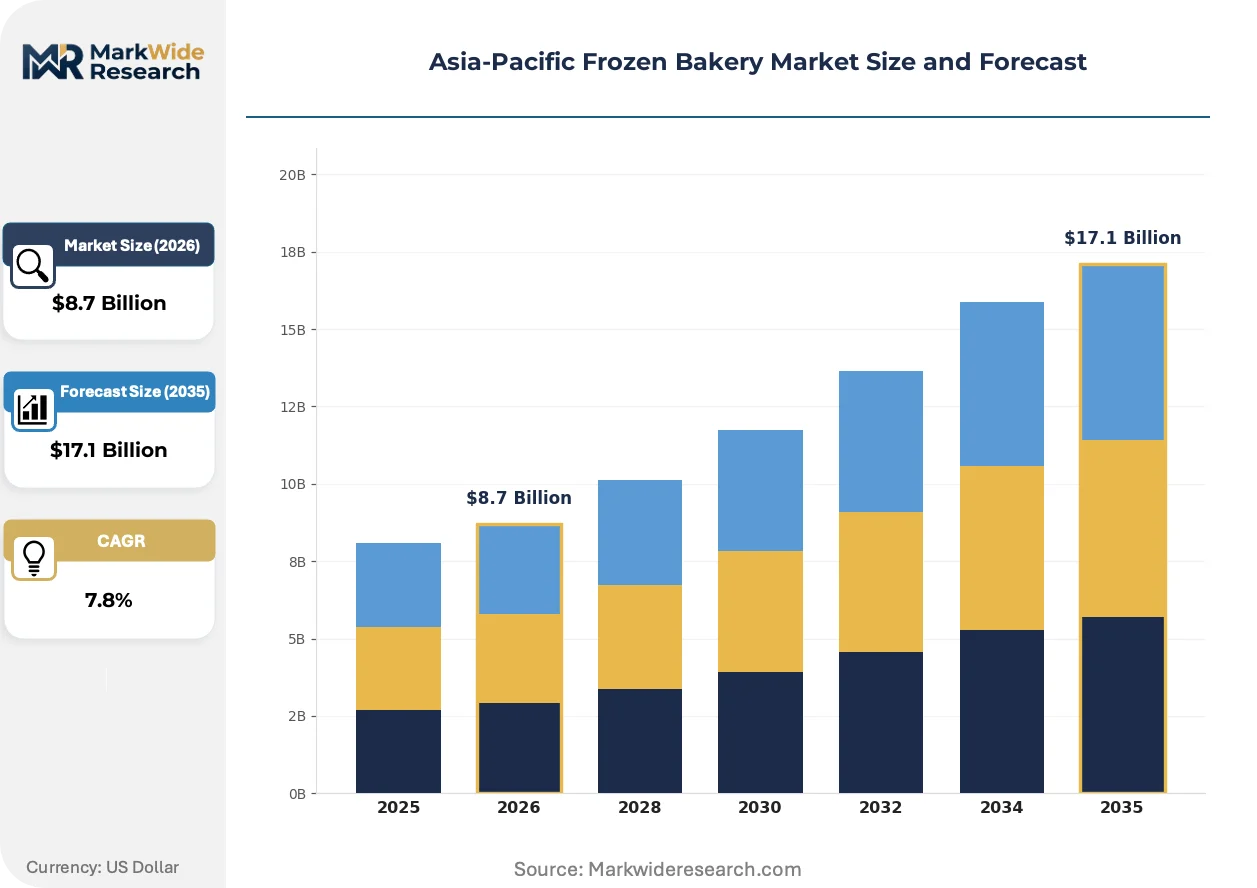
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cakes, Pizza Bases End User: Food Service, Retail, Bakeries, Cafes Delivery Mode: Direct Shipping, Retail Distribution, Online Sales, Wholesalers Packaging Type: Boxed, Vacuum Sealed, Bags, Trays |
| Companies Covered | Aryzta AG, Ajinomoto, Lantmannen Unibake, Nestle SA, Conagra Brands, Grupo Bimbo, McCain Foods, Pasco Shikishima Corporation, General Mills, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Frozen Bakery Market Strategic Shifts
Automation of freezing and packaging lines is compressing unit economics while regulatory pressure on energy intensity and packaging waste is reshaping capital allocation across the Asia-Pacific frozen bakery value chain.
Advanced cryogenic freezing systems with nitrogen injection and spiral belt configurations are automating the transition from batch to continuous processing. Japanese and South Korean industrial bakeries are adopting these lines at replacement cycle pace. The technology is automating labor out of high-throughput croissant and Danish production while tightening temperature uniformity to minus twenty degrees Celsius.
China's SAMR enforcement of GB standards on frozen dough imports is tightening additive disclosure and origin documentation requirements. Foreign suppliers must now maintain parallel labeling systems for domestic and export batches. Premium pizza base and specialty pastry categories face the steepest compliance cost escalation as they rely most heavily on imported inputs.
Food service operators are consolidating supplier relationships around integrated frozen-to-thaw solutions rather than discrete product procurement. Australian and Japanese cafe chains are bundling par-baked inventory with thawing equipment and staff training. This behavioral shift is most visible in Sydney and Melbourne where European-style cafe concepts are scaling rapidly and demanding consistent finished-product quality without on-site baking expertise.
Asia-Pacific Frozen Bakery Market Segmentation
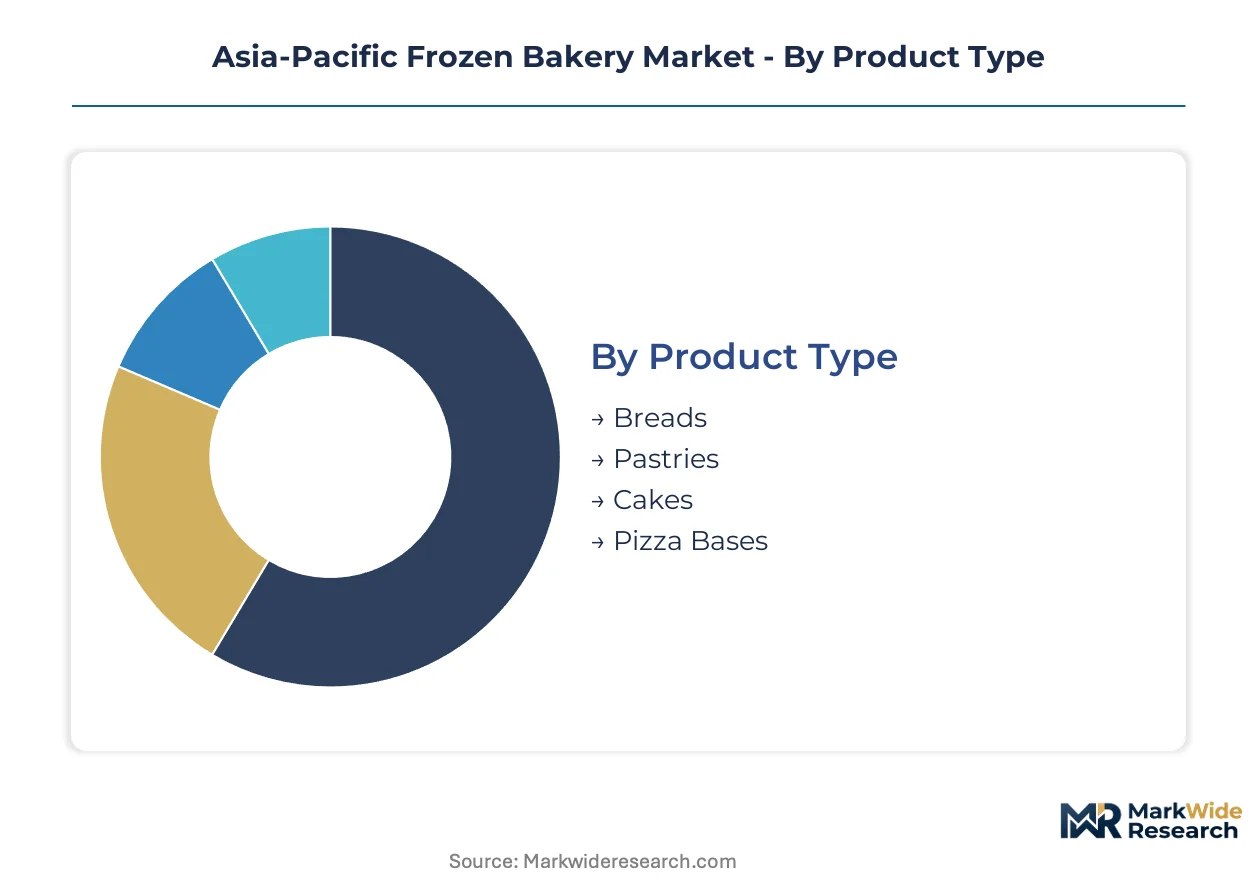
Segmentation in the Asia-Pacific frozen bakery market determines which production technologies and distribution investments manufacturers prioritize. Product type and end-user channel configurations dictate blast-freezing specifications, packaging formats, and cold-chain routing decisions across Southeast Asian, Australian, and Northeast Asian markets.
Product Type:
Integration depth varies sharply: breads and pastries serve as standalone finished goods requiring minimal downstream processing, while pizza bases and cakes embed into broader food preparation workflows demanding precise thaw-to-bake coordination.
- Breads:Standard loaves, rolls, and specialty grain formulations constitute the volume foundation of frozen bakery production. Demand concentrates in Australian and Japanese quick-service restaurant chains standardizing par-baked sourdough and brioche formats to eliminate on-site proofing labor.
- Pastries:Croissants, Danishes, and laminated dough products require cryogenic freezing to preserve butter-layer integrity through distribution. Ho Chi Minh City and Metro Manila bakery-cafe expansions are absorbing premium laminated products as European-style concepts proliferate.
- Cakes:Frozen sponge and layer cake components target institutional food service and celebration catering channels. FSSAI additive disclosure mandates in India constrain cream-filled and decorated varieties to qualified cold-chain distributors.
- Pizza Bases:Thin-crust, deep-dish, and artisanal sourdough platforms command customization premiums in food service procurement. Australian pizza chains are locking in direct-ship replenishment contracts for par-baked bases with specified thickness and edge-rise characteristics.
Volume placements concentrate in breads and pastries; the faster expansion belongs to pizza bases as Asian pizza delivery chains scale.
End User:
Channel cost tiers separate high-touch food service relationships from transactional retail throughput, with bakeries and cafes occupying an intermediate position demanding technical support bundled with product supply.
- Food Service:Quick-service restaurants, hotels, and institutional caterers procure frozen bakery inputs to compress labor costs and standardize output quality. Centralized production hubs in Thailand and Malaysia are anchoring supply consistency for Southeast Asian food service networks.
- Retail:Supermarkets and hypermarkets stock frozen bakery for home consumption, prioritizing extended shelf-life packaging and competitive unit pricing. Japan's convenience store chains are expanding private-label frozen pastry assortments with METI-aligned energy-efficient refrigeration.
- Bakeries:Independent and chain bakeries use frozen dough and par-baked components to extend product range without capital-intensive mixing and proofing infrastructure. Indian urban bakeries in Mumbai and Bangalore are adopting frozen Danish and puff pastry sheets to diversify morning offerings.
- Cafes:European-style coffee shop concepts require consistent croissant, muffin, and cake quality without on-site baking expertise. Sydney and Melbourne cafe chains are bundling par-baked inventory with thawing equipment and staff training programs.
Food service claims the dominant procurement volume; cafes are gaining share fastest as premium coffee culture spreads across Australian and Southeast Asian cities.
Delivery Mode:
Supply concentration patterns favor direct relationships with large-volume operators, while fragmented retail and wholesale channels require intermediary infrastructure investments.
- Direct Shipping:Manufacturer-to-operator delivery eliminates distributor margins and enables temperature-monitoring integration with customer ERP systems. Japanese and Australian cafe chains are consolidating procurement around direct-ship replenishment subscriptions.
- Retail Distribution:Branded and private-label frozen bakery moves through supermarket and convenience store networks with dedicated freezer-aisle placement. China's SAMR GB labeling compliance creates documentation friction for imported products entering retail channels.
- Online Sales:E-commerce platforms and direct-to-consumer frozen bakery subscriptions are emerging in urban Australian and South Korean markets. Cold-chain last-mile capabilities constrain category penetration outside major metropolitan zones.
- Wholesalers:Broadline food service distributors aggregate frozen bakery with protein and produce categories for smaller restaurant and catering accounts. India's tier-2 and tier-3 urban corridors depend on wholesaler networks where cold-chain integrity documentation remains inconsistent.
Direct shipping captures the highest-margin volume; online sales are climbing the fastest as urban consumers adopt subscription replenishment models.
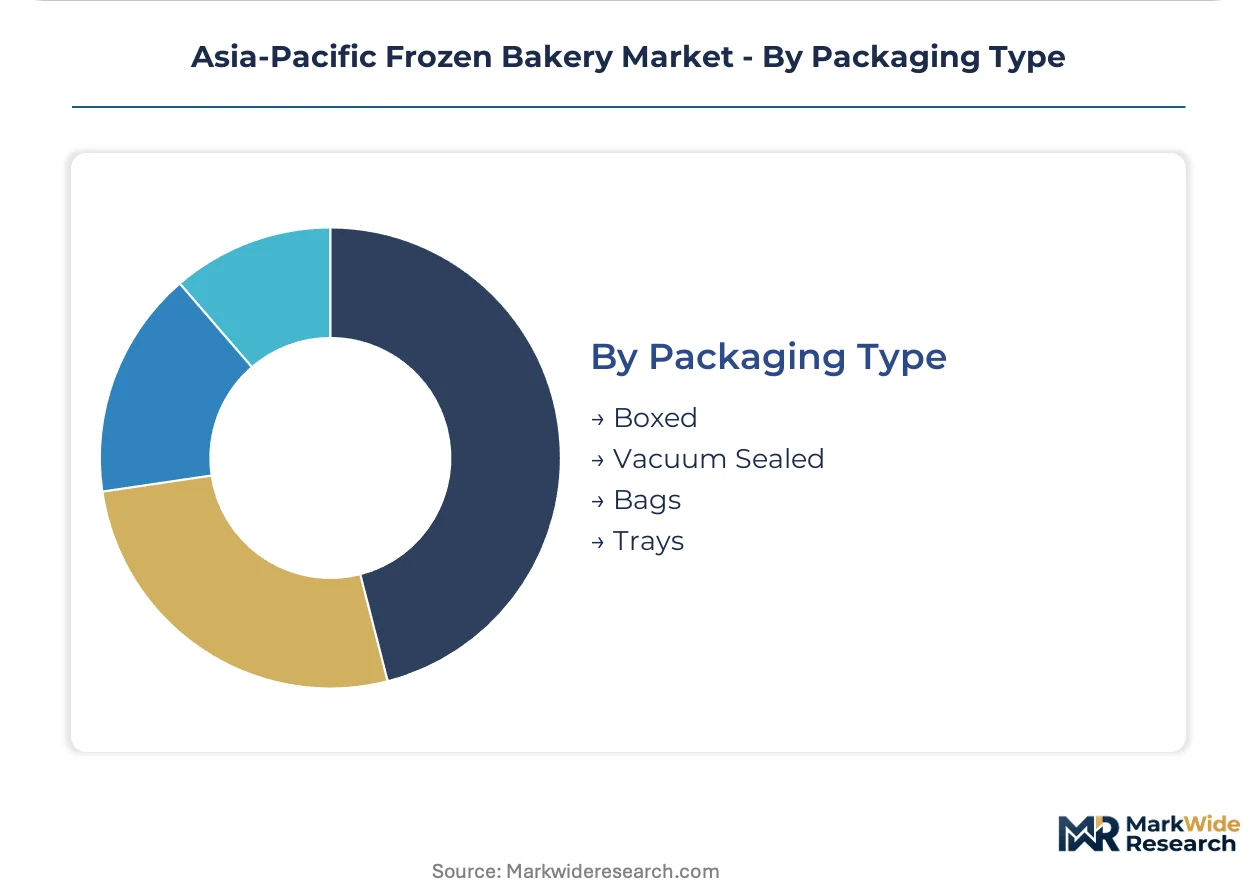
Packaging Type:
Margin structure separates premium vacuum-sealed formats from commodity boxed and bagged alternatives, with tray configurations optimizing food service handling efficiency.
- Boxed:Rigid cardboard enclosures protect layered cakes and delicate pastries through multi-handling distribution. Australian celebration cake suppliers rely on boxed formats for retail and wholesale channel penetration.
- Vacuum Sealed:Oxygen-extracted flexible packaging extends shelf life and preserves thaw consistency for premium laminated dough and artisan bread categories. Japanese industrial bakeries are converting freezing lines to accommodate vacuum-sealed output for export and domestic premium channels.
- Bags:Polyethylene and laminated film bags serve commodity bread and roll categories with cost-minimized protection. Indian retail distributors favor bagged formats for price-sensitive mass-market positioning.
- Trays:Rigid plastic or aluminum trays enable direct oven insertion for par-baked pizza bases and portioned pastries. Southeast Asian quick-service pizza chains specify tray formats to accelerate kitchen throughput.
Boxed and bagged formats dominate current volume; vacuum-sealed packaging is gaining share fastest as operators prioritize extended shelf life and display aesthetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centralized production in Thailand and Malaysia supplies consumption across Southeast Asian urban corridors, while Northeast Asian markets maintain distinct cold-chain specifications shaped by national energy-efficiency mandates.
China
Quick-service restaurant chains in Shanghai and Beijing compress proof-to-serve windows through par-baked procurement. SAMR's GB labeling standards enforce additive disclosure and origin documentation for frozen dough imports. Yangtze River Delta manufacturers are retooling blast-freezing infrastructure to meet dual carbon energy-efficiency targets.
India
Urban bakery-cafe expansion in Mumbai and Bangalore drives demand for frozen Danish and puff pastry sheets. FSSAI mandates cold-chain integrity documentation and additive labeling, consolidating volume toward qualified distributors. Tier-2 corridors including Pune and Hyderabad depend on wholesaler networks with inconsistent refrigeration.
Japan
Convenience store chains expand private-label frozen pastry assortments as METI refrigeration guidelines filter processing technology imports. Kanto region industrial bakeries adopt cryogenic freezing lines with nitrogen injection for croissant production. Osaka-based cafe concepts bundle par-baked inventory with thawing equipment and staff training.
Australia
Sydney and Melbourne European-style cafe chains standardize procurement around direct-ship replenishment subscriptions. Premium pizza base suppliers lock in thickness and edge-rise specifications through food service contracts. Victoria and New South Wales distribution networks prioritize vacuum-sealed packaging for extended shelf-life consistency.
Vietnam
Ho Chi Minh City quick-service and bakery-cafe channels absorb premium laminated products as European-style concepts proliferate. Underpenetrated food service corridors offer positioning for par-baked pizza base suppliers. Local distributors face cold-chain infrastructure gaps limiting cream-filled and temperature-sensitive product penetration.
Asia-Pacific Frozen Bakery Market Competitive Environment
Top-tier vendors anchor centralized production scale, while mid-tier specialists compete through portfolio specialization. The market structures around three to four dominant multinational players with regional hub strategies, supplemented by national bakery conglomerates and frozen food diversifiers. Strategic archetypes include hub-and-spoke manufacturers, par-baked specialists, and broadline frozen food operators. Competitive moves concentrate on direct-ship subscription models and ASEAN cross-border certification alignment.
Within the hub-and-spoke tier, Aryzta AG and Lantmannen Unibake exemplify centralized production strategies. Ajinomoto occupies a position bridging Japanese industrial bakery technology with Southeast Asian market development. These three entities represent distinct geographic anchoring patterns: Swiss-based multinational hub operations, European par-baked portfolio specialization, and Japanese integrated food technology application.
| Leading Market Players |
|---|
| Aryzta AG |
| Ajinomoto |
| Lantmannen Unibake |
| Nestle SA |
| Conagra Brands |
| Grupo Bimbo |
| McCain Foods |
| Pasco Shikishima Corporation |
| General Mills |
| Others |
Value Chain & Pricing Dynamics
Captive cold-chain infrastructure in Thailand and Malaysia anchors both supply security and pricing power for frozen bakery manufacturers serving Southeast Asian food service networks. Centralized blast-freezing hubs enable volume-tiered contract structures that compress per-unit costs while locking in subscription commitments from quick-service restaurant chains.
Pricing Analysis
Margin tightening in commodity bread and pastry tiers reflects wheat and butter price volatility from Australian and Black Sea grain markets. Three-tier pricing structure across premium vacuum-sealed laminated dough, standard par-baked components, and economy bagged formats separates customization-intensive pizza base contracts from transactional retail volumes. Cost-down pressure accelerates as Indian FSSAI compliance documentation raises distributor qualification barriers. Food service operators demonstrate lowest price sensitivity due to labor-cost substitution value, while Indian tier-2 retail channels remain most price-responsive.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and Australian cafe chains mandate multi-hub qualification across Thai, Malaysian, and Vietnamese production facilities. Raw material dependencies center on Australian wheat, New Zealand butter, and Chinese packaging substrates. Single-source vulnerability concentrates in cryogenic freezing equipment where Japanese and South Korean technology suppliers dominate. Distribution runs through direct-ship replenishment subscriptions for large food service accounts, with wholesaler networks covering fragmented retail and bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum across the Asia-Pacific frozen bakery market is accelerating as manufacturers pursue captive cold-chain infrastructure to defend margin position against input volatility and regulatory compliance costs.
For Market Incumbents: Anchor supply consistency through centralized hub expansion in Vietnam and Philippines corridors where quick-service restaurant penetration remains underdeveloped. Invest in FSSAI and SAMR certification documentation capabilities to consolidate volume as compliance barriers eliminate informal distributors. Cryogenic freezing equipment maintenance networks require technician training partnerships to reduce downtime risk in secondary markets. For New Entrants and Emerging Players: Direct-to-operator digital replenishment platforms offer white-space entry into Australian and Japanese cafe chains seeking bundled par-baked inventory with thawing equipment. Vietnam's Ho Chi Minh City food service corridor presents the most penetrable geography for par-baked pizza base specialists. Subscription-based procurement models displace spot purchasing and lock in volume commitments against incumbent distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational hub-and-spoke operators seeking Southeast Asian production scale. Mid-scale manufacturers with integrated cold-chain documentation and ASEAN cross-border certification alignment represent priority target archetypes. The signal to watch is acceleration of subscription replenishment adoption rates among Australian and Japanese food service operators as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Hub Expansion | Thai and Malaysian production scale anchors supply consistency across Southeast Asian urban corridors. |
| Cryogenic Freezing Technology Adoption | Nitrogen injection lines from Japanese suppliers automate labor out of high-throughput croissant production. |
| Direct-Ship Subscription Models | Manufacturer-to-operator replenishment locks in volume commitments from Australian cafe chains. |
| Regulatory Certification Investment | FSSAI and SAMR documentation capabilities consolidate volume toward qualified distributors in India and China. |
| ASEAN Cross-Border Harmonization | Emerging qualification standards reduce duplicate certification costs for manufacturers operating across Thailand, Malaysia, and Indonesia. |
Study Parameters
Multi-period observation of blast-freezing equipment deployment, cold-chain infrastructure investment, and subscription replenishment adoption anchored the trend analysis, supplemented by interviews with frozen bakery plant managers, food service procurement directors, cold-chain logistics operators, and regulatory compliance officers. Secondary validation drew from customs and trade data, FSSAI and SAMR regulatory filings, ASEAN harmonization protocol documents, and industrial bakery equipment manufacturer disclosures. Bottom-up volume modeling and top-down market sizing triangulated across segmentation dimensions.
Input-output matrices mapped frozen bakery production capacity, cold-chain routing efficiency, and end-user procurement patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, delivery mode, and packaging format. CAGRs were derived from trend extrapolation of historical volume movements and forward projection of quick-service restaurant expansion rates. Forecast inputs incorporated energy-efficiency mandate compliance costs and wheat futures price trajectory assumptions.
The model holds under stable regulatory enforcement intensity and sustained quick-service restaurant expansion; deviation in cold-chain infrastructure investment rates or grain market volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Fat Bread Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Cake Base Discs Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Global Bakery Product Market
Bakery Products
Bread Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
North America Bakery Products Market
Bakery Products
North America Fortified Bakery Products Market