
 Pancake Mixes Market | 2026-2036
Pancake Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Pancake Mixes Market Outlook
Grain-milling technician shortages across the Midwest is rotating production scheduling toward automated batching systems at larger facilities. General Mills sustains its position through in-house flour milling and extensive retail shelf-space agreements. Kodiak Cakes differentiates via protein-fortified formulations that command premium placement in health-focused retail channels. Bob's Red Mill occupies the stone-ground heritage niche with strong direct-to-consumer fulfillment infrastructure.
Pancake mixes are dry, pre-portioned blends of refined or whole-grain flour, leavening agents, and functional additives requiring hydration and thermal processing to produce flat, griddle-cooked cakes. Manufacturing employs roller-milled or hammer-milled flour bases, with leavening systems calibrated to specific hydration ratios and cook temperatures for texture control. The organic and gluten-free product type segments are capturing expanding margin pools as ingredient certification costs create barriers for smaller entrants. Ready-to-cook liquid and instant forms are gaining velocity through convenience-store and food-service channels where labor minimization drives procurement decisions.
The FDA governs ingredient disclosure and nutrient content claims, while the USDA Organic seal governs certification requirements for premium-positioned products. State-level cottage-food laws in California, Texas, and New York create fragmented market-access conditions for artisan producers selling through farmers markets and regional retail. Stakeholders must monitor evolving clean-label thresholds and alternative-protein fortification standards as formulation complexity intensifies.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements and sodium reduction targets are pressing manufacturers toward reformulation of conventional pancake mix formulations, reshaping ingredient sourcing and production economics across the category.
Growth Catalysts
- Quick-service restaurant expansion:Breakfast menu proliferation at fast-casual chains is driving commercial procurement volumes for bulk pancake mix formats.
- USDA Organic certification demand:Premium-positioned products bearing the USDA Organic seal command expanded shelf-space allocation in health-focused retail channels.
- Protein fortification technology:Whey and plant-based protein integration into dry blends is capturing margin pools in performance-nutrition segments.
Market Restraints
- Wheat flour price volatility:Input cost swings for hard red winter wheat constrain margin predictability for conventional formulation producers.
- Midwest grain-milling concentration:Technician shortages across Kansas, Nebraska, and Iowa facilities limit production scaling flexibility.
- Gluten-free certification barriers:Third-party testing and facility segregation requirements create capital intensity for artisan entrants.
Strategic Opportunities
- Convenience-store channel penetration:Ready-to-cook liquid formats address labor minimization priorities in food-service and C-store environments.
- California cottage-food market access:State-level direct-to-consumer sales laws enable artisan producers to bypass traditional retail gatekeepers.
- Stone-ground heritage positioning:Traditional milling narratives differentiate private-label and regional brands in premium shelf-space competition.
Industry Challenges
- Automated batching system integration:Legacy facilities face capex burdens retooling from manual to programmable flour handling and leavening calibration.
- Clean-label threshold evolution:Shifting consumer definitions of "natural" and "simple" force continuous ingredient declaration revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancake Mixes Market |
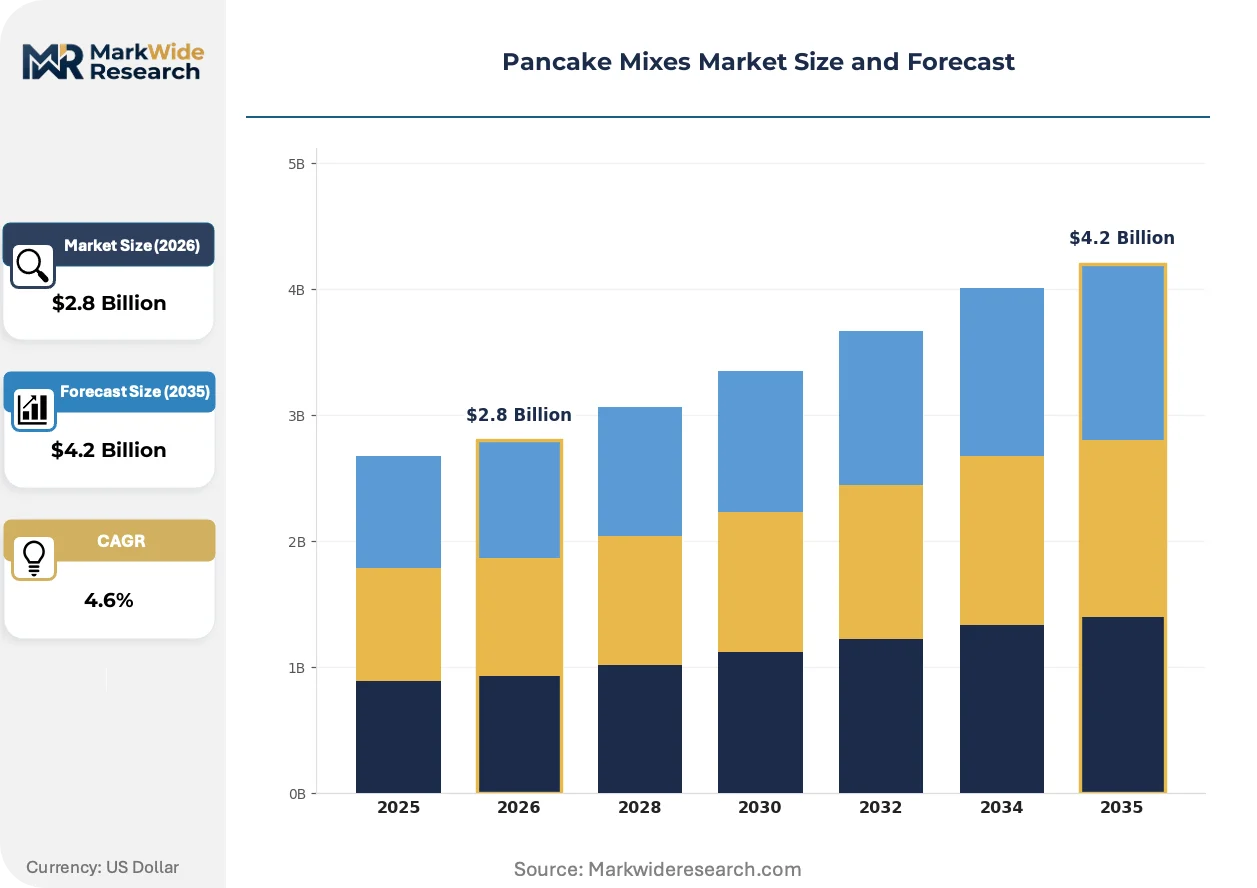
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Whole Wheat, Gluten-Free, Organic Form: Powder, Ready-to-Cook, Liquid, Instant Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Hometown Food Company, Bob's Red Mill, General Mills, King Arthur Baking Company, C.H. Guenther & Son, Continental Mills, Kodiak Cakes, Simple Mills, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancake Mixes Market Strategic Shifts
Formulation complexity is intensifying across the pancake mixes category as manufacturers balance convenience expectations against clean-label demands and functional fortification requirements.
Spray-dried egg and buttermilk powder systems are miniaturizing leavening reaction control, enabling single-step hydration without separate wet ingredient addition. Food-service operators in high-turnover breakfast environments are adopting these simplified systems to compress prep time. The technology is miniaturizing equipment footprints in back-of-house configurations while standardizing texture outputs across variable staff skill levels.
The FDA's updated Nutrition Facts labeling requirements mandate added-sugar disclosure and revised serving-size definitions for dry mix categories. Manufacturers must reformulate or accept prominent negative nutrient callouts on front-facing packaging. Conventional mass-market formulations with elevated sodium and sugar content face the steepest compliance costs and consumer perception headwinds.
Direct-to-consumer subscription models are displacing traditional grocery replenishment cycles for specialty and allergen-free pancake mix varieties. Heritage brands with established e-commerce fulfillment infrastructure are capturing recurring revenue streams independent of retail slotting fee negotiations. This channel rotation is most pronounced in coastal metropolitan markets where pantry stocking convenience outweighs price sensitivity.
Pancake Mixes Market Segmentation
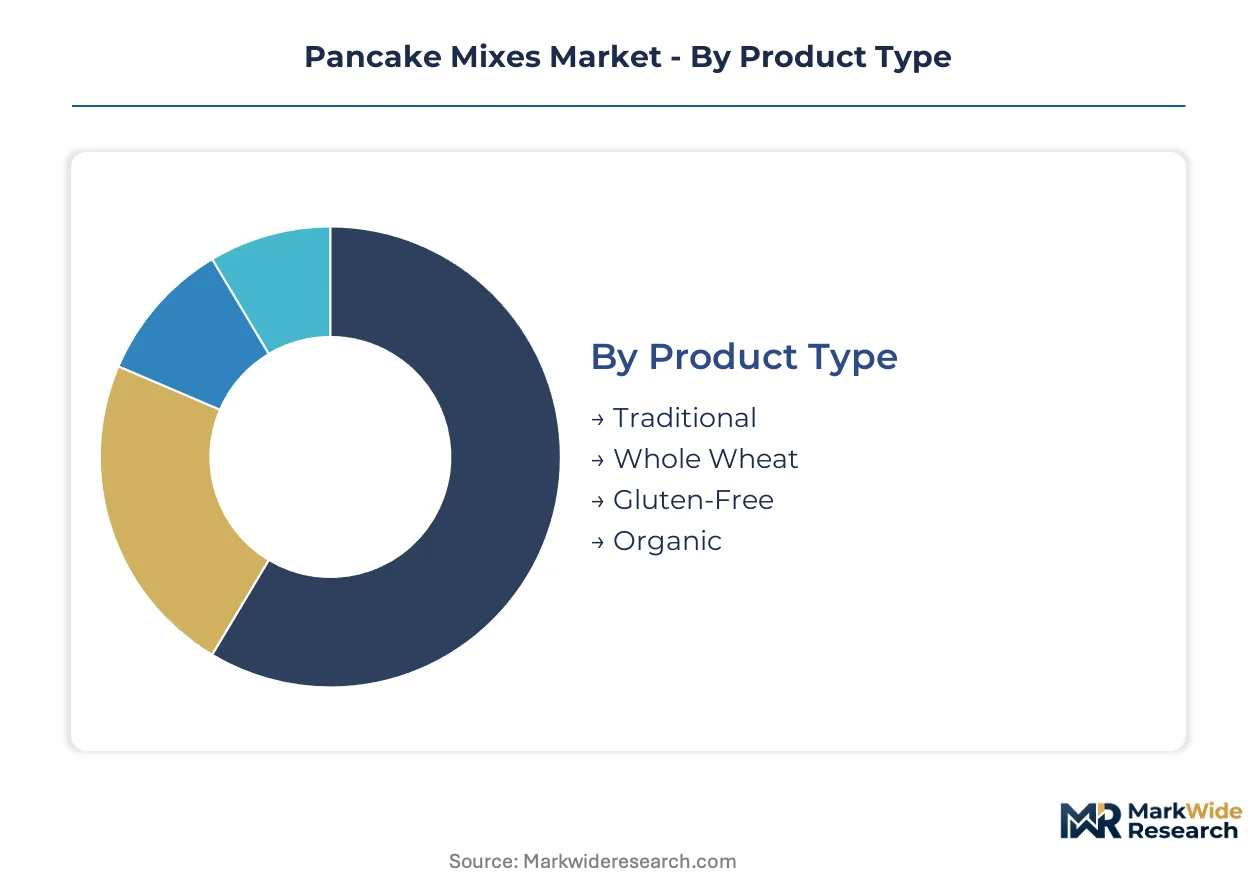
Segmentation in pancake mixes determines channel economics and margin architecture. Formulation complexity, shelf stability, and hydration requirements dictate which products flow through retail versus food-service routes.
Product Type:
Channel-mix patterns diverge sharply across product types, with conventional formulations dominating mass retail while certified variants command specialty placement.
- Traditional:Refined wheat flour bases with calibrated leavening systems dominate supermarket shelf-space and quick-service restaurant procurement. Demand concentrates in the United States where private-label penetration pressures branded margins.
- Organic:USDA-certified formulations require segregated supply chains and third-party verification, creating barriers that limit competition to established players with captive milling operations. Coastal metropolitan markets drive direct-to-consumer velocity for these SKUs.
- Whole Wheat:Stone-ground or roller-milled whole grain bases appeal to health-positioned retail channels.
- Gluten-Free:Sorghum, rice, or almond flour substitutes require dedicated facility certification.
Traditional mixes dominate installed base. Organic is where expansion concentrates.
Form:
Cost tier stratification separates commodity powder formats from premium liquid and instant systems.
- Powder:Dry blended flour and leavening agents in moisture-barrier packaging constitute the volume base. Food-service operators in high-turnover breakfast environments favor bulk powder for cost control and storage efficiency.
- Liquid:Pre-hydrated batters in refrigerated distribution capture convenience-store and cafe channels where labor minimization overrides ingredient cost premiums. The format commands shelf-space allocation in grab-and-go retail sections.
- Ready-to-Cook:Single-step hydration systems with spray-dried dairy components.
- Instant:Just-add-water formulations with extended stabilizer systems.
Powder dominates installed base. Liquid is climbing the fastest.
Distribution Channel:
Customer type determines procurement patterns across institutional and retail pathways.
- Supermarkets:Mass-market and premium artisan brands compete for shelf-space allocation through slotting fee negotiations and promotional calendar coordination. The channel captures household replenishment cycles and impulse purchase occasions.
- Food Service:Bulk format procurement by restaurant chains and institutional operators emphasizes consistency, yield predictability, and back-of-house labor reduction over brand recognition.
- Online Retail:Subscription models and allergen-free specialty varieties bypass traditional retail gatekeepers.
- Convenience Stores:Single-serve and ready-to-cook formats address immediate consumption occasions.
Supermarkets dominate installed base. Food Service is gaining share fastest.
End User:
Application requirements separate household preparation flexibility from commercial operational constraints.
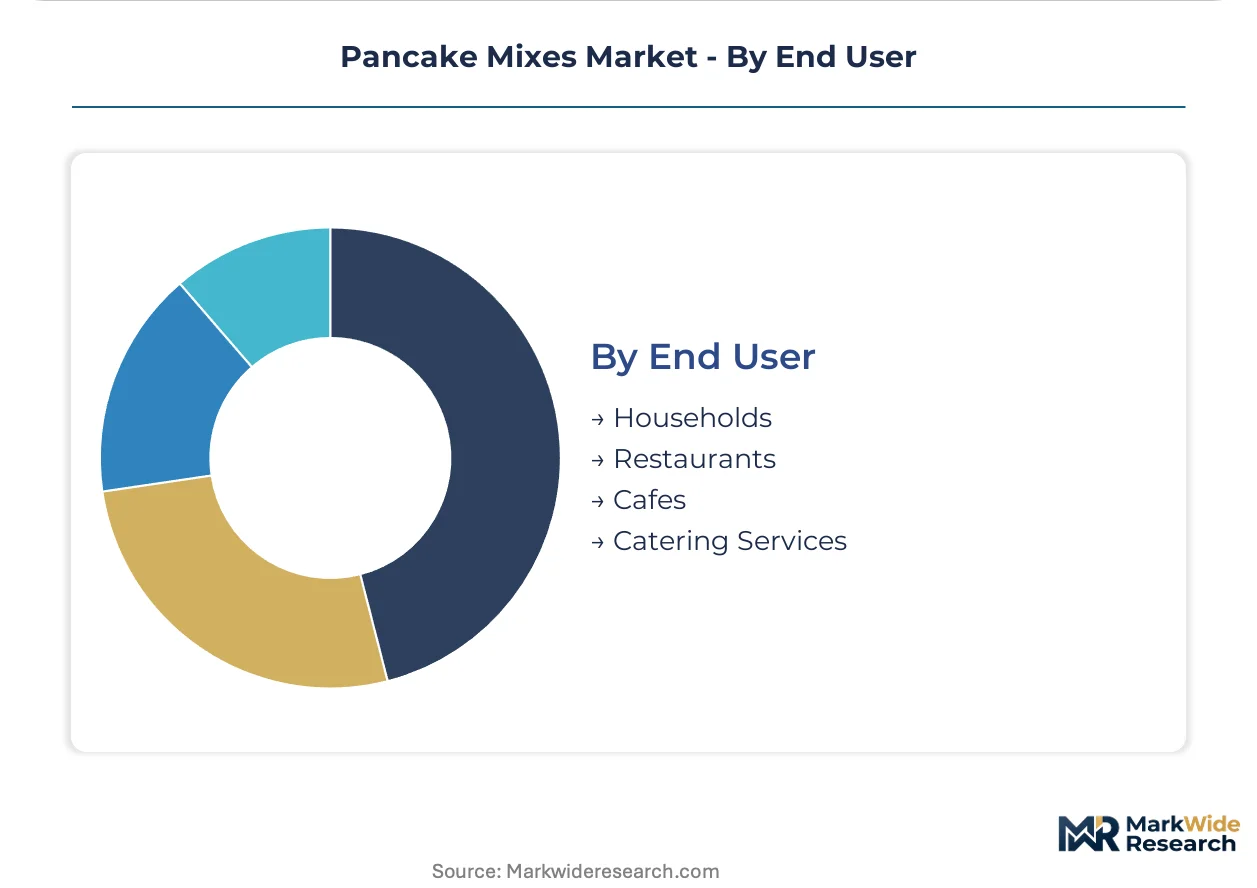
- Households:Weekend and occasion-based consumption drives variety-seeking behavior across flavor and nutritional-positioned SKUs. Pantry stocking patterns favor multi-use formats with extended shelf stability.
- Restaurants:Breakfast menu proliferation at fast-casual chains generates concentrated procurement volumes with strict texture and hold-time specifications.
- Cafes:Smaller-batch operators prioritize equipment footprint minimization and staff skill independence.
- Catering Services:Event-based volume spikes require scalable preparation systems with transport-stable outputs.
Households dominate installed base. Restaurants represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breakfast consumption patterns diverge sharply across geographies, with the United States treating pancake mixes as a pantry staple while other markets position them as occasional specialty items. This differential shapes formulation priorities, distribution infrastructure, and regulatory compliance investments.
United States
Private-label penetration and premium artisan positioning are reshaping supermarket shelf-space allocation across the Midwest and coastal metropolitan markets. The FDA's updated Nutrition Facts labeling requirements and sodium reduction targets are pressing reformulation across conventional formulations. Kansas, Nebraska, and Iowa host concentrated grain-milling operations where technician shortages are rotating production scheduling toward automated batching systems.
Canada
Health Canada and the PMRA govern ingredient disclosure and allergen labeling for imported and domestically produced dry mix categories. Provincial cottage-food regulations in Ontario and British Columbia create fragmented market-access conditions for artisan producers selling through farmers markets. Toronto and Vancouver metropolitan areas drive direct-to-consumer velocity for organic and gluten-free certified varieties.
Germany
EFSA guidelines on nutrient content claims and the EU Green Deal's sustainable packaging requirements are reshaping import specifications for North American pancake mix suppliers. Stone-ground heritage positioning from regional millers competes with mass-market formats in Bavaria and North Rhine-Westphalia retail channels. Berlin's food-service sector is adopting ready-to-cook liquid formats for cafe breakfast menu compression.
United Kingdom
FSSA enforcement of post-Brexit food labeling standards creates compliance friction for US and EU suppliers seeking supermarket distribution. London and Southeast England concentrate demand for protein-fortified and allergen-free specialty varieties through subscription commerce. Midlands-based industrial bakeries supply bulk formats to quick-service restaurant chains expanding breakfast menus.
Japan
METI standards on functional food claims and JIS packaging specifications govern formulation and import requirements for dry mix categories. Tokyo and Osaka metropolitan markets exhibit demand for miniaturized single-serve formats suited to compact urban household storage. Kyushu-based regional millers are developing rice-flour substitutes for gluten-intolerant consumer segments.
Pancake Mixes Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the pancake mixes market, with scale advantages in flour milling and retail shelf-space agreements separating the tiers. The integrated leaders control captive supply chains from grain procurement through packaged goods distribution. Specialist competitors occupy protein-fortified, stone-ground heritage, and allergen-free archetypes. M&A activity targets regional artisan brands with direct-to-consumer infrastructure, while portfolio diversification into adjacent breakfast categories represents the second dominant competitive move.
Within the heritage-milling archetype, Bob's Red Mill anchors stone-ground positioning with established fulfillment infrastructure. General Mills exemplifies the integrated leader tier through in-house flour milling operations and extensive retail agreements. Kodiak Cakes occupies the protein-fortification vector, commanding premium placement in health-focused retail channels. These three companies represent the strategic poles—heritage narrative, supply-chain scale, and functional differentiation—around which competitive positioning organizes.
| Leading Market Players |
|---|
| Hometown Food Company |
| Bob's Red Mill |
| General Mills |
| King Arthur Baking Company |
| C.H. Guenther & Son |
| Continental Mills |
| Kodiak Cakes |
| Simple Mills |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Hard red winter wheat substitution by alternative grain bases in gluten-free and protein-fortified formulations is rotating procurement geography toward sorghum-growing regions in Kansas and Texas while compressing margin structures for conventional roller-milled suppliers dependent on commodity wheat futures.
Pricing Analysis
Contract-based long-term offtake agreements dominate food-service procurement for bulk powder formats, while spot-market purchasing prevails in retail private-label sourcing. Price differentiation rests on certification grade (USDA Organic versus conventional) and volume scale, with artisan stone-ground SKUs commanding premiums against mass-market commodity tiers. Cost compression in conventional formulations is intensifying because FDA-mandated sodium and added-sugar disclosure pressures reformulation investments. Quick-service restaurant chains exhibit lowest price sensitivity due to operational consistency requirements, while household private-label buyers demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences characterize food-service operators managing bulk powder inventories against seasonal demand spikes, contrasting with just-in-time replenishment patterns in direct-to-consumer subscription channels. Geographic supply concentrates in the United States, Canada, and Germany, with hard red winter wheat drawing from Midwest grain elevators and alternative flours sourcing from Texas sorghum and California almond processing. Single-source vulnerability sits with segregated gluten-free facility certification, where dedicated production lines create capacity bottlenecks. Distribution runs through regional milling networks into retail grocery and food-service redistribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Midwest grain-milling technician attrition is constraining production scaling flexibility, making automated batching expertise and captive flour-milling assets the decisive capability differentiators across formulation tiers.
For Market Incumbents: Secure automated batching system integration at legacy facilities to offset technician scarcity in Kansas, Nebraska, and Iowa production clusters. Defend shelf-space allocation through exclusive retail agreements while acquiring regional artisan brands with established direct-to-consumer fulfillment infrastructure to neutralize subscription-channel displacement. For New Entrants and Emerging Players: Differentiate on stone-ground heritage narratives targeting coastal metropolitan markets where pantry-stocking convenience outweighs price sensitivity. White-space concentrates in California cottage-food direct sales enabled by state-level exemptions, with protein-fortified formulations offering the most penetrable premium tier. Launch through farmers market channels bypassing traditional retail slotting fee barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional millers possessing USDA Organic certification and e-commerce infrastructure. Long-term viability hinges on clean-label threshold evolution and alternative-protein fortification standards across a five-to-ten-year horizon. Target acquisition archetypes include heritage-positioned stone-ground specialists with captive supply chains. The signal to watch is FDA enforcement intensity on sodium reduction timelines as reformulation capex inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Batching System Deployment | Midwest facilities offset technician shortages through programmable flour handling and leavening calibration. |
| Protein Fortification Technology Investment | Whey and plant-based integration captures margin pools in performance-nutrition retail channels. |
| Direct-to-Consumer Subscription Launch | Heritage brands bypass slotting fees through recurring revenue in coastal metropolitan markets. |
| USDA Organic Certification Expansion | Segregated supply chains create barriers limiting competition to established captive milling operations. |
| Ready-to-Cook Liquid Format Development | Pre-hydrated batters address labor minimization priorities in convenience-store and cafe channels. |
Study Parameters
Operator-level perspectives from grain-milling technicians, food-service procurement directors, retail category buyers, and regulatory compliance officers anchored the qualitative base. Secondary validation drew from FDA guidance documents, USDA Organic certification databases, SEC 10-K filings of integrated milling operations, and Nielsen retail audit data. Bottom-up volume estimates triangulated against top-down category spending analysis across the projection horizon.
Sensitivity analysis tested input cost volatility scenarios for hard red winter wheat and alternative grain substitutes. Segmentation dimensions modeled include product type (traditional, organic, whole wheat, gluten-free), form (powder, liquid, ready-to-cook, instant), distribution channel, and end-user application. CAGRs derived from historical trajectory analysis adjusted for regulatory reformulation timelines and channel-shift velocity. Industry-specific inputs incorporated FDA Nutrition Facts compliance deadlines and cottage-food law expansion patterns.
Material uncertainties — wheat futures volatility, technician labor availability, and clean-label threshold evolution — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable regulatory enforcement intensity and continued quick-service restaurant breakfast menu expansion. Revision becomes warranted when FDA sodium reduction mandate timelines accelerate or automated batching technology adoption crosses critical mass thresholds in Midwest production clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Dough Conveyor Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Global Bakery Product Market
Bakery Products
Vegan Donuts Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Bakery Premixes Market
Bakery Products
Bakery Flavors Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Bakers Yeast Market
Bakery Products
Soft Biscuit Market
Bakery Products
Low Fat Bread Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
APMEA Frozen Bakery Products Market