
 Bread Dough Improver Market | 2026-2036
Bread Dough Improver Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Dough Improver Market Analysis
Bakery technologist shortages across industrialized markets is redrawing competitive boundaries for ingredient suppliers. Corbion NV leverages its fermentation science depth to sustain enzyme supply contracts with pan-European millers. Puratos Group anchors global distribution through sourdough and improver innovation centers in Belgium and Singapore. ADM competes on North American grain origination, controlling wheat protein extraction that feeds captive improver production.
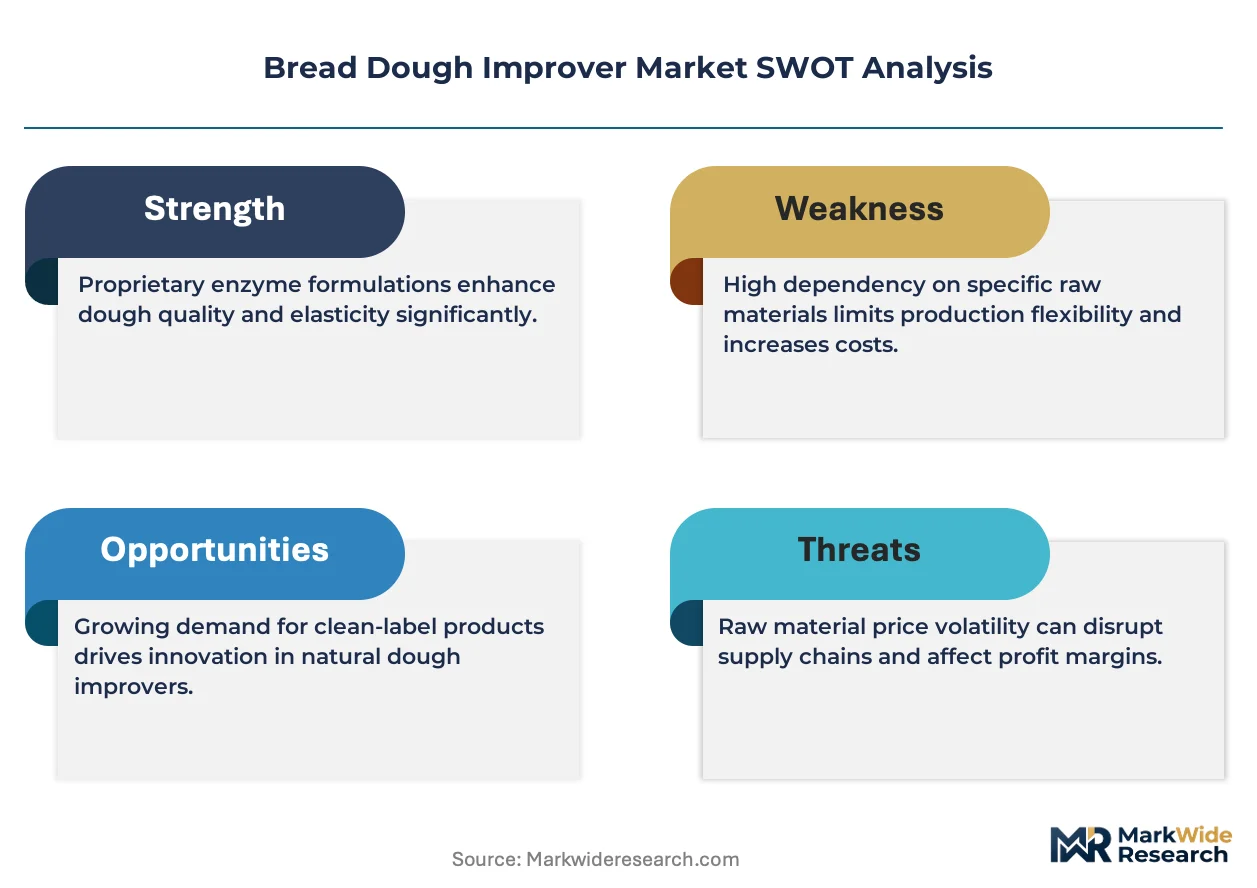
Bread dough improvers are functional ingredient systems—typically comprising emulsifiers such as DATEM or SSL, enzymes including amylase and xylanase, and oxidants like ascorbic acid or azodicarbonamide—that modify gluten network development, gas retention, and crumb structure during mechanical mixing and proofing. Industrial bakers deploy these systems to standardize dough handling under high-speed, continuous-mix conditions where flour variability would otherwise cause production losses. Enzyme-based improvers command expanding share as bakeries reformulate to reduce chemical additive declarations, while emulsifier demand persists in frozen dough applications where cryostability proves critical. Oxidant segments face substitution pressure from clean-label trends, compressing margin pools in commodity-grade ascorbic acid while premium fermented alternatives gain pricing power.
FDA GRAS self-determination and USDA organic certification shape North American product development timelines, whereas EFSA evaluations under EU food additive reauthorization programs determine which oxidants retain market access. BIS standards in India and China's SAMR food safety registrations create divergent compliance pathways that fragment formulation strategies for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to decide whether regional SKU customization or global platform standardization delivers superior returns.
Market Dynamics
Clean-label reformulations under the EU Green Deal are compressing oxidant margins while fermentative biotechnology creates new premium ingredient categories that redefine competitive positioning.
Growth Catalysts
- Fermented Wheat Gluten Substitution:Artisan bakeries across Western Europe are replacing synthetic emulsifiers with bio-fermented alternatives to meet EU Green Deal additive reduction mandates.
- Enzyme Engineering Advances:Amylase and xylanase blends now enable frozen dough cryostability without DATEM or SSL declarations, expanding clean-label frozen bakery applications.
- Industrial Bakery Clustering:Munich and Stuttgart production hubs concentrate bulk oxidant procurement, creating economies of scale for improver blend suppliers serving continuous-mix operations.
Market Restraints
- Wheat Protein Supply Volatility:Drought cycles in North American grain belts destabilize gluten extraction yields, forcing improver manufacturers to absorb input cost swings or reformulate.
- EFSA Reauthorization Timelines:EU food additive review cycles extend 18-24 months, freezing formulation decisions for azodicarbonamide and other oxidants pending safety reassessment.
- Technical Performance Gaps:Ascorbic acid alternatives in clean-label systems fail to match oxidation speed in high-speed mixing, creating throughput losses industrial bakers resist absorbing.
Strategic Opportunities
- India BIS Standardization:Emerging bakery automation in Mumbai and Bangalore creates demand for enzyme-based improvers compliant with Bureau of Indian Standards food additive registrations.
- Dual Carbon Goals in China:SAMR registrations for fermented improvers align with national decarbonization targets, opening procurement channels for bio-processed ingredient systems.
- Sourdough Convergence:Combination of traditional fermentation with precision enzyme dosing creates hybrid improver categories capturing premium positioning in craft-industrial bakery segments.
Industry Challenges
- Bakery Technologist Scarcity:Industrialized markets face acute shortages of fermentation scientists and dough rheology specialists, constraining supplier technical service capacity.
- Legacy Equipment Retrofit Costs:Continuous-mix lines require sensor and dosing system upgrades to handle variable enzyme activity levels, demanding capital deployment bakeries defer.
- Cross-Jurisdiction Formulation Drift:Divergent FDA GRAS self-determination versus EFSA positive-list requirements force SKU proliferation, fragmenting production runs and diluting margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Dough Improver Market |
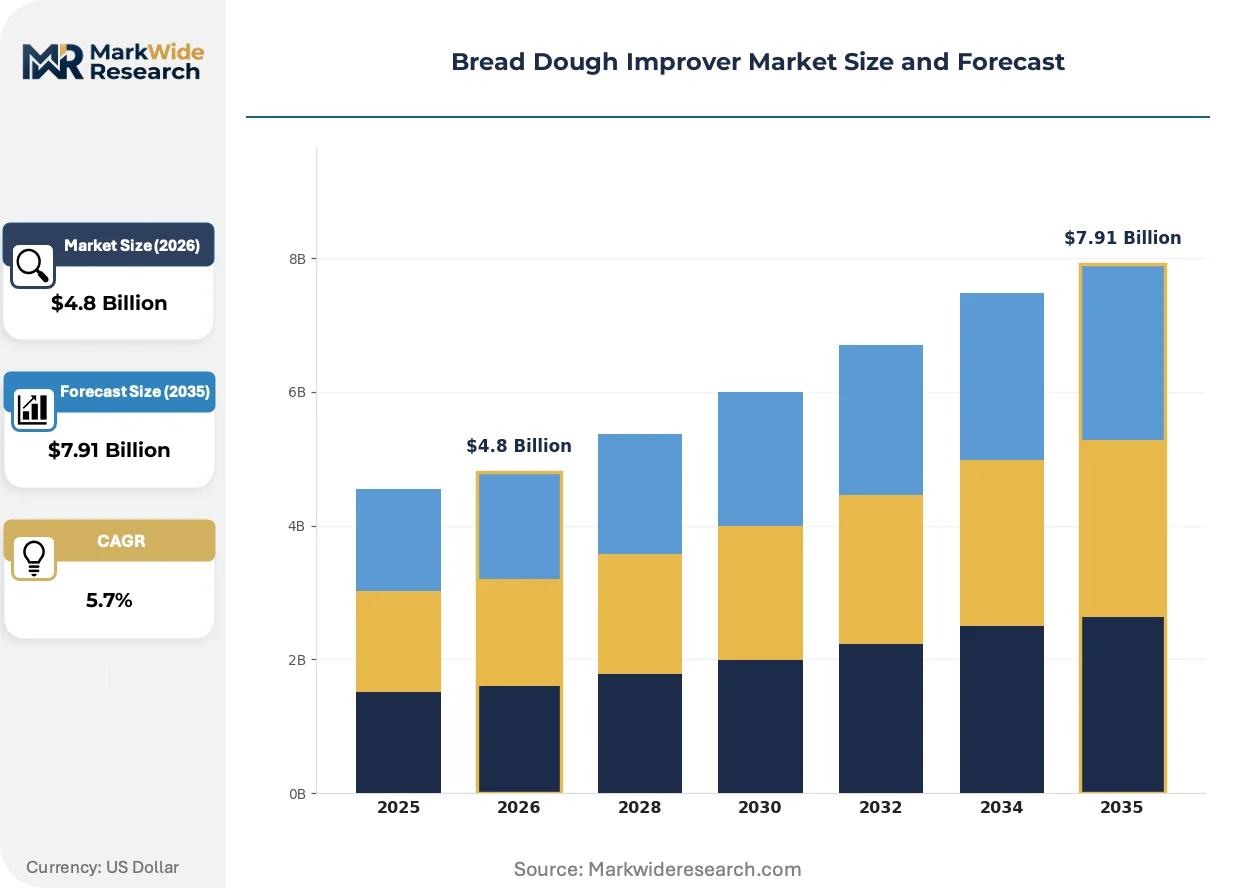
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Enzymes, Oxidants, Other Additives Application: Bakery Products, Breads, Pastries, Cakes End User: Commercial Bakeries, Artisan Bakeries, Home Bakers, Food Service Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Dawn Food Products, Corbion NV, AB Mauri, BreadPartners, Bakels Worldwide, Puratos Group, ADM, Cain Food Industries, Lesaffre et Compagnie SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Dough Improver Market Emerging Trajectories
Biotechnology and regulatory chemistry are converging to replace petrochemical-derived dough conditioners with fermentation-based functional systems that alter competitive boundaries.
Precision fermentation platforms for ascorbic acid production are fragmenting the oxidant supply base. Biotech startups and ingredient multinationals now compete to supply bakeries with non-synthetic alternatives that match chemical oxidation kinetics. Early adoption concentrates in German industrial clusters where EFSA pressure on synthetic additives is most acute, compressing commodity ascorbic acid pricing while premium fermented variants capture margin expansion.
REACH chemical registration requirements and EU Green Deal additive reduction targets are accelerating clean-label reformulation investments. Industrial bakeries face reformulation deadlines that force parallel qualification of enzyme-based replacements for emulsifier functions. Frozen dough specialists in Belgium and the Netherlands are most exposed, retrofitting production lines to handle enzyme-sensitive cryostability protocols ahead of 2027 regulatory milestones.
Buyer concentration among pan-European millers is consolidating procurement decisions into fewer technical gatekeepers. Large-scale flour suppliers now specify improver blends for captive bakery customers, displacing direct supplier relationships. This pattern is most visible in France and Germany where industrial bakery chains source through integrated milling operations, forcing ingredient vendors to secure miller partnerships rather than end-user contracts.
Bread Dough Improver Market Segmentation
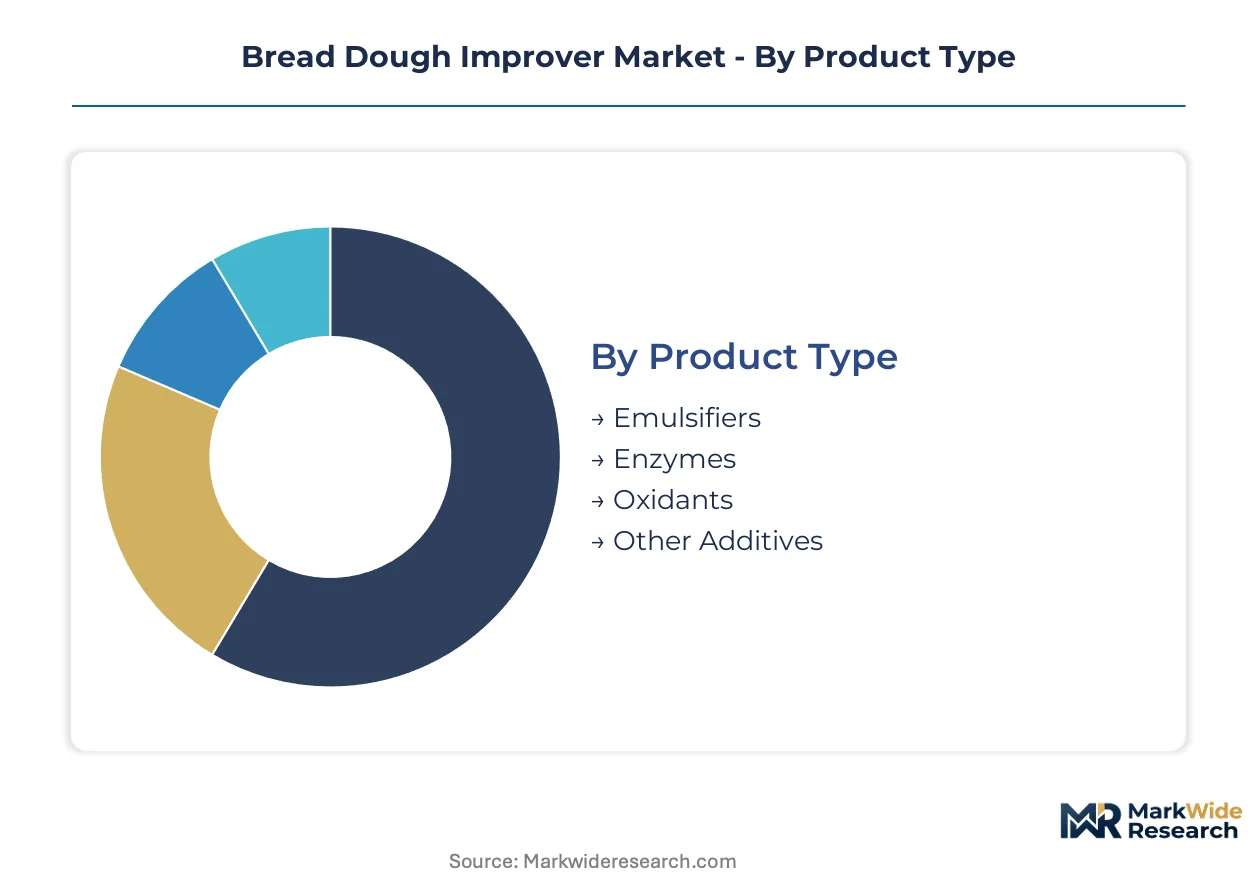
Segmentation in bread dough improvers reveals how functional chemistry, end-use requirements, and procurement channels fragment margin capture across the value chain. Suppliers must align formulation portfolios with distinct performance specifications and buyer concentration patterns.
Product Type:
Margin pools concentrate in enzyme systems where biotechnology differentiation commands premium pricing, while oxidant commoditization compresses returns.
- Emulsifiers:DATEM and SSL dominate frozen dough applications where cryostability prevents ice crystal damage during freeze-thaw cycles. Belgian and Dutch frozen bakery specialists drive bulk procurement despite clean-label reformulation pressure.
- Enzymes:Amylase and xylanase blends enable gluten network modification without synthetic additive declarations. German industrial clusters around Munich absorb expanding volumes as EFSA reauthorization timelines freeze azodicarbonamide usage.
- Oxidants:Ascorbic acid faces substitution from fermented alternatives under EU Green Deal mandates.
- Other Additives:Fermented wheat gluten and ascorbic acid alternatives capture emerging clean-label positioning.
The dominant share belongs to Enzymes, while Oxidants is closing the gap fastest through precision fermentation substitution.
Application:
Volume concentration tracks industrial automation intensity, with high-speed continuous-mix operations demanding standardized functional systems.
- Bakery Products:Pan-European millers specify improver blends for captive industrial bakery chains, consolidating procurement decisions into fewer technical gatekeepers.
- Breads:Artisan bakeries across Western Europe account for rising enzyme and fermented additive purchases as EU additive reduction mandates tighten.
- Pastries:Laminated dough applications require specialized emulsifier systems for fat distribution and layer integrity.
- Cakes:Aeration-focused formulations demand distinct emulsifier-enzyme combinations for crumb structure control.
Breads holds the largest volume position, though Bakery Products is expanding most quickly through miller-led consolidation.
End User:
Technical service requirements and formulation complexity create divergent margin structures across buyer sophistication levels.
- Commercial Bakeries:Industrial continuous-mix operations in Germany and France standardize on bulk oxidant blends and enzyme systems. These buyers demand fermentation science support that strains supplier technical service capacity amid technologist shortages.
- Artisan Bakeries:Western European craft producers drive fermented wheat gluten adoption for clean-label positioning. Their smaller scale limits direct supplier relationships, pushing purchases through specialty distributors.
- Home Bakers:Retail-format improver blends concentrate in supermarket and online channels.
- Food Service:Central kitchen operations require frozen dough stability solutions.
Commercial Bakeries commands the dominant revenue share, with Artisan Bakeries gaining ground fastest on clean-label conversion.
Distribution Channel:
Channel selection determines formulation standardization versus customization tradeoffs and working capital intensity.
- Direct Sales:Pan-European millers and industrial bakery clusters negotiate bulk oxidant and enzyme contracts with technical specification requirements. These relationships lock in volume commitments and technical service obligations.
- Online Retail:Home baker and small artisan purchases concentrate here, with specialty enzyme blends and clean-label alternatives expanding assortment depth.
- Supermarkets:Mass-market emulsifier and oxidant blends for consumer baking segments.
- Specialty Stores:Professional bakery supply outlets serve artisan segment technical consultation needs.
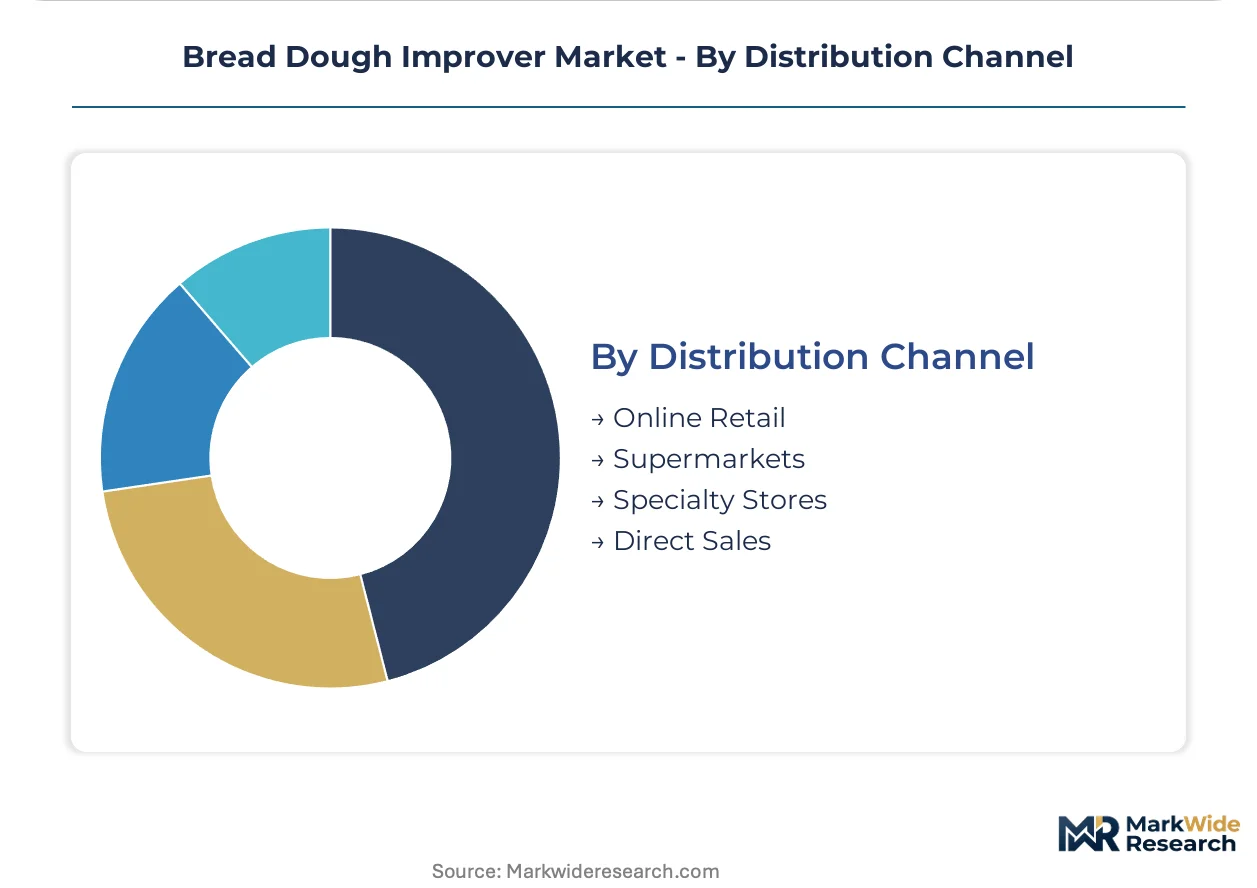
Direct Sales maintains the leading position, while Online Retail is climbing the fastest on small-buyer digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA reauthorization timelines anchor European regulatory gravity, while procurement clusters in Germany and France concentrate bulk oxidant demand. Divergent compliance pathways across FDA GRAS self-determination, China's SAMR registrations, and India's BIS standards fragment multinational formulation strategies.
Germany
Munich and Stuttgart industrial bakery clusters drive concentrated bulk procurement of oxidant blends and enzyme systems. EU Green Deal additive reduction mandates compress synthetic emulsifier margins while fermentative biotechnology gains regulatory preference. Bavarian continuous-mix operations absorb expanding volumes of precision-dosed enzyme improvers.
United States
FDA GRAS self-determination enables faster clean-label reformulation cycles than European regulatory timelines. North American grain origination controls wheat protein extraction yields that feed captive improver production. Industrial bakeries in the Midwest standardize on bulk emulsifier systems for high-speed frozen dough operations.
China
SAMR food safety registrations create distinct compliance pathways for fermented improver categories aligned with national dual carbon goals. Shandong Peninsula and Yangtze River Delta production hubs concentrate bakery automation investment demanding enzyme-based systems. Precision fermentation platforms for ascorbic acid alternatives attract domestic biotech capacity expansion.
India
BIS standards for food additive registrations shape emerging demand from Mumbai and Bangalore bakery automation projects. Central kitchen proliferation in food service channels drives frozen dough stability requirements. Domestic miller consolidation concentrates procurement decisions into fewer technical gatekeepers specifying improver blends.
France
Pan-European miller integration displaces direct supplier relationships through captive bakery chain sourcing. Île-de-France and Hauts-de-France industrial clusters face 2027 regulatory milestones for emulsifier reformulation. Artisan bakery density in regional markets accelerates fermented wheat gluten adoption for clean-label positioning.
Bread Dough Improver Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation science depth and grain origination control separating competitive positions. The upper tier captures bulk oxidant and enzyme contracts through pan-European miller relationships, while specialists anchor artisan segment distribution. Three archetypes dominate: biotechnology-integrated fermentation platforms, grain-origination-backed protein extractors, and sourdough-centered innovation systems. Capacity expansion in precision fermentation and strategic partnerships with industrial bakery clusters represent the dominant competitive vectors.
Within the biotechnology-integrated tier, Corbion NV and Puratos Group exemplify divergent geographic anchoring strategies. Corbion occupies a position tied to European fermentation science depth and enzyme supply relationships with industrial millers. Puratos sits within a global innovation center model spanning Belgian sourdough expertise and Asian market development. ADM represents the grain-origination archetype, with North American wheat protein extraction feeding captive improver production capacity. Lesaffre et Compagnie SA and AB Mauri anchor positions within yeast and fermentation-derived ingredient systems serving artisan and industrial channels respectively.
| Leading Market Players |
|---|
| Dawn Food Products |
| Corbion NV |
| AB Mauri |
| BreadPartners |
| Bakels Worldwide |
| Puratos Group |
| ADM |
| Cain Food Industries |
| Lesaffre et Compagnie SA |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German industrial bakery clusters and enzyme suppliers lock in multi-year supply access while compressing price visibility for spot-market buyers facing wheat protein volatility. These agreements concentrate procurement leverage among Munich and Stuttgart continuous-mix operators, forcing smaller artisan bakeries toward premium-tier fermented alternatives with less favorable unit economics.
Pricing Analysis
Geographic price spreads widen between German industrial clusters and peripheral EU markets, reflecting concentrated bulk procurement power. Three-tier pricing structure across premium fermented, standard enzyme-based, and economy chemical oxidant levels segments buyer access. Cost compression in commodity ascorbic acid is intensifying because precision fermentation platforms fragment supply bases. Industrial continuous-mix buyers exhibit lowest price sensitivity due to throughput guarantees, while artisan bakeries face acute margin pressure from clean-label reformulation mandates.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors elevates inbound logistics costs for emulsifier raw materials, compressing margins on DATEM and SSL shipments. Supply concentrates in Belgium, the Netherlands, and Germany for emulsifier production, while enzyme manufacturing draws from Danish and German fermentation science clusters. Wheat protein extraction hinges on North American grain belt harvest cycles, creating single-source vulnerability during drought periods. Distribution runs through pan-European miller networks that displace direct supplier relationships with captive bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation science depth represents the critical capability gap constraining supplier technical service capacity and fragmenting competitive positions across industrial and artisan channels.
For Market Incumbents: Consolidate miller partnership networks to defend bulk oxidant contract positions against biotechnology entrants offering precision-fermented alternatives. Secure backward integration into wheat protein extraction to buffer input cost swings from North American grain belt volatility. Deepen technical service teams with dough rheology specialists to offset acute bakery technologist scarcity constraining supplier support capacity. For New Entrants and Emerging Players: Technical consultation gaps in artisan bakery distribution channels create white-space entry points where incumbents under-serve smaller-scale clean-label converters. Target Western European craft-industrial hybrid segments with hybrid sourdough-enzyme dosing systems that capture premium positioning. Deploy direct-to-artisan digital platforms bypassing legacy specialty distributor markups. For Investors and Strategic Acquirers: Biotechnology-anchored fermentation platforms with existing EFSA-compliant product pipelines represent the most defensible acquisition archetype for long-term viability within a five-to-ten-year window. Monitor EFSA reauthorization timelines for azodicarbonamide as the critical inflection signal determining oxidant segment restructuring intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Builds non-synthetic ascorbic acid supply aligned with EU Green Deal additive reduction mandates. |
| Miller Partnership Consolidation | Secures procurement gatekeeper relationships displacing direct supplier access to industrial bakery chains. |
| Clean-Label Certification Investment | Enables EFSA-compliant positioning for enzyme-based systems replacing synthetic emulsifier declarations. |
| Artisan Distribution Channel Development | Captures fermented wheat gluten demand from Western European craft bakery clean-label conversion. |
| Backward Integration into Wheat Protein | Reduces exposure to North American grain belt drought cycles destabilizing gluten extraction yields. |
Methodological Framework
Operator-level perspectives from bakery technologists, flour mill procurement leads, fermentation science directors, and industrial production managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from EFSA additive reauthorization filings, EU Green Deal policy documentation, BIS and SAMR registration databases, and trade flow records through Rotterdam-Antwerp chemical corridors. Bottom-up volume estimates from ingredient supplier shipments and top-down consumption models from pan-European milling operations were triangulated to reconcile segmentation outputs.
Sensitivity analysis tested forecast robustness across wheat protein price volatility scenarios, EFSA reauthorization delay assumptions, and enzyme adoption rate variations. The analytical framework modeled product type, application, end user, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of clean-label reformulation penetration and industrial automation intensity. Forecast inputs incorporated precision fermentation platform deployment timelines and bakery technologist supply constraints.
Forecasts assume regulatory continuity in EFSA reauthorization programs, FDA GRAS self-determination pathways, and SAMR food additive registration regimes; material policy shifts would require re-modeling. Wheat belt drought frequency, biotechnology scale-up delays, and miller consolidation pace represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Fortified Bakery Market
Bakery Products
Global Cake Mix Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Bakery Cases Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Bread Improver Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Muffins Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Organic Bread Flour Market
Bakery Products
India Cake Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Soft Biscuit Market