
 Shelf-Stable Dough Market | 2026-2036
Shelf-Stable Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf-Stable Dough Market Analytics
North American production capacity is tilting toward ambient-stable formulations as manufacturers retrofit lines for extended-shelf-life outputs. General Mills leverages its milling-to-retail infrastructure to sustain cost advantages across multiple dough formats. Pillsbury anchors the refrigerated-to-shelf-stable transition with reformulated enzyme systems that preserve texture without cold-chain requirements. Nestlé competes through global procurement networks that control input costs for emulsifiers and preservatives.
Shelf-stable dough comprises flour-based formulations processed with controlled water activity, pH modulation, and antimicrobial packaging to achieve ambient storage stability of six to eighteen months without refrigeration, serving retail and foodservice channels requiring inventory flexibility and reduced spoilage exposure. Refrigerated dough occupies the dominant revenue position due to entrenched consumer familiarity and established retail slotting, while par-baked dough captures the fastest expansion as quick-service restaurants adopt thaw-and-finish protocols to reduce labor and equipment footprints. Plastic pouches command margin pools through lightweighting benefits and barrier-layer innovations that extend shelf life without metal can costs.
The FDA governs acidified food regulations and pathogen-control standards that directly shape formulation chemistry and validation protocols for ambient dough products. USDA oversight of grain-based ingredients intersects with EPA packaging-waste directives to influence material selection and end-of-life claims across the supply base. Stakeholders must monitor evolving state-level extended producer responsibility laws and federal clean-label guidance that could recalibrate preservative thresholds and disclosure requirements.
Market Dynamics
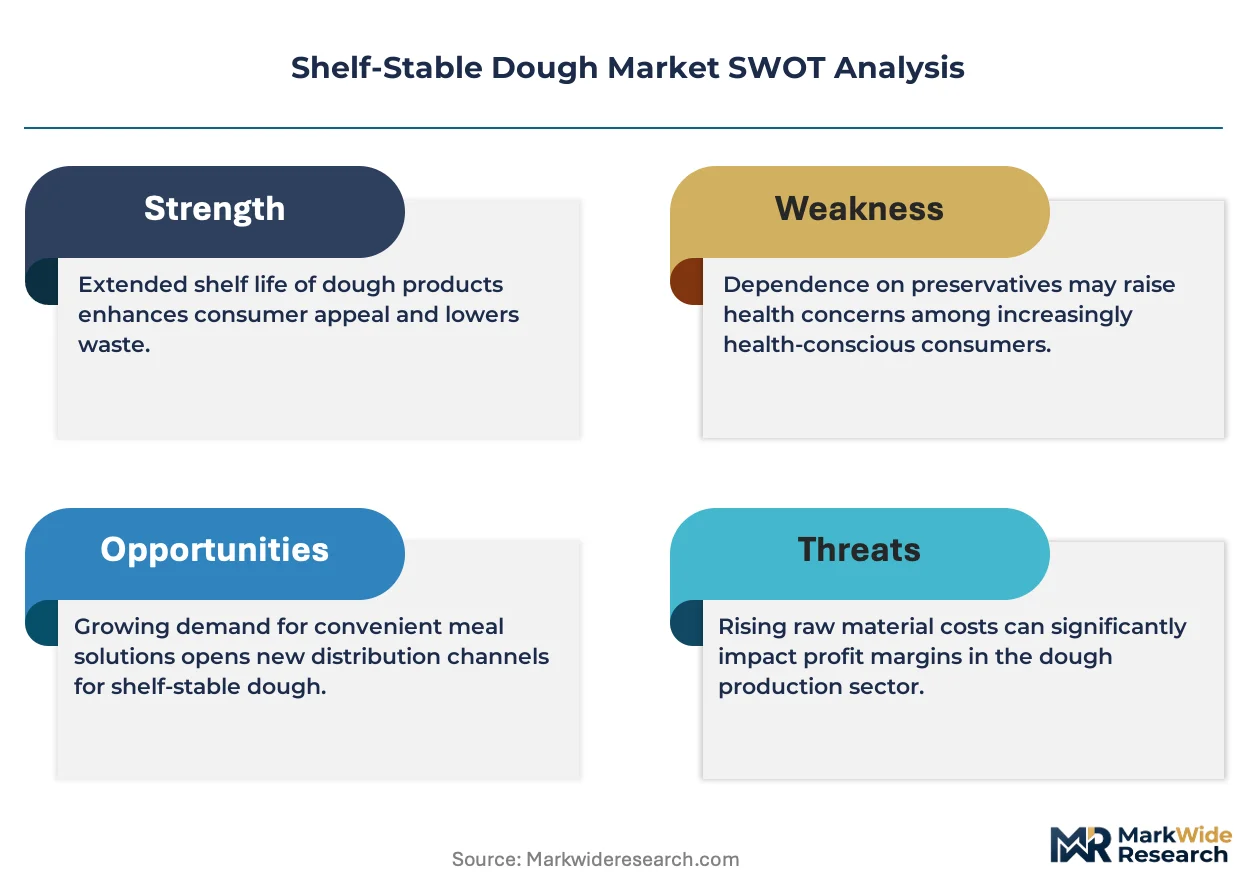
Formulation chemistry is the central force reshaping competitive position, as manufacturers reengineer water activity and pH parameters to satisfy FDA acidified food standards while eliminating cold-chain dependency.
Growth Catalysts
- Quick-service restaurant thaw-and-finish protocols:Par-baked formats reduce labor and equipment footprints for operators seeking speed-to-oven efficiency.
- FDA Food Safety Modernization Act pathogen controls:Ambient-stable validation protocols create formulation barriers that favor capitalized incumbents with testing infrastructure.
- Emulsifier and preservative cost arbitrage:Global procurement networks for input chemicals compress unit economics versus regional sourcing models.
Market Restraints
- Wheat and specialty grain input volatility:Concentrated sourcing from drought-exposed growing regions exposes margin compression during supply shocks.
- Barrier-layer packaging resin concentration:Petrochemical feedstock dependence ties cost structures to crude derivative markets with limited hedging instruments.
- Clean-label disclosure thresholds:Pending federal guidance on preservative labeling creates formulation uncertainty ahead of compliance deadlines.
Strategic Opportunities
- India foodservice channel penetration:Cold-chain infrastructure gaps in tier-two cities create addressable white space for ambient-stable formats.
- Extended producer responsibility packaging mandates:State-level laws in California and New York incentivize recyclable mono-material pouch development.
- Enzyme-microencapsulation convergence:Controlled-release biotechnology enables texture preservation with reduced chemical preservative loads.
Industry Challenges
- Food microbiology validation timelines:Accelerated shelf-life testing protocols strain laboratory capacity and extend new product introduction cycles.
- Legacy refrigerated distribution integration:Cold-chain operators retrofitting for ambient storage face warehouse management system reconfiguration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf-Stable Dough Market |
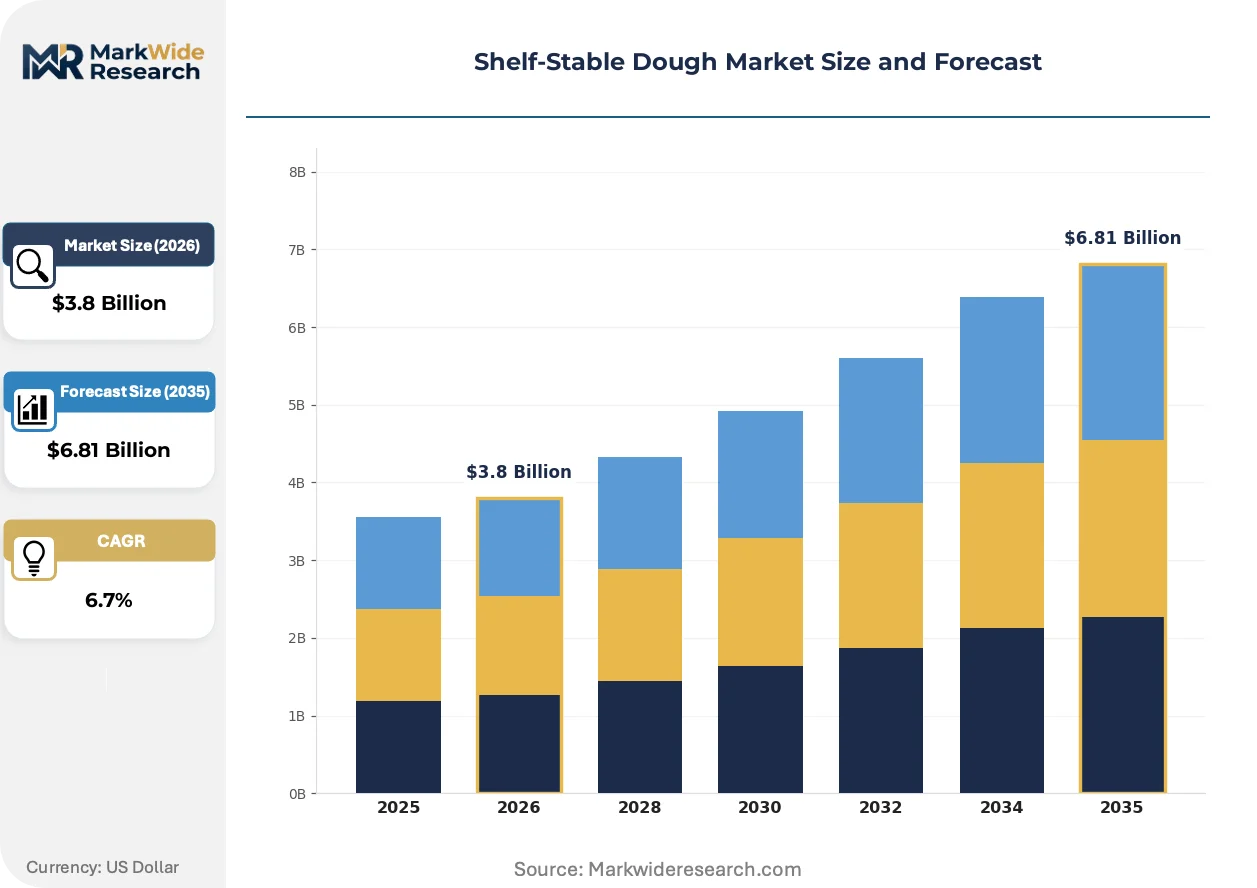
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Dough, Frozen Dough, Par-Baked Dough, Pre-Baked Dough Packaging Type: Plastic Pouches, Cans, Boxes, Resealable Bags End User: Households, Restaurants, Bakeries, Catering Services Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Hungryroot, Taste of Nature, Midland Cookie Dough, General Mills, Neighbors Cookie Dough, Doughlish, Eventful Sweets, Pillsbury, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf-Stable Dough Market Evolving Landscape
Active and intelligent packaging systems are redefining shelf-life extension, moving beyond passive barrier layers toward real-time quality monitoring and responsive preservation chemistry.
Controlled-atmosphere packaging with embedded oxygen scavengers is collapsing the traditional trade-off between shelf duration and ingredient simplicity. Quick-service restaurant procurement teams are specifying these formats for back-of-house inventory reduction. The technology compresses spoilage risk premiums previously priced into ambient distribution contracts.
EPA packaging-waste directives intersect with state extended producer responsibility frameworks to mandate recyclable mono-material structures. Manufacturers are reformulating multilayer pouches into polyethylene-only constructions with equivalent moisture barriers. Foodservice distributors in California and New York are prioritizing suppliers with verified end-of-life pathways.
Centralized commissary procurement is compressing direct-store-delivery relationships for ambient dough. National bakery chains are consolidating purchasing through cooperative buying organizations with specification authority. This concentration is most visible in the United States, where retail slotting fees and volume rebates favor scaled suppliers with national distribution density.
Shelf-Stable Dough Market Segmentation
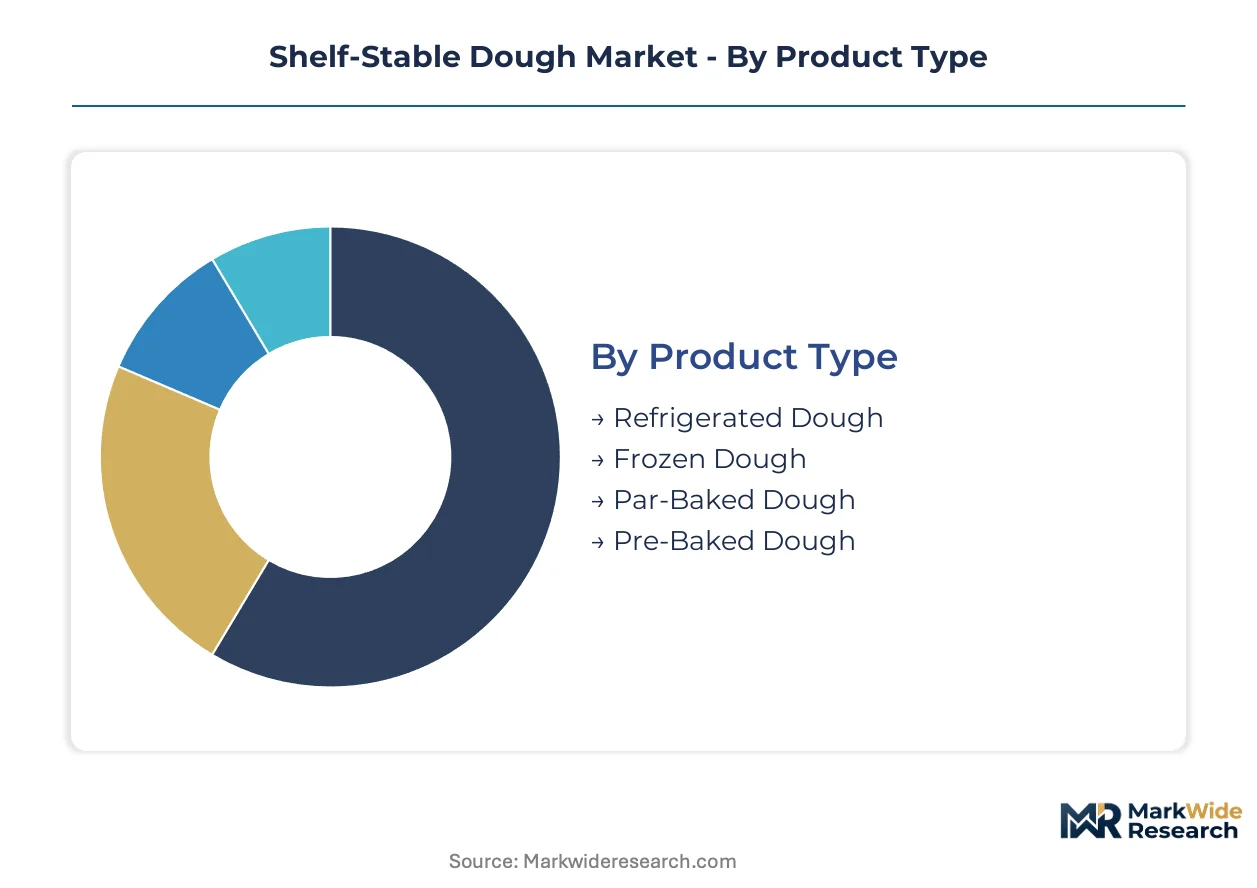
Segmentation in shelf-stable dough reveals divergent velocity profiles across product formats, with inventory turns varying by an order of magnitude between par-baked and frozen categories. Understanding these cycle-time differentials enables capacity planning and margin protection across volatile input cost environments.
Product Type:
Par-baked dough turns inventory fastest through quick-service restaurant channels, while frozen dough sits longest in warehouse rotation due to extended thaw protocols and batch production scheduling.
- Refrigerated Dough:Formulations requiring continuous cold-chain maintenance from production through retail display. Household penetration in the United States sustains volume concentration despite energy-intensive distribution requirements and spoilage exposure at temperature excursion points.
- Par-Baked Dough:Partially baked products finished at point of service. Restaurant chains in the United States specify these formats for labor reduction and equipment footprint compression, with thaw-and-finish protocols collapsing time-to-oven versus scratch preparation.
- Frozen Dough:Blast-frozen formulations with extended storage windows. Bakeries with irregular demand patterns favor this format for production flexibility.
- Pre-Baked Dough:Fully baked products requiring only warming or ambient staging. Catering services specify these for event logistics simplification.
Refrigerated dough dominates installed base. Par-baked dough is where expansion concentrates.
Packaging Type:
Cost tier stratification separates commodity metal formats from engineered flexible structures with active barrier layers.
- Plastic Pouches:Multilayer or mono-material flexible structures with moisture and oxygen barriers. California and New York foodservice distributors prioritize suppliers with verified polyethylene-only constructions meeting extended producer responsibility mandates.
- Cans:Metal cylindrical containers with double-seamed closures. Established retail slotting in the United States sustains volume despite material cost volatility and recycling friction.
- Boxes:Paperboard secondary packaging with primary film liners. Wholesale channels favor these for palletization efficiency.
- Resealable Bags:Zipper-equipped flexible structures with oxygen scavenger integration. Household segment demand concentrates here for portion control and storage convenience.
Plastic pouches command margin premiums through lightweighting benefits. Resealable bags with active barriers are gaining share fastest.
End User:
Application intensity varies from high-frequency household consumption to event-driven catering procurement with lumpy demand patterns.
- Restaurants:Commercial foodservice operators with standardized preparation protocols. Quick-service chains in the United States drive par-baked specification for speed-to-oven efficiency and labor cost containment.
- Bakeries:Production facilities and retail operators seeking operational flexibility without cold-chain dependency. FDA Food Safety Modernization Act compliance investments favor capitalized operators with ambient-stable validation infrastructure.
- Households:Individual consumers purchasing through retail channels. Convenience-oriented behavior in the United States sustains category expansion.
- Catering Services:Event-based food providers with intermittent volume spikes. Pre-baked formats reduce on-site equipment requirements.
Restaurants anchor volume concentration. Bakeries represent the steepest expansion trajectory as operators retrofit for ambient-stable formats.
Distribution Channel:
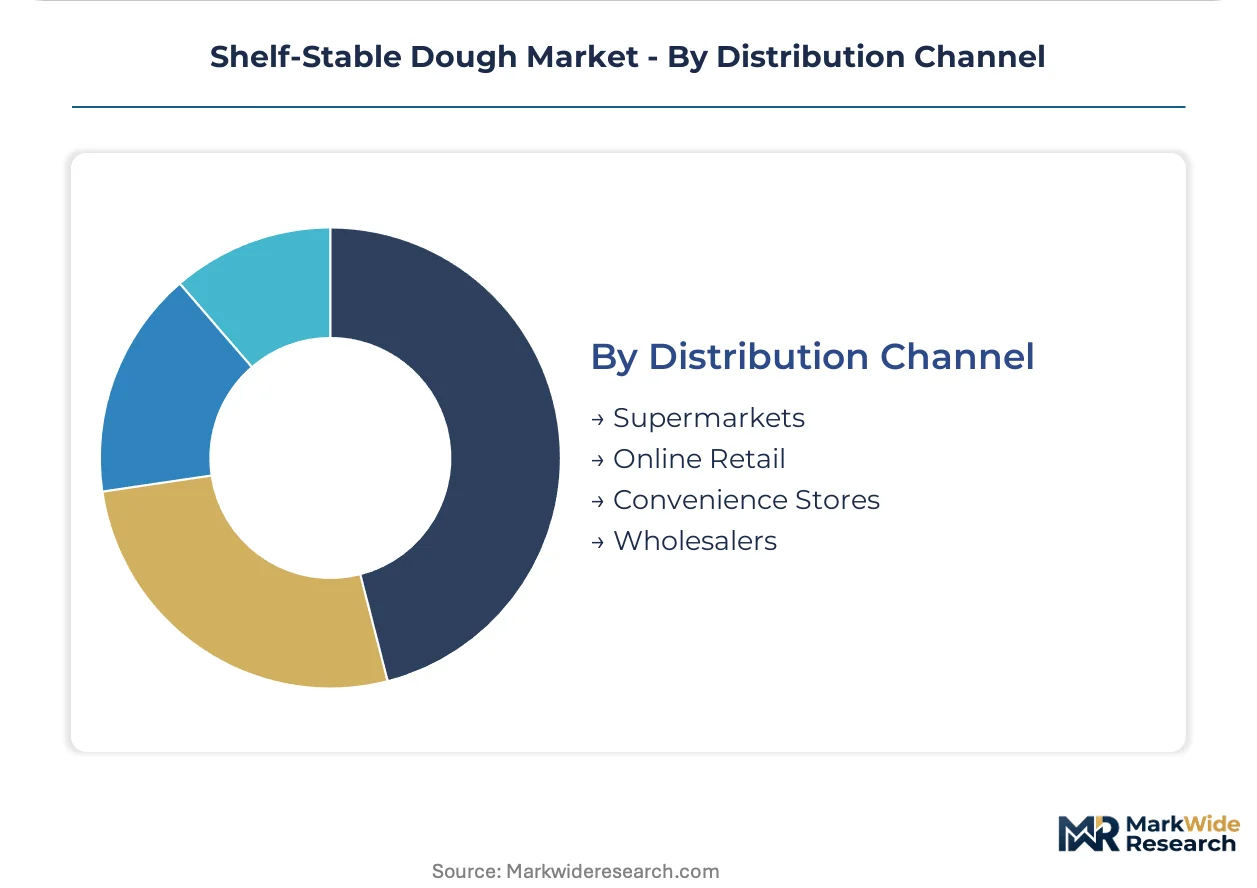
Customer type separates high-volume wholesale procurement from fragmented convenience store replenishment.
- Supermarkets:Full-service retail with refrigerated and ambient shelf allocation. Slotting fee structures in the United States favor scaled suppliers with national distribution density.
- Wholesalers:Business-to-business distributors serving foodservice accounts. Cooperative buying organizations consolidate purchasing power for bakery chains.
- Online Retail:Direct-to-consumer and B2B platforms with ambient shipping protocols. Packaging durability requirements differ from retail-display specifications.
- Convenience Stores:Limited-assortment retail with rapid inventory turns. Shelf-stable formats reduce spoilage risk in temperature-variable environments.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA acidified food regulations anchor the United States as the dominant geography, where retail infrastructure and convenience-oriented consumer behavior sustain category expansion. Demand concentrates in markets with established ambient distribution networks and foodservice procurement sophistication.
United States
Quick-service restaurant chains and bakery cooperatives drive par-baked dough specification for labor reduction and speed-to-oven efficiency. FDA Food Safety Modernization Act pathogen-control standards reshape formulation chemistry and validation protocols nationwide. Chicago and Minneapolis-St. Paul host milling-to-retail infrastructure that General Mills leverages for cost advantages across multiple dough formats.
Germany
Industrial bakeries seek operational flexibility without cold-chain dependency as energy costs pressure refrigerated distribution economics. EFSA guidance on clean-label preservatives influences disclosure thresholds and consumer-facing ingredient panels. The Munich-Stuttgart corridor concentrates reformulation expertise for enzyme-microencapsulation technologies that reduce chemical preservative loads.
India
Cold-chain infrastructure gaps in tier-two cities create addressable white space for ambient-stable formats in foodservice channels. FSSAI standards for acidified foods and antimicrobial packaging establish compliance baselines for multinational entrants. Bangalore and Hyderabad anchor quick-service restaurant expansion where thaw-and-finish protocols reduce back-of-house equipment requirements.
Japan
Convenience store chains with rapid inventory turns favor shelf-stable formats to minimize spoilage risk in temperature-variable environments. METI packaging-waste directives intersect with corporate sustainability commitments to mandate recyclable mono-material structures. The Osaka-Kobe industrial zone concentrates active barrier film manufacturing for oxygen-scavenger integration into resealable pouch formats.
Brazil
Wholesale distributors serving bakery chains consolidate purchasing through cooperative buying organizations with specification authority. ANVISA regulations on food additives and preservatives shape formulation chemistry for ambient-stable validation. São Paulo state hosts the largest concentration of foodservice procurement teams specifying par-baked formats for equipment footprint compression.
Shelf-Stable Dough Market Competitive Landscape
Integrated milling-to-retail conglomerates and specialized dough formulators split the market into distinct capability tiers. Capital requirements for FDA-compliant validation infrastructure favor scaled incumbents with testing laboratories and ambient-stable formulation expertise. Three archetypes dominate: diversified food conglomerates with backward integration into grain sourcing, specialist dough manufacturers with enzyme-biotechnology partnerships, and private-label suppliers serving retail channel consolidation. Competitive moves concentrate on capacity expansion for par-baked output and strategic partnerships for controlled-release preservation technologies.
Within the diversified conglomerate tier, General Mills and Nestlé occupy positions defined by global procurement networks and milling infrastructure. Pillsbury anchors the refrigerated-to-shelf-stable transition archetype, representing reformulated enzyme system capabilities that preserve texture without cold-chain requirements. These three exemplify how capitalized incumbents leverage testing infrastructure to satisfy evolving acidified food standards while compressing unit economics through input cost control.
| Leading Market Players |
|---|
| Hungryroot |
| Taste of Nature |
| Midland Cookie Dough |
| General Mills |
| Neighbors Cookie Dough |
| Doughlish |
| Eventful Sweets |
| Pillsbury |
| Nestlé |
| Others |
Value Network & Pricing Analysis
Chicago-Minneapolis freight corridors set the baseline for regional price spreads, compressing margins for distributors lacking backward integration into grain sourcing while enabling tiered pricing power for milling-to-retail conglomerates with captive logistics networks.
Pricing Analysis
Geographic price spreads between coastal and inland markets exceed fifteen percent for par-baked formats, reflecting cold-chain avoidance premiums. Three-tier pricing structure across premium enzyme-microencapsulated, standard acidified, and economy preservative-heavy tiers separates formulation sophistication levels. Cost compression in economy tiers is intensifying because wheat input volatility and resin barrier-layer costs are transferring downstream. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to labor-cost trade-off calculations, while convenience store operators show highest sensitivity to per-unit packaging costs.
Supply Chain Analysis
Tariff exposure between the United States and petrochemical-exporting regions dominates input cost volatility for multilayer pouch structures. Manufacturing concentrates in the United States, Germany, and Japan for active barrier film production, with formulation chemistry expertise clustering in the Midwest United States and Munich-Stuttgart corridor. Raw material dependencies center on North American hard red winter wheat, Southeast Asian emulsifier feedstocks, and Gulf Coast petrochemical derivatives. Single-source vulnerability in oxygen-scavenger additive supply creates chokepoint risk. Distribution runs through cooperative buying organizations consolidating bakery chain procurement with specification authority over national foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-compliant ambient-stable validation infrastructure separates capitalized incumbents from regional formulators unable to absorb laboratory capacity investments, creating consolidation pressure as compliance timelines compress.
For Market Incumbents: Harden formulation chemistry capabilities through enzyme-microencapsulation partnerships that reduce preservative loads ahead of federal clean-label guidance. Expand par-baked production capacity in Chicago-Minneapolis corridor to capture quick-service restaurant procurement consolidation. These moves defend against private-label suppliers leveraging retail channel concentration to undercut branded positioning. For New Entrants and Emerging Players: Pursue tier-two Indian cities where cold-chain infrastructure gaps create addressable white space for ambient-stable foodservice formats. Target bakery cooperatives seeking operational flexibility without refrigerated distribution investments. A specification-selling approach through cooperative buying organizations offers faster traction than direct retail slotting fee competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist dough manufacturers with controlled-release biotechnology partnerships over diversified conglomerates with legacy refrigerated infrastructure. Long-term viability hinges on enzyme-microencapsulation convergence enabling texture preservation with reduced chemical loads. The signal to watch is state-level extended producer responsibility enforcement accelerating mono-material pouch adoption and filtering suppliers without verified end-of-life pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Microencapsulation Partnership | Controlled-release biotechnology reduces preservative loads while satisfying FDA acidified food standards. |
| Mono-Material Pouch Development | California and New York extended producer responsibility mandates favor polyethylene-only recyclable structures. |
| Par-Baked Capacity Expansion | Quick-service restaurant thaw-and-finish protocols drive fastest-expanding product format demand. |
| Cooperative Buying Organization Integration | National bakery chain procurement consolidation rewards suppliers with specification authority and national density. |
| Ambient-Stable Validation Infrastructure Investment | FDA Food Safety Modernization Act compliance creates formulation barriers favoring capitalized testing laboratories. |
Research Methodology
A spread of perspectives from bakery operations directors, quick-service restaurant procurement managers, foodservice distributor category buyers, and enzyme biotechnology R&D leads converged on the working assumptions shaping demand trajectories. Primary fieldwork with these stakeholders combined with secondary validation against FDA guidance documents, USDA grain market reports, EPA packaging-waste directives, and state-level extended producer responsibility legislation. Bottom-up segment sizing across product format, packaging type, end user, and distribution channel triangulated against top-down market value estimates derived from milling capacity and retail velocity data.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeling incorporating product format sophistication tiers, packaging barrier-layer specifications, end-user application intensity, and regional regulatory cluster variations. CAGRs emerged from trajectory fitting to historical velocity patterns and elasticity-adjusted demand projections. Industry-specific forecast inputs included quick-service restaurant back-of-house equipment footprint reduction targets and cooperative buying organization procurement consolidation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by private-label suppliers or accelerated FDA enforcement timelines would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Slicer Blades Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Laminated Dough Market
Bakery Products
Cake Concentrate Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Ice Cream Market
Bakery Products
Fondant Market
Bakery Products
United States Bread Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Muffins Market