
 Frozen Dough Market | 2026-2036
Frozen Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Dough Market Intelligence
The capital-intensity divergence between large-scale industrial producers and regional specialists is redrawing competitive boundaries in frozen dough manufacturing. Europastry leverages automated production lines across multiple European facilities to sustain cost leadership in bread and pastry dough. Aryzta AG anchors its position through deep European food service relationships, while Grupo Bimbo dominates Latin American retail channels with extensive distribution infrastructure.
Frozen dough comprises wheat-based formulations, leavening agents, and stabilizers that manufacturers pre-mix, portion, and flash-freeze at temperatures below minus eighteen degrees Celsius for later baking. Industrial users deploy these products to reduce labor costs, minimize waste, and standardize output across decentralized kitchen operations. Bread and pizza crust categories command the largest volume share due to universal food service penetration, while pastry and cookie dough segments generate higher margin pools through premium positioning in retail and bakery channels. Ready-to-bake and partially baked forms attract diverging buyer profiles, with food service operators favoring speed-to-oven solutions and retail consumers accepting longer preparation cycles.
The FDA's Food Safety Modernization Act preventive controls rule and the USDA's oversight of egg-containing dough formulations elevate compliance thresholds for cross-border suppliers. EU REACH chemical standards and EFSA food contact material regulations further constrain formulation choices for exporters serving European food manufacturers and retailers. Stakeholders must monitor evolving allergen labeling mandates and cold-chain integrity requirements as regulatory fragmentation intensifies between major consuming regions.
Market Dynamics
The frozen dough sector is restructuring around preventive control mandates that elevate fixed-cost thresholds for smaller manufacturers while rewarding capital-intensive automation at scale. FDA's updated Food Safety Modernization Act rules on hazard analysis and preventive controls are compressing the viable producer base.
Growth Catalysts
- Quick-service restaurant standardization:Chain operators deploy frozen dough to eliminate batch-to-batch variation across hundreds of outlets. This operational discipline reduces training overhead and waste.
- Commercial bakery automation:Automated mixing, portioning, and flash-freezing lines cut labor costs per unit while tightening temperature control below minus eighteen degrees Celsius.
- EU REACH compliance infrastructure:European manufacturers that invested early in chemical safety documentation now capture export contracts from suppliers caught unprepared by EFSA food contact material rules.
Market Restraints
- Wheat price volatility:Input cost swings compress margin predictability for producers locked into annual food service contracts with fixed pricing terms.
- Cold-chain concentration:Third-party logistics providers with sub-zero warehousing capacity cluster in the United States and Western Europe, leaving emerging markets underserved.
- Fresh dough substitution:Artisan bakery concepts and in-house mixing programs at regional restaurant groups erode penetration in premium positioning tiers.
Strategic Opportunities
- India food service expansion:Quick-service pizza and bakery chains in Mumbai and Bangalore lack reliable frozen dough suppliers with HACCP-certified production.
- Clean-label enzyme systems:Novel stabilizer technologies replace chemical conditioners, opening premium retail placement in European markets with strict EFSA additive scrutiny.
- Direct-to-bakery distribution:Bypassing traditional broadline distributors, manufacturers build captive delivery networks to independent bakeries seeking technical support.
Industry Challenges
- Preventive control qualified individual shortage:FDA mandates require on-staff experts to oversee hazard plans, but experienced candidates command salaries that strain mid-tier producers.
- Legacy ERP integration:Track-and-trace requirements for lot-level recall capability force expensive upgrades to manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Dough Market |
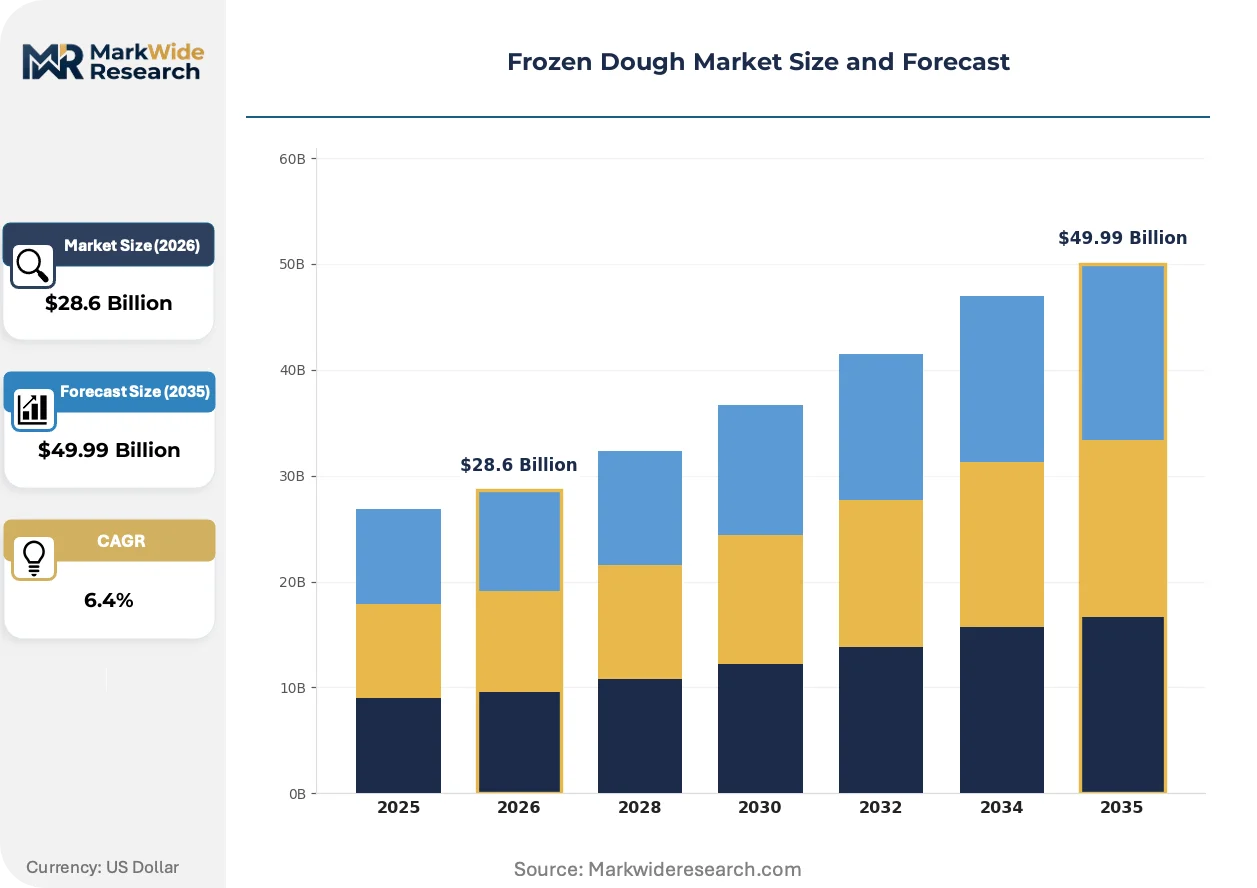
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pizza Crust, Pastry, Cookie Dough End User: Food Service, Retail, Bakery, Restaurants Form: Ready-to-Bake, Partially Baked, Frozen Dough Balls, Sheet Dough Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales |
| Companies Covered | Europastry, Rich Products Corporation, Aryzta AG, Flowers Foods, Inc., Conagra Brands, Inc., General Mills, Inc., Lantmännen Unibake International, Vandemoortele, Grupo Bimbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Dough Market Strategic Shifts & Innovations
Refrigeration technology and regulatory data infrastructure are converging to reshape how frozen dough moves from production line to oven. Manufacturers that master temperature integrity documentation and rapid-thaw formulations are capturing disproportionate share in contract negotiations.
Advanced cryogenic freezing using liquid nitrogen is supplanting mechanical blast freezing in high-throughput facilities. Pizza crust producers with volumes exceeding ten thousand units daily adopt nitrogen tunnels to minimize ice crystal formation and preserve gluten structure. This capital-intensive shift is compressing the viable producer base to operators with balance sheet capacity for seven-figure equipment deployments.
EU REACH chemical registration deadlines and EFSA food contact material restrictions are forcing reformulation of long-established dough conditioners. Manufacturers serving European retail channels must document safety profiles for every additive at concentrations above 0.1 percent. Bread and pastry dough exporters to Germany and France are accelerating substitution of azodicarbonamide and other contested conditioners with enzyme-based alternatives.
Food service procurement teams are consolidating supplier rosters and demanding real-time temperature monitoring data across frozen dough shipments. Broadline distributors that cannot provide blockchain-verified cold-chain records are losing placement at multi-unit restaurant chains. This specification tightening is most visible in the United States, where Aramark, Compass Group, and Sodexo have centralized sourcing decisions at corporate headquarters with dedicated quality audit teams.
Frozen Dough Market Segmentation
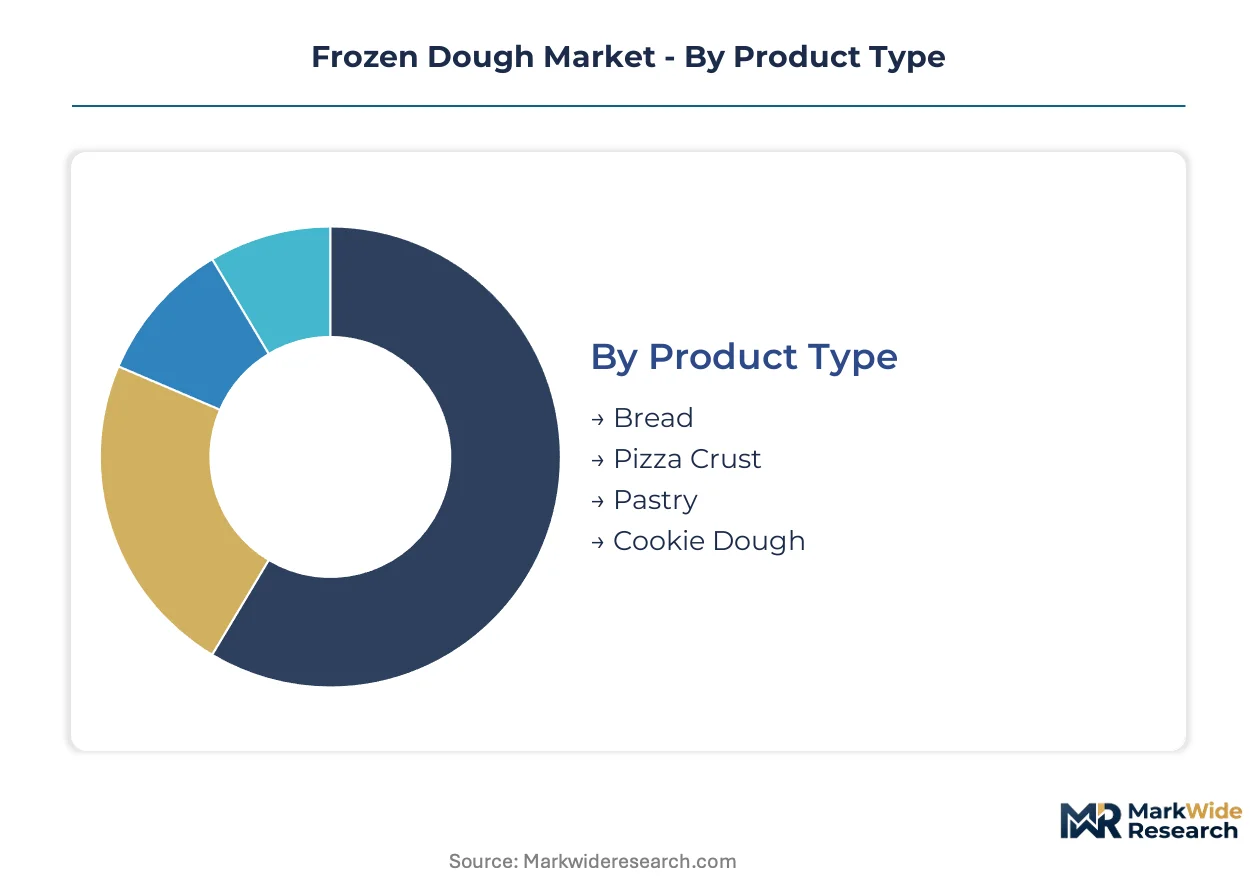
Frozen dough manufacturers configure production assets around four distinct segmentation axes. Each axis carries divergent margin profiles, regulatory exposure, and capital intensity requirements that determine viable competitive positioning.
Product Type:
FDA preventive controls and EFSA additive scrutiny create divergent compliance burdens across formulations, with wheat-based and egg-containing products facing distinct hazard analysis protocols.
- Bread:High-hydration wheat formulations with extended fermentation profiles dominate institutional food service procurement. Automated production lines in the United States process bread dough at volumes exceeding ten thousand units daily for quick-service sandwich chains.
- Pizza Crust:Low-moisture formulations optimized for cryogenic freezing preserve gluten structure through rapid temperature drop. Pizza Hut and Domino's supply agreements in India concentrate demand for HACCP-certified production with specified thickness tolerances.
- Pastry:Laminated butter doughs carry premium positioning in European retail channels.
- Cookie Dough:Egg-containing formulations trigger USDA oversight and elevated allergen labeling requirements.
Established volume favors Bread; emerging adoption favors Pizza Crust.
End User:
Customer procurement sophistication determines specification stringency, with centralized chain purchasing demanding real-time temperature documentation that fragments the supplier base.
- Food Service:Broadline distributors and contract food service operators source frozen dough for operational standardization across decentralized kitchen footprints. Aramark and Compass Group consolidated sourcing decisions at corporate headquarters with dedicated quality audit teams.
- Retail:Supermarket private-label programs and branded freezer-aisle placement drive volume through consumer convenience positioning. Clean-label enzyme systems replace chemical conditioners to satisfy EFSA additive scrutiny in Germany and France.
- Bakery:Independent operators seek technical support and smaller batch flexibility.
- Restaurants:Regional chains balance speed-to-oven requirements against artisan positioning.
Food Service commands current volume concentration; Retail exhibits the steepest expansion trajectory through premium positioning.
Form:
Processing stage at freezing point determines thaw-cycle requirements and oven-ready speed, creating diverging equipment investments across production facilities.
- Ready-to-Bake:Fully proofed dough portions move directly from freezer to oven, eliminating labor-intensive preparation steps. Quick-service operators in Mumbai and Bangalore favor this format for pizza and bakery applications where kitchen space constrains in-house mixing capacity.
- Partially Baked:Par-baked products require final oven finish but extend shelf stability and reduce shipping weight. European food service channels deploy par-baked bread for on-premise finishing that simulates artisan output.
- Frozen Dough Balls:Portioned but unproofed units demand controlled thaw environments.
- Sheet Dough:Industrial bakeries process bulk sheets for custom cutting and shaping.
Ready-to-Bake anchors food service penetration; Partially Baked gains share in premium retail positioning.
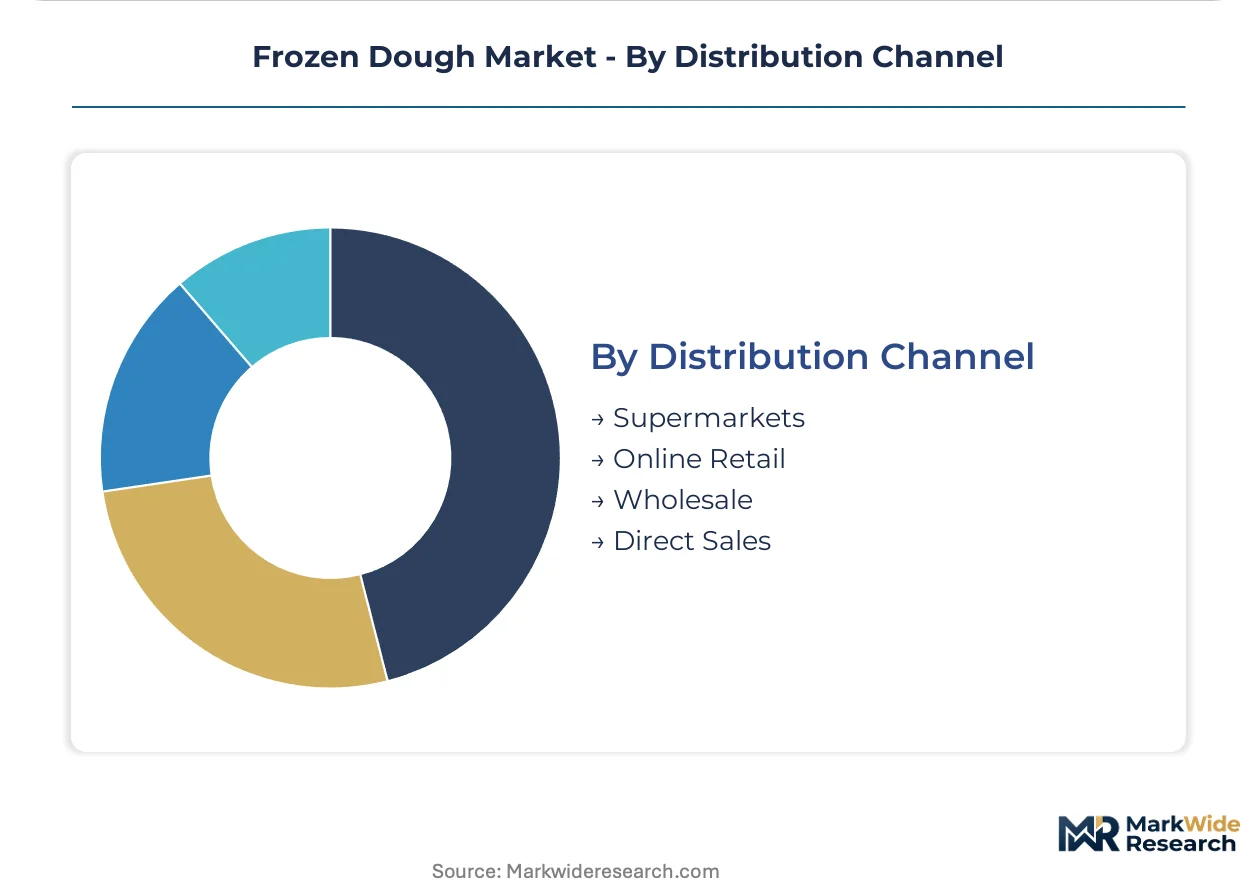
Distribution Channel:
Cold-chain infrastructure concentration in the United States and Western Europe leaves emerging markets structurally underserved, shaping channel viability by geography.
- Supermarkets:Branded freezer-aisle placement and private-label programs drive retail volume through impulse and planned purchase patterns. Walmart and Kroger centralized frozen dough category management with direct supplier scorecards.
- Online Retail:Direct-to-consumer fulfillment demands specialized insulated packaging and expedited delivery windows. Amazon Fresh and specialty food platforms expand penetration in urban corridors with reliable last-mile cold-chain capacity.
- Wholesale:Broadline distributors aggregate volume across independent operators.
- Direct Sales:Manufacturers bypass intermediaries to build captive delivery networks with technical service components.
Supermarkets maintain volume dominance; Online Retail climbs the fastest as fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with food service buyers in the United States accepting long-term contracts at fixed rates while emerging market operators remain highly sensitive to wheat input fluctuations. This divergence reshapes where manufacturers deploy capital versus where they chase volume.
United States
Quick-service restaurant chains drive procurement consolidation, with centralized sourcing teams at Aramark and Compass Group mandating real-time cold-chain documentation. FDA preventive controls under the Food Safety Modernization Act elevate compliance costs for smaller producers. Automated production facilities cluster in the Midwest, where ten-thousand-unit-daily bread lines supply national sandwich chains.
Germany
Retail private-label programs demand clean-label enzyme systems to satisfy EFSA additive scrutiny in freezer-aisle placement. REACH chemical registration deadlines force reformulation of established dough conditioners. Industrial bakeries in Bavaria deploy par-baked formats for on-premise finishing that simulates artisan output across food service channels.
India
Quick-service pizza expansion in Mumbai and Bangalore outpaces reliable HACCP-certified supply, creating procurement bottlenecks for Domino's and Pizza Hut operators. FSSAI food safety standards tighten import documentation for egg-containing formulations. Karnataka-based production investments target captive supply agreements with emerging bakery chains.
France
Premium laminated butter doughs command retail placement through strict EFSA food contact material compliance. ANSM oversight of processing aids constrains formulation choices for exporters. Paris-region distribution hubs consolidate volume for European food service networks seeking technical support and smaller batch flexibility.
Brazil
Grupo Bimbo's Latin American infrastructure anchors retail channel penetration with extensive cold-chain distribution. ANVISA allergen labeling mandates elevate documentation burdens for imported formulations. São Paulo industrial zones concentrate frozen dough production for regional quick-service expansion.
Frozen Dough Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale-driven automation separating viable national suppliers from margin-constrained regional operators. The producer base compresses around preventive control mandates that reward seven-figure equipment deployments. Three archetypes dominate: European food service specialists with deep contract relationships, Latin American retail channel masters with captive distribution, and diversified North American conglomerates with broadline leverage. Competitive moves concentrate on M&A-driven portfolio expansion and backward integration into wheat sourcing.
Within the European specialist tier, Europastry and Aryzta AG exemplify divergent paths to scale, with the former leveraging automated production lines across multiple facilities and the latter anchoring position through food service relationship depth. Grupo Bimbo occupies a distinct geography-first position, representing Latin American retail channel dominance through extensive distribution infrastructure rather than manufacturing concentration. These three entities collectively illustrate how regional regulatory adaptation and capital deployment sequencing determine sustainable positioning.
| Leading Market Players |
|---|
| Europastry |
| Rich Products Corporation |
| Aryzta AG |
| Flowers Foods, Inc. |
| Conagra Brands, Inc. |
| General Mills, Inc. |
| Lantmännen Unibake International |
| Vandemoortele |
| Grupo Bimbo |
| Others |
Cost & Logistics Intelligence
FDA preventive controls under the Food Safety Modernization Act gate both supplier qualification and price differentiation simultaneously, with HACCP-certified manufacturers commanding premium placement in quick-service restaurant procurement while uncertified regional operators compete on cost in fragmented retail channels.
Pricing Analysis
After-sales technical service contracts drive lifetime value for frozen dough manufacturers, with on-site formulation support and equipment calibration generating recurring revenue streams that exceed initial product margins. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FDA-tier suppliers capturing fixed-price multi-year agreements from Aramark and Compass Group while regional players face spot-market wheat cost pass-through. Cost compression in the economy tier is intensifying because artisan bakery substitution erodes volume leverage. Food service chains exhibit lowest price sensitivity due to operational standardization requirements, while independent bakeries demonstrate highest sensitivity with limited switching costs.
Supply Chain Analysis
Inbound logistics costs from port congestion on Asia-Pacific trade lanes and container availability constraints at Mumbai and Jawaharlal Nehru ports elevate landed costs for European and North American exporters serving Indian quick-service expansion. Supply concentrates in the United States, Germany, and Brazil, with automated production lines in the Midwest and Bavaria feeding global distribution networks. Raw material dependencies center on wheat futures, specialized enzyme stabilizers, and cryogenic freezing equipment. Single-source vulnerability runs through concentrated third-party cold-chain providers with sub-zero warehousing capacity. Distribution runs through broadline distributors for food service and supermarket direct accounts for retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen dough manufacturing presents a service-attach opportunity where technical support contracts and formulation consulting expand faster than commodity dough volumes, rewarding operators that bundle expertise with product supply.
For Market Incumbents: Shield market position by deepening backward integration into wheat sourcing to buffer margin compression from futures volatility, while accelerating ERP upgrades to meet blockchain-verified track-and-trace mandates from consolidated food service procurement teams. Fresh dough substitution from artisan bakery concepts represents the core threat requiring defensive certification investment. For New Entrants and Emerging Players: FSSAI fast-track certification for HACCP-compliant production creates entry pathways into underserved Indian quick-service markets where Domino's and Pizza Hut operators face procurement bottlenecks. White-space targets include direct-to-bakery distribution in Bangalore and Mumbai with captive delivery networks, and clean-label enzyme system development for European retail private-label programs. Go-to-market execution should anchor on technical service bundling rather than price competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underoptimized frozen dough divisions lacking dedicated cold-chain infrastructure or preventive control expertise. Long-term viability favors operators with balance sheet capacity for cryogenic freezing equipment and multi-facility automation across the analysis window. Monitor FSSAI enforcement tightening as the inflection signal for Indian market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Sourcing | Captive supply from Kansas and Saskatchewan grain belts buffers futures volatility for fixed-price contract fulfillment. |
| Cryogenic Freezing Capacity Expansion | Liquid nitrogen tunnel deployment preserves gluten structure for Pizza Hut and Domino's thickness specifications. |
| Clean-Label Enzyme Reformulation | Azodicarbonamide substitution satisfies EFSA additive scrutiny for German and French retail placement. |
| Direct-to-Bakery Distribution Network | Technical service bundling captures independent operators seeking formulation support beyond broadline distributor reach. |
| Blockchain Cold-Chain Documentation | Real-time temperature monitoring meets Aramark and Compass Group centralized quality audit requirements. |
Research Approach
Cross-validation between executive interviews and customs trade data anchors the qualitative findings, with primary conversations spanning plant managers at automated production facilities, procurement leads at quick-service restaurant chains, distribution channel partners with cold-chain capacity, and technical R&D directors developing enzyme stabilizer formulations. Secondary sources include FDA FSMA compliance filings, EFSA food contact material registrations, FSSAI import documentation records, and SEC 10-K disclosures from diversified food conglomerates. Bottom-up facility capacity analysis and top-down food service procurement spend estimates triangulate market sizing.
Sensitivity analysis across wheat price scenarios, regulatory enforcement timelines, and quick-service expansion rates tests forecast robustness. Segmentation dimensions modeled include product type, end-user procurement sophistication, form factor processing stage, and distribution channel cold-chain maturity. CAGRs derive from installed production capacity trajectories and food service outlet expansion patterns. Cryogenic freezing adoption curves and clean-label reformulation timelines serve as industry-specific forecast inputs.
Underlying assumptions cover sustained quick-service standardization demand, stable FDA enforcement intensity, and functional cold-chain infrastructure expansion in target emerging markets, with deviation risk concentrated in wheat futures volatility spikes and artisan bakery concept proliferation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market