
 Frozen Bakery Products Market | 2026-2036
Frozen Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Bakery Products Market Intelligence
European frozen dough production is broadening as industrial bakeries expand capacity to serve quick-service chains and retail private-label programs. Grupo Bimbo leverages its pan-regional plant network to sustain cost advantages across Latin American and European markets. Lantmännen Unibake anchors Nordic supply through specialized frozen bread lines for foodservice clients. Aryzta AG competes on R&D intensity, operating technical centers that refine par-bake protocols for airline and hotel catering channels.
Frozen bakery products comprise dough-based goods preserved at sub-zero temperatures to arrest staling and microbial activity, typically formulated with modified starches and emulsifiers to ensure post-thaw structural recovery. Blast freezing at minus thirty-five degrees Celsius within twenty minutes of forming locks in moisture and extends shelf life to twelve months for unbaked formats. Bread and pastries lead product type value pools due to daily consumption frequency and foodservice penetration, while frozen dough represents the fastest-expanding form segment as operators seek labor arbitrage through bake-off models. Online retail and food service distribution channels are capturing margin from supermarkets as delivery platforms and ghost kitchens proliferate.
The FDA enforces frozen food safety standards under the Food Safety Modernization Act, requiring hazard analysis and preventive controls for ready-to-bake imports entering US commerce. EFSA and national EU regulators mandate labeling for allergens and thawing instructions under the EU Food Information to Consumers Regulation, directly influencing packaging design and export compliance costs. The USDA oversees ingredient sourcing claims for frozen bakery containing dairy or egg components. Stakeholders must monitor evolving cold chain energy standards and carbon border adjustments that will reshape sourcing geography and freezer technology investment.
Market Dynamics
Quick-service restaurants are consolidating frozen pastry procurement to compress labor costs and standardize output quality, forcing suppliers to retool production lines for par-bake and thaw-and-serve formats at industrial scale.
Growth Catalysts
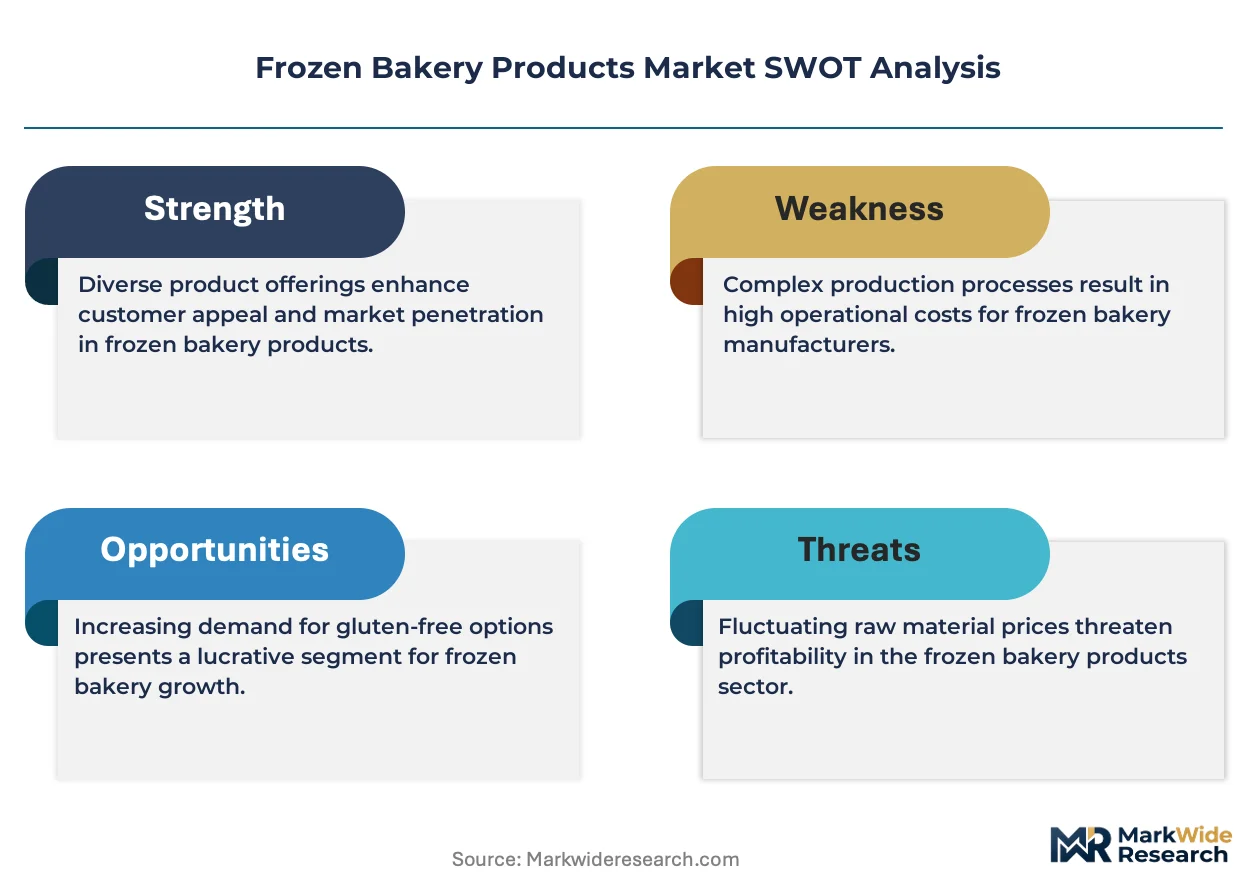
- EU F-Gas Regulation:Cold chain equipment mandates are accelerating freezer technology replacement cycles, creating captive demand for compliant blast-freezing systems in industrial bakeries.
- Ghost kitchen proliferation:Delivery-platform commissaries are adopting frozen dough to eliminate on-site mixing and reduce skilled labor dependency.
- Germany discount retail concentration:Aldi and Lidl volume commitments are pulling capacity expansion from industrial bakeries serving private-label frozen bread programs.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in the EU are compressing margins for blast-freezing operations that run continuous cycles.
- Emulsifier supply concentration:Modified starch and lecithin sourcing clusters in Southeast Asia, exposing formulators to shipping lane disruptions.
- Substitution by ambient-stable alternatives:Extended-shelf-life packaged breads from in-store bakeries are capturing convenience-oriented household purchases.
Strategic Opportunities
- India foodservice penetration:Quick-service pizza and bakery chains are importing frozen dough as domestic cold chain infrastructure matures.
- Clean-label emulsifier convergence:Enzyme-based dough conditioners combined with fermented wheat proteins are opening premium positioning.
- US FDA Food Safety Modernization Act:Preventive control documentation requirements favor suppliers with validated hazard analysis systems, creating compliance-based differentiation.
Industry Challenges
- Blast-freezing technician scarcity:Industrial bakeries face recruitment gaps for operators certified on minus-thirty-five-degree Celsius tunnel freezer maintenance.
- Legacy ERP integration:Temperature monitoring and lot-traceability systems require expensive middleware to connect with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Bakery Products Market |
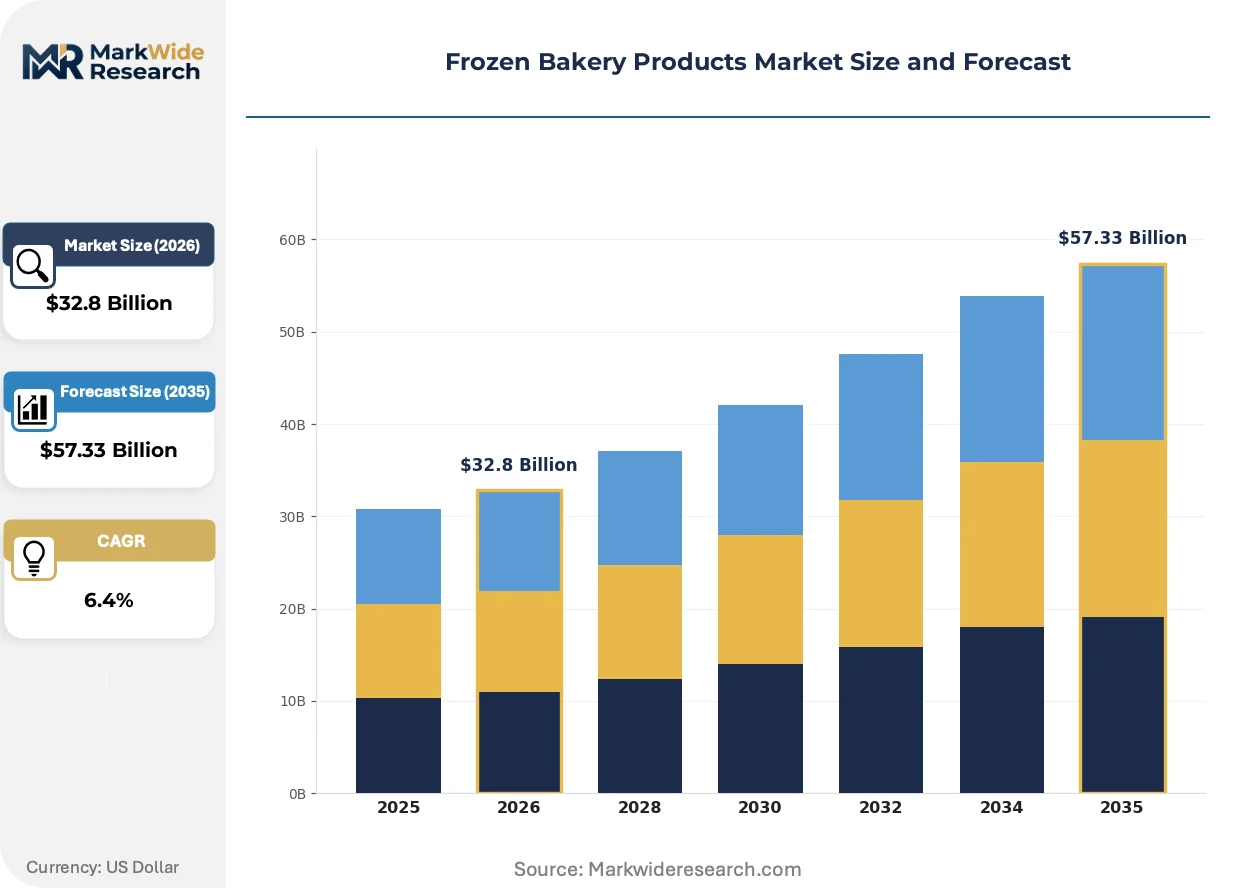
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pastries, Bread, Cakes, Muffins Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Restaurants, Cafés, Bakeries, Catering Services Form: Raw, Pre-baked, Fully-baked, Frozen Dough |
| Companies Covered | Conagra Brands, Inc., Lantmännen Unibake, Grupo Bimbo, Flowers Foods, Inc., Europastry S.A., Aryzta AG, Rich Products Corporation, Vandemoortele, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Bakery Products Market Strategic Shifts & Innovations
Refrigeration chemistry and digital traceability are converging to transform how frozen bakery moves through cold chains, with regulatory pressure and procurement centralization accelerating format standardization.
Pressure-adsorbed cryogenic freezing using liquid nitrogen injection is rewriting moisture retention protocols for delicate laminated doughs. High-volume croissant suppliers in France and Belgium are retrofitting lines to capture the technology. The shift is compressing acceptable thaw-loss thresholds and disqualifying conventional mechanical freezing for premium foodservice contracts.
The EU F-Gas Regulation phasedown schedule is forcing cold chain operators to abandon hydrofluorocarbon-based refrigeration by 2030. Industrial bakeries in Germany and Poland are trialling ammonia-CO2 cascade systems and magnetic refrigeration prototypes. Frozen dough exporters to the EU must now document freezer coolant types in customs declarations, adding compliance overhead for US and Latin American suppliers.
Centralized procurement desks at quick-service chains are consolidating supplier rosters and demanding outcome-based specifications rather than ingredient-grade contracts. Category managers at major North American restaurant groups now specify finished-product performance metrics—specific volume, crust color, staling curve—shifting quality risk onto manufacturers. This concentration is most visible in the US Southeast, where regional commissary hubs are awarding multi-year frozen bread contracts to single-source suppliers.
Frozen Bakery Products Market Segmentation
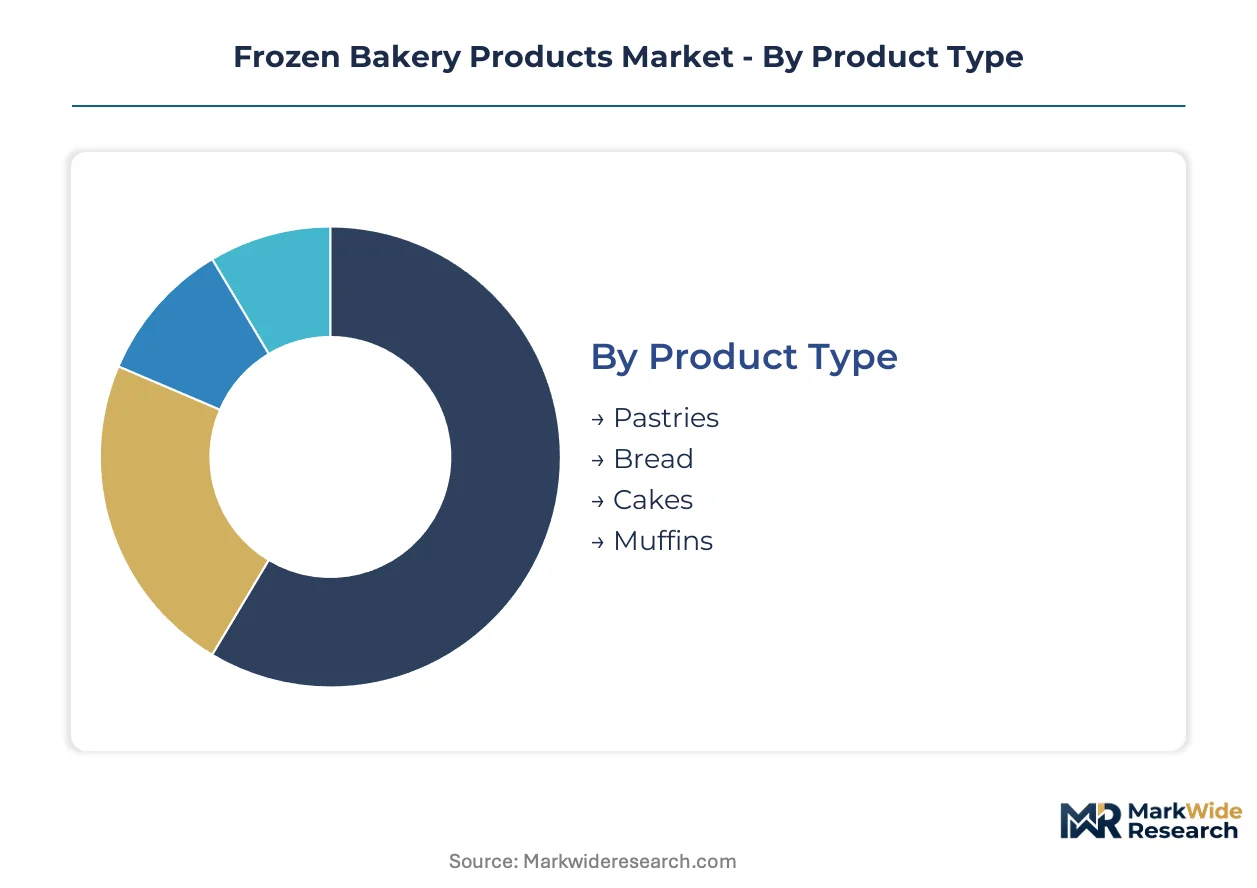
Segmentation in frozen bakery reveals how format choices and channel access determine margin capture. Product type and distribution channel combinations dictate whether suppliers serve high-volume foodservice contracts or premium retail placements.
Product Type:
Standalone consumption occasions dominate bread and pastries, while cakes and muffins embed into broader meal occasions or snacking contexts.
- Bread:Daily consumption staple formulated with modified starches for freeze-thaw stability. Quick-service restaurants in the US and Germany concentrate procurement for sandwich programs, compressing supplier margins through volume commitments.
- Pastries:Laminated dough products requiring precise blast-freezing protocols to preserve butter layer integrity. French and Belgian industrial bakeries supply laminated formats to airline catering channels demanding consistent rise and flake post-rethermalization.
- Cakes:Aerated batters stabilized with emulsifier systems for extended frozen shelf life.
- Muffins:Individual-portion formats targeting convenience retail and grab-and-go foodservice.
Bread leads volumes today; pastries are gaining share fastest.
Distribution Channel:
Channel selection determines cold chain investment intensity and customer concentration risk for suppliers.
- Food Service:Direct supply to restaurant commissaries and ghost kitchen hubs requiring par-bake or thaw-and-serve formats. North American quick-service chains are consolidating supplier rosters and demanding outcome-based performance specifications.
- Supermarkets:High-volume private-label programs with standardized packaging and extended shelf-life requirements. German discount chains Aldi and Lidl drive volume commitments that pull capacity from industrial bakeries.
- Online Retail:Direct-to-consumer and platform-mediated delivery requiring insulated packaging and last-mile frozen integrity.
- Convenience Stores:Impulse-focused placements with limited freezer space and rapid turnover expectations.
Supermarkets anchor current volume; food service channels are climbing the fastest.
End User:
User type dictates labor substitution depth and technical support requirements from suppliers.
- Restaurants:Full-service and limited-service operators adopting bake-off models to eliminate on-site mixing and reduce skilled labor dependency.
- Catering Services:Event and institutional feeders requiring consistent portion control and holding stability across extended service windows.
- Cafés:Coffee-focused formats seeking pastry differentiation with minimal kitchen footprint.
- Bakeries:Traditional operators using frozen dough to extend product range without capital investment in mixing and proofing infrastructure.
Restaurants dominate procurement volumes today; catering services show the steepest expansion trajectory.
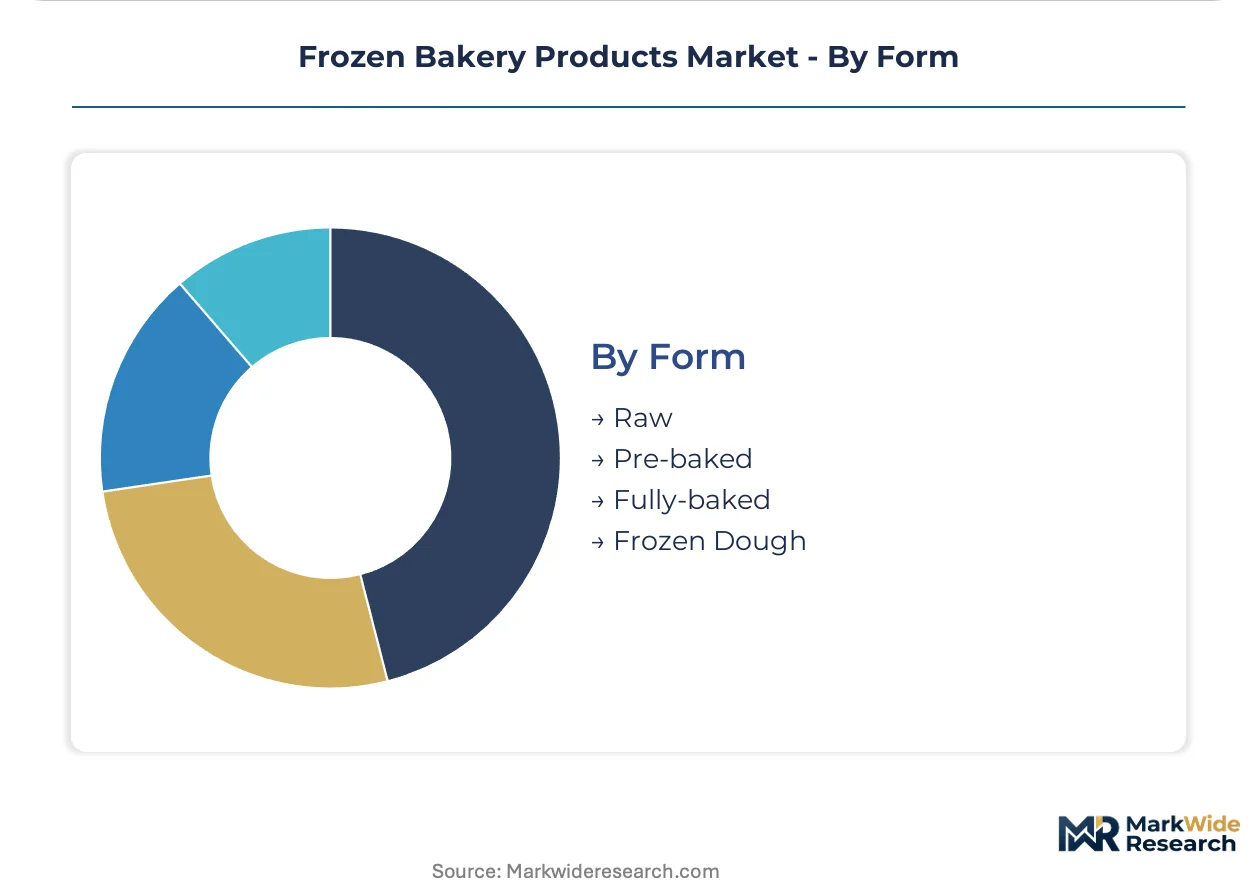
Form:
Form selection reflects the trade-off between labor elimination and quality control retained by the end operator.
- Frozen Dough:Unbaked formats requiring proofing and baking on-site, offering maximum labor arbitrage for operators with oven capacity. Ghost kitchen proliferation in urban US markets is accelerating uptake.
- Pre-baked:Par-baked products finishing in operator ovens with controlled crust development and aroma release.
- Fully-baked:Thaw-and-serve formats eliminating all on-site baking, common in convenience retail and small-footprint cafés.
- Raw:Unformed dough blocks for operators seeking maximum shaping flexibility.
Frozen dough leads volume today; pre-baked formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's discount retail chains pull frozen bread volumes that exceed France's laminated pastry exports to airline catering channels. The United States concentrates quick-service procurement consolidation in the Southeast commissary belt. India's nascent cold chain infrastructure now supports frozen dough imports for pizza chains expanding beyond tier-one cities.
United States
Quick-service restaurant groups in the Southeast award multi-year frozen bread contracts to single-source suppliers, compressing vendor rosters. The FDA Food Safety Modernization Act mandates hazard analysis documentation for ready-to-bake imports. Atlanta and Dallas commissary hubs now specify finished-product performance metrics rather than ingredient-grade contracts.
Germany
Aldi and Lidl volume commitments drive capacity expansion from industrial bakeries serving private-label frozen bread programs. The EU F-Gas Regulation forces ammonia-CO2 cascade adoption in blast-freezing operations by 2030. Munich and Hamburg industrial zones trial magnetic refrigeration prototypes for dough preservation lines.
France
Airline catering channels demand consistent croissant rise and flake post-rethermalization from laminated dough suppliers. EFSA allergen labeling mandates under the EU Food Information to Consumers Regulation reshape export packaging design. Paris and Lille industrial bakeries retrofit lines for pressure-adsorbed cryogenic freezing using liquid nitrogen injection.
India
Quick-service pizza and bakery chains import frozen dough as domestic cold chain infrastructure matures beyond Delhi and Mumbai. FSSAI frozen food safety standards govern hazard analysis for ready-to-bake products entering commerce. Bangalore and Hyderabad ghost kitchen clusters adopt bake-off models to eliminate on-site mixing.
China
Urban bakery chains expand frozen pastry procurement to standardize output across franchise networks. SAMR oversees ingredient sourcing claims for frozen bakery containing dairy or egg components. Shanghai and Guangzhou industrial zones concentrate par-bake capacity for foodservice clients seeking labor arbitrage.
Frozen Bakery Products Market Key Industry Players
European producers anchor the premium laminated-dough tier; North American specialists hold consolidated positions in quick-service bread supply. The vendor base splits between pan-regional conglomerates with plant networks and national champions serving discount retail or foodservice niches. Three archetypes dominate: scale-driven private-label suppliers, R&D-intensive technical specialists, and vertically integrated grain-to-retail operators. Capacity expansion and outcome-based contract restructuring represent the dominant competitive moves reshaping supplier relationships.
Within the scale-driven tier, Grupo Bimbo and Lantmännen Unibake occupy positions reflecting geographic anchoring and format specialization. Aryzta AG exemplifies the R&D-intensive archetype through technical center investments. These three entities represent contrasting strategic postures—pan-regional network leverage, Nordic supply concentration, and foodservice channel focus—without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Lantmännen Unibake |
| Grupo Bimbo |
| Flowers Foods, Inc. |
| Europastry S.A. |
| Aryzta AG |
| Rich Products Corporation |
| Vandemoortele |
| General Mills, Inc. |
| Others |
Cost & Logistics Intelligence
Wheat futures and palm oil benchmarks cascade through frozen bakery supply chains into three distinct pricing tiers. Foodservice buyers absorb premium markups for validated blast-freezing protocols while discount retail channels compress supplier margins through volume commitments.
Pricing Analysis
Retailer markup layers dominate downstream pricing, with German discount chains extracting 12-18 point margins on private-label frozen bread programs. Three-tier pricing structure across premium, standard, and economy levels separates cryogenically frozen laminated doughs from mechanical-freeze commodity formats. Price differentiation hinges on emulsifier grade and cold chain certification tier. Cost compression in the economy tier is intensifying because energy-intensive blast-freezing operations face natural gas price volatility. Quick-service restaurant procurement desks show lowest price sensitivity due to outcome-based contract structures, while independent bakeries exhibit highest sensitivity to dough base-price movements.
Supply Chain Analysis
Return flows of temperature-compromised shipments and expired inventory create reverse-logistics cost centers that suppliers absorb or pass through contract terms. Manufacturing concentrates in Germany, France, and Belgium for laminated doughs, with pre-baked bread capacity clustering in Poland and the United States. Modified starch supply draws from Thailand and Indonesia, while lecithin sourcing rests on Argentinian and Ukrainian crushing operations. Single-source vulnerability in Southeast Asian emulsifier supply exposes formulators to shipping lane disruptions. Distribution runs through cold-chain logistics operators with blast-freezing custody transfer points at port and commissary entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in frozen bakery hinges on clean-label emulsifier substitution reducing input costs and premium-tier positioning capturing foodservice outcome-based premiums.
For Market Incumbents: To counter consolidated quick-service procurement desks, lock in multi-year commissary contracts with guaranteed volume floors and invest in ammonia-CO2 cascade freezer retrofitting ahead of EU F-Gas Regulation deadlines. Backward integration into modified starch tolling agreements secures emulsifier supply continuity against Southeast Asian shipping disruptions. For New Entrants and Emerging Players: The mid-tier price gap between liquid nitrogen-cryogenic premium croissants and mechanical-freeze economy breads offers entry space for enzyme-conditioned dough specialists. Target India's nascent ghost kitchen clusters in Bangalore and Hyderabad with frozen dough formats eliminating on-site mixing infrastructure. Lead with FSSAI pre-certified import documentation to compress customs clearance timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with regional cold-chain logistics operators consolidating last-mile frozen integrity capabilities. Five-to-ten year viability favors assets with EU F-Gas Regulation-compliant freezer fleets and validated hazard analysis systems under FDA preventive control frameworks. Monitor EU carbon border adjustment implementation timelines as inflection indicator for sourcing geography shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Technology Upgrade | Ammonia-CO2 cascade adoption satisfies EU F-Gas Regulation while capturing premium foodservice contracts. |
| Clean-Label Reformulation | Enzyme-based dough conditioners open premium positioning in allergen-sensitive retail channels. |
| Commissary Hub Consolidation | Single-source supplier awards in Atlanta and Dallas compress vendor rosters and lock in volume. |
| Emerging Market Import Infrastructure | FSSAI-compliant cold chain investments in India enable frozen dough penetration beyond tier-one cities. |
| Outcome-Based Contract Restructuring | Performance-metric specifications shift quality risk onto manufacturers while securing multi-year commitments. |
Research Approach
Multiple input streams — executive interviews with industrial bakery operations directors, regulatory affairs leads at frozen food exporters, and category buyers at quick-service restaurant groups — were reconciled against secondary validation. Secondary sources included EU F-Gas Regulation implementation filings, FDA Food Safety Modernization Act guidance documents, customs trade data for frozen dough HS codes, and cold chain energy consumption surveys. Bottom-up capacity assessments at plant level were triangulated against top-down demand modeling by channel and format.
Data-stream reconciliation across supply-side capacity expansion announcements and demand-side procurement consolidation patterns shaped the analytical framework. Segmentation dimensions spanned product type, distribution channel, end user archetype, and form specification across the projection horizon. CAGRs were derived from slope analysis of volume trajectory inflection points, incorporating emulsifier cost curve movements and cold chain equipment replacement cycles as industry-specific forecast inputs.
Caveats apply where EU carbon border adjustment implementation, natural gas price volatility in blast-freezing operations, or Southeast Asian shipping lane disruptions could materially shift the outlook. Practitioners should monitor F-Gas Regulation compliance deadlines and clean-label emulsifier substitution rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Muffins Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Malted Rye Flour Market
Bakery Products
South America Bakery Products Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Low Fat Bread Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Pancake Mixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Marzipan Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
North America Sweet Biscuits Market