
 Bakery Improvers Market | 2026-2036
Bakery Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Improvers Market Outlook
Asset-light leasing models for industrial mixing and fermentation equipment are rewriting competitive entry dynamics in bakery improver supply. Corbion NV leverages its bio-based fermentation platform to sustain enzyme production at scale across European contract manufacturing networks. Puratos Group anchors global distribution through direct technical service teams embedded in bakery manufacturer facilities. Lesaffre et Compagnie SA differentiates via vertically controlled yeast-to-enzyme supply chains that reduce raw material variability for industrial bread clients.
Bakery improvers constitute functional additive blends—typically comprising amylases, lipases, xylanases, and emulsifiers such as DATEM or SSL—designed to optimize dough rheology, gas retention, and finished product texture under industrial processing conditions. Enzyme-based improvers command expanding share as clean-label formulations displace chemical conditioners in premium bread and pastry applications. The bread application segment dominates volume consumption, while pastries and cakes generate higher per-kilogram margins due to specialized conditioning requirements and shorter production runs. Bakery manufacturers represent the largest end-user channel, though food service operators are gaining purchasing sophistication through consolidated procurement platforms.
EFSA evaluates novel enzyme safety under updated guidance, while FDA GRAS self-determination pathways shape U.S. market access timelines for new improver blends. REACH compliance requirements for emulsifier feedstocks add formulation cost complexity for suppliers serving European industrial bakeries. Stakeholders must monitor evolving enzyme labeling thresholds in major markets and calibrate R&D pipelines toward regulatory pre-approval rather than post-market defense.
Market Dynamics
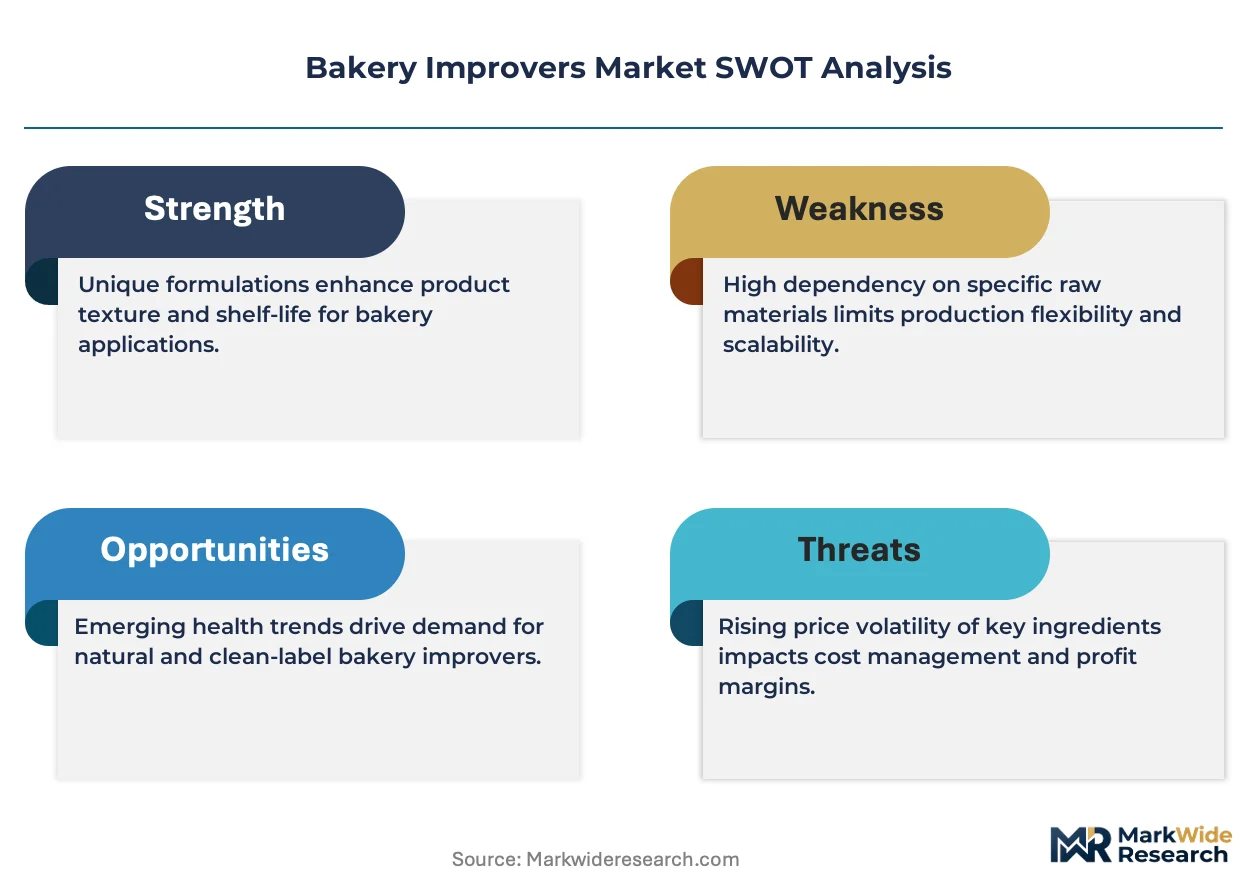
Enzyme-based improvers are displacing chemical conditioners as the dominant functional additive category, driven by clean-label mandates from EFSA and FDA that now require substantiated claims for shelf-life extension and texture modification in commercial bread production.
Growth Catalysts
- Clean-label enzyme adoption:Industrial bakeries in Germany retrofit production lines to accommodate reduced-additive formulations that meet EFSA's updated Food Improvement Agent regulations.
- Fermentation platform scaling:Bio-based production methods for amylases and lipases achieve cost parity with chemical emulsifiers across European contract manufacturing networks.
- Extended shelf-life requirements:Food service operators demand improvers that maintain crumb structure through frozen distribution chains without DATEM or SSL labeling.
Market Restraints
- Raw material concentration:Specialized enzyme feedstocks depend on concentrated European fermentation capacity, creating supply vulnerability during energy price spikes.
- REACH compliance costs:Emulsifier feedstock registration and safety data requirements add formulation complexity for suppliers serving industrial bakeries in EU member states.
- Clean-label substitution ceiling:Enzyme performance gaps in high-speed industrial lines limit complete displacement of chemical conditioners in certain bread categories.
Strategic Opportunities
- Artisan bakery penetration:Small-scale producers in France and Italy represent underdeveloped demand for enzyme-based improvers that replicate traditional fermentation profiles.
- Pastry margin capture:Specialized conditioning requirements for laminated doughs generate higher per-kilogram returns than commodity bread applications.
- Consolidated procurement platforms:Food service operators are aggregating purchasing power through digital platforms that favor technical service-embedded suppliers.
Industry Challenges
- Fermentation technologist scarcity:Industrial enzyme production requires specialized biochemistry expertise that outpaces European technical training pipeline output.
- Legacy equipment incompatibility:Retrofitting high-speed mixing lines for enzyme-optimized dough rheology demands capital outlays that strain mid-tier bakery margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Improvers Market |
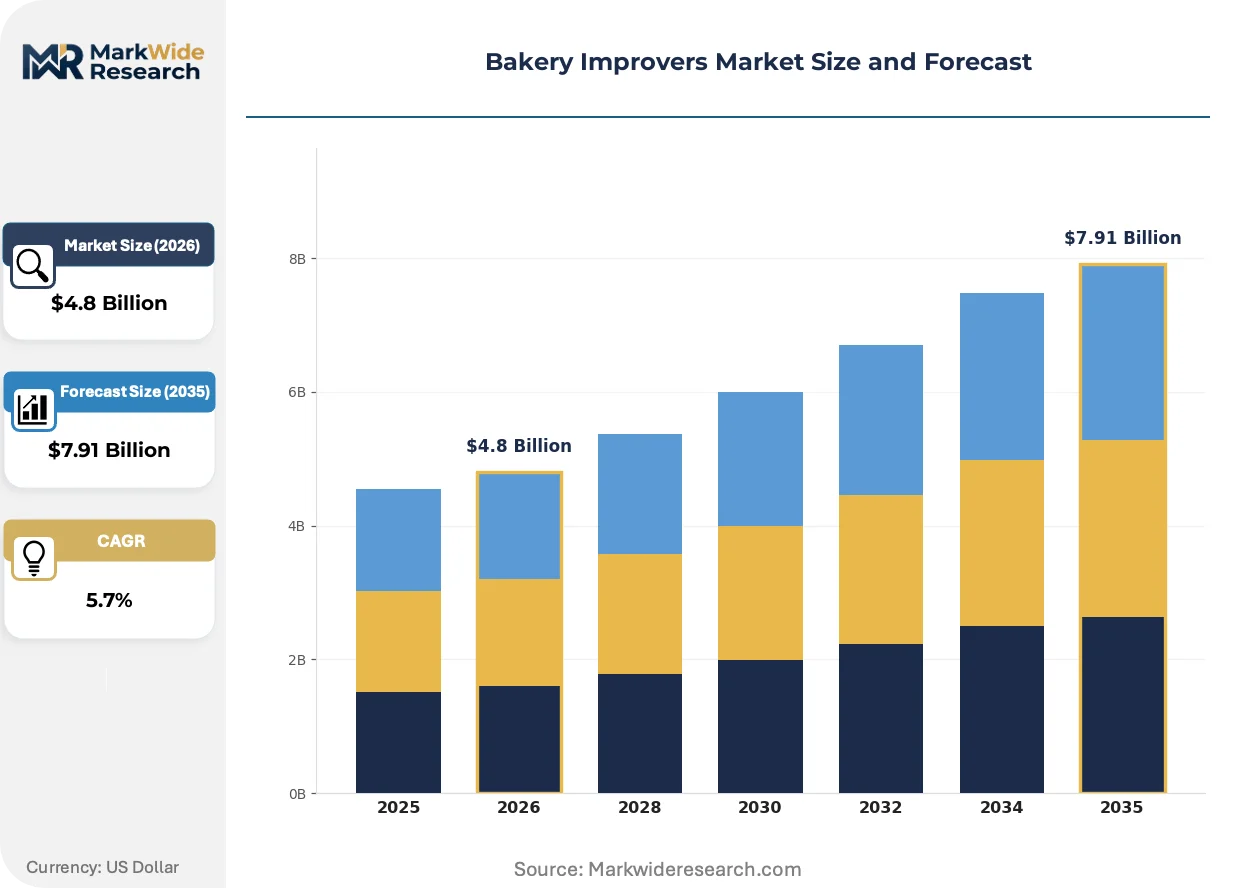
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Emulsifiers, Preservatives, Dough Conditioners Application: Bread, Pastries, Cakes, Cookies End User: Bakery Manufacturers, Food Service, Retail Bakeries, Home Bakers Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Supermarkets |
| Companies Covered | Archer Daniels Midland Company, Corbion NV, Puratos Group, Bakels Worldwide, Fazer Group, Lesaffre et Compagnie SA, Ireks, BreadPartners, AB Mauri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Improvers Market Strategic Shifts
Formulation science is pivoting from chemical conditioning toward precision enzyme engineering, with regulatory pre-approval replacing post-market defense as the critical gating factor for new improver launches.
Multi-enzyme synergistic blends are migrating from premium artisan applications into industrial bread production. These optimized amylase-lipase-xylanase combinations deliver consistent gas retention and crumb structure under variable flour quality conditions. Large-scale manufacturers in Germany and the Netherlands adopt these systems to reduce dependence on DATEM and SSL emulsifiers. The technology is migrating from niche clean-label segments into mainstream high-volume lines as cost structures compress.
EFSA's updated guidance on novel enzyme safety evaluations tightens pre-market authorization timelines for suppliers targeting EU industrial bakeries. The framework now requires extended dietary exposure assessments that extend development cycles by 12-18 months. Bread improver categories face the strictest scrutiny, while pastry and cake applications benefit from shorter review pathways due to lower consumption volume assumptions.
Technical service unbundling is fragmenting traditional supplier-buyer relationships in the bakery channel. Food manufacturers increasingly separate ingredient procurement from formulation consulting, engaging independent food technologists for dough system optimization. This pattern concentrates in German and French markets where consolidated bakery groups possess internal R&D capabilities. Suppliers must now compete on enzyme performance metrics alone rather than embedded technical support value.
Bakery Improvers Market Segmentation
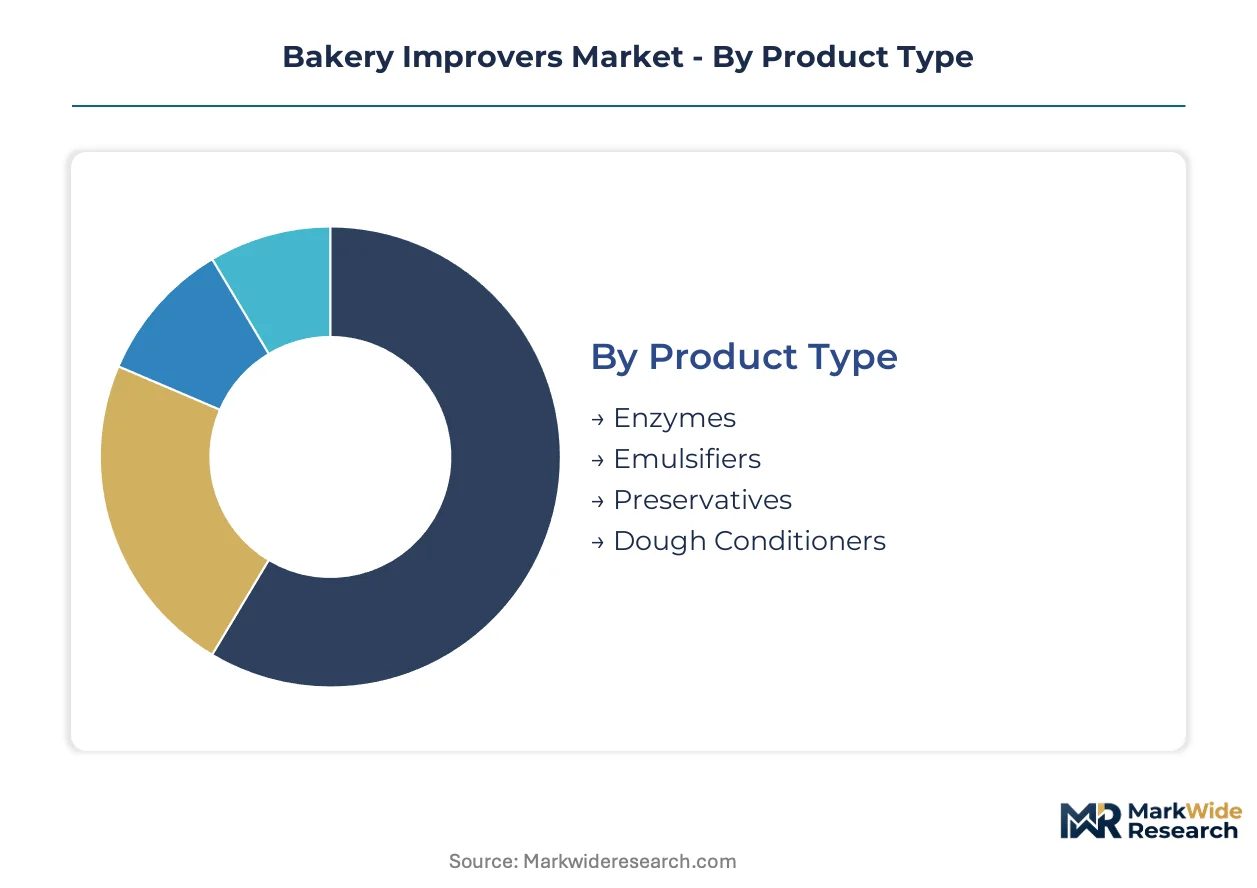
Bakery improver suppliers configure technical service teams and formulation support around distinct product-performance requirements. Segmentation reveals where after-sales intensity concentrates and which channels reward embedded expertise versus transactional supply.
Product Type:
After-sales-service intensity peaks with enzyme-based improvers, where suppliers deploy fermentation technologists to optimize dosing protocols for variable flour batches.
- Enzymes:Amylase, lipase, and xylanase blends enable clean-label crumb structure modification without chemical emulsifiers. German industrial bakeries retrofit high-speed lines to accommodate enzyme-optimized dough rheology, though fermentation technologist scarcity extends implementation timelines.
- Emulsifiers:DATEM and SSL conditioners deliver consistent gas retention in high-speed industrial bread production. REACH compliance costs for feedstock registration are concentrating supply among large-scale European manufacturers with dedicated regulatory affairs capacity.
- Preservatives:Propionates and sorbates extend shelf life in frozen distribution chains for food service operators.
- Dough Conditioners:Ascorbic acid and azodicarbonamide variants optimize gluten network development for high-volume bread lines.
Enzymes holds the largest share; momentum sits with emulsifiers as clean-label substitution ceilings limit complete displacement in certain bread categories.
Application:
Margin tiering separates commodity bread from specialized pastry applications, with per-kilogram returns climbing as production run lengths shorten and conditioning complexity intensifies.
- Bread:Industrial loaves and rolls consume the highest improver volumes, with enzyme blends displacing chemical conditioners under EFSA's updated Food Improvement Agent regulations. Large-scale manufacturers in Germany and the Netherlands drive formulation standardization.
- Pastries:Laminated doughs for croissants and Danish require specialized lipase-xylanase combinations that generate the steepest expansion trajectory across all application segments. French and Italian artisan producers represent underdeveloped demand for industrial-grade enzyme systems.
- Cakes:Aeration stability and crumb softness specifications favor emulsifier-heavy formulations with shorter EFSA review pathways.
- Cookies:Spread control and texture modification rely on amylase-selective blends for consistent snap and mouthfeel.
Bread dominates volume consumption; pastry margin capture is climbing the fastest as specialized conditioning requirements command premium positioning.
End User:
Customer type determines procurement sophistication, with consolidated bakery groups separating ingredient purchasing from independent formulation consulting.
- Bakery Manufacturers:Industrial-scale bread and pastry producers represent the largest consumption channel, retrofitting production lines for reduced-additive formulations. Internal R&D capabilities at German and French consolidated groups enable unbundled technical service relationships.
- Food Service:Frozen distribution chains demand improvers maintaining crumb structure without DATEM or SSL labeling. Digital procurement platforms are aggregating purchasing power and favoring suppliers with direct technical service embedding.
- Retail Bakeries:Small-scale urban operators in France and Italy seek enzyme-based systems replicating traditional fermentation profiles.
- Home Bakers:Pre-mixed consumer improver blends concentrate in supermarket and online channels with minimal technical support requirements.
Bakery manufacturers retain the largest share; food service is gaining share fastest through consolidated procurement platform expansion.
Distribution Channel:
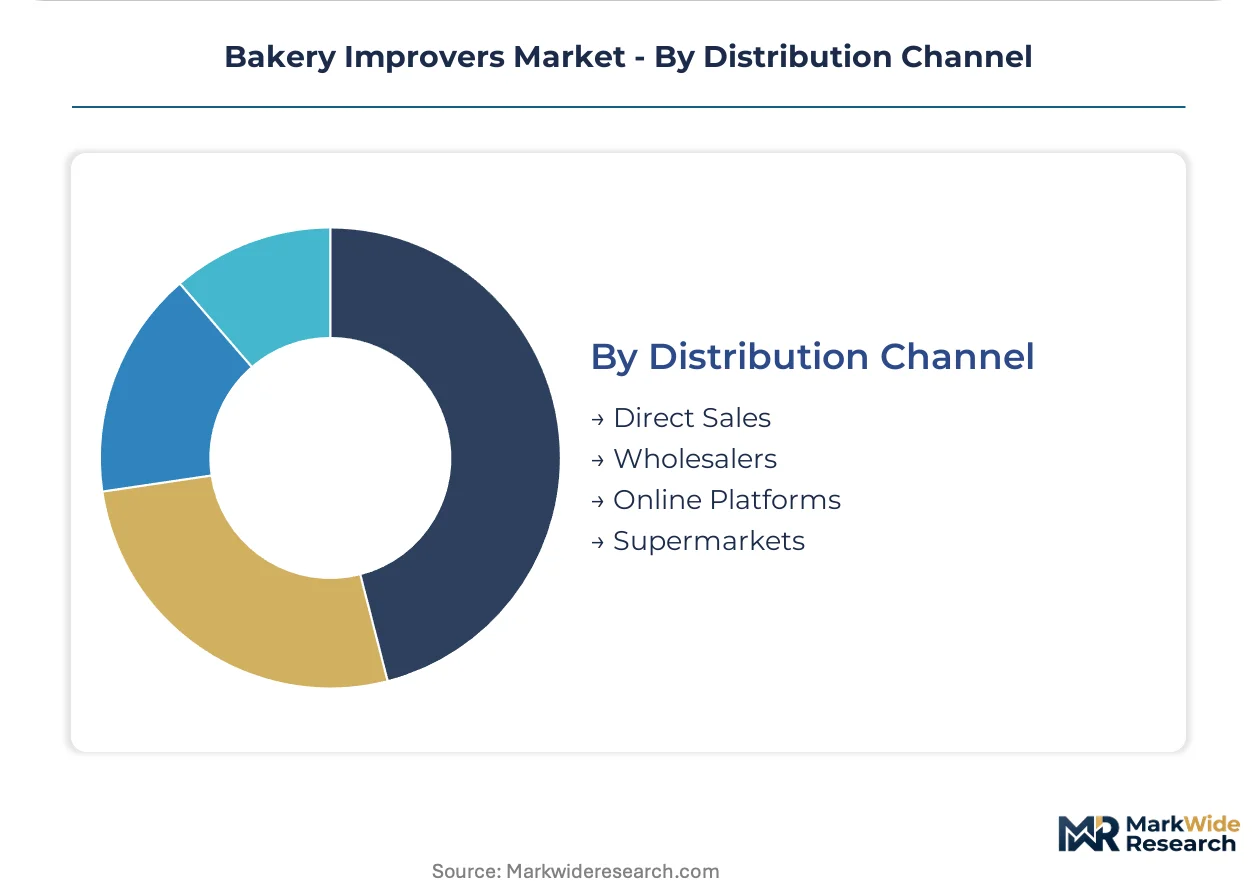
Supply concentration patterns vary sharply across channels, with direct relationships rewarding formulation customization while wholesale and digital routes favor price-competitive standard blends.
- Direct Sales:Technical service teams embedded in bakery manufacturer facilities anchor global distribution for premium enzyme blends. Corbion NV and Puratos Group compete on fermentation platform scale and direct formulation consulting capacity.
- Wholesalers:Regional distributors serve mid-tier industrial bakeries with limited internal R&D capabilities, concentrating in German and Dutch manufacturing clusters.
- Online Platforms:Food service procurement aggregation and home baker pre-mix sales are expanding through digital channels with minimal technical support attachment.
- Supermarkets:Consumer-facing retail bakeries and home baker segments access standardized improver formulations through grocery supply chains.
Direct sales commands the largest share; online platforms are expanding most quickly as food service procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in bakery improvers tilt toward net-exporting European fermentation clusters, while import-dependent markets in Asia-Pacific and the Middle East absorb surplus enzyme capacity. Currency volatility and energy cost differentials are reshaping regional sourcing patterns.
Germany
Industrial bakeries in North Rhine-Westphalia and Bavaria retrofit high-speed lines for reduced-additive formulations under EFSA's updated Food Improvement Agent regulations. The country's national food safety authority enforces strict clean-label thresholds for shelf-life claims. Munich and Hamburg anchor contract manufacturing networks that supply enzyme blends across Central Europe.
France
Artisan producers in Île-de-France and Auvergne-Rhône-Alpes drive demand for enzyme systems replicating traditional fermentation profiles. ANSM monitors novel enzyme safety submissions alongside EFSA harmonized standards. Lyon-based technical service teams embed directly with mid-scale bakery groups to optimize dosing protocols.
United States
Frozen distribution chains for food service operators concentrate demand in the Midwest and Southeast baking corridors. FDA GRAS self-determination pathways shape market access timelines for new improver blends. Chicago and Atlanta host formulation labs that adapt European enzyme systems to domestic flour varieties.
China
Industrial bread production expansion in the Yangtze River Delta and Pearl River Delta absorbs imported enzyme technology. SAMR implements updated food additive standards that align with CODEX frameworks. Shanghai and Shenzhen manufacturers trial bio-based improvers for premium bakery segments.
Brazil
Consolidated bakery groups in São Paulo and Minas Gerais import enzyme formulations to displace chemical conditioners in packaged bread. ANVISA evaluates novel food enzymes under Mercosur harmonization protocols. Campinas anchors regional distribution for South American industrial bakeries.
Bakery Improvers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base concentrates among European fermentation houses with captive enzyme production and Asian distributors serving price-sensitive industrial bakeries. Three archetypes dominate: vertically integrated fermentation platforms, technical service-embedded formulators, and regional ingredient traders. Capacity expansion and formulation licensing represent the primary competitive vectors.
Within the integrated fermentation tier, Corbion NV exemplifies platform scale across European contract manufacturing networks. Puratos Group anchors technical service embedding through direct deployment in bakery manufacturer facilities. Lesaffre et Compagnie SA occupies a position reflecting vertically controlled supply chains from yeast to finished enzyme systems.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Corbion NV |
| Puratos Group |
| Bakels Worldwide |
| Fazer Group |
| Lesaffre et Compagnie SA |
| Ireks |
| BreadPartners |
| AB Mauri |
| Others |
Value Chain & Pricing Dynamics
European fermentation capacity concentration in Germany and the Netherlands anchors upstream supply of amylase and lipase feedstocks, directing margin capture toward formulation specialists who blend and dose these enzymes for industrial bakery clients. This geographic clustering of bio-based production capacity creates asymmetric pricing power that downstream improver suppliers must navigate through long-term offtake agreements or captive fermentation investments.
Pricing Analysis
Industrial bakery manufacturers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by enzyme purity grades and embedded technical service intensity. Price compression in commodity bread applications stems from unbundled procurement patterns where consolidated bakery groups separate ingredient purchasing from formulation consulting. Mid-tier industrial bakeries with limited internal R&D capabilities exhibit highest price sensitivity, while artisan producers in France and Italy accept premium positioning for clean-label enzyme systems that replicate traditional fermentation profiles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from large-scale European fermentation houses have become standard contracting practice, compressing working capital for smaller improver blenders. Raw material supply concentrates in Germany, the Netherlands, and Denmark, drawing from specialized fermentation feedstocks and emulsifier precursors subject to REACH registration requirements. Single-source vulnerability in concentrated European enzyme production capacity represents the dominant structural risk, while distribution runs through direct technical service embedding for premium accounts and regional wholesalers for standardized formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against in-house enzyme production investments by consolidated bakery groups seeking supply security and formulation autonomy. Clean-label mandates from EFSA and FDA accelerate this threat by rewarding vertically integrated producers who control their own fermentation capacity.
For Market Incumbents: Entrench market position through backward integration into captive fermentation capacity in North Rhine-Westphalia or Bavaria, securing enzyme supply against energy price volatility. Deepen technical service embedding with mid-tier bakery manufacturers who lack internal R&D capabilities, creating switching costs that resist unbundling trends. Prioritize EFSA pre-approval investments for novel enzyme blends to compress authorization timelines relative to competitors. For New Entrants and Emerging Players: Artisan bakery clusters in Auvergne-Rhône-Alpes and Lombardy represent the most penetrable entry point for enzyme-based improvers replicating traditional fermentation profiles. Food service procurement platforms aggregating frozen distribution chain demand offer a digital-native go-to-market angle bypassing entrenched direct sales relationships. Target pastry applications with specialized lipase-xylanase combinations that command premium per-kilogram returns and shorter production run requirements. For Investors and Strategic Acquirers: Capital is best deployed toward technical service-embedded formulators with established EFSA regulatory affairs capacity and direct relationships with German industrial bakery groups. Long-term viability over a multi-year horizon hinges on differentiation through fermentation platform scale rather than commodity blending operations. Monitor EFSA authorization timelines for novel enzyme categories as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive enzyme production in Munich or Hamburg insulates margin from energy price spikes and supply disruption. |
| EFSA Pre-Approval Investment | Early engagement with novel enzyme safety assessments compresses market access timelines relative to reactive competitors. |
| Technical Service Embedding Expansion | Direct deployment in French and Italian artisan facilities creates switching costs resistant to procurement unbundling. |
| Pastry Application Specialization | Laminated dough conditioning expertise commands premium positioning in croissant and Danish production segments. |
| Digital Procurement Platform Partnership | Alignment with food service aggregation platforms captures share in fastest-expanding distribution channel. |
Study Parameters
A spread of perspectives from fermentation technologists, bakery manufacturer R&D directors, procurement leads at consolidated industrial bakery groups, and regulatory affairs specialists at EFSA-notified bodies converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, European fermentation industry association reports, SEC filings from publicly listed ingredient suppliers, and EFSA novel food enzyme submission databases. Bottom-up volume modeling across enzyme type, application segment, and end-user channel triangulated against top-down market sizing from supplier revenue disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling spanning product type, application, end-user sophistication tier, and distribution channel intensity. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and clean-label substitution elasticities. Industry-specific forecast inputs included flour quality variability indices, EFSA authorization pipeline status, and energy cost differentials affecting fermentation economics.
Macroeconomic conditions sit as an overlay; deviation in European energy pricing, wheat commodity volatility, or EFSA regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about substitution ceilings for chemical conditioners and fermentation capacity expansion timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Malted Rye Flour Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Cake Base Discs Market
Bakery Products
Fortified Bakery Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Pastry Dough Market
Bakery Products
Cake Concentrate Market
Bakery Products
Bread Premix Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Muffins Market
Bakery Products
Pastry Premixes Market
Bakery Products
Bread Improver Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Low Fat Oatmeal Cookies Market