
 Wine Enzymes Market | 2026-2036
Wine Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Enzymes Market Analytics
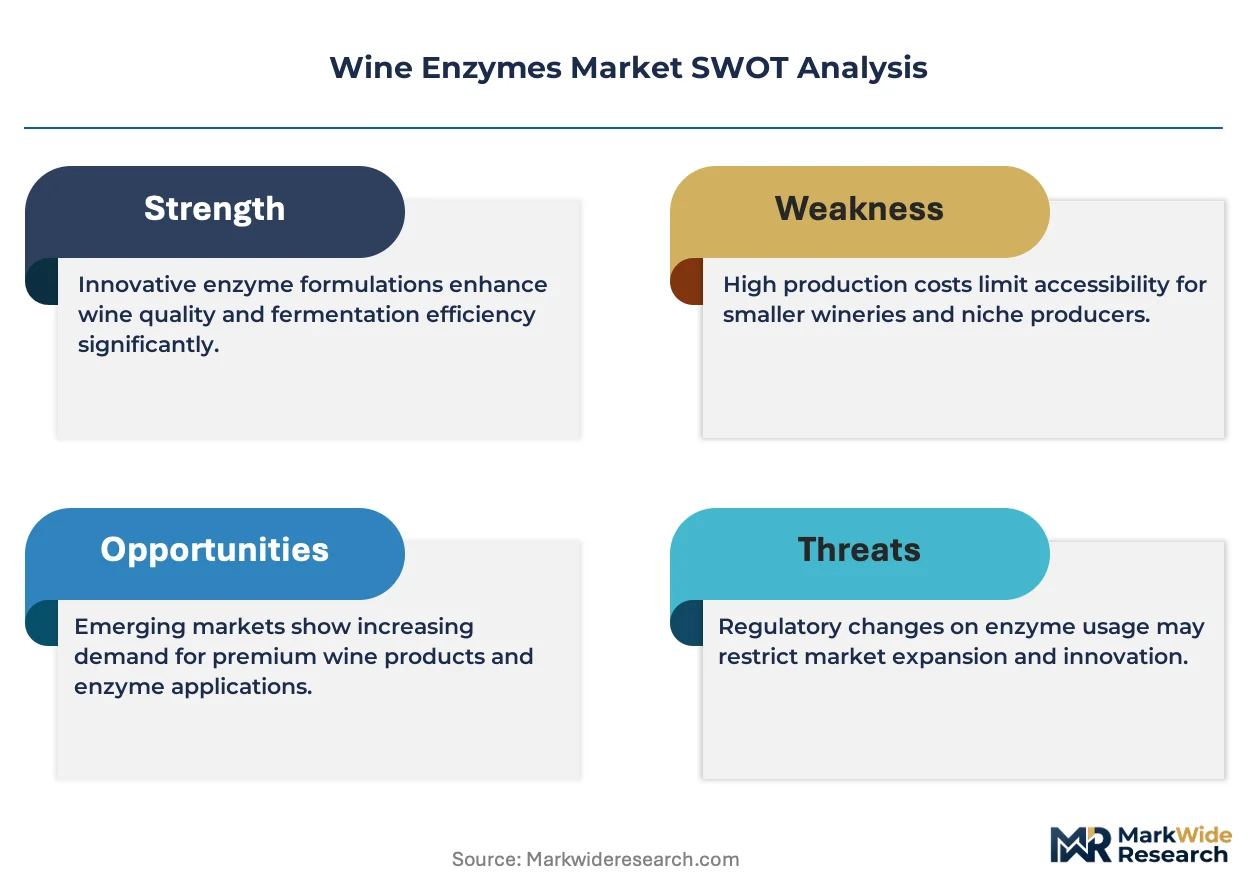
European enzyme producers is expanding fermentation-grade capacity to serve premium wine regions across Bordeaux, Tuscany, and Rioja. Novozymes A/S leverages its microbial platform to supply high-activity pectinase blends for cold-soak maceration protocols. DSM-Firmenich anchors its position through specialized glucose oxidase formulations that stabilize bottled white wines against premature browning. Lallemand Bio-Ingredients competes on yeast-enzyme synergies, bundling tailored inoculants with clarifying enzymes for contract winemakers.
Wine enzymes are protein-based biocatalysts, typically derived from Aspergillus niger or Trichoderma reesei fermentation, that hydrolyze polysaccharides and proteins during grape processing to improve yield, clarity, and phenolic extraction. These preparations function at temperatures between 15°C and 30°C and pH ranges of 2.8–4.0, matching natural must conditions without thermal degradation of volatile aromatics. Pectinase dominates type-level value contribution due to its essential role in juice liberation and lees compaction during primary fermentation. Liquid formulations lead the form dimension because of dosing precision in automated cellar systems, though powder enzymes retain share among small-batch artisanal producers seeking extended shelf stability. Red wine production anchors application demand, as extended maceration protocols require higher pectinase and cellulase loadings than white wine pressing operations.
EMA and EFSA frameworks govern enzyme safety assessments for food-contact applications within EU member states, while REACH mandates full toxicological dossiers for non-food-grade processing aids that may contact equipment surfaces. The USDA's National Organic Program and FDA GRAS notifications shape market access for enzymes sold into American premium wine channels, where organic certification commands shelf price premiums. Stakeholders must monitor evolving enzyme labeling thresholds under EU Green Deal agricultural sustainability protocols, as carbon footprint disclosure requirements for biotech inputs are tightening across French and Italian cooperative purchasing agreements.
Market Dynamics
EU F-Gas Regulation disclosure mandates are compressing formulation timelines and forcing enzyme suppliers to accelerate organic-compliant certification pathways before cooperative purchasing deadlines.
Growth Catalysts
- REACH toxicological dossiers:Full disclosure requirements under ECHA frameworks are filtering out non-compliant suppliers, creating shelf space for certified enzyme formulators in French and Italian cooperative networks.
- Cold-soak maceration protocols:Premium red winemakers in Bordeaux and Rioja are expanding pectinase loadings to extract deeper phenolic compounds without thermal aromatic degradation.
- USDA National Organic Program:American premium channels now require third-party organic certification for processing aids, opening price-premium positioning for GRAS-notified enzyme variants.
Market Restraints
- Fermentation-grade capacity concentration:European producers dominate high-activity pectinase supply, creating geographic single-source risk for contract winemakers in emerging regions.
- Aspergillus niger feedstock volatility:Industrial fermentation substrate costs fluctuate with agricultural commodity cycles, compressing margin stability for liquid formulation suppliers.
- Thermal stability ceiling:Protein denaturation above 30°C limits enzyme efficacy in warm-climate harvest conditions, restricting adoption in southern hemisphere operations without refrigeration infrastructure.
Strategic Opportunities
- EU Green Deal agricultural sustainability protocols:Carbon footprint disclosure requirements for biotech inputs are creating first-mover advantage for suppliers with lifecycle-certified production facilities.
- Yeast-enzyme synergies:Bundled inoculant-clarifier offerings address operational simplification needs among mid-sized contract winemakers seeking reduced cellar labor.
- Powder formulation shelf stability:Artisanal producers in emerging wine regions prefer dry enzyme formats for extended storage without cold-chain dependency.
Industry Challenges
- EMA enzyme safety assessment timelines:EFSA novel food consultations for new microbial strains extend market entry by 18-24 months, delaying revenue recognition for R&D-intensive formulators.
- Automated dosing system integration:Legacy cellar infrastructure in traditional vineyard economies requires retrofit investment to achieve precision enzyme delivery.
- Cross-contamination protocols:Allergen management for Aspergillus-derived proteins demands segregated production lines, elevating capital intensity for multi-product fermentation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Enzymes Market |
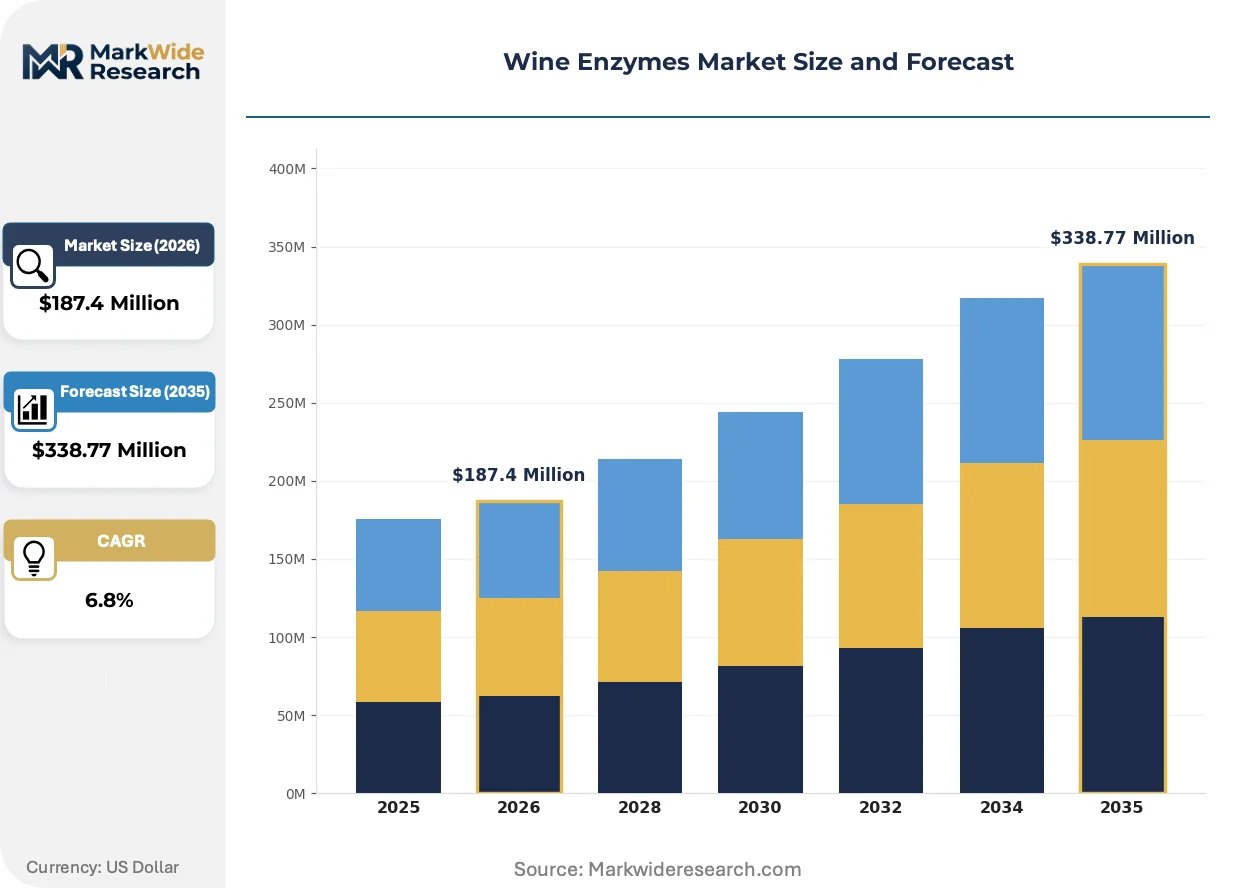
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cellulase, Pectinase, Protease, Glucose Oxidase Application: Red Wine Production, White Wine Production, Sparkling Wine Production, Fortified Wine Production Form: Liquid, Powder, Granular, Tablet End User: Winemakers, Food Beverage Manufacturers, Research Institutions, Laboratories |
| Companies Covered | BASF SE, Associated British Foods plc, Novozymes A/S, Chr. Hansen Holding A/S, Lallemand Bio-Ingredients, DSM-Firmenich, Amano Enzyme Inc., International Flavors & Fragrances, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Enzymes Market Evolving Landscape
Biocatalytic processing is converging with digital cellar management systems, creating precision dosing protocols that optimize enzyme loadings against real-time must analysis.
Cellulase-pectinase co-formulations are converging with automated pressing sequences. Large cooperative wineries in Spain and Italy are deploying sensor-driven maceration controls that adjust enzyme feed rates based on cap management algorithms. This convergence is compressing labor requirements while standardizing extraction consistency across variable harvest conditions.
EU F-Gas Regulation phase-down schedules are tightening processing aid disclosure thresholds. Wineries in France must now document enzyme carbon footprints through supply chain tiers. Premium organic-certified producers are responding by sourcing exclusively from fermentation facilities with verified renewable energy inputs.
Buyer concentration among cooperative purchasing alliances is consolidating procurement authority. Mid-sized Bordeaux châteaux now negotiate enzyme supply through regional consortiums rather than individual supplier relationships. Spain's Rioja regulatory council is formalizing preferred supplier lists based on combined price-performance-certification scoring.
Wine Enzymes Market Segmentation
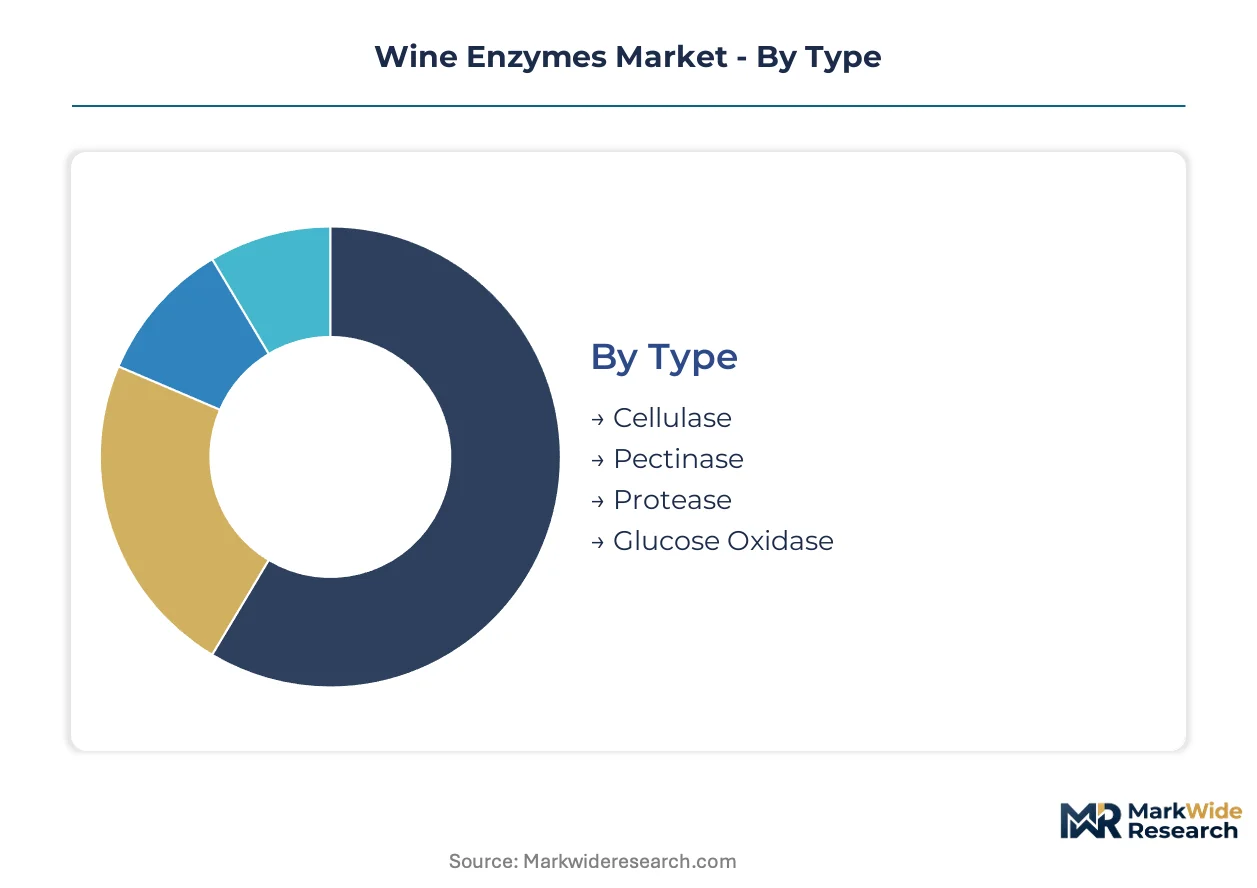
Wine enzyme procurement follows distinct technical hierarchies across processing stages, with formulators selecting biocatalysts based on must chemistry, cellar infrastructure, and certification requirements. Segmentation reveals how premiumization trends and regulatory disclosure mandates reshape supplier positioning across enzymatic categories.
Type:
Buyers prioritize enzymatic activity profiles and substrate specificity when selecting biocatalysts for maceration and clarification protocols.
- Pectinase:These polygalacturonase-rich preparations hydrolyze pectin chains in grape cell walls, liberating juice and enabling compact lees settlement. Demand concentrates in Bordeaux and Rioja, where extended maceration protocols require high-activity formulations for phenolic extraction without thermal degradation.
- Cellulase:β-glucanase and cellobiohydrolase activities degrade cellulose matrices in grape skins, improving press yield and color stability in premium red operations. Italian cooperative wineries in Tuscany deploy cellulase-pectinase co-formulations to standardize extraction across variable harvest conditions.
- Protease:These protein-hydrolyzing enzymes reduce haze-forming proteins in white musts, supporting protein stability without bentonite overfining.
- Glucose Oxidase:Oxygen-scavenging formulations catalyze glucose conversion to gluconic acid, protecting bottled white wines from premature browning in premium distribution channels.
Pectinase leads on scale; glucose oxidase leads on momentum as organic-certified variants gain traction in American premium channels.
Application:
Production protocol complexity and phenolic extraction requirements differentiate enzymatic loading strategies across wine styles.
- Red Wine Production:Extended skin contact protocols demand elevated pectinase and cellulase loadings to maximize anthocyanin and tannin extraction. French châteaux in Médoc and Saint-Émilion deploy enzyme sequences across cold-soak, fermentation, and post-fermentation maceration phases.
- White Wine Production:Gentle pressing operations prioritize clarifying enzymes at lower concentrations, with glucose oxidase gaining share for oxidative stability in bottle-aged styles.
- Sparkling Wine Production:Secondary fermentation management requires specialized enzyme protocols for lees autolysis enhancement and bubble persistence.
- Fortified Wine Production:High-alcohol must conditions necessitate alcohol-tolerant enzyme variants for residual sugar management and clarification.
Red wine production commands volume concentration; sparkling wine production shows steepest expansion trajectory as premiumization extends to traditional-method segments.
Form:
Dosing precision requirements and storage infrastructure constraints determine format selection across producer scale tiers.
- Liquid:Standardized activity solutions enable automated metering in continuous-flow cellar systems. Large cooperative wineries in Spain favor liquid pectinase for integration with sensor-driven maceration controls.
- Powder:Lyophilized preparations offer extended shelf stability without cold-chain dependency. Artisanal producers in emerging wine regions select powder formats for inventory flexibility.
- Granular:Intermediate dissolution characteristics suit mid-scale operations seeking dosing precision without full automation investment.
- Tablet:Pre-weighed solid formats simplify small-batch operations and mobile cellar services.
Liquid formulations dominate value contribution; powder formats gain share fastest among organic-certified suppliers serving distributed procurement networks.
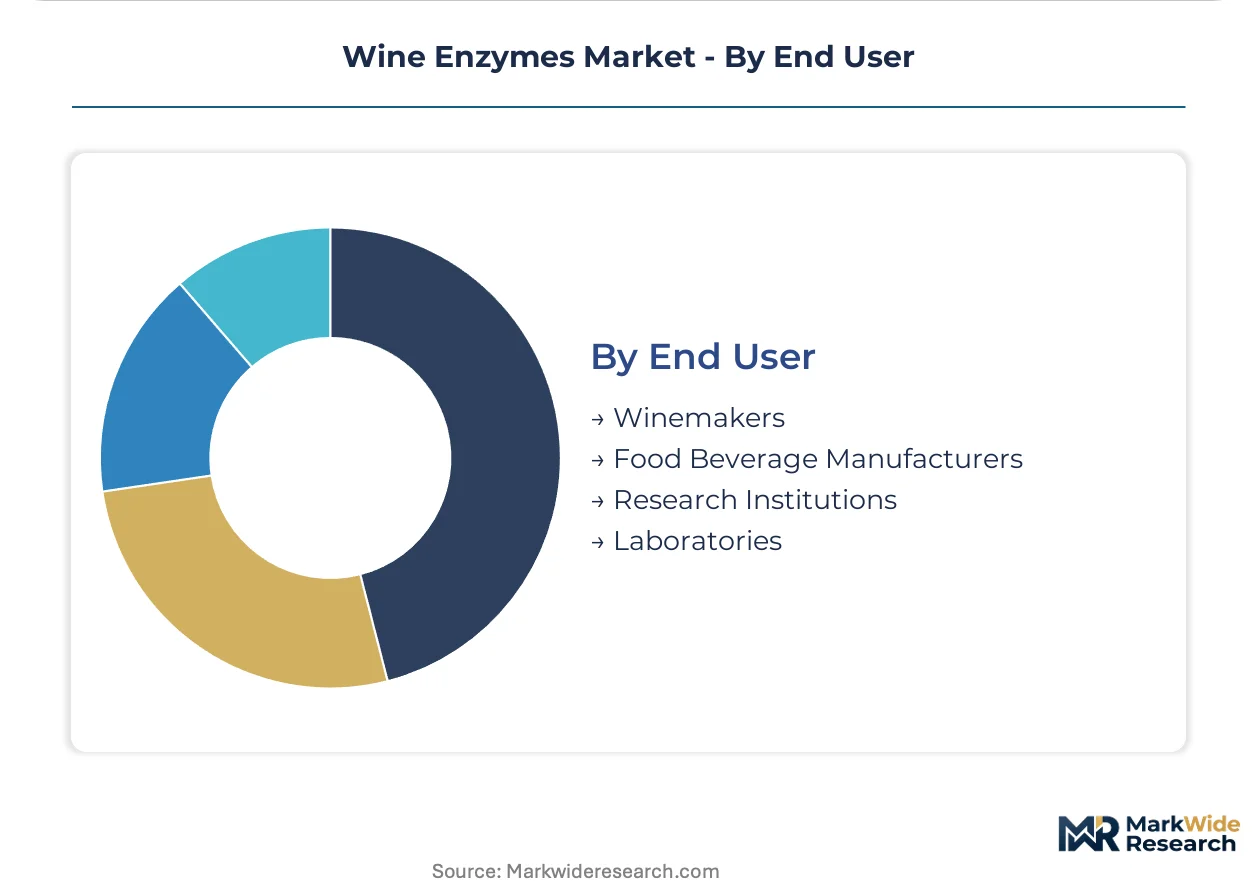
End User:
Operational scale and regulatory exposure shape enzyme specification requirements across buyer categories.
- Winemakers:Commercial cellar operations drive specification development, with French and Italian cooperatives consolidating procurement through regional consortiums. EFSA-compliant documentation requirements filter supplier access.
- Food Beverage Manufacturers:Integrated beverage groups leverage enzyme synergies across wine, cider, and fruit juice operations.
- Research Institutions:Academic enology programs in Spain and Italy evaluate novel microbial strains for fermentation efficiency gains.
- Laboratories:Analytical service providers utilize reference-grade enzymes for method validation and quality control protocols.
Winemakers anchor demand concentration; research institutions expand fastest as EU Green Deal funding accelerates biocatalytic innovation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands premium enzyme volumes through Bordeaux and Burgundy cooperatives, while Italy's Tuscan and Piedmont clusters drive faster adoption curves through modernized cellar infrastructure.
France
Bordeaux châteaux and Burgundy négociants anchor European pectinase consumption through extended maceration protocols. EFSA novel food consultation timelines shape supplier qualification windows for new microbial strains. The Médoc cooperative network consolidates procurement authority, pressuring formulators to deliver combined price-performance-certification scoring.
Italy
Tuscan and Piedmont wineries deploy cellulase-pectinase co-formulations to standardize extraction across variable harvest conditions. REACH toxicological dossier requirements under ECHA filter non-compliant suppliers from cooperative purchasing agreements. The Consorzio Chianti Classico region formalizes preferred supplier lists based on organic certification and carbon footprint disclosure.
Spain
Rioja and Catalonia drive sensor-driven maceration control adoption, integrating liquid pectinase with automated pressing sequences. EU F-Gas Regulation phase-down schedules tighten processing aid documentation thresholds. The Rioja regulatory council mandates supply chain tier verification for enzyme carbon footprints across member bodegas.
United States
California's Napa and Sonoma premium channels require USDA National Organic Program certification for processing aids, opening price-premium positioning for GRAS-notified variants. FDA enzyme safety assessments shape market access timelines for new fermentation-grade preparations. The Central Valley contract winemaking sector bundles yeast-enzyme offerings to reduce cellar labor costs.
Australia
Barossa Valley and Margaret River producers face thermal stability constraints during warm-climate harvests, restricting enzyme efficacy without refrigeration infrastructure. The country's national food standards code governs processing aid labeling requirements for export-bound wines. South Australian cooperative wineries pilot powder formulation adoption to eliminate cold-chain dependency in distributed procurement networks.
Wine Enzymes Market Competitive Landscape
European producers anchor the premium certification tier; North American specialists hold positions in GRAS-notified and organic-compliant segments. The vendor base concentrates around fermentation-grade capacity holders with EFSA-compliant documentation capabilities. Three archetypes dominate: microbial platform specialists, yeast-enzyme bundlers, and diversified ingredient conglomerates with cross-category enzyme portfolios. Competitive moves center on cooperative purchasing alliance penetration and lifecycle-certified production facility investment.
Within the microbial platform tier, Novozymes A/S and Amano Enzyme Inc. represent high-activity fermentation specialists serving automated cellar systems. DSM-Firmenich and BASF SE occupy positions among diversified ingredient conglomerates leveraging cross-category biocatalytic expertise. Lallemand Bio-Ingredients exemplifies the yeast-enzyme bundler archetype, addressing operational simplification needs among mid-sized contract winemakers.
| Leading Market Players |
|---|
| BASF SE |
| Associated British Foods plc |
| Novozymes A/S |
| Chr. Hansen Holding A/S |
| Lallemand Bio-Ingredients |
| DSM-Firmenich |
| Amano Enzyme Inc. |
| International Flavors & Fragrances |
| DuPont de Nemours |
| Others |
Value Network & Pricing Analysis
Automated dosing system integration in French and Italian cooperative cellars compresses labor costs while elevating enzyme specification requirements, simultaneously reshaping procurement economics and concentrating supplier qualification authority among EFSA-compliant fermentation specialists. This technological transition tightens margin structures for non-certified formulators while rewarding lifecycle-certified producers with preferred supplier status.
Pricing Analysis
Capacity additions in Denmark and the Netherlands are reshaping price floors for fermentation-grade pectinase, intensifying competition among microbial platform specialists. Pricing stratifies across organic-certified premium tiers, EFSA-compliant standard grades, and economy formulations for commodity wine channels. Cost compression in standard-grade liquid pectinase reflects Aspergillus niger substrate volatility. Artisanal producers in emerging regions exhibit highest price sensitivity; Bordeaux cooperative networks prioritize certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Lyon, Milan, and Barcelona coordinate hub-and-spoke patterns for liquid enzyme deliveries to automated cellar systems. Manufacturing concentrates in Denmark, the Netherlands, and Germany, with fermentation substrate sourcing drawn from agricultural commodity markets in France and Spain. Single-source vulnerability persists for high-activity pectinase strains. Distribution runs through cooperative purchasing alliances that consolidate procurement authority across French and Italian vineyard clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine enzymes function as a stable compounder anchored by regulatory disclosure mandates that perpetually refresh demand for certified formulation upgrades. Premiumization in traditional-method sparkling segments extends enzymatic processing into higher-value production tiers.
For Market Incumbents: Extend EFSA-compliant documentation capabilities to capture cooperative purchasing consolidation in Bordeaux and Rioja. Invest in lifecycle-certified production facilities ahead of EU Green Deal carbon disclosure deadlines. Deepen backward integration into Aspergillus niger strain development to insulate margin structures from agricultural feedstock volatility. For New Entrants and Emerging Players: Enter via powder formulation specialization targeting Australian and South American distributed procurement networks lacking cold-chain infrastructure. White-space concentrates in organic-certified glucose oxidase for American premium white wine channels. Lead with yeast-enzyme bundling to address operational simplification needs among mid-sized contract winemakers. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified ingredient conglomerates with underutilized fermentation capacity. Long-term viability rests on regulatory compliance moats rather than technological differentiation. Target microbial platform specialists with EFSA novel food consultation track records. Watch EU F-Gas Regulation phase-down schedules as inflection indicators for organic-compliant certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Consultation Track Record | Accelerates market entry timelines for new microbial strain formulations by 12-18 months. |
| Lifecycle-Certified Production Facility Investment | Secures preferred supplier status under EU Green Deal agricultural sustainability protocols. |
| Yeast-Enzyme Bundling Partnership | Addresses operational simplification needs among mid-sized contract winemakers in California. |
| Backward Integration into Strain Development | Reduces dependency on Aspergillus niger feedstock volatility from agricultural commodity cycles. |
| Automated Dosing System Integration | Captures specification authority in French and Italian cooperative cellar modernization programs. |
Research Methodology
Bottom-up winemaker procurement modeling reconciled against top-down fermentation-grade capacity tracking forms the analytical core. Primary interviews with cellar managers at Bordeaux châteaux, technical directors at Italian cooperative wineries, procurement leads at Spanish bodega consortia, and R&D heads at enzyme formulators combined with secondary validation from EFSA novel food consultation databases, REACH toxicological dossier filings, USDA National Organic Program certification records, and EU F-Gas Regulation disclosure registries.
Input-output matrices map enzymatic activity demand across type, application, form, and end-user segments throughout the forecast period. Modeled dimensions include pectinase/cellulase/protease/glucose oxidase categories, red/white/sparkling/fortified wine production protocols, liquid/powder/granular/tablet formats, and winemaker/food beverage manufacturer/research institution/laboratory buyer archetypes. CAGRs derive from segmented volume projections calibrated against historical cooperative purchasing data and regulatory compliance timelines. Forecast inputs incorporate cold-soak maceration protocol adoption curves and organic certification penetration rates.
Inputs from EFSA consultation timelines and REACH dossier disclosures were available through the study window; gaps in proprietary fermentation yield data introduce uncertainty bands around capacity expansion assumptions. Forecasts reflect documented assumptions regarding regulatory phase-down schedules and cooperative purchasing consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market