
 France Online Gambling Market | 2026-2036
France Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
France Online Gambling Market Intelligence
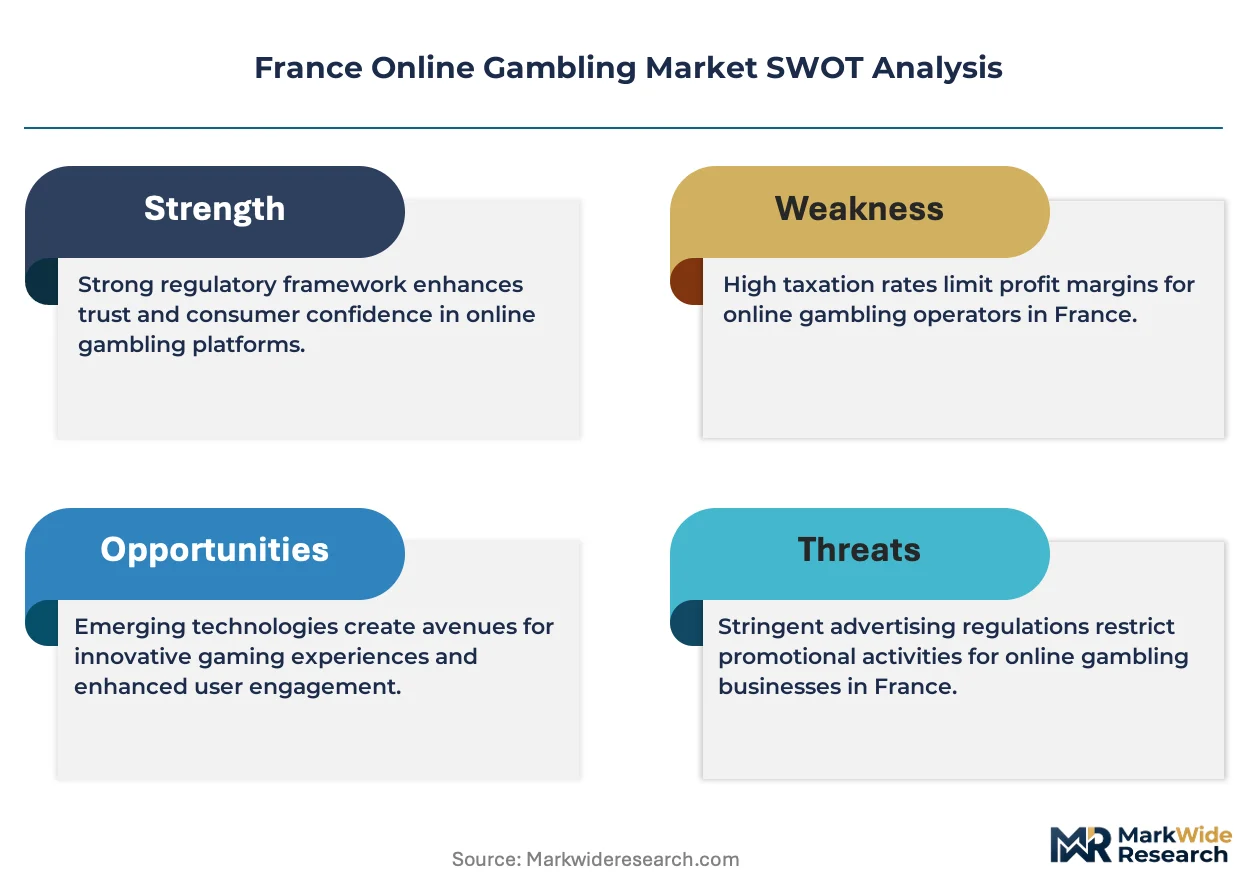
Asset-light platform licensing is narrowing the capital barrier for new entrants in France's regulated online gambling space. Winamax leverages its proprietary technology stack to sustain margin efficiency across poker and sports betting verticals. Française des Jeux anchors its position through state-backed retail-to-digital channel control and exclusive lottery rights. Betclic competes aggressively on brand visibility and football sponsorship density.
France online gambling comprises digitally delivered wagering and gaming services operating under the national regulatory framework, requiring certified random number generators, mandatory player identity verification, and real-time transaction monitoring to ensure consumer protection and fiscal compliance. The primary commercial purpose is to generate tax revenue for the state while channeling consumer betting activity away from unlicensed operators. Sports betting dominates transaction volume among product type categories, reflecting France's deep football culture and year-round racing calendars. Mobile device type access captures the fastest growth trajectory as 5G infrastructure expands and younger players abandon desktop interfaces. E-wallets within payment method segments command disproportionate operator attention due to lower chargeback rates and faster KYC integration than traditional bank transfers.
ANJ, France's national gambling authority, enforces advertising restrictions and loss-limit protocols that directly constrain operator marketing budgets and player acquisition economics. GDPR compliance adds data governance costs across customer type segmentation, particularly for VIP database management and cross-platform tracking. The country's anti-money laundering cell within Tracfin coordinates with licensed platforms on suspicious transaction reporting. Stakeholders must monitor pending European Court rulings on cross-border licensing recognition that could disrupt France's closed regulatory perimeter.
Market Dynamics
Mobile-first platform migration is compressing operator technology refresh cycles while ANJ advertising restrictions force customer acquisition toward owned-channel content and affiliate partnerships. The tension between margin pressure and compliance investment defines current strategic positioning.
Growth Catalysts
- 5G infrastructure deployment:Metropolitan France's network densification enables sub-second live betting latency previously impossible on 4G networks. Younger demographics in Paris-Ile-de-France and southern coastal corridors adopt these enhanced mobile experiences fastest.
- ARJEL successor framework:The unified regulatory architecture streamlines multi-vertical licensing and reduces compliance fragmentation for operators holding both poker and sports betting certificates. Player fund segregation mandates build institutional trust.
- Football calendar density:Ligue 1, Coupe de France, and UEFA competition schedules create year-round wagering inventory unmatched by seasonal American sports. Racing maintains its traditional audience through PMU integration.
Market Restraints
- Payment processor concentration:French-licensed operators depend on a narrow pool of PSD2-compliant payment service providers, creating single-point-of-failure risk for deposit flows. E-wallet KYC integration timelines extend onboarding friction.
- Advertising volume caps:ANJ-imposed loss-limit protocols and broadcast restrictions constrain brand visibility spend to levels below unlicensed competitor budgets. Customer acquisition costs absorb disproportionate revenue share.
- Cross-border arbitrage:European Court pending rulings on licensing mutual recognition threaten France's closed perimeter model. Maltese and Curaçao-based platforms capture marginal players seeking bonus-driven incentives.
Strategic Opportunities
- Provincial market penetration:Auvergne-Rhône-Alpes and Occitanie regions show smartphone penetration growth exceeding Paris saturation levels. Digital infrastructure investment in secondary cities precedes operator market entry.
- Esports wagering verticals:Regulatory frameworks for competitive gaming remain underdeveloped relative to traditional sports. ANJ consultation processes suggest potential 2027-2028 authorization timelines.
- Blockchain settlement rails:Stablecoin integration for withdrawals addresses chargeback elimination and weekend settlement acceleration. GDPR-compliant wallet architectures resolve data residency requirements.
Industry Challenges
- Responsible gaming engineering talent:Real-time behavioral analytics and automated intervention system development requires scarce machine learning specialists. Operators compete with fintech and ad-tech for Paris-based data science profiles.
- Legacy platform migration:Desktop-era technology stacks require complete rebuilds to achieve mobile-native performance. Flash-based poker clients and aging sportsbook architectures demand capital-intensive replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Online Gambling Market |
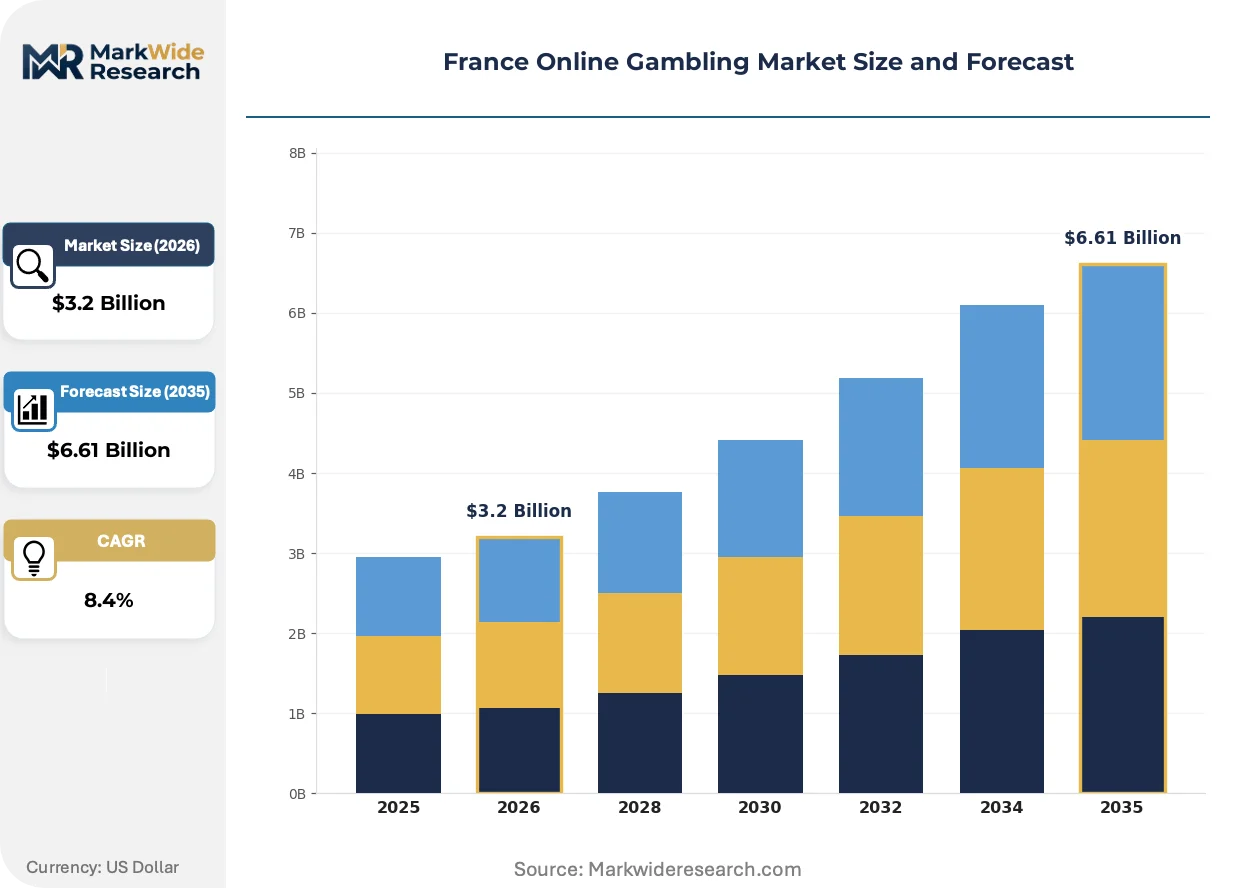
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Betting, Casino Games, Poker, Bingo Customer Type: Casual Players, High Rollers, VIPs, New Users Device Type: Mobile, Desktop, Tablet, Wearable Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cryptocurrencies |
| Companies Covered | Française des Jeux (FDJ), PMU, Winamax, Unibet, Betclic, Parions Sport, Genybet, ZEturf, M Bet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Online Gambling Market Strategic Shifts & Innovations
Artificial intelligence personalization engines and biometric authentication protocols are redefining player experience standards while regulatory technology automates compliance workflows. These shifts compress competitive differentiation timelines.
Edge computing deployment for live odds calculation is collapsing latency thresholds between stadium event occurrence and wager acceptance. Tier-1 operators in Paris-Ile-de-France deploy micro-data centers within 50 kilometers of major sporting venues. Millisecond advantages in in-play markets now determine premium player retention economics.
ANJ's strengthened player protection mandates require real-time deposit monitoring and automated cooling-off triggers. Operators must integrate behavioral analytics engines that flag at-risk patterns before manual intervention becomes viable. Smaller platforms lacking proprietary responsible gaming technology face partnership or acquisition pressure from compliance-capable competitors.
Younger demographics abandon desktop interfaces entirely, forcing platform design prioritization of thumb-optimized single-hand navigation. Affiliate marketing displaces traditional broadcast advertising as the primary acquisition channel under ANJ restrictions. Southern coastal cities from Marseille to Nice demonstrate the highest mobile session frequency metrics, shaping regional content and promotion strategies.
France Online Gambling Market Segmentation
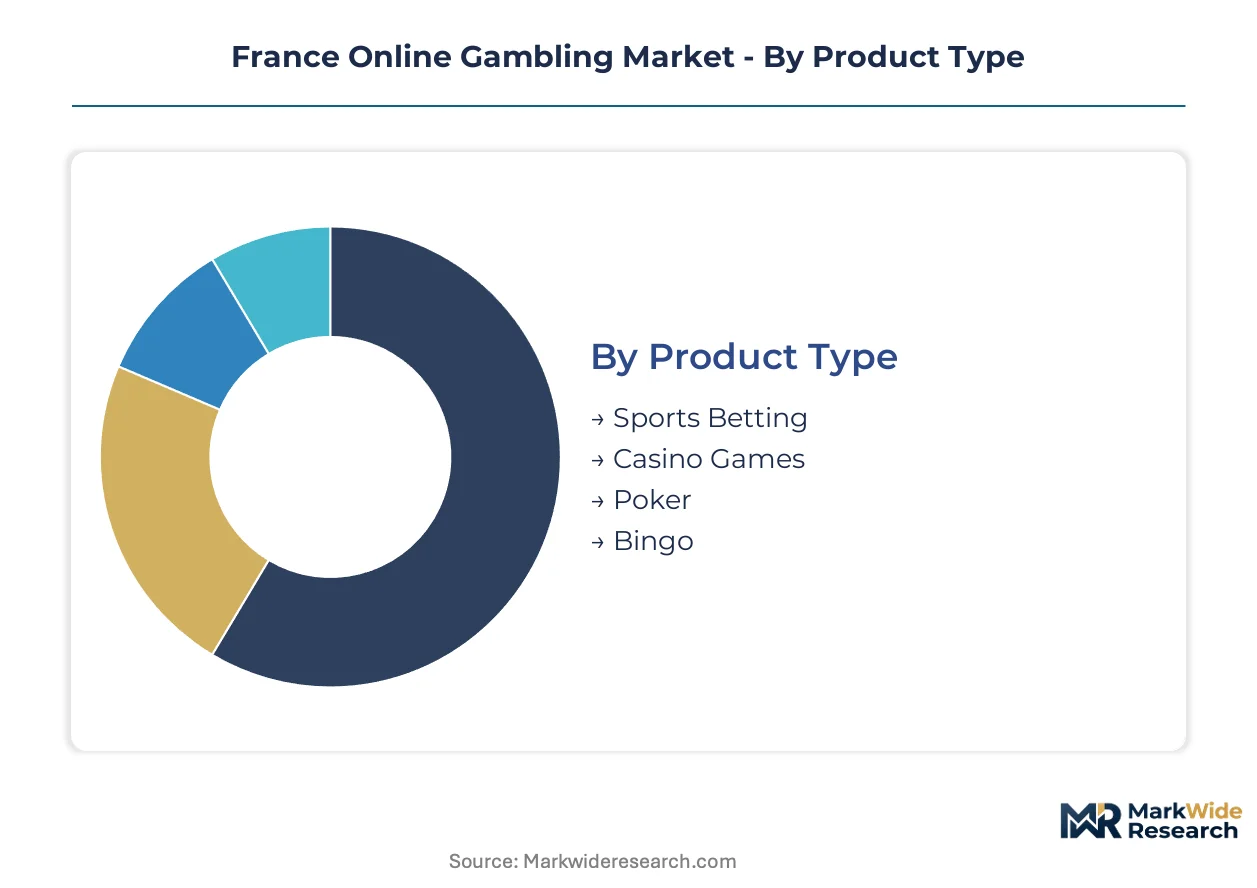
Segmentation in France's regulated online gambling market reveals distinct operational economics across player profiles and access modes. ANJ compliance requirements and payment infrastructure constraints create divergent margin structures that reshape competitive priorities.
Product Type:
Sports betting cycles through inventory fastest with daily match schedules, while casino games and poker exhibit slower player migration patterns between platforms.
- Sports Betting:Real-time wagering on football, tennis, and racing dominates transaction velocity. Paris-Ile-de-France corridors and southern coastal cities from Marseille to Nice generate the highest per-capita stakes, driven by Ligue 1 seasonality and PMU heritage integration.
- Casino Games:Certified random number generator slots and live dealer tables operate on extended session durations. Auvergne-Rhône-Alpes secondary cities show rising adoption as digital infrastructure catches metropolitan benchmarks.
- Poker:Tournament and cash game formats retain player loyalty across longer engagement cycles. Occitanie regions demonstrate growth in smartphone-native participation.
- Bingo:Lower-frequency vertical with demographic concentration among older digital adopters. Regulatory frameworks limit promotional flexibility relative to other categories.
Sports betting dominates installed base. Casino games is where expansion concentrates.
Customer Type:
Acquisition cost tiers separate casual players from VIP segments, with compliance overhead distributed unevenly across verification depth requirements.
- Casual Players:Low-stakes, high-churn participants acquired through affiliate channels. GDPR-compliant onboarding friction in Paris metropolitan areas exceeds secondary city benchmarks.
- High Rollers:Elevated deposit thresholds trigger enhanced due diligence protocols. ANJ loss-limit mandates constrain maximum exposure per session.
- VIPs:Dedicated account management and behavioral monitoring investment. Real-time intervention systems flag at-risk patterns before manual review.
- New Users:Identity verification bottlenecks extend first-deposit timelines. KYC integration with PSD2-compliant payment rails determines conversion efficiency.
Casual players absorb disproportionate marketing spend. VIPs deliver margin concentration despite smaller population share.
Device Type:
Technology refresh cycles compress fastest in mobile, where 5G deployment resets performance baselines annually.
- Mobile:Thumb-optimized interfaces capture younger demographics entirely. Sub-second live betting latency in 5G-dense corridors from Lyon to Toulouse enables in-play market leadership.
- Desktop:Legacy Flash-based poker clients require complete platform rebuilds. Aging sportsbook architectures face capital-intensive replacement pressure.
- Tablet:Intermediate form factor retaining casino game preference among home-based sessions. Screen real estate supports multi-table poker visibility.
- Wearable:Emerging notification layer for bet alerts and account monitoring. Regulatory restrictions on display size limit wagering functionality.
Mobile commands development priority. Desktop carries technical debt concentration.
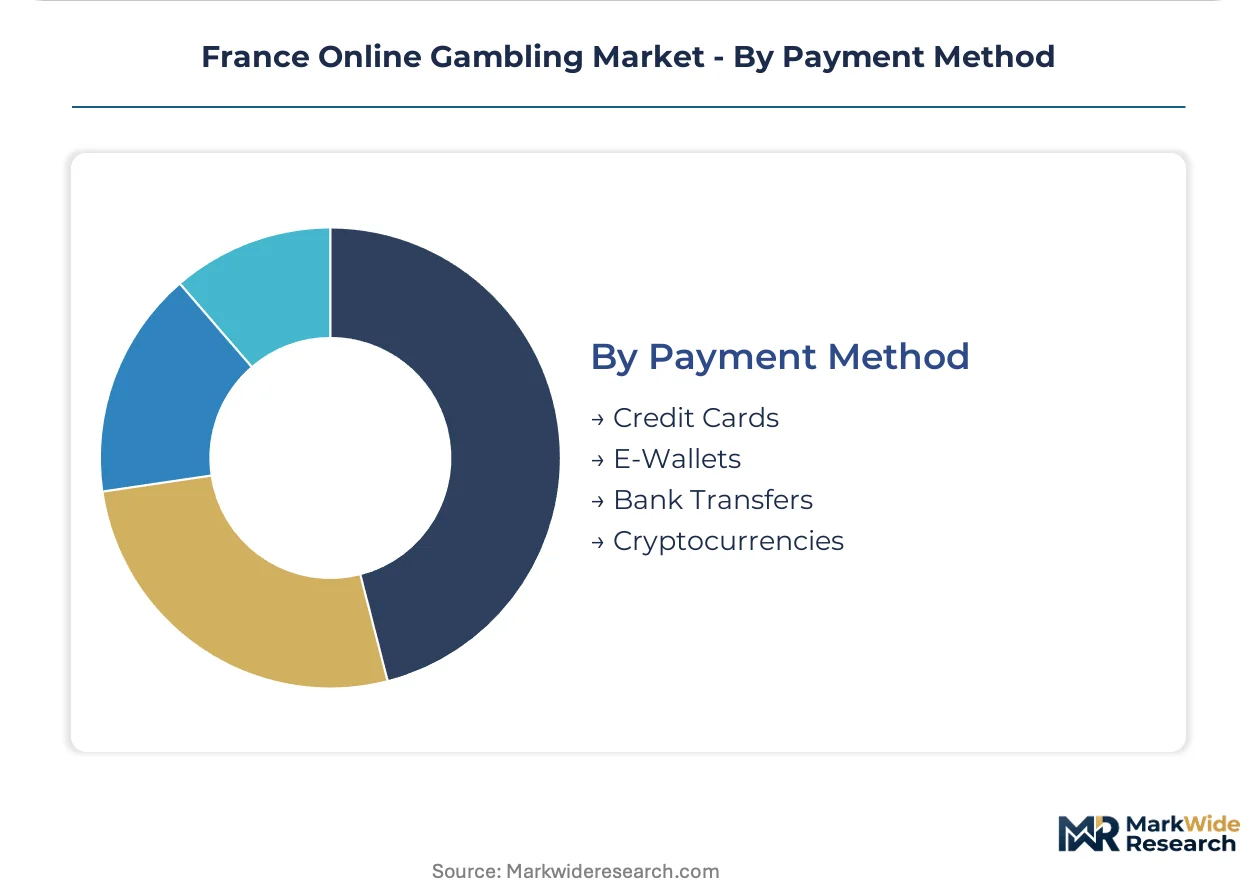
Payment Method:
Settlement speed and chargeback exposure separate cost tiers, with compliance integration timelines varying sharply across provider categories.
- Credit Cards:Traditional rails with elevated chargeback rates and extended settlement windows. Major French banking networks maintain deposit flow dominance despite friction.
- E-Wallets:Faster KYC integration and lower fraud exposure command operator preference. Narrow PSD2-compliant provider pool creates concentration risk.
- Bank Transfers:SEPA-based deposits carry longest onboarding delays. Institutional trust sustains usage among risk-averse demographic segments.
- Cryptocurrencies:Stablecoin withdrawal pilots address weekend settlement gaps. GDPR-compliant wallet architectures remain under regulatory consultation.
E-wallets gain share fastest among new user acquisition. Credit cards retain legacy deposit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANJ's unified regulatory architecture and player protection mandates are reshaping operator obligations across French metropolitan zones. Tax revenue generation priorities and channeling objectives against unlicensed platforms drive policy calibration. Digital infrastructure investment in secondary corridors precedes market entry by licensed platforms.
Île-de-France
Paris-Ile-de-France corridors generate the highest per-capita stakes through Ligue 1 seasonality and concentrated disposable income. ANJ advertising restrictions and loss-limit protocols constrain brand visibility spend below unlicensed competitor budgets. Edge computing deployment within 50 kilometers of major sporting venues enables sub-second live betting latency for tier-1 operators.
Auvergne-Rhône-Alpes
Lyon and secondary cities demonstrate smartphone penetration growth exceeding Paris saturation levels. 5G network densification enables enhanced mobile experiences with sub-second latency previously impossible on 4G. Casino game adoption rises as digital infrastructure catches metropolitan benchmarks.
Provence-Alpes-Côte d'Azur
Southern coastal cities from Marseille to Nice exhibit the highest mobile session frequency metrics. Younger demographics abandon desktop interfaces entirely in this corridor. Regional content and promotion strategies concentrate on thumb-optimized single-hand navigation for football and racing wagering.
Occitanie
Toulouse anchors smartphone-native participation growth in poker and sports betting verticals. Digital infrastructure investment precedes operator market entry in this secondary corridor. GDPR-compliant onboarding friction remains below Paris metropolitan benchmarks.
Nouvelle-Aquitaine
Bordeaux and Atlantic coastal zones show rising adoption of certified random number generator slots and live dealer tables. SEPA-based deposits sustain usage among risk-averse demographic segments. Affiliate marketing displaces traditional broadcast advertising as primary acquisition channel under ANJ restrictions.
France Online Gambling Market Key Industry Players
On the supply side, the industry is consolidating around three distinct competitive tiers defined by regulatory compliance depth and technology ownership. State-backed incumbents leverage exclusive lottery rights and retail-to-digital channel control. Proprietary technology specialists sustain margin efficiency through in-house platform stacks. Brand-heavy operators compete on sponsorship density and football visibility. Capacity expansion through micro-data center deployment and strategic partnerships with PSD2-compliant payment rails constitute dominant competitive moves.
Within the state-backed tier, Française des Jeux anchors position through retail-to-digital channel control and exclusive lottery rights. Among proprietary technology specialists, Winamax occupies a position exemplifying margin efficiency through in-house platform development across poker and sports betting verticals. On the brand-visibility vector, Betclic represents aggressive positioning through football sponsorship density and metropolitan marketing concentration.
| Leading Market Players |
|---|
| Française des Jeux (FDJ) |
| PMU |
| Winamax |
| Unibet |
| Betclic |
| Parions Sport |
| Genybet |
| ZEturf |
| M Bet |
| Others |
Cost & Logistics Intelligence
Overcapacity in Paris-Ile-de-France server infrastructure drives hosting cost compression while forcing tier-2 operators toward outsourced platform partnerships. ANJ compliance investment requirements create fixed cost absorption disparities that reshape competitive pricing postures across metropolitan and secondary corridors.
Pricing Analysis
Certification level under ANJ's unified regulatory architecture creates the primary spread between tier-1 and tier-2 operators. Three-tier pricing structure across premium, standard, and economy levels segments player acquisition economics, with VIP account management commanding premium service bundles. Cost compression in affiliate channel payments is intensifying because ANJ advertising caps constrain owned-media alternatives. Casual players exhibit highest price sensitivity to deposit friction, while high rollers absorb premium pricing for dedicated account infrastructure.
Supply Chain Analysis
Tariff exposure between Malta and France on cross-border payment processing dominates operational risk planning for licensed operators. Technology sourcing draws from Ireland, Estonia, and domestic Paris-based development clusters for platform engineering. PSD2-compliant e-wallet rails, random number generator certification services, and edge computing micro-data centers constitute critical input dependencies. Single-source vulnerability concentrates in the narrow pool of certified payment service providers. Distribution runs through affiliate partner networks and owned mobile applications rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's online gambling market sits at a platform-economics inflection where proprietary technology ownership separates margin-sustainable competitors from outsourced-stack operators. The shift toward API-first wallet integration and cross-operator player fund portability redefines ecosystem control points.
For Market Incumbents: Pre-empt margin erosion from asset-light entrants by deepening in-house responsible gaming technology development and securing exclusive data center partnerships within 50 kilometers of major sporting venues. ANJ's strengthened player protection mandates threaten operators lacking proprietary behavioral analytics engines. Vertical integration into edge computing infrastructure preserves live betting latency advantages against competitors dependent on third-party hosting.
For New Entrants and Emerging Players: Build out white-space positions in Occitanie and Auvergne-Rhône-Alpes secondary cities where smartphone penetration growth exceeds Paris saturation and GDPR-compliant onboarding friction runs lower. Esports wagering verticals present the most penetrable regulatory gap, with ANJ consultation timelines suggesting authorization windows ahead of established competitors. A mobile-native, thumb-optimized platform architecture targeting football and racing verticals bypasses desktop-era technical debt carried by incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because France's closed licensing perimeter and ANJ compliance depth requirements create sustainable moats against cross-border arbitrage. Acquisition targets should display proprietary platform stacks with integrated responsible gaming technology and established PSD2-compliant payment rail relationships. The signal to watch is European Court rulings on licensing mutual recognition that could disrupt perimeter economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Technology Acquisition | Proprietary stack ownership preserves margin efficiency against outsourced-stack competitors under ANJ cost pressures. |
| Edge Computing Infrastructure Deployment | Micro-data centers within 50 kilometers of Ligue 1 venues enable sub-second live betting latency leadership. |
| Responsible Gaming Technology Investment | Real-time behavioral analytics engines satisfy ANJ automated intervention mandates and reduce manual compliance headcount. |
| PSD2 Payment Rail Partnership | E-wallet integration with certified providers reduces chargeback exposure and accelerates KYC onboarding conversion. |
| Provincial Market Geographic Expansion | Secondary city entry in Occitanie and Auvergne-Rhône-Alpes captures smartphone penetration growth ahead of competitor saturation. |
Research Approach
A standing panel of platform engineering directors, ANJ regulatory affairs leads, affiliate network operators, and payment service provider executives provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against ANJ enforcement bulletins, operator licensing disclosures, Tracfin suspicious transaction reports, and 5G infrastructure deployment databases. Bottom-up player segmentation analysis and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around ANJ advertising restriction severity and European Court licensing recognition outcomes bounded the forecast range across the analysis window. Segmentation dimensions modeled include product type, customer tier, device access mode, payment method, and regional infrastructure maturity. CAGRs derived from technology adoption S-curves and regulatory event probability weighting. Industry-specific inputs incorporated PMU racing calendar density, Ligue 1 broadcast rights cycles, and edge computing latency benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Maltese-licensed cross-border platforms or blockchain settlement innovators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
United States Gaming Accessories Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
South Asia Mobile Gaming Market
Gaming
China in-Game Advertising Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Global Battle Royale Games Market
Gaming
Online Casino Market
Gaming
Europe Gaming Peripherals Market
Gaming
Lottery Market
Gaming
H5 Games Market
Gaming
Mobile MOBA Games Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Game API Market
Gaming
Game Applications Market
Gaming
Mobile Gaming Market
Gaming
VR Racing Gaming Market