
 United Kingdom Online Gambling Market | 2026-2036
United Kingdom Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Online Gambling Market Intelligence
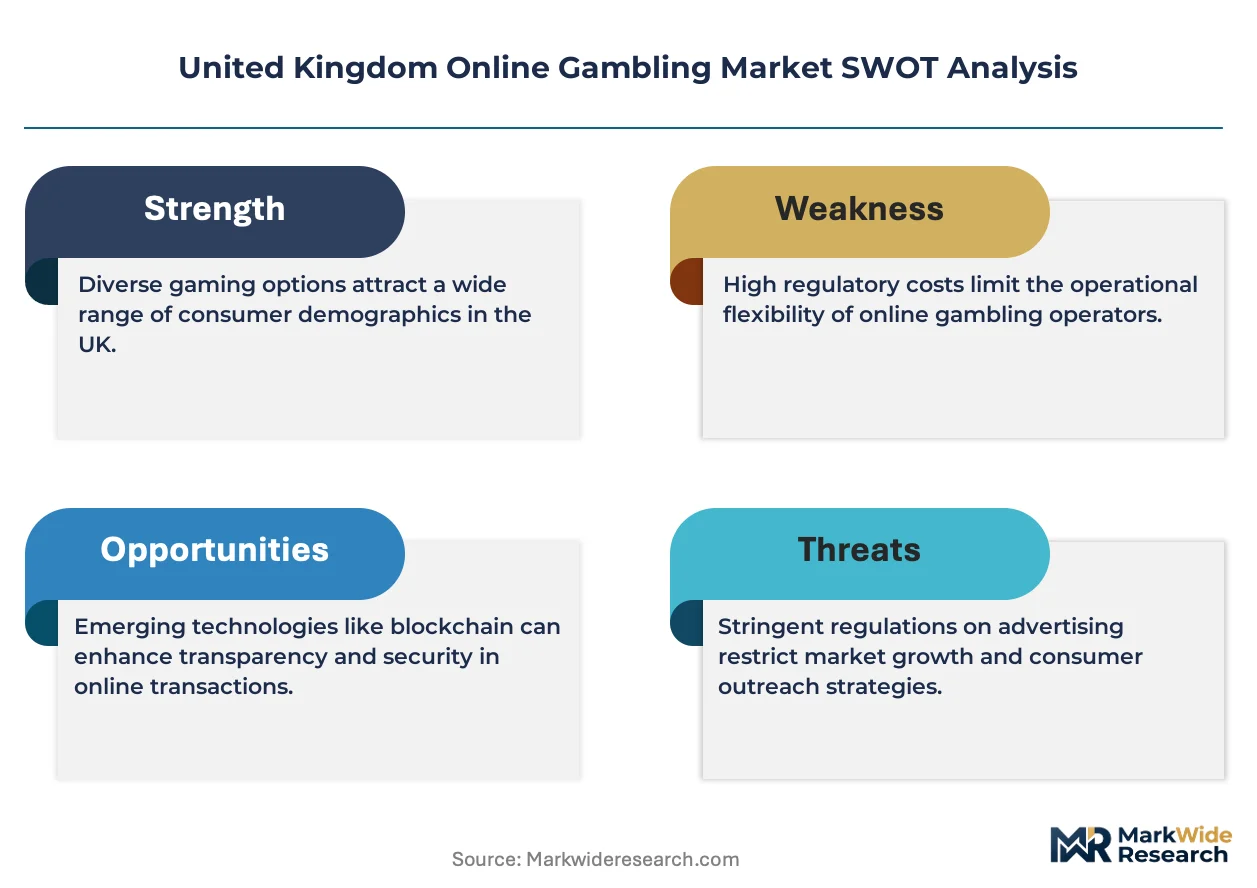
The Gambling Commission's affordability check mandate is rebalancing capital requirements for new market entrants. Flutter Entertainment PLC leverages its vertically integrated sportsbook technology to sustain margin resilience under tighter compliance. Entain PLC anchors its position through proprietary platform infrastructure that navigates evolving player protection protocols. Bet365 competes via deep specialization in in-play wagering algorithms that differentiate its real-time product suite.
United Kingdom online gambling denotes digitally delivered wagering services encompassing remote sports betting, casino gaming, poker tournaments, and bingo sessions conducted via internet-connected devices, with platforms employing random number generation certification and SSL encryption protocols to ensure transactional integrity and game fairness. The primary commercial purpose centers on monetizing entertainment engagement through house-edge mechanics while capturing recurring player activity via loyalty architectures. Sports betting dominates transaction volume among product type segments, reflecting embedded cultural affinity for football and horse racing wagering. Mobile device usage leads platform access patterns, with smartphone-optimized interfaces displacing desktop engagement across casual gambler and high roller customer type segments alike.
The UK Gambling Commission enforces licensing conditions under the Gambling Act 2005, while the Competition and Markets Authority scrutinizes promotional fairness and the Advertising Standards Authority governs marketing content across broadcast and digital channels. These frameworks elevate operational compliance costs but simultaneously consolidate market access around licensed incumbents with established responsible gambling infrastructure. Stakeholders must monitor pending legislative revisions to the Gambling Act, as prospective stake limits and advertising restrictions threaten to reshape revenue architecture across the licensed operator base.
Market Dynamics
The Gambling Commission's affordability check mandate is compressing operator margins while simultaneously raising barriers for unlicensed competitors. This regulatory pivot forces capital reallocation toward compliance infrastructure and player protection systems.
Growth Catalysts
- Mobile-first platform architecture:Smartphone-optimized interfaces capture casual gamblers seeking frictionless wagering access. Sports betting volumes concentrate on handheld devices.
- The Gambling Act 2005 licensing framework:Strict regulatory enforcement consolidates market access around compliant operators with established responsible gambling infrastructure.
- In-play wagering technology:Real-time odds algorithms and micro-betting capabilities sustain engagement during live football and horse racing events.
Market Restraints
- Affordability check compliance costs:The Gambling Commission's enhanced due diligence requirements inflate operational expenditure for customer verification and financial screening.
- Payment processor concentration:Reliance on a limited pool of UK-licensed financial intermediaries creates settlement friction and elevates transaction fees.
- Advertising Standards Authority restrictions:Tighter marketing content rules constrain customer acquisition channels and compress lifetime value metrics.
Strategic Opportunities
- England's metropolitan betting corridors:London, Manchester and Birmingham concentrate high-frequency gamblers with disposable entertainment budgets.
- Artificial intelligence and machine learning convergence:Predictive analytics for responsible gambling intervention and personalized retention offers differentiate operator capabilities.
- The Competition and Markets Authority's promotional fairness focus:Transparent bonus structures attract switchers from non-compliant offshore platforms.
Industry Challenges
- Responsible gambling algorithm deployment:Operators struggle to balance automated intervention triggers with player experience continuity.
- Legacy platform migration complexity:Established incumbents face technical debt when integrating real-time compliance monitoring into aging core systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Online Gambling Market |
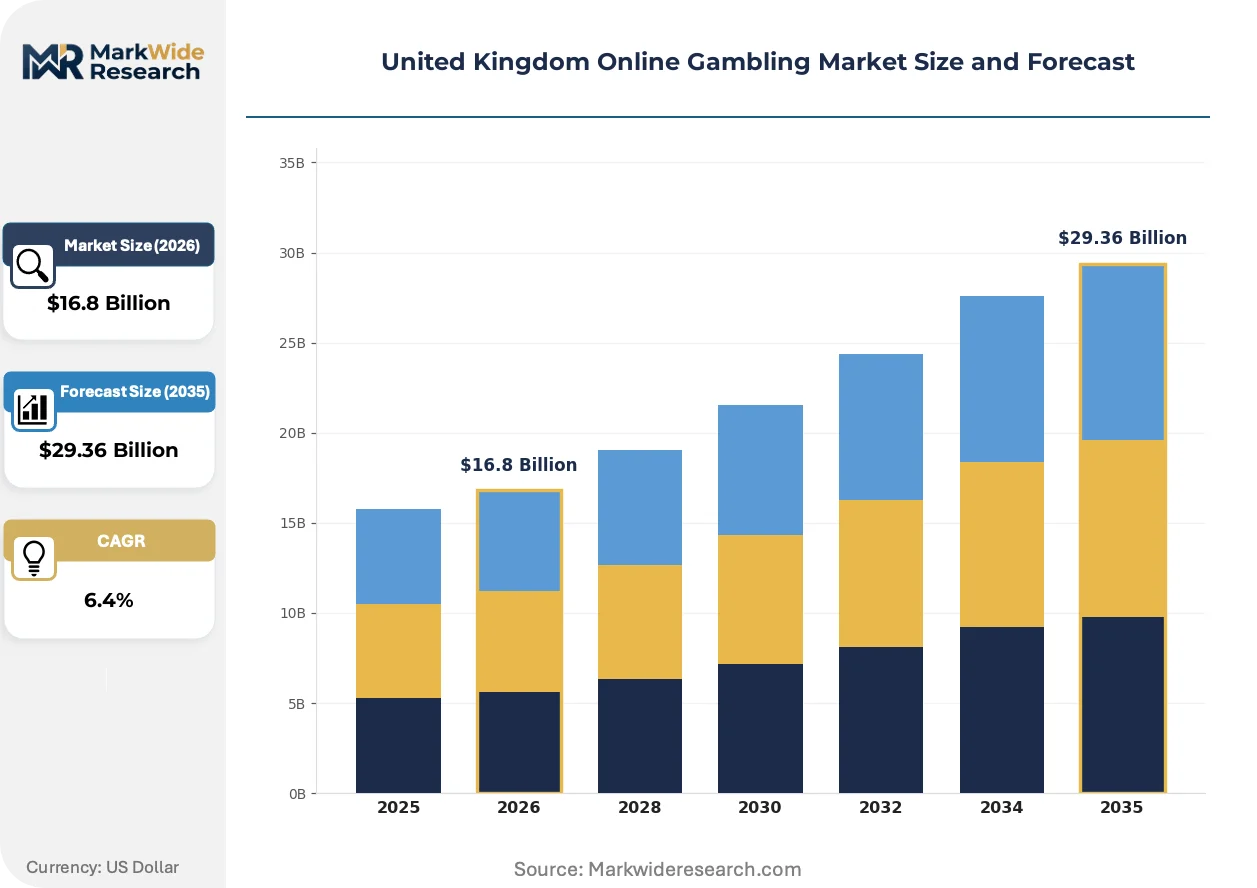
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Betting, Casino Games, Poker, Bingo Customer Type: Casual Gamblers, High Rollers, Beginners, VIP Players Payment Method: Credit Card, E-Wallets, Bank Transfer, Prepaid Cards Device Type: Desktop, Mobile, Tablet, Smart TV |
| Companies Covered | Flutter Entertainment PLC, Entain PLC, Bet365, Evoke PLC, Kindred Group PLC, Sky Betting and Gaming, Ladbrokes Coral Group, Betfred Group, Playtech PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Online Gambling Market Strategic Shifts & Innovations
Digital wagering platforms are absorbing artificial intelligence capabilities that reshape both player protection and competitive differentiation. Three interconnected developments are restructuring how operators acquire, retain, and safeguard customers.
Machine learning-based behavioral analytics is absorbing problem gambling detection responsibilities previously handled by manual review teams. Tier-one operators deploy these systems to flag at-risk patterns in real-time wagering velocity and deposit frequency. The technology is absorbing compliance burden while simultaneously reducing human oversight costs across customer monitoring functions.
The Gambling Commission's pending Gambling Act revisions are tightening stake limits and advertising windows for online slots. Licensed operators are pre-emptively restructuring revenue architecture toward sports betting and live casino products. England's digital gambling corridors face the most acute exposure given slot density in metropolitan user bases.
Betting patterns are compressing toward micro-wagering formats that align with smartphone attention spans. In-play football markets and rapid-fire horse racing pools displace traditional pre-event accumulators among casual demographics. This behavioral pivot concentrates transaction volume within London and Manchester's mobile-first user clusters.
United Kingdom Online Gambling Market Segmentation
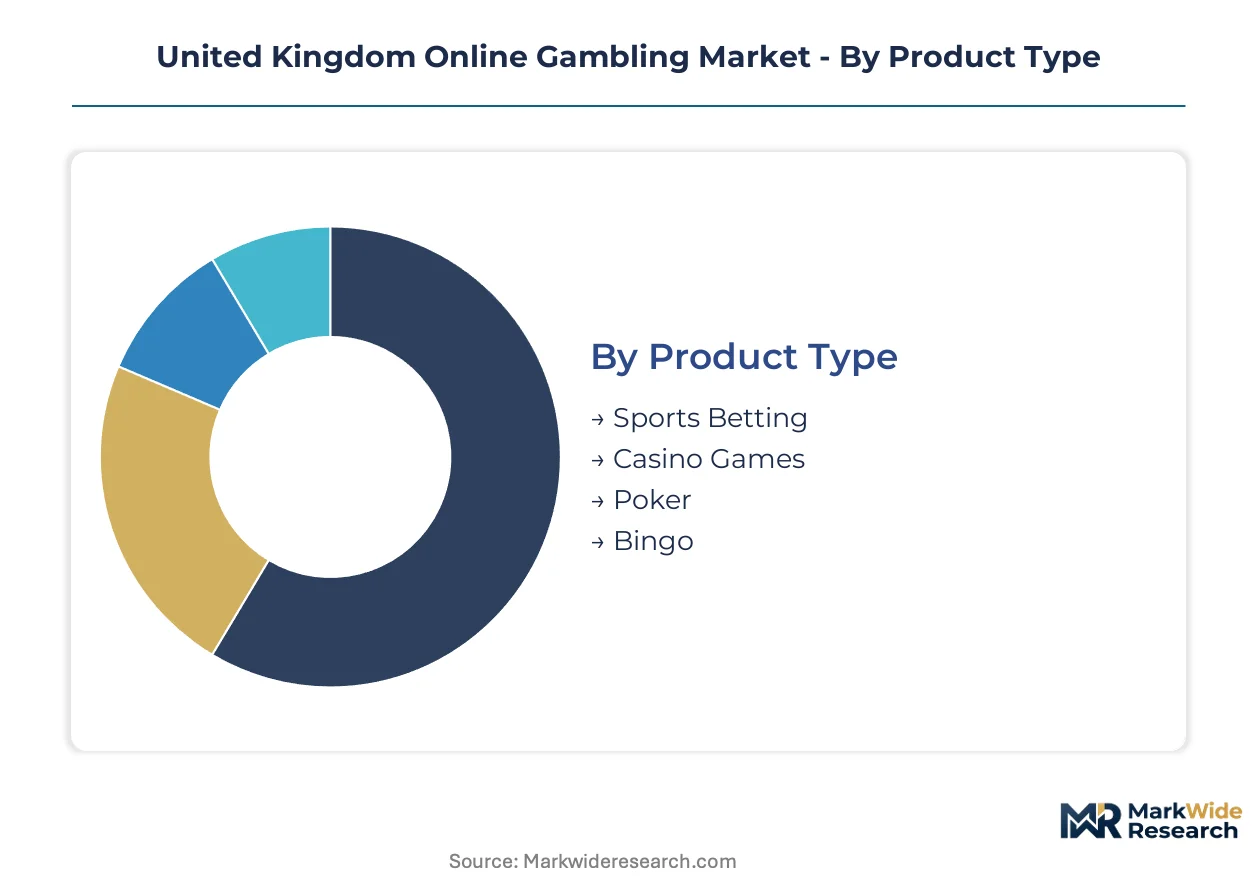
United Kingdom online gambling operators calibrate product portfolios and acquisition spend across distinct player archetypes and access modalities. Segmentation precision determines compliance cost allocation and lifetime value optimization in a tightening regulatory environment.
Product Type:
Standardized wagering mechanics dominate mass-market segments while proprietary algorithms differentiate premium offerings across this spectrum.
- Sports Betting:Real-time odds engines process football and horse racing wagers through smartphone-optimized interfaces. England's metropolitan corridors concentrate transaction density as casual demographics gravitate toward in-play micro-betting formats during Premier League and Cheltenham Festival events.
- Casino Games:Random number generation certification underpins slot, blackjack, and roulette offerings with return-to-player ratios fixed between operator margin requirements and player retention thresholds. Pending Gambling Act stake limit proposals threaten revenue architecture in London's high-frequency user clusters.
- Poker:Tournament structures and cash table liquidity pools attract skilled player segments with lower house-edge economics.
- Bingo:Session-based community wagering retains aging demographics through chat-integrated mobile platforms.
Most installed capacity flows through Sports Betting. Expansion is steepest in Casino Games.
Customer Type:
Acquisition cost tiers separate mass-market onboarding from high-touch relationship management across player lifecycle stages.
- Casual Gamblers:Smartphone-first engagement patterns drive deposit frequency through frictionless payment rails and push-notification promotional triggers. Manchester and Birmingham user clusters exhibit highest session velocity among this demographic.
- High Rollers:Dedicated account management and bespoke liability limits sustain margin contribution despite lower transaction counts. The Gambling Commission's affordability checks impose enhanced due diligence burdens on operator compliance infrastructure serving this segment.
- Beginners:Low-stake entry thresholds and tutorial content reduce churn during initial platform orientation.
- VIP Players:Invitation-only tier structures deploy hospitality budgets and exclusive event access to defend wallet share.
Volume concentrates in Casual Gamblers. Value per user climbs fastest among VIP Players.
Payment Method:
Settlement speed and regulatory scrutiny intensity vary across financial intermediary relationships.
- Credit Card:Chargeback risk and affordability verification requirements elevate operator screening costs under Gambling Commission mandates. Transaction velocity remains highest among England's metropolitan betting corridors despite regulatory friction.
- E-Wallets:PayPal, Skrill, and Neteller integration delivers instantaneous deposit settlement with reduced Know Your Customer duplication. Younger demographics in London and Manchester exhibit strongest preference for this rail.
- Bank Transfer:Higher deposit ceilings attract high-value players willing to accept settlement delays.
- Prepaid Cards:Anonymity constraints and deposit limits restrict adoption to budget-controlled recreational segments.
Transaction volume runs heaviest through E-Wallets. Compliance cost pressure is most acute for Credit Card.
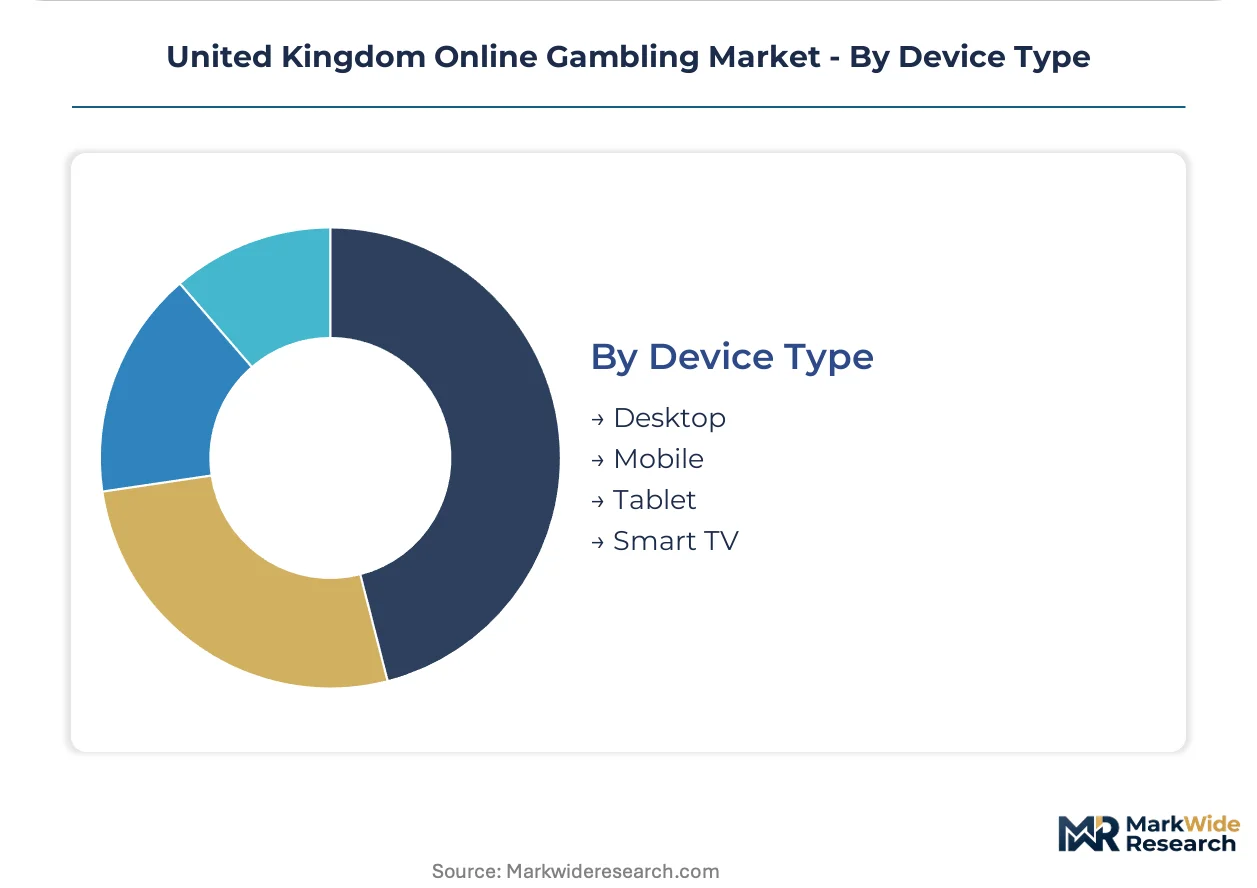
Device Type:
Screen size and connectivity assumptions shape platform development roadmaps and user experience investment priorities.
- Mobile:Portrait-optimized interfaces and biometric authentication capture commuter and in-play wagering occasions. Smartphone penetration reaches saturation across all UK demographic segments with iOS and Android OS fragmentation driving dual-platform development overhead.
- Desktop:Multi-tab research behavior and larger display real estate sustain sports analytics and casino lobby navigation among serious recreational players. Retention metrics skew older in England's regional cities outside London.
- Tablet:Touch-optimized mid-screen formats occupy niche position between mobile convenience and desktop information density.
- Smart TV:Second-screen synchronization with live broadcast sports creates experimental wagering contexts with limited mainstream adoption.
Engagement hours concentrate on Mobile. Development resource allocation tilts toward maintaining feature parity across Desktop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's online gambling industry traces its regulatory foundations to the Gambling Act 2005, which established the UK Gambling Commission and positioned the country as the world's first major jurisdiction to create a comprehensive licensing framework for remote wagering. This early-mover advantage concentrated operator headquarters, technology development, and compliance expertise within British borders before other European markets liberalized.
England
London, Manchester and Birmingham generate the highest transaction densities through metropolitan betting corridors where disposable entertainment budgets concentrate. The Gambling Commission's affordability check mandate imposes enhanced due diligence requirements on operators serving England's high-frequency user clusters. Mobile-first sports betting platforms capture commuter wagering occasions across Greater London's transport networks.
Scotland
Edinburgh and Glasgow sustain distinct player preferences toward football accumulator betting and horse racing pools that diverge from English wagering patterns. The Scottish Government's devolved public health powers enable localized responsible gambling campaigns that complement UK-wide Gambling Commission enforcement. Glasgow's urban corridors exhibit strongest adoption of e-wallet payment rails among younger demographics.
Wales
Cardiff and Swansea user clusters demonstrate elevated engagement with bingo and casino products relative to sports betting intensity seen in English markets. Welsh language accessibility requirements shape operator platform localization investments under Equality Act obligations. South Wales valleys present distinct affordability profiles that trigger Gambling Commission intervention thresholds at lower deposit velocities.
Northern Ireland
Belfast's betting market operates under distinct legislative inheritance from the Betting, Gaming, Lotteries and Amusements (Northern Ireland) Order 1985, creating regulatory friction with GB-licensed operators. The Northern Ireland Assembly's stalled gambling reform prolongs reliance on outdated physical betting shop infrastructure. Cross-border player migration to Republic of Ireland-licensed platforms fragments market data visibility.
Republic of Ireland
Dublin serves as a secondary hub for UK-facing operators seeking European Economic Area regulatory continuity post-Brexit. The Gambling Regulatory Authority of Ireland's pending establishment threatens to divert licensing revenue from UK Gambling Commission jurisdiction. Irish player pools overlap substantially with Northern Ireland demographics, complicating territorial market sizing.
United Kingdom Online Gambling Market Key Industry Players
The competitive structure tilts toward vertically integrated platform operators with proprietary technology stacks and established responsible gambling infrastructure. Tier-one incumbents absorb disproportionate compliance costs while sustaining margin resilience through scale economies in customer acquisition and retention. Three archetypes dominate: integrated sportsbook-casino conglomerates, specialized in-play wagering technology platforms, and B2B platform providers licensing infrastructure to smaller brands. Consolidation pressure intensifies through regulatory capital requirements and technology debt burdens that disadvantage sub-scale competitors.
Within the integrated operator tier, Flutter Entertainment PLC and Entain PLC exemplify the vertically integrated model that combines proprietary sportsbook technology with casino gaming infrastructure. Bet365 occupies a distinct specialization position anchored in real-time wagering algorithms. These three entities represent the dominant competitive anchors against which mid-tier operators and new entrants benchmark compliance investment and product development velocity.
| Leading Market Players |
|---|
| Flutter Entertainment PLC |
| Entain PLC |
| Bet365 |
| Evoke PLC |
| Kindred Group PLC |
| Sky Betting and Gaming |
| Ladbrokes Coral Group |
| Betfred Group |
| Playtech PLC |
| Others |
Cost & Logistics Intelligence
Platform-to-operator service bifurcation between vertically integrated proprietary stacks and white-label B2B licensing arrangements determines both customer acquisition cost structures and technology sourcing configurations across the United Kingdom online gambling market. Premium-tier operators absorbing full-stack development overhead capture margin control through reduced per-transaction platform fees, while commodity-tier brands licensing third-party infrastructure face compressed unit economics under Gambling Commission compliance cost inflation.
Pricing Analysis
Bundled full-service platform contracts dominate tier-one operator procurement, unbundled modular pricing gains traction among mid-market brands seeking flexibility. Customer lifetime value calculations and responsible gambling infrastructure certification tiers drive price differentiation between premium proprietary deployments and standard white-label arrangements. Pricing pressure intensifies in the casual gambler acquisition layer as Advertising Standards Authority restrictions elevate paid media costs. High roller relationship management commands lowest price sensitivity due to bespoke liability arrangements and dedicated account overhead.
Supply Chain Analysis
Workforce availability constraints in Malta, Gibraltar, and Isle of Man licensing jurisdictions concentrate compliance technology development and customer service operations among established operators with established recruitment pipelines. Random number generation certification, real-time odds engine computation, and payment processor API integration constitute critical input dependencies. Single-source vulnerability in UK-licensed financial intermediary relationships creates settlement friction exposure. Distribution runs through direct-to-consumer mobile applications and mobile-optimized web platforms with minimal retail intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates among operators achieving compliance cost absorption through player base scale and proprietary technology leverage, with premium-tier platform control emerging as the decisive cost-down driver separating viable incumbents from structurally disadvantaged competitors.
For Market Incumbents: Extend proprietary platform infrastructure investment to capture compliance efficiency gains unavailable to white-label dependent competitors. Deepen real-time wagering algorithm capabilities to defend against specialized in-play technology entrants. The Gambling Commission's affordability check mandate threatens margin compression for operators lacking automated player protection systems. Vertical integration into core platform technology represents the critical lever for sustaining margin resilience. For New Entrants and Emerging Players: Artificial intelligence-driven behavioral analytics capabilities offer technology-first wedge positioning against legacy operators burdened by technical debt. White-space concentration exists in responsible gambling intervention tooling and automated compliance monitoring solutions licensable to mid-tier brands. Target Manchester and Birmingham metropolitan corridors with mobile-optimized micro-betting products. Go-to-market execution should emphasize transparent bonus structures aligned with Competition and Markets Authority promotional fairness guidance. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale operators face disproportionate compliance cost burdens relative to revenue base. Long-term viability favors vertically integrated platform operators with established responsible gambling infrastructure and England metropolitan corridor market presence. Acquisition target archetype: mid-tier brands with distressed compliance cost structures but defensible player liquidity pools. Monitor Gambling Act revision legislative progression as inflection signal for stake limit and advertising restriction impact severity.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Platform Development | Captures compliance cost efficiencies under Gambling Commission affordability mandates. |
| Real-Time Wagering Algorithm Investment | Differentiates product positioning against Bet365's established in-play specialization. |
| Responsible Gambling AI Deployment | Reduces manual oversight burden while satisfying UK Gambling Commission intervention protocols. |
| Metropolitan Corridor Marketing Concentration | Targets London, Manchester, and Birmingham's high-frequency disposable entertainment budgets. |
| Payment Rail Diversification | Mitigates single-source vulnerability in UK-licensed financial intermediary relationships. |
Research Approach
Direct dialogue with chief technology officers at tier-one operators, compliance directors navigating Gambling Commission licensing conditions, platform engineering leads, and customer acquisition strategists grounded qualitative findings in operational reality. Secondary validation drew from UK Gambling Commission enforcement action records, Gambling Act 2005 statutory instruments, Advertising Standards Authority rulings, Competition and Markets Authority market studies, and operator annual report disclosures. Bottom-up transaction volume modeling and top-down regulatory impact assessment triangulated market sizing across product type, customer type, payment method, and device type segmentation dimensions.
Installed base projections and revenue architecture estimates emerged from integrated modeling across the projection horizon without reliance on single-source extrapolation. Segmentation dimensions encompassed sports betting, casino games, poker, and bingo product types; casual gambler, high roller, beginner, and VIP player archetypes; credit card, e-wallet, bank transfer, and prepaid settlement rails; plus mobile, desktop, tablet, and connected television access modalities. CAGRs derived from regression analysis against regulatory enforcement intensity, platform technology adoption curves, and metropolitan corridor disposable income trends. Forecast inputs incorporated pending Gambling Act revision legislative probability and affordability check compliance cost trajectories.
The model holds under stable UK regulatory jurisdiction and continued Gambling Commission licensing framework continuity; deviation in statutory stake limit implementation severity or advertising window restrictions would shift revenue architecture assumptions materially. Forecasts reflect documented base-case assumptions regarding technology adoption velocity and compliance cost inflation. Material deviation in named legislative triggers or payment processor concentration events warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
LAMEA in-Game Advertising Market
Gaming
Cloud Gaming Market
Gaming
Global Online Gambling and Betting Market
Gaming
Advanced Digital Gaming Market
Gaming
Game Engine Management Market
Gaming
North America Gaming Market
Gaming
Social Gaming Market
Gaming
VR Melee Games Market
Gaming
Lottery Market
Gaming
VR Racing Gaming Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Animation, VFX & Game Market
Gaming
GCC Gaming Headsets Market
Gaming
VR Gaming Accessories Market
Gaming
Mobile MOBA Games Market
Gaming
Console Games Market