
 Europe Gaming Peripherals Market | 2026-2036
Europe Gaming Peripherals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gaming Peripherals Market Intelligence
Polish contract manufacturers is realigning their assembly capacity toward low-latency wireless modules for gaming mice and keyboards. Logitech G leverages its Swiss engineering heritage to sustain premium positioning across mechanical switch categories. Razer competes through aggressive esports sponsorship pipelines that anchor brand visibility in tier-one tournaments.
Europe gaming peripherals encompass input and output devices engineered for interactive entertainment, typically featuring sub-1ms polling rates, mechanical actuation points between 1.2mm and 2.0mm, and driver software supporting macro programmability. Their commercial purpose centers on reducing input lag and enhancing tactile feedback during competitive and immersive gameplay. Headsets with surround sound virtualization and noise-canceling microphones command the largest margin pools within product type categories. Wireless technology variants are displacing wired counterparts among professional gamers who prioritize unrestricted movement during tournament play.
REACH and RoHS frameworks restrict hazardous substances in peripheral plastics and solder compositions, compelling reformulation of PCB assemblies and cable sheathing across EU member states. The EU Green Deal's circular economy mandates are forcing producers to design for disassembly and establish take-back programs for end-of-life devices. EMA and national regulators do not directly govern this category, but CE marking requirements enforce electromagnetic compatibility standards that shape RF performance claims for wireless peripherals. Stakeholders must monitor how impending battery passport regulations will trace lithium-cell provenance in rechargeable wireless devices.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing peripheral manufacturers to redesign products for disassembly and establish take-back programs, fundamentally altering cost structures and supply chain configurations across the continent.
Growth Catalysts
- Esports infrastructure expansion:Tournament organizers in Germany, France, and Poland are mandating professional-grade equipment specifications that drive standardized procurement at scale.
- REACH chemical reformulation:Restrictions on hazardous substances in plastics and solder are accelerating adoption of halogen-free PCB assemblies and bio-based cable sheathing among compliant suppliers.
- Wireless latency breakthroughs:Sub-1ms polling rate technologies are enabling cord-free tournament play without performance penalties, converting wired holdouts in competitive gaming segments.
Market Restraints
- Raw material concentration:Rare earth elements for magnet production in haptic feedback motors concentrate in limited supply geographies, exposing manufacturers to price volatility and sourcing disruptions.
- Technical ceiling on battery density:Lithium-ion cell energy density limitations constrain runtime in wireless headsets and mice, forcing trade-offs between weight and operating duration.
- RoHS compliance friction:Lead-free solder alternatives exhibit inferior thermal fatigue resistance, elevating failure rates in high-heat gaming environments and increasing warranty exposure.
Strategic Opportunities
- Eastern European manufacturing expansion:Polish and Romanian assembly facilities offer cost-competitive production capacity with EU regulatory alignment, attracting contract manufacturing relocation from Asian sources.
- Battery passport traceability:Impending regulations will create competitive differentiation for producers with transparent lithium-cell supply chains and verified carbon footprints in rechargeable wireless devices.
- Cloud gaming peripheral convergence:Latency-tolerant input devices paired with streaming services are opening addressable markets among casual gamers who prioritize convenience over raw performance specifications.
Industry Challenges
- Firmware security certification:CE marking requirements for electromagnetic compatibility are expanding to encompass wireless encryption standards, extending product validation timelines by 4-6 months.
- Disassembly engineering talent:EU Green Deal mandates for repairability and component recovery are outpacing availability of industrial designers trained in circular product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gaming Peripherals Market |
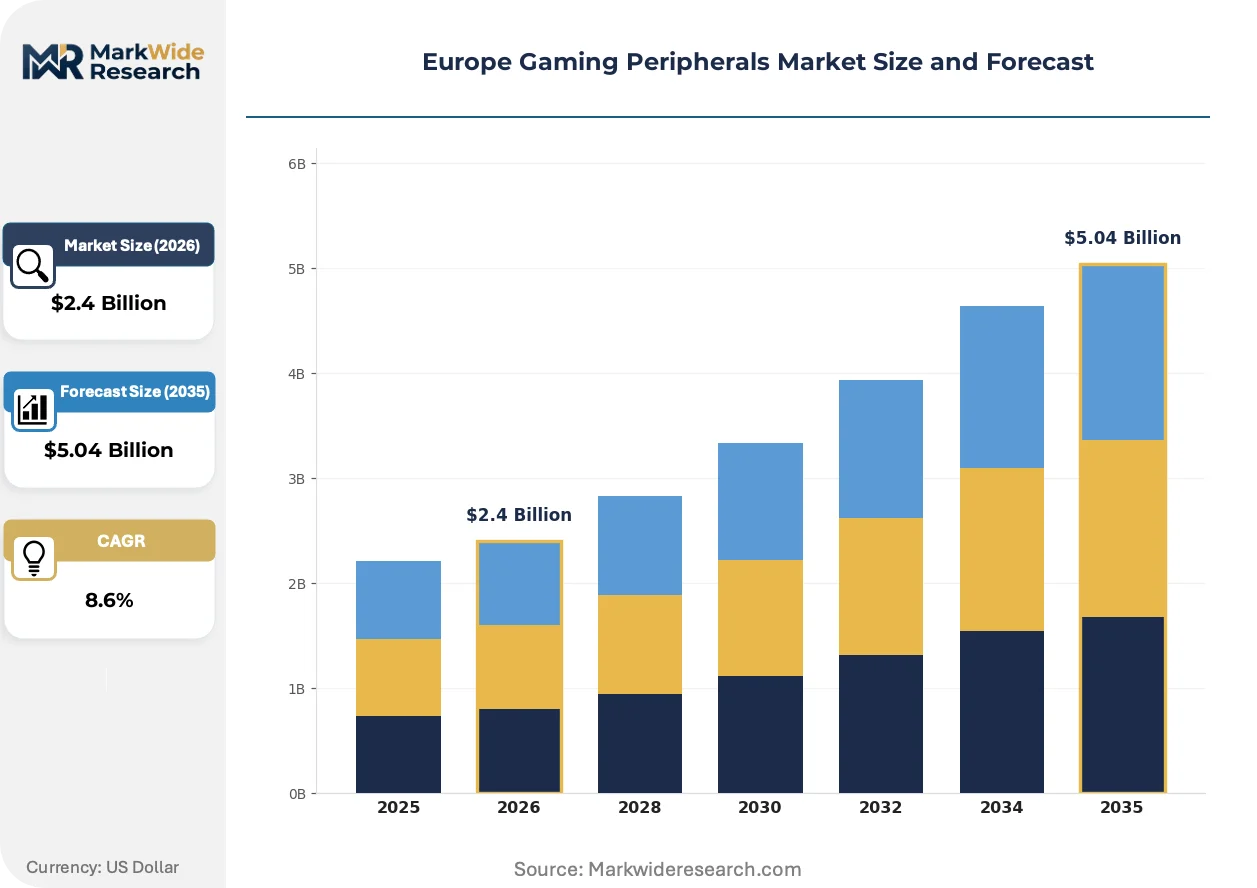
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
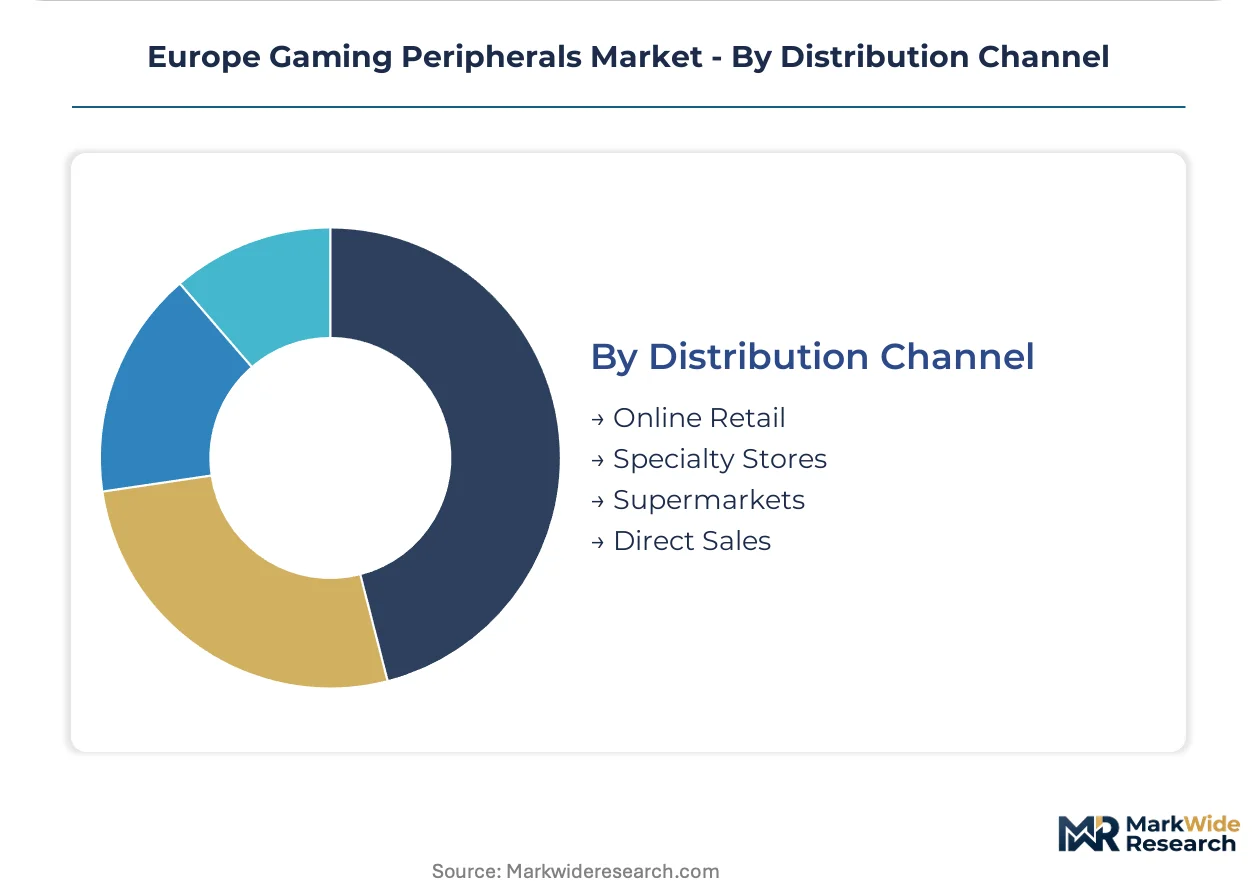
| Segmentation | Product Type: Keyboards, Mice, Headsets, Controllers Technology: Wired, Wireless, Bluetooth, Optical End User: Casual Gamers, Professional Gamers, Streamers, Esports Teams Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | SteelSeries, HyperX, Logitech G, ROCCAT, Thrustmaster, Razer, Turtle Beach, Sennheiser, Corsair, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gaming Peripherals Market Strategic Shifts & Innovations
Peripheral architectures are fragmenting into interoperable subsystems that allow gamers to customize switch types, sensor modules, and connectivity options without complete device replacement.
Mechanical switch platforms are modularizing around standardized mounting specifications and hot-swappable sockets. Enthusiast builders in Germany and the Netherlands are mixing proprietary and third-party components within single keyboards. This modularity is compressing replacement cycles while elevating aftermarket component margins above complete unit sales.
REACH authorization procedures are restricting chromate passivation coatings on metal chassis, compelling anodization and PVD finish substitutions. Italian and Spanish manufacturers are retooling surface treatment lines to maintain corrosion resistance without hexavalent chromium. Premium product tiers absorb these process costs more readily than economy segments.
Direct-to-consumer configuration tools are displacing retail assortment constraints. French and Swedish gamers increasingly specify actuation force, travel distance, and sound profiles through brand websites rather than accepting pre-configured retail SKUs. This behavior concentrates in metropolitan markets with established maker cultures and short delivery windows.
Europe Gaming Peripherals Market Segmentation

Product architecture in European gaming peripherals fragments across input modalities, connectivity protocols, and buyer sophistication tiers. Certification requirements from REACH, RoHS, and CE marking apply unevenly across these boundaries, creating compliance cost differentials that reshape competitive positioning.
Product Type:
Keyboards and mice carry the heaviest REACH substance restrictions due to PCB solder and plasticizer content, while headsets face additional electromagnetic compatibility scrutiny for wireless RF emissions.
- Keyboards:Mechanical switch assemblies with actuation forces between 45g and 80g dominate enthusiast procurement. German and Polish esports organizations are standardizing on hot-swappable PCB designs that allow tournament staff to replace switches without soldering. REACH compliance costs for halogen-free flame retardants in keycap plastics compress margins on economy-tier products more severely than premium lines.
- Mice:Optical and laser sensor modules with DPI ranges from 800 to 25,600 anchor competitive differentiation. French and Swedish professional players are migrating toward sub-60g ultralight designs with honeycomb chassis. RoHS lead-free solder mandates in scroll wheel encoders elevate warranty exposure in high-heat gaming environments.
- Headsets:Surround sound virtualization and noise-canceling microphone arrays define performance tiers. CE marking for wireless RF emissions extends validation timelines for Bluetooth variants.
- Controllers:Haptic feedback motors and adaptive trigger mechanisms compete for console and PC crossover users. Rare earth magnet sourcing constraints concentrate supply risk.
Mice sit at the top of the volume ranking, with headsets climbing the fastest.
Technology:
Cost tiers stratify sharply across connectivity architectures, with wireless modules commanding 40-60% manufacturing cost premiums over wired equivalents.
- Wired:USB-C and braided cable configurations persist in tournament environments where latency tolerance approaches zero. Polish and Romanian contract manufacturers maintain cost-competitive assembly capacity for OEM brands.
- Wireless:Proprietary 2.4GHz protocols with sub-1ms polling rates are displacing wired holdouts among professional gamers. Battery passport traceability requirements will soon differentiate supply chain transparency.
- Bluetooth:Multi-device pairing capabilities attract mobile and casual gaming segments. ETSI compliance for European spectrum allocation adds certification overhead.
- Optical:Infrared and laser-based input detection eliminates mechanical switch debounce delay. Italian surface treatment specialists supply PVD-finished sensor lenses.
Wireless sits at the top of the volume ranking, with optical climbing the fastest.
End User:
Application intensity determines durability specifications and warranty exposure, with esports teams demanding 24-month replacement guarantees under tournament stress conditions.
- Casual Gamers:Price-sensitive buyers prioritizing plug-and-play convenience over customization. Spanish and Italian retail channels concentrate volume in sub-€50 peripheral categories.
- Professional Gamers:Sub-1ms latency requirements and standardized equipment mandates from tournament organizers. German Gamescom-adjacent studios anchor procurement decisions for high-performance gear.
- Streamers:Aesthetic customization and RGB synchronization with broadcast setups drive purchasing. Dutch direct-to-consumer configuration tools capture this segment.
- Esports Teams:Bulk procurement with uniform specifications and sponsor co-branding requirements. French tournament organizers are mandating professional-grade equipment standards.
Professional gamers sit at the top of the volume ranking, with streamers climbing the fastest.
Distribution Channel:
Customer type concentration varies by geography, with metropolitan markets showing stronger direct-to-consumer penetration than peripheral regions.
- Online Retail:Amazon and regional platforms dominate volume in Germany and France. Configuration tools and customization options bypass retail SKU constraints.
- Specialty Stores:Physical try-before-buy experiences sustain relevance for switch feel and headset fit evaluation. Berlin and Cologne retail clusters serve enthusiast communities.
- Supermarkets:Economy-tier bundled products targeting gift purchases and impulse buyers. Price compression limits compliant supplier participation.
- Direct Sales:Brand-owned configuration platforms with actuation force and travel distance customization. Swedish and metropolitan French gamers show strongest adoption.
Online retail sits at the top of the volume ranking, with direct sales climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest absolute spending on gaming peripherals in Europe, while Poland demonstrates the fastest procurement velocity among emerging esports markets.
Germany
Gamescom in Cologne and Berlin's dense studio cluster anchor continental purchasing decisions for professional-grade equipment. REACH compliance costs for halogen-free PCB assemblies compress margins on economy-tier products more severely than premium lines. Munich and Hamburg retail networks sustain physical try-before-buy experiences for switch evaluation and headset fitting.
Poland
Contract manufacturers in Warsaw and Krakow are realigning assembly capacity toward low-latency wireless modules for gaming mice and keyboards. EU Green Deal circular economy mandates are accelerating redesign for disassembly among Polish production facilities. Katowice's esports infrastructure expansion is mandating standardized professional equipment specifications at tournament scale.
France
Paris and Lyon metropolitan markets show strongest adoption of direct-to-consumer configuration tools specifying actuation force and travel distance. RoHS lead-free solder mandates in scroll wheel encoders elevate warranty exposure in high-heat gaming environments. French tournament organizers are mandating professional-grade equipment standards for sponsor-compliant procurement.
Netherlands
Amsterdam and Rotterdam host established maker cultures driving demand for hot-swappable mechanical switch platforms. ETSI compliance for European spectrum allocation adds certification overhead for Bluetooth multi-device peripherals. Dutch direct-to-consumer platforms capture streamer segments prioritizing RGB synchronization with broadcast setups.
Sweden
Stockholm's short delivery windows concentrate direct sales adoption for customized peripheral specifications. CE marking requirements for electromagnetic compatibility extend validation timelines for wireless RF emissions in Bluetooth variants. Malmö and Gothenburg retail channels serve enthusiast communities with physical evaluation of honeycomb chassis ultralight designs.
Europe Gaming Peripherals Market Key Industry Players
Swiss and German engineering houses anchor the premium tier; Polish and Romanian assembly specialists hold cost-competitive contract manufacturing positions. The vendor base stratifies across three tiers: integrated multinationals with full-stack capabilities, modular specialists focusing on switch or sensor subsystems, and white-label assemblers serving retail brands. Strategic moves center on M&A for wireless protocol IP and geographic expansion into Eastern European production zones.
Within the integrated multinational tier, Logitech G and Razer exemplify divergent positioning archetypes. Logitech G occupies a position tied to Swiss engineering heritage and mechanical switch category depth. Razer sits within the esports sponsorship-intensive vector, anchoring brand visibility through tournament pipeline investments. SteelSeries represents the Nordic design-specialist archetype with Copenhagen-rooted product development traditions.
| Leading Market Players |
|---|
| SteelSeries |
| HyperX |
| Logitech G |
| ROCCAT |
| Thrustmaster |
| Razer |
| Turtle Beach |
| Sennheiser |
| Corsair |
| Others |
Cost & Logistics Intelligence
Esports team procurement programs anchor pricing power in the European gaming peripherals market, compressing margins on economy-tier products while sustaining premium positioning for tournament-grade equipment with sub-1ms latency specifications and hot-swappable mechanical switch architectures.
Pricing Analysis
Capacity additions in Polish and Romanian assembly facilities are reshaping price floors for wired peripheral categories, while wireless modules retain manufacturing cost premiums. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and customization depth. Cost compression in economy-tier keyboards intensifies because REACH halogen-free flame retardant mandates elevate material expenses. Casual gamers in Spanish and Italian retail channels exhibit highest price sensitivity; professional esports teams demonstrate lowest sensitivity due to standardized equipment mandates.
Supply Chain Analysis
Dual-sourcing requirements from German and French tournament organizers mandate multi-supplier qualification for wireless sensor modules and mechanical switch assemblies. Manufacturing concentrates in China, Taiwan, and Vietnam for PCB fabrication and optical sensor dies. Rare earth elements for haptic feedback motors and lithium-ion cells for wireless headsets constitute critical input dependencies. Single-source vulnerability in rare earth magnet supply chains exposes controller manufacturers to price volatility. Distribution runs through Amazon and regional online platforms in metropolitan markets, with specialty retail sustaining relevance for physical evaluation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European gaming peripherals market functions as a stable compounder, with esports infrastructure expansion across Germany, France, and Poland delivering sustained procurement velocity for professional-grade equipment.
For Market Incumbents: Deploy circular economy design capabilities as a defensive moat. Invest in disassembly engineering talent to meet EU Green Deal mandates ahead of compliance deadlines. Acquire wireless protocol IP to counter emerging entrants with proprietary low-latency technologies. Control channel positioning through direct-to-consumer configuration platforms that bypass retail SKU constraints. For New Entrants and Emerging Players: The price-point gap between premium Swiss-engineered peripherals and economy-tier Polish-assembled products offers white-space entry. Target streamer segments in Dutch and Swedish metropolitan markets with RGB synchronization and aesthetic customization tools. Pursue battery passport traceability as a differentiated go-to-market angle for wireless categories. For Investors and Strategic Acquirers: Peripheral OEMs seeking wireless competency represent the most active acquirer in this space. The market supports long-term viability through recurring replacement cycles driven by modular upgrade cultures. Monitor firmware security certification timelines as the key inflection signal; CE marking expansion to wireless encryption standards extends validation periods and creates consolidation pressure on undercapitalized players.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Acquisition | Secures sub-1ms polling rate IP needed for tournament-grade peripheral certification. |
| Circular Design Certification | Positions products ahead of EU Green Deal disassembly mandates and battery passport regulations. |
| Direct-to-Consumer Platform Launch | Bypasses retail assortment constraints in French and Swedish metropolitan configuration markets. |
| Eastern European Manufacturing Expansion | Captures cost-competitive Polish and Romanian assembly capacity with full REACH compliance. |
| Esports Sponsorship Pipeline Investment | Anchors brand visibility in tier-one tournaments with standardized equipment procurement mandates. |
Research Approach
Direct dialogue with esports team equipment managers, peripheral OEM procurement directors, Polish contract manufacturing executives, and REACH compliance specialists grounded the qualitative foundation. Secondary validation drew from ECHA substance restriction databases, CE marking electromagnetic compatibility filings, EU Green Deal circular economy policy documents, and esports tournament equipment specification sheets. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate market value assessments.
Bottom-up modeling aggregated segment-level volume and pricing across product type, connectivity technology, and end-user sophistication tiers. Segmentation dimensions included input modality, wireless protocol architecture, and buyer application intensity from casual through professional. CAGRs derived from historical trajectory analysis adjusted for regulatory compliance cost inflections. Forecast inputs incorporated battery passport implementation timelines and esports infrastructure investment pipelines.
Caveats apply where REACH authorization expansions or rare earth supply disruptions could materially shift the outlook. Deviation in wireless latency technology adoption curves or EU circular economy enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Japan Virtual Reality Gaming Market
Gaming
SLG Game Market
Gaming
MMORPG Gaming Market
Gaming
Europe Casino Gambling Market
Gaming
Global Casino Market
Gaming
Social Gaming Market
Gaming
Latin America Mobile Gaming Market
Gaming
Gaming Gadgets Market
Gaming
Chinese Gaming Industry Market
Gaming
Gaming Simulator Market
Gaming
Global Gaming Market
Gaming
Gaming Software Market
Gaming
H5 Games Market
Gaming
Global 3D Gaming Console Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Galgames Market