
 VR Racing Gaming Market | 2026-2036
VR Racing Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
VR Racing Gaming Market Insights
China's manufacturing corridor for display panels and haptic controllers is reshaping upstream supply dynamics for VR racing hardware. Meta Platforms leverages its Quest ecosystem and content store to dominate standalone headset distribution for racing titles. Sony Interactive Entertainment anchors premium console-based VR racing through its PSVR2 platform and first-party studio partnerships. Valve Corporation competes in the high-fidelity PC segment with its Index hardware and SteamVR content pipeline.
VR Racing Gaming denotes immersive motorsport simulation delivered through head-mounted displays with stereoscopic rendering, typically requiring 90 Hz minimum refresh rates and sub-20 ms motion-to-photon latency to prevent simulator sickness. The technology serves both consumer entertainment and professional driver training applications. Platform segmentation shows PC and console installations commanding the highest per-user revenue, while mobile and arcade channels are expanding fastest in emerging markets. Game type dynamics reveal simulation and Formula categories capturing dedicated enthusiast spending, whereas street racing and rally formats attract broader casual audiences through shorter session designs.
FCC equipment authorization governs wireless headset emissions in the United States, while the EU's CE marking and RoHS directives shape material and electromagnetic compliance for European market entry. China's GB standards and MIIT certification requirements for VR devices are raising technical barriers for smaller hardware entrants. Stakeholders must monitor regulatory divergence in display safety standards and haptic device liability frameworks as hardware-software bundles proliferate across commercial venues.
Market Dynamics
Arcade venues and dedicated simulation centers are consolidating purchasing power, forcing hardware vendors to reconfigure distribution networks and service models around commercial deployment cycles rather than consumer retail.
Growth Catalysts
- Esports infrastructure scaling:Purpose-built racing arenas in the United States are installing multi-station VR rigs to host spectator-friendly tournaments. These venues command premium hardware specifications and recurring content licensing.
- MIIT refresh rate mandates:China's tightening standards for 90 Hz minimums and sub-20 ms latency are filtering low-performance headsets from supply chains, elevating baseline quality expectations across export markets.
- Cloud rendering architectures:Edge computing deployments are reducing local GPU requirements, enabling lighter headset designs that lower venue capex barriers for entry-level simulation centers.
Market Restraints
- Display panel supply concentration:Korean and Chinese OLED manufacturers control high-refresh microdisplay output, creating allocation bottlenecks during demand surges.
- Motion-to-photon latency floors:Current wireless transmission protocols impose hard physics limits on latency reduction, constraining simulator sickness mitigation in untethered deployments.
- CE marking complexity:EU electromagnetic compatibility and RoHS material directives extend certification timelines for hardware bundles targeting European commercial venues.
Strategic Opportunities
- Professional driver training:Motorsport teams are adopting VR for telemetry visualization and track familiarization, creating B2B subscription revenue streams detached from consumer entertainment cycles.
- India's commercial entertainment corridors:Shopping mall operators in Mumbai and Bangalore are allocating floor space to experience zones, importing turnkey simulation pods from Chinese OEMs.
- Haptic suit convergence:Integration of force-feedback vests with steering wheel rigs is enabling full-body immersion that differentiates premium venue offerings from home setups.
Industry Challenges
- Motion sickness mitigation engineering:Developers must calibrate vestibular cues across heterogeneous hardware configurations, fragmenting QA pipelines and delaying release schedules.
- Content licensing fragmentation:Vehicle manufacturers and track rights holders negotiate disparate territorial agreements, complicating global title distribution for publishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Racing Gaming Market |
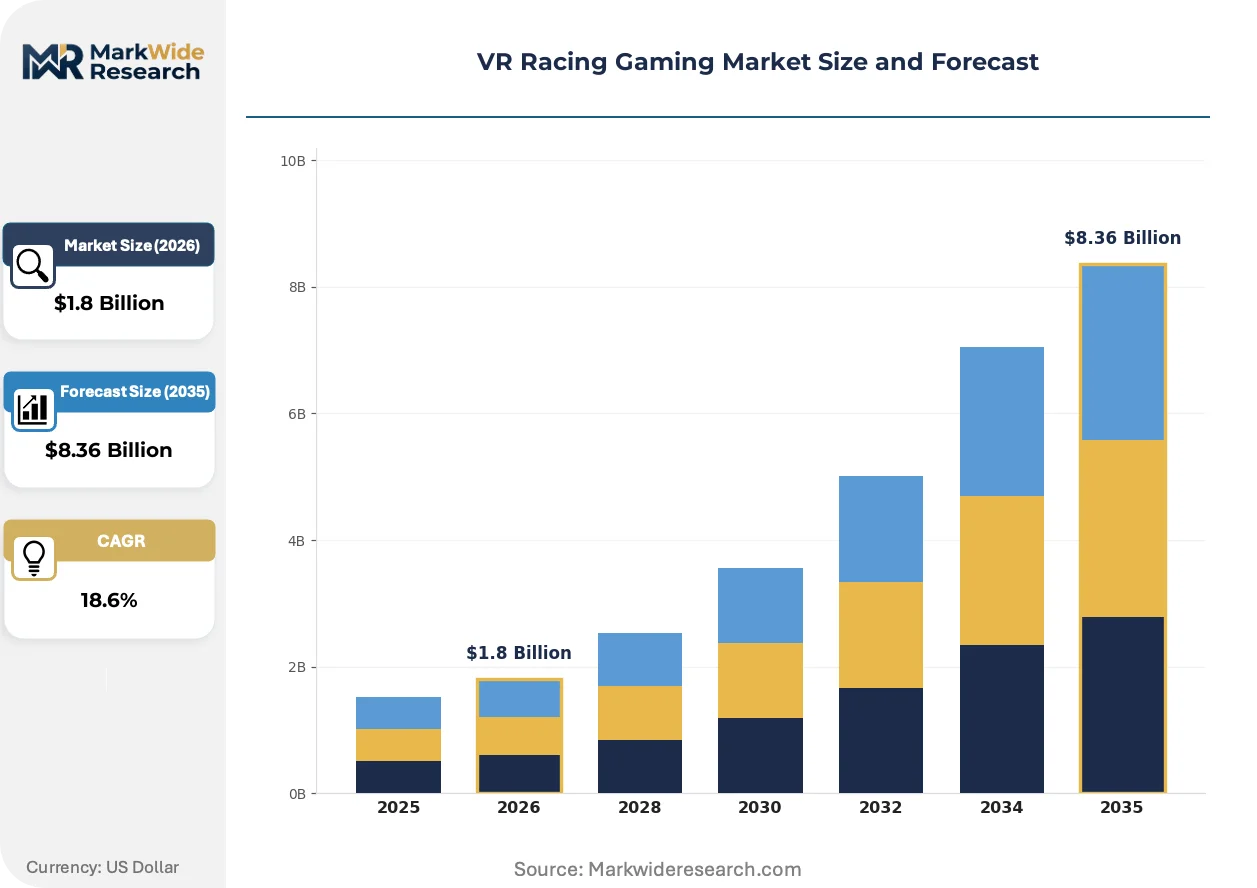
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Arcade Game Type: Rally, Formula, Street Racing, Simulation User Experience: Single Player, Multiplayer, Co-op, Esports Technology: Haptic Feedback, Motion Sensing, 3D Audio, Visual Displays |
| Companies Covered | Meta Platforms, Sony Interactive Entertainment, Valve Corporation, HTC Corporation, Codemasters, Electronic Arts, Ubisoft, Turn 10 Studios, CXC Simulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Racing Gaming Market Trends and Innovations
Hardware-software bundling is accelerating as vendors seek recurring revenue through content stores rather than one-time device sales, reshaping competitive metrics toward lifetime value capture.
Foveated rendering with dynamic resolution scaling is virtualizing GPU workload distribution. Arcade operators are adopting eye-tracking headsets to maintain visual fidelity on mid-tier PC hardware. This compression of rendering requirements is virtualizing the traditional performance-cost tradeoff that previously segmented premium from economy venue tiers.
China's MIIT certification requirements for VR device electromagnetic emissions are tightening technical documentation burdens. Domestic manufacturers are absorbing compliance costs into product development cycles earlier. Export-oriented OEMs are responding by pre-certifying platforms for multiple jurisdictions, compressing time-to-market for international venue deployments.
Consumption patterns among casual audiences favor shorter session designs over endurance simulation. Street racing and rally formats are displacing Formula-category titles in mall-based entertainment zones. This rotation toward arcade-friendly content is most visible in United States commercial venues, where operators optimize throughput per square meter over fidelity per user.
VR Racing Gaming Market Segmentation
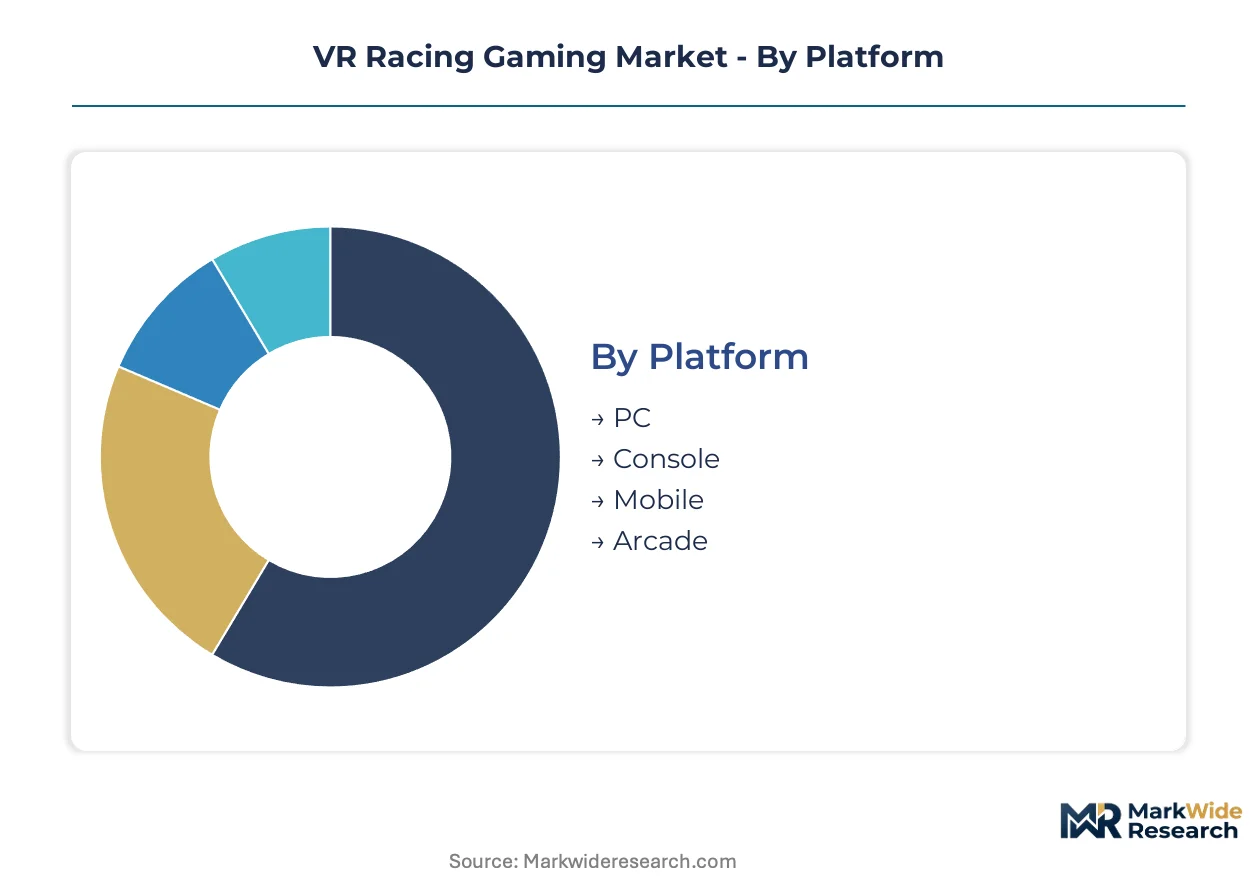
Platform choice dictates hardware refresh cycles and venue investment horizons in VR racing. Game type and technology selections determine content development costs and user acquisition strategies across commercial and consumer channels.
Platform:
Arcade installations cycle hardware every 18-24 months to maintain competitive throughput, while PC and console setups operate on 3-5 year replacement schedules. Mobile platforms turn over fastest as smartphone refresh rates compress.
- PC:High-fidelity rendering pipelines demand discrete GPU architectures with sustained thermal headroom. United States esports arenas specify liquid-cooled workstations to eliminate frame-time variance during tournament broadcasts. FCC equipment authorization governs wireless headset emissions for PC-tethered configurations.
- Console:Closed ecosystems from Sony anchor premium living-room deployments through standardized PSVR2 hardware. Japan's METI efficiency standards shape power supply specifications for console bundles targeting Asian markets.
- Mobile:Smartphone-dependent streaming reduces venue capex to controller peripherals alone. Indian mall operators import turnkey mobile-VR pods from Shenzhen OEMs to minimize upfront hardware exposure.
- Arcade:Purpose-built motion rigs with force-feedback steering and six-axis platforms command the highest per-station revenue. China's MIIT refresh rate mandates filter low-performance headsets from commercial supply chains.
Console anchors the volume base while Arcade gains share at the steepest rate.
Game Type:
Development cost tiers separate simulation-grade physics engines from arcade-optimized alternatives. Rally titles demand terrain deformation systems that inflate production budgets relative to circuit-based formats.
- Rally:Procedural surface modeling and dynamic weather layers require specialized physics middleware. Scandinavian development studios concentrate expertise in loose-surface vehicle dynamics.
- Formula:Official FIA licensing and track laser-scanning create content production timelines exceeding 24 months. Professional driver training contracts in Germany specify Formula-category telemetry fidelity.
- Street Racing:Urban environment asset libraries enable rapid content iteration for casual session designs. United States commercial venues optimize throughput with 8-12 minute street racing experiences.
- Simulation:Laser-scanned circuits and vehicle dynamics validated against real-world telemetry attract enthusiast spending. Motorsport teams in the United Kingdom subscribe to simulation platforms for driver coaching programs.
Street Racing commands the largest installed base while Simulation captures the highest revenue per user.
User Experience:
Session duration patterns vary sharply across experience modes, with Esports demanding synchronous infrastructure investments that single-player deployments avoid entirely.
- Single Player:Campaign-driven progression systems sustain engagement without network latency constraints. Home consumers in Australia favor single-player formats for irregular play schedules.
- Multiplayer:Matchmaking infrastructure and regional server placement determine competitive integrity. Brazilian internet exchange points host dedicated multiplayer nodes to reduce trans-Atlantic latency.
- Co-op:Team-based endurance racing formats require voice communication integration and shared telemetry dashboards. European venue operators pair co-op modes with hospitality packages for corporate events.
- Esports:Spectator-friendly camera pipelines and broadcast overlay systems mandate specialized software development. Purpose-built racing arenas in Los Angeles and Las Vegas install multi-station rigs with spectator seating.
Single Player retains the broadest demographic reach while Esports expands most quickly in commercial venue deployments.
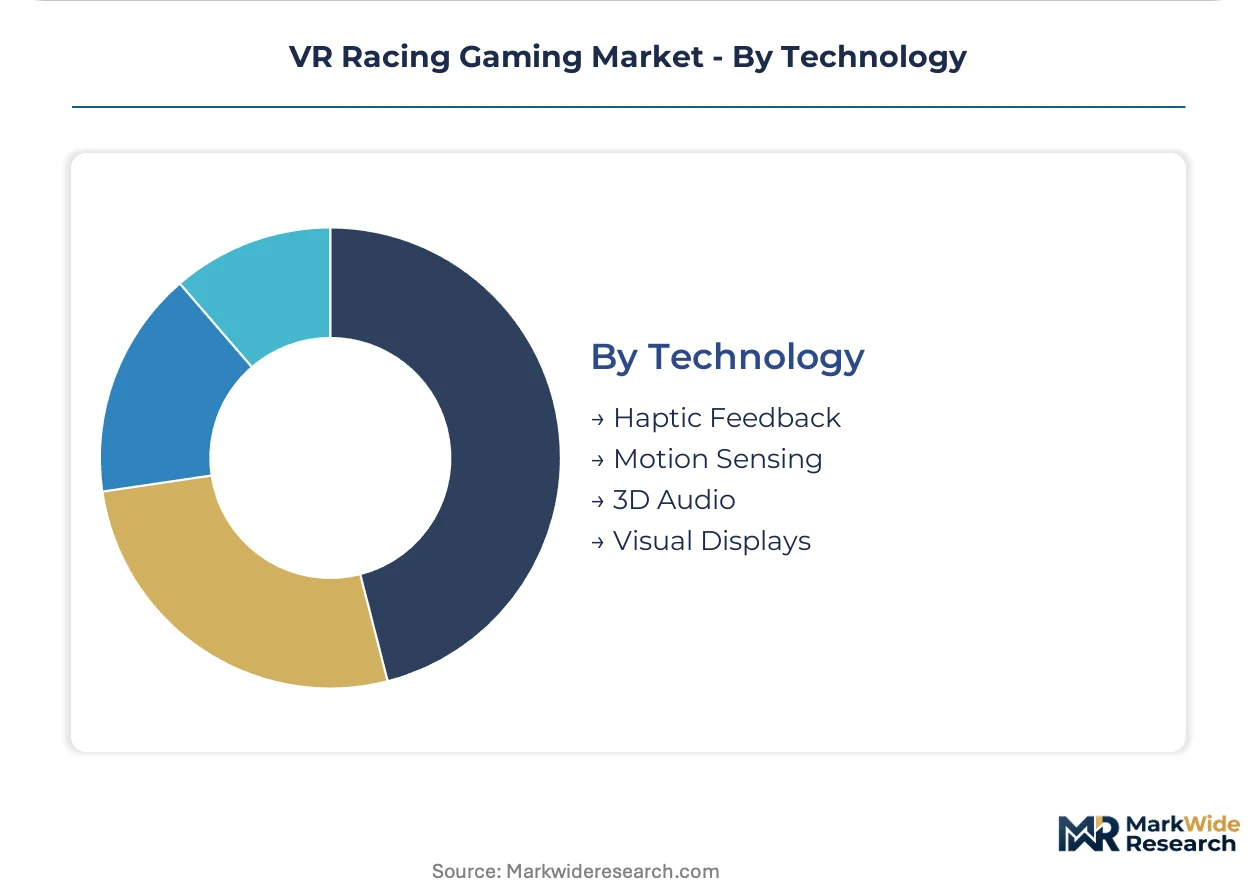
Technology:
Hardware integration complexity escalates from audio-only upgrades through full-body haptic systems, fragmenting vendor specialization and procurement patterns.
- Haptic Feedback:Force-feedback steering wheels with direct-drive motors deliver torque fidelity exceeding consumer-grade belt systems. Chinese OEMs consolidate haptic controller manufacturing for export to European simulation centers.
- Motion Sensing:Six-axis platform actuators synchronize vestibular cues with visual flow to mitigate simulator sickness. Korean display panel suppliers integrate motion sensing telemetry into headset firmware.
- 3D Audio:Spatial audio engines render engine position and surface texture through HRTF processing. Game audio middleware from French studios dominates European publisher adoption.
- Visual Displays:Micro-OLED panels with 90 Hz minimums satisfy China's MIIT latency standards for commercial certification. Japanese display manufacturers specialize in high-refresh microdisplays for premium headset tiers.
Visual Displays constitute the largest technology expenditure while Haptic Feedback differentiates premium venue offerings most distinctly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese display panel and haptic controller manufacturing clusters supply upstream components to hardware assemblers worldwide. Venue deployment patterns diverge sharply across national markets based on esports infrastructure maturity and commercial entertainment zoning regulations.
United States
Purpose-built racing arenas in Los Angeles and Las Vegas install multi-station VR rigs with spectator seating for tournament broadcasts. FCC equipment authorization governs wireless headset emissions for commercial deployments. Texas and Florida mall operators optimize throughput per square meter with 8-12 minute street racing experiences.
China
MIIT refresh rate mandates filtering low-performance headsets from commercial supply chains elevate baseline quality for export markets. GB standards and electromagnetic certification requirements raise technical barriers for smaller hardware entrants. Shenzhen OEMs manufacture turnkey simulation pods for Indian and Southeast Asian venue imports.
Germany
Professional motorsport teams in Stuttgart and Munich subscribe to Formula-category simulation platforms for driver coaching and telemetry visualization. KBA vehicle certification norms indirectly shape simulation fidelity expectations for training applications. Bavarian simulation centers specify laser-scanned circuit accuracy for endurance racing preparation.
Japan
METI efficiency standards govern power supply specifications for console-VR bundles targeting domestic and Asian markets. Tokyo-based development studios concentrate expertise in spatial audio middleware for European publisher adoption. Osaka hardware manufacturers specialize in high-refresh microdisplays for premium headset tiers.
India
Shopping mall operators in Mumbai and Bangalore allocate floor space to experience zones importing Chinese turnkey simulation pods. TRAI broadband infrastructure investments reduce latency for multiplayer matchmaking nodes. Delhi-NCR commercial entertainment corridors experiment with mobile-VR pods to minimize upfront hardware exposure.
VR Racing Gaming Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying display panels, haptic controllers, and audio middleware to multiple assemblers. The vendor base organizes around three strategic archetypes: closed-ecosystem platform owners, hardware-agnostic software publishers, and venue-focused simulation system integrators. Consolidation pressures concentrate around content licensing negotiations and exclusive hardware-software bundling agreements. Vertical integration into haptic controller manufacturing represents the dominant competitive move, alongside geographic expansion through turnkey venue licensing.
Within the closed-ecosystem tier, Meta Platforms exemplifies platform-first strategy through standalone headset distribution and content store monetization. Sony Interactive Entertainment anchors premium console-based positioning through first-party studio partnerships and standardized hardware. Valve Corporation occupies the high-fidelity PC segment archetype, competing through open hardware standards and content pipeline aggregation.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Interactive Entertainment |
| Valve Corporation |
| HTC Corporation |
| Codemasters |
| Electronic Arts |
| Ubisoft |
| Turn 10 Studios |
| CXC Simulations |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese micro-OLED fabrication is compressing panel pricing while elevating supplier leverage over headset assemblers, forcing hardware vendors to absorb certification costs into longer-term contract structures or surrender margin to secure allocation priority.
Pricing Analysis
China's MIIT electromagnetic certification dictates the pricing tier structure across commercial and consumer VR racing hardware. Three-tier pricing structure across premium, standard, and economy levels separates arcade-grade motion rigs with sub-20 ms latency guarantees from tethered PC headsets and mobile-streaming pods. Price differentiation hinges on refresh rate certification tier and haptic controller torque fidelity. Cost compression in economy-tier mobile pods is intensifying because Indian mall operators are consolidating procurement through Shenzhen OEMs. Arcade venues demonstrate the lowest price sensitivity due to throughput-per-square-meter optimization, while individual consumers in price-sensitive markets resist premium hardware without bundled content subscriptions.
Supply Chain Analysis
Export controls on advanced lithography equipment limiting semiconductor flows to Chinese foundries are fragmenting GPU sourcing strategies for VR headset manufacturers. Geographic supply concentration centers on China for micro-OLED panels and haptic controller assemblies, South Korea for high-refresh display drivers, and Japan for precision motion-sensing components. Raw material dependencies include rare-earth magnets for direct-drive steering motors, gallium substrates for micro-LED epitaxy, and specialized polymers for lightweight headset housings. Single-source vulnerability in Korean OLED driver ICs exposes assemblers to allocation disruptions during demand surges. Distribution runs through Shenzhen-based OEMs serving commercial venue integrators, with direct-to-consumer channels anchored by platform-owned content stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arcade venue consolidation into multi-station tournament operators is shifting procurement leverage toward volume buyers capable of dictating hardware specifications and service terms.
For Market Incumbents: Pre-empt cloud-rendering entrants by anching premium positioning through exclusive haptic suit integration and captive content licensing. Threat from edge-computing startups offering reduced capex simulation pods demands accelerated backward integration into motion-platform manufacturing. Priority lever: secure multi-year exclusive track licensing from FIA and motorsport series before subscription-based competitors aggregate content libraries. For New Entrants and Emerging Players: India's underpenetrated commercial entertainment corridors offer the most accessible white-space expansion, with Mumbai and Bangalore mall operators actively sourcing turnkey simulation pods without incumbent service entanglements. Target professional driver training subscriptions in Germany and the United Kingdom, where motorsport teams seek telemetry-visualization platforms detached from consumer entertainment cycles. Go-to-market angle: white-label hardware-software bundles for regional venue operators lacking technical integration capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward haptic controller specialists with captive manufacturing in China's Pearl River Delta and established MIIT certification pathways. Long-term viability across the analysis window favors component suppliers over pure-play content publishers, as hardware-software bundling concentrates margin capture at the system tier. Signal to watch: exclusive licensing negotiations between platform owners and Formula One or WRC rights holders, which would indicate content aggregation tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Pre-Certification Investment | Accelerates time-to-market for Chinese OEMs exporting to European arcade venues under CE marking requirements. |
| Haptic Suit Integration Partnership | Differentiates premium venue offerings from home setups through full-body force-feedback convergence. |
| Cloud Rendering Architecture Deployment | Reduces local GPU requirements for Indian mall operators minimizing upfront hardware exposure. |
| Professional Training Subscription Launch | Creates B2B revenue streams detached from consumer entertainment cycles for motorsport teams. |
| Exclusive Track Licensing Negotiation | Secures territorial content rights before competitors aggregate global distribution capabilities. |
Research Methodology
Cross-validation between executive interviews at hardware OEMs and secondary analysis of MIIT certification filings anchors the qualitative findings in documented compliance timelines. Primary fieldwork engaged arcade venue operators, haptic controller procurement leads at simulation centers, content licensing directors at racing studios, and technical standards officers at display panel manufacturers. Secondary sources include FCC equipment authorization databases, EU CE marking registries, Chinese customs export records for VR hardware, and venue operator capex disclosures. Bottom-up triangulation across component bill-of-materials estimates and top-down reconciliation against platform revenue disclosures validates market sizing.
Calibration against historical refresh cycle patterns and regulatory implementation lags shapes the projection framework across the analysis window. Segmentation dimensions modeled include platform tier, game type physics fidelity, user experience mode, and technology integration depth. CAGRs derive from installed base growth rates, hardware replacement cycles, and content monetization trajectories. Industry-specific inputs capture MIIT refresh rate mandate compliance costs and cloud rendering adoption curves in commercial venue deployments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-rendering specialists or haptic suit convergence players would shift outcomes. Material shifts in Chinese export licensing for micro-OLED panels or FIA content licensing exclusivity terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Tarot Cards Market
Gaming
Global Battle Royale Games Market
Gaming
North America Casino Gambling Market
Gaming
VR Gaming Accessories Market
Gaming
Game Applications Market
Gaming
Video Game Software Market
Gaming
Puzzle Video Game Market
Gaming
Southeast Asia Gaming Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Global Online Simulation Games Market
Gaming
Online Casino Market
Gaming
Advanced Digital Gaming Market
Gaming
VR Gaming Market
Gaming
Chinese Gaming Industry Market
Gaming
Racing Games Market
Gaming
Arcade Cabinet Market