
 South Korea Gaming Peripherals Market | 2026-2036
South Korea Gaming Peripherals Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Gaming Peripherals Market Intelligence
Esports athlete pipeline shortages is bifurcating how peripheral vendors allocate R&D resources between mass-market and pro-tier product lines. Razer Inc. leverages its Seoul-based esports partnerships to sustain brand loyalty among professional teams. Logitech anchors its Korean operations through localized wireless latency optimization labs. ABKO Co., Ltd. differentiates via domestic manufacturing scale that controls regional distribution costs.
Gaming peripherals encompass input and output devices engineered for interactive entertainment, typically featuring sub-1ms polling rates, mechanical switch actuation forces between 45-60g, and driver software stacks for macro programmability. The keyboard segment dominates unit volume through RGB mechanical switch demand from PC bang operators. Wireless technology is capturing margin pools as Bluetooth Low Energy and 2.4GHz proprietary protocols displace wired connections in tournament settings. The esports players end-user category commands premium pricing through sponsorship-driven equipment standardization.
MFDS radio equipment regulations and KCC electromagnetic compatibility certifications govern wireless peripheral market access, while Bluetooth SIG interoperability mandates shape product development timelines. The Korea Consumer Agency's product safety alerts influence retailer stocking decisions for imported gaming hardware. Stakeholders must monitor whether domestic semiconductor foundry capacity constraints alter wireless chipset sourcing strategies for Korean peripheral OEMs.
Market Dynamics
Wireless protocol standardization is compressing product development timelines across South Korean peripheral manufacturers while MFDS radio certification requirements extend commercialization lead times for Bluetooth-enabled tournament hardware.
Growth Catalysts
- Esports infrastructure investment:PC bang operators in Seoul and Busan are refreshing mechanical keyboard fleets on 18-month cycles to maintain competitive gaming environments. Bulk procurement contracts from team house operators sustain volume demand for sub-1ms polling rate devices.
- MFDS equipment safety framework:The Ministry of Food and Drug Safety's radio equipment regulations are creating compliance moats for domestic manufacturers with established certification pipelines. Local OEMs leverage pre-approved wireless chipset configurations to accelerate product launches.
- Streaming content creator economy:Individual broadcasters operating from Gangnam and Hongdae districts are driving premium peripheral adoption through sponsorship-visible equipment standardization. RGB lighting synchronization and macro programmability function as content differentiation tools.
Market Restraints
- Semiconductor foundry concentration:Domestic wireless controller IC supply depends on Samsung Foundry and SK Hynix capacity allocation, creating input cost volatility when consumer electronics and automotive sectors compete for 12nm and 14nm wafer starts.
- KCC electromagnetic compatibility testing backlog:Korea Communications Commission certification queues for 2.4GHz proprietary protocols extend time-to-revenue by 8-12 weeks for imported peripheral brands without established local testing partnerships.
- Smartphone gaming substitution:Mobile esports titles including PUBG Mobile and League of Legends Wild Rift are capturing casual gamer hours previously allocated to PC-based peripheral-dependent experiences.
Strategic Opportunities
- Busan-Gyeongnam manufacturing corridor:Peripheral assembly facilities in Busan and Changwon offer logistics cost advantages for export-oriented production serving Southeast Asian esports markets. Regional free economic zone incentives reduce landed cost for re-export configurations.
- Bluetooth Low Energy audio convergence:Gaming headsets integrating LE Audio for broadcast-quality voice capture while maintaining sub-20ms latency represent unoccupied product white space between consumer audio and pro-tier tournament equipment.
- Gwangju esports valley development:The municipal government's esports infrastructure investment program is creating anchor tenancy opportunities for peripheral vendors establishing regional distribution hubs outside Seoul Capital Area concentration.
Industry Challenges
- Firmware engineering talent scarcity:Wireless latency optimization and power management algorithm development requires specialized embedded systems expertise concentrated among Samsung and LG alumni networks. Peripheral OEMs compete for this limited talent pool against automotive and IoT sectors.
- Bluetooth SIG interoperability timeline compression:Certification body testing windows for new protocol implementations create product launch synchronization challenges when tournament seasons and retail calendar peaks misalign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Gaming Peripherals Market |
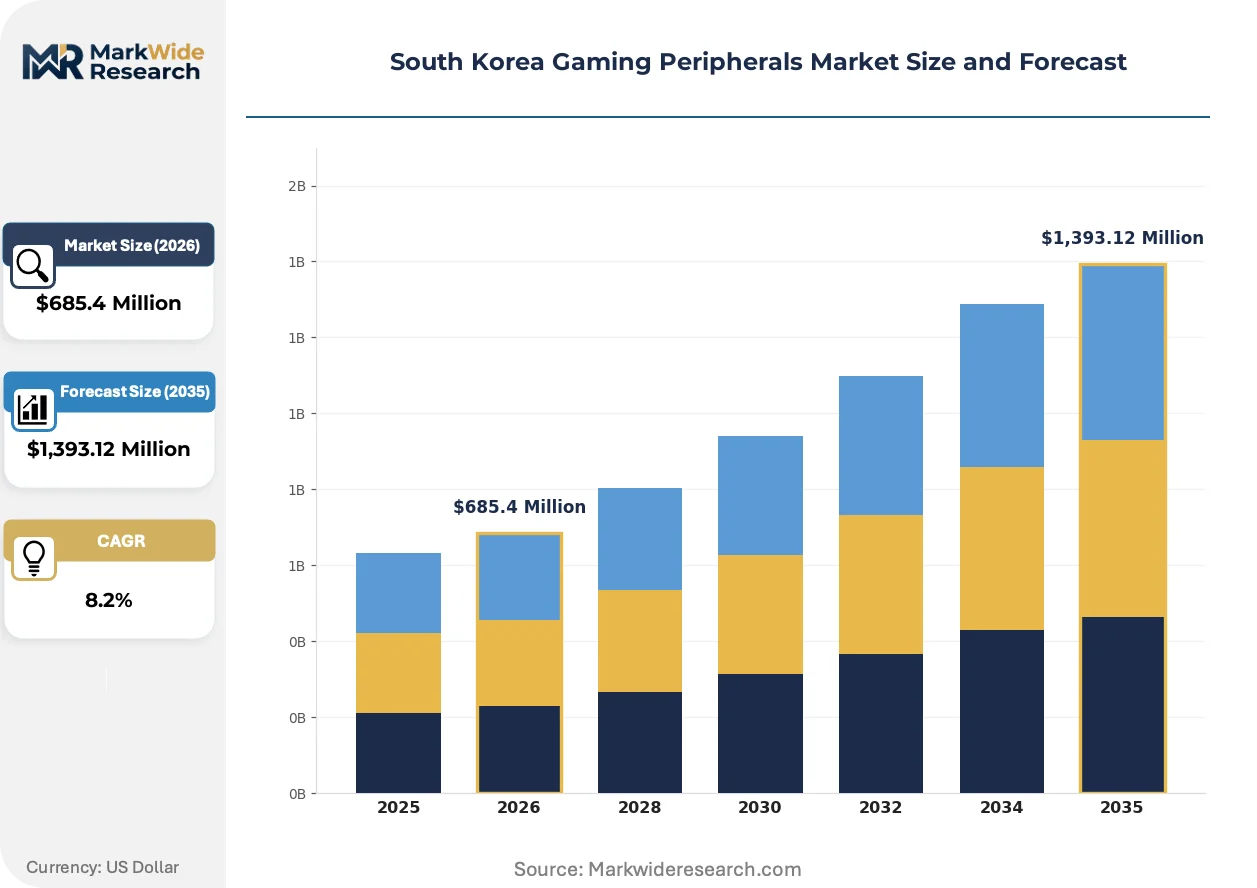
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mouse, Keyboard, Headset, Controller Technology: Wired, Wireless, Bluetooth, Hybrid End User: Casual Gamers, Professional Gamers, Streamers, Esports Players Distribution Channel: Online Retail, Brick-and-Mortar, Specialty Stores, E-Commerce |
| Companies Covered | Danawa Co., Ltd., Razer Inc., LG Electronics, SteelSeries, Corsair, Zalman Tech Co., Ltd., Logitech, Cooler Master Technology Inc., ABKO Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Gaming Peripherals Market Strategic Shifts & Innovations
Proprietary wireless protocol development is fragmenting competitive positioning as vendors abandon universal Bluetooth implementations in favor of tournament-optimized 2.4GHz stacks with custom latency profiles.
Magnetic switch technology is fragmenting mechanical keyboard actuation paradigms. Hall-effect sensors replacing physical contact points enable adjustable actuation point programming from 0.1mm to 4.0mm travel. Seoul-based esports teams are piloting these configurations for per-game sensitivity profiles. The technology is fragmenting switch supplier hierarchies as traditional Cherry MX and Kailh mechanical architectures face displacement in premium segments.
MFDS radio equipment regulations are tightening electromagnetic emission standards for wireless peripherals operating in 2.4GHz and 5GHz bands. Domestic manufacturers must submit revised test documentation for products previously certified under 2019 guidelines. Tournament-grade wireless mice and headsets face the most significant compliance burden as their high-polling-rate transmission profiles approach revised power density thresholds.
Team house procurement consolidation is compressing individual player equipment choice. Professional esports organizations in Seoul are standardizing peripheral configurations across entire rosters to simplify technical support and sponsorship fulfillment. This behavior concentrates volume with single vendors per peripheral category and reduces fragmentation in premium pricing tiers where individual player preference previously sustained brand diversity.
South Korea Gaming Peripherals Market Segmentation
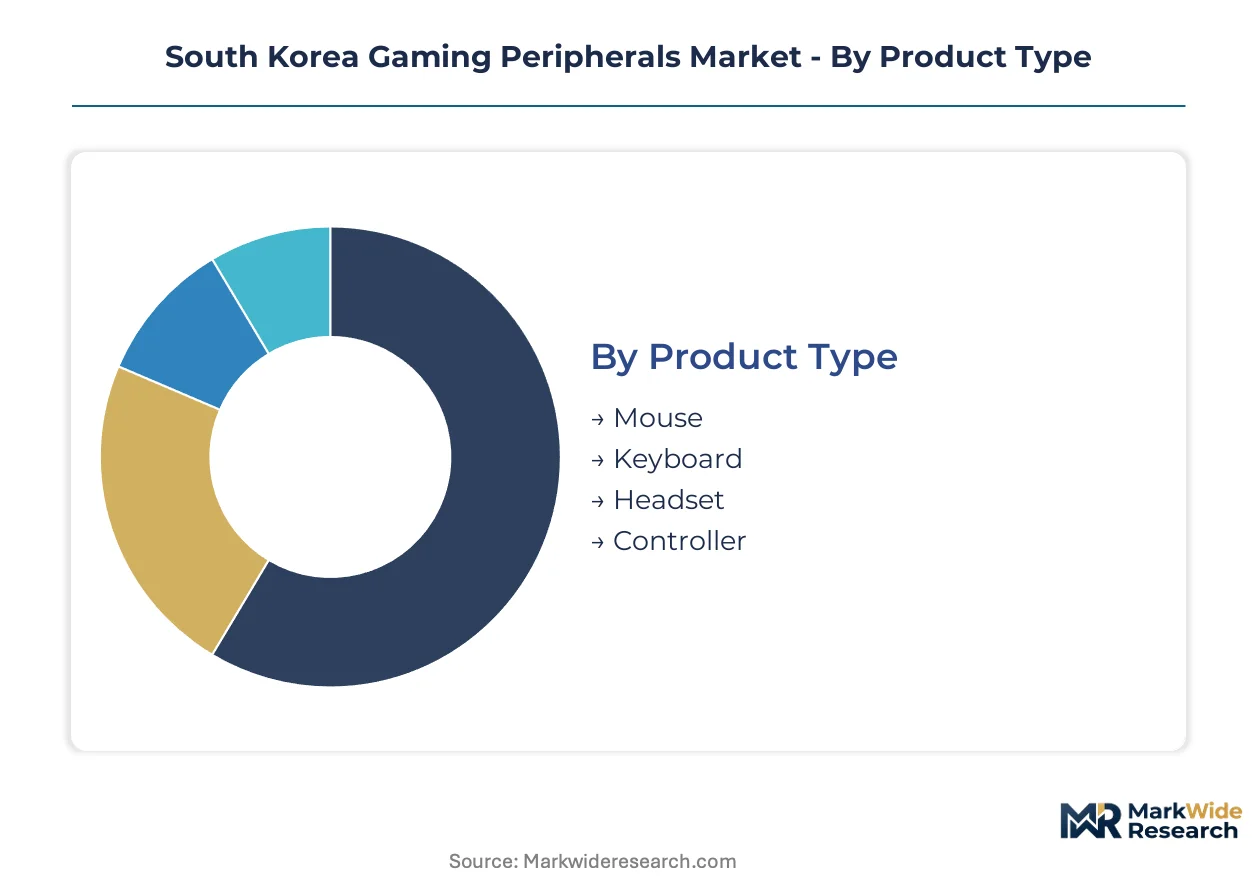
Segmentation in the South Korean gaming peripherals market reveals how smartphone gaming substitution and console platform competition differentially threaten specific product categories. Understanding these pressure gradients enables vendors to allocate R&D and certification resources across the Seoul Capital Area and Busan-Gyeongnam corridor.
Product Type:
Keyboard and mouse segments face the strongest substitution pressure from mobile esports titles, while headsets and controllers maintain defensive positioning through audio fidelity and console ecosystem lock-in.
- Keyboard:RGB mechanical switch configurations with 45-60g actuation forces dominate PC bang procurement cycles. Seoul operators refresh fleets on 18-month intervals to sustain competitive gaming environments for League of Legends and Valorant players.
- Headset:Broadcast-quality voice capture with sub-20ms latency distinguishes tournament-grade equipment from consumer audio alternatives. Streamers in Gangnam and Hongdae districts drive demand for LE Audio convergence features.
- Mouse:Sub-1ms polling rate sensors with adjustable DPI profiles serve professional esports rosters. Hall-effect sensor implementations are displacing optical architectures in premium tiers.
- Controller:Proprietary wireless protocols optimized for console ecosystems face limited PC peripheral substitution. Domestic manufacturing in Changwon supports cost-competitive PlayStation and Xbox accessory production.
Keyboard anchors the volume base through PC bang bulk procurement while headset gains share at the steepest rate via streaming economy sponsorship visibility.
Technology:
Wired configurations retain cost advantages in mass-market tiers, while wireless and Bluetooth segments capture margin expansion through MFDS certification moats and tournament latency optimization.
- Wired:USB-C and braided cable architectures sustain unit economics for entry-level gaming cafes. Busan peripheral assemblers leverage domestic wire harness suppliers to control landed costs.
- Wireless:Proprietary 2.4GHz stacks with custom latency profiles fragment competitive positioning away from universal Bluetooth implementations. Samsung Foundry capacity constraints create input cost volatility for controller IC sourcing.
- Bluetooth:SIG interoperability mandates compress development timelines while MFDS radio certification extends commercialization lead times. KCC electromagnetic compatibility testing backlogs disadvantage imported brands without local partnerships.
- Hybrid:Dual-mode connectivity bridging wired tournament reliability with wireless convenience targets team house standardization requirements. Gwangju esports valley infrastructure investments create anchor tenancy opportunities for hybrid protocol vendors.
Wired technology retains the installed base through PC bang cost sensitivity while wireless climbs the fastest as professional team sponsorships mandate cable-free broadcast aesthetics.
End User:
Casual gamer demand fragments across price tiers, whereas professional and esports user categories concentrate purchasing power through roster-level standardization.
- Professional Gamers:Team house procurement consolidation eliminates individual equipment choice in favor of vendor exclusivity per peripheral category. Razer and Logitech leverage Seoul-based partnerships to secure multi-year roster contracts.
- Streamers:Content differentiation through RGB synchronization and macro programmability drives premium peripheral adoption. Gangnam broadcast studios require sponsorship-visible equipment standardization.
- Casual Gamers:Price-sensitive demand concentrates in online retail channels with 12-18 month replacement cycles. Smartphone gaming substitution captures hours previously allocated to peripheral-dependent PC experiences.
- Esports Players:Tournament-grade specifications with sub-1ms latency requirements command premium pricing through sponsorship-driven equipment mandates. MFDS radio equipment regulations tighten compliance burdens for high-polling-rate transmission profiles.
Casual gamers anchor the volume base through mass-market accessibility while esports players expand most quickly via professional infrastructure investment across Seoul and Busan.
Distribution Channel:
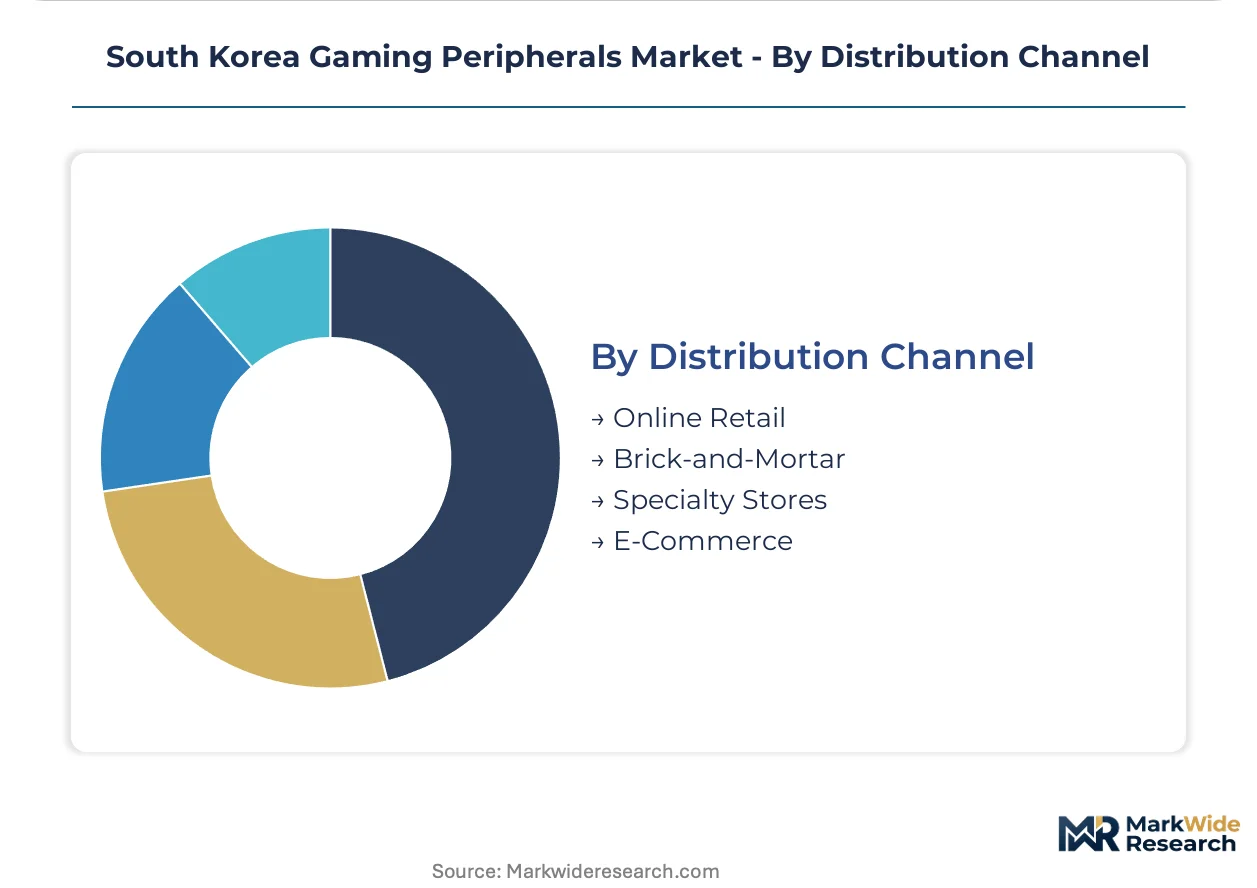
Online and e-commerce channels fragment price discovery, while specialty stores and brick-and-mortar retain experiential advantages for high-consideration peripheral purchases.
- Online Retail:Price transparency and specification comparison tools dominate casual gamer procurement patterns. Domestic platforms leverage same-day delivery networks across the Seoul Capital Area.
- Specialty Stores:Hands-on switch testing and latency demonstration stations sustain premium tier conversion rates. Yongsan Electronics Market vendors maintain technical expertise for enthusiast consultation.
- Brick-and-Mortar:Big-box retailers face compression from digital substitution but retain PC bang operator bulk contract fulfillment. Regional chains in Busan and Daegu serve secondary city gaming cafe demand.
- E-Commerce:Cross-border platforms expose Korean consumers to imported peripheral pricing, pressuring domestic OEM margin structures. KCC certification requirements filter non-compliant listings.
Online retail anchors the volume base through price-sensitive casual gamer access while specialty stores gain share at the steepest rate via experiential premium tier conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS radio equipment regulations anchor South Korea's peripheral compliance framework, with regional demand clustering around esports infrastructure investments and manufacturing corridor advantages across five distinct economic zones.
Seoul Capital Area
PC bang operators in Gangnam and Hongdae districts drive mechanical keyboard refresh cycles on 18-month intervals to sustain competitive gaming environments. The Korea Consumer Agency's product safety alerts directly influence retailer stocking decisions in Yongsan Electronics Market. Streamer sponsorship visibility requirements concentrate premium peripheral demand in broadcast studio clusters across the metropolitan region.
Busan-Ulsan
Peripheral assembly facilities in Busan and Changwon leverage regional free economic zone incentives for export-oriented production serving Southeast Asian esports markets. Domestic wire harness suppliers anchor cost-competitive manufacturing for entry-level gaming cafe equipment. The Busan-Gyeongnam corridor offers logistics advantages for re-export configurations targeting Vietnamese and Thai tournament organizers.
Daegu-Gyeongbuk
Secondary city gaming cafes sustain wired peripheral volume through price-sensitive bulk procurement patterns. Regional electronics distribution networks connect Daegu retailers to Seoul-based import channels. Local operators face compression from smartphone gaming substitution among casual player segments previously dependent on PC bang infrastructure.
Daejeon-Sejong
Government-backed esports training facilities in the administrative capital create anchor tenancy opportunities for peripheral vendors establishing non-Seoul distribution presence. Sejong's smart city infrastructure investments include tournament-grade connectivity specifications that drive sub-1ms polling rate equipment standardization. Public procurement frameworks favor domestic OEMs with established MFDS certification pipelines.
Gwangju-Honam
The municipal esports valley development program attracts peripheral vendors seeking regional hub status outside the Seoul-Busan axis. Gwangju's infrastructure investment creates team house procurement opportunities for hybrid connectivity protocol providers. Honam region gaming cafes operate on extended replacement cycles compared to capital area operators.
South Korea Gaming Peripherals Market Key Industry Players
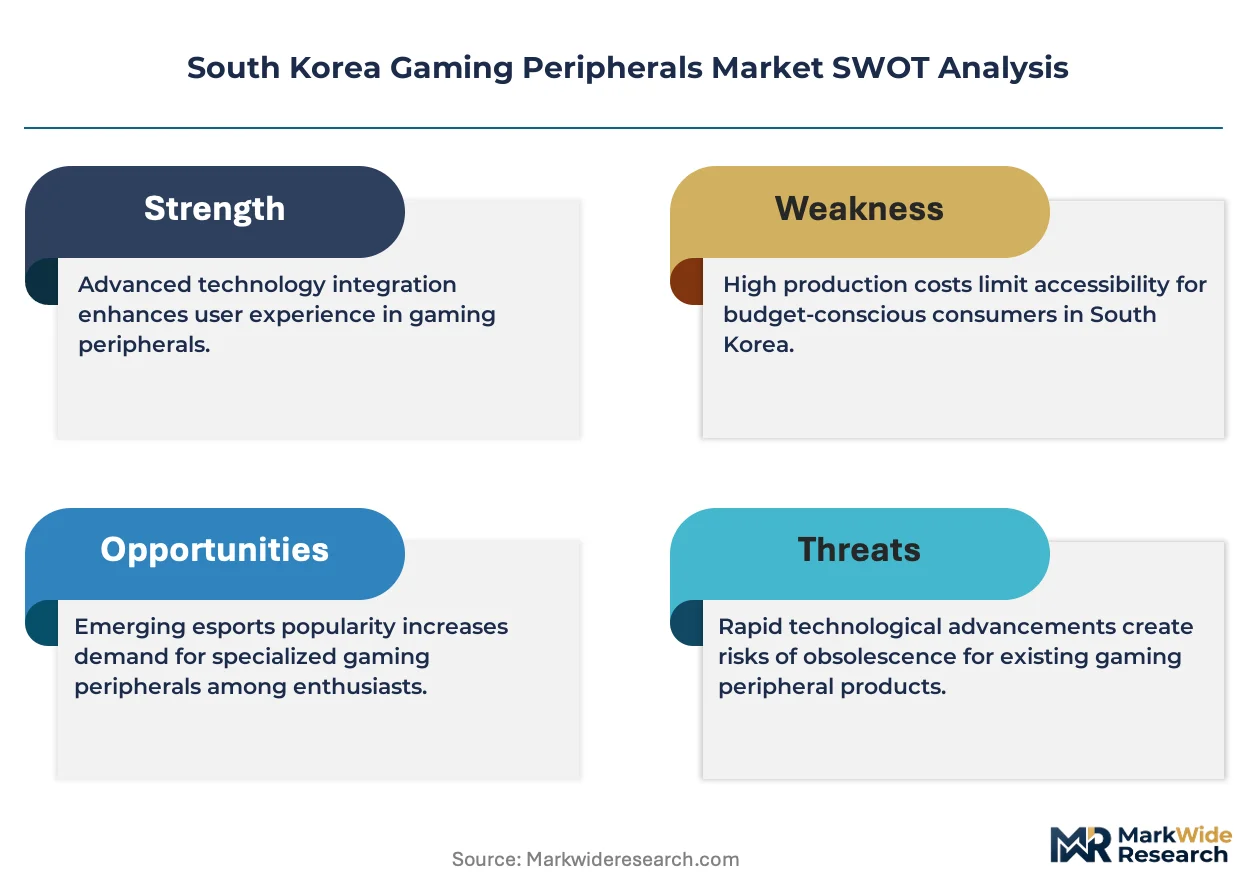
A small set of integrated leaders sits above a broader specialist tier in South Korea's gaming peripheral structure. Domestic manufacturers with captive certification pipelines and multinational brands with localized latency optimization labs occupy distinct competitive positions. Three archetypes dominate: Seoul-based esports partnership specialists, Busan corridor assemblers with regional distribution cost control, and global brands leveraging wireless protocol R&D concentration. Competitive moves center on roster-level team house exclusivity contracts and Bluetooth SIG pre-certification investments that compress rival launch timelines.
Within the integrated tier, Razer Inc. and Logitech anchor multinational positioning through Seoul-based esports partnerships and localized wireless latency facilities. ABKO Co., Ltd. represents the domestic manufacturing archetype with Busan-Gyeongnam corridor assembly scale controlling regional distribution economics. These three occupy positions spanning premium sponsorship-driven standardization and cost-competitive PC bang supply, with each exemplifying distinct certification and partnership strategies that shape competitive dynamics across the Seoul Capital Area and secondary city markets.
| Leading Market Players |
|---|
| Danawa Co., Ltd. |
| Razer Inc. |
| LG Electronics |
| SteelSeries |
| Corsair |
| Zalman Tech Co., Ltd. |
| Logitech |
| Cooler Master Technology Inc. |
| ABKO Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between PC bang operators and domestic peripheral assemblers lock in volume commitments while insulating Seoul-based buyers from Samsung Foundry wafer price volatility. These contracts bundle 18-month refresh cycles with fixed per-unit pricing that transfers semiconductor input risk to Busan-Gyeongnam manufacturers holding strategic stockpiles of wireless controller ICs.
Pricing Analysis
Project-based procurement contracts dominate PC bang fleet refreshes, with three-tier pricing structure across premium, standard, and economy levels differentiating by polling rate performance and MFDS certification tier. Price differentiation stems from Bluetooth SIG pre-certification investments and volume scale across Seoul Capital Area bulk orders. Cost compression in entry-level wired peripherals is intensifying because Vietnamese assemblers compete on landed cost for USB-C cable harnesses. Casual gamers in Daegu-Gyeongbuk exhibit highest price sensitivity, while professional esports rosters accept premium tiers for sub-1ms latency guarantees.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Seoul-based peripheral vendors serving streaming content creators, whereas strategic stockpiling of wireless chipsets characterizes Busan corridor manufacturers buffering Samsung Foundry capacity allocation volatility. Component sourcing draws from Taiwan for sensor die, China for PCB substrates, and domestic suppliers for mechanical switch assemblies. Single-source vulnerability concentrates in 12nm and 14nm controller IC fabrication where Samsung Foundry and SK Hynix dominate regional capacity. Distribution runs through Yongsan Electronics Market specialty vendors for premium tier conversion, with online retail platforms capturing mass-market volume across secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where MFDS certification pipelines create switching costs that lock professional esports organizations into established vendor relationships. Network effects concentrate among Seoul-based team houses where roster-level standardization amplifies sponsor-visible equipment mandates.
For Market Incumbents: Shield market position by deepening backward integration into Busan-Gyeongnam assembly capacity that controls regional distribution economics against Vietnamese cost competitors. Prioritize Bluetooth SIG pre-certification investments that compress rival launch timelines and extend MFDS compliance moats. Counter smartphone gaming substitution by anchoring premium wireless latency optimization labs in Seoul to secure multi-year team house exclusivity contracts. For New Entrants and Emerging Players: Differentiate on LE Audio convergence for gaming headsets targeting Gangnam broadcast studios with sub-20ms latency specifications unoccupied by incumbent portfolios. Penetrate Gwangju esports valley infrastructure investments as anchor tenancy opportunities outside Seoul-Busan concentration. Pursue hybrid connectivity protocol development bridging wired tournament reliability with wireless convenience for municipal training facility procurement. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with captive MFDS certification pipelines and established Samsung Foundry allocation relationships that sustain input cost visibility across the projection horizon. Acquisition candidates should demonstrate roster-level team house contracts with professional esports organizations and localized wireless latency optimization capabilities. Monitor Bluetooth SIG interoperability timeline compression as inflection indicator when tournament seasons misalign with certification windows.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Pipeline Investment | Pre-approved wireless chipset configurations accelerate product launches ahead of KCC testing backlogs. |
| Seoul-Based Latency Optimization Lab | Localized firmware engineering captures professional esports roster contracts from multinational competitors. |
| Busan-Gyeongnam Capacity Expansion | Regional free economic zone incentives reduce landed costs for Southeast Asian re-export configurations. |
| Team House Exclusivity Contract | Roster-level standardization eliminates individual player choice and concentrates volume with single vendors. |
| LE Audio Headset Development | Broadcast-quality voice capture with sub-20ms latency occupies white space between consumer and pro-tier equipment. |
Research Approach
The analysis maps mechanical keyboard, gaming headset, wireless mouse, and controller segments, each validated through primary interviews with PC bang operators, esports team house procurement managers, peripheral OEM product directors, and MFDS certification consultants. Secondary sources include Korea Communications Commission electromagnetic compatibility filings, Bluetooth SIG qualification listings, Korea Consumer Agency safety alerts, and Seoul Capital Area electronics distribution trade data. Bottom-up unit volume estimates from PC bang refresh cycles triangulate against top-down market value projections across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor foundry capacity allocation disclosures from Samsung and SK Hynix. The analytical framework segments by product type, technology configuration, end-user category, and distribution channel across the modeling period. CAGRs derive from weighted average of historical refresh cycle patterns and projected esports infrastructure investment trajectories. Forecast inputs incorporate MFDS regulatory timeline assumptions and Bluetooth SIG interoperability mandate compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained PC bang culture density and continued semiconductor foundry capacity allocation to consumer electronics would require recalibration. Forecasts reflect assumptions about professional esports roster expansion and streaming content creator economy growth. Revision becomes warranted when smartphone gaming substitution crosses thresholds that materially compress peripheral-dependent PC gaming hours.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global 3D Gaming Console Market
Gaming
Online Strategy Games Market
Gaming
Chinese Gaming Industry Market
Gaming
North America Gaming Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Global Tarot Cards Market
Gaming
United Kingdom Online Gambling Market
Gaming
Europe Casino Gambling Market
Gaming
Videogames Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Shooter Game Market
Gaming
Console Games Market
Gaming
AAA Games Market
Gaming
Mobile Game Controller Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Playstation Network (PSN) Market