
 Online Casino Market | 2026-2036
Online Casino Market Size, Share, and Industry Trends Forecast 2026-2036
Online Casino Market Outlook
Platform development sourcing is shifting from fully outsourced third-party solutions toward hybrid in-house and captive technology stacks. Flutter Entertainment anchors its competitive position through proprietary technology infrastructure across multiple brands. Bet365 Group Ltd. sustains market presence via vertical integration into odds-compilation and risk management systems. Entain plc differentiates through a technology-led operating model spanning proprietary platforms and acquired capabilities.
An online casino constitutes a digital wagering environment enabling real-money gambling through internet-connected interfaces, typically requiring RNG certification, SSL encryption, and jurisdictional licensing to ensure game integrity and player fund protection. Slots commands the largest revenue share among game type segments due to low operational complexity and high player frequency. Live dealer offerings represent the fastest-expanding category as streaming infrastructure and latency reduction technology mature. Mobile device type segments capture the dominant share of session volume as smartphone penetration and 5G connectivity improve.
The UK Gambling Commission, state-level gaming regulators across the United States, and Malta Gaming Authority collectively shape market access through licensing frameworks, advertising restrictions, and responsible gambling mandates including self-exclusion protocols and deposit limits. Compliance costs and tax rate differentials between jurisdictions directly influence operator profitability and market entry sequencing. Stakeholders must monitor regulatory divergence between permissive and restrictive jurisdictions to calibrate geographic expansion and technology investment priorities.
Market Dynamics
Mobile-first wagering architecture is compressing platform development cycles and forcing operators to rebuild core infrastructure around smartphone-native experiences rather than desktop adaptations.
Growth Catalysts
- State-level licensing liberalization:New Jersey, Pennsylvania, and Michigan frameworks create contiguous licensed market corridors that reduce operator compliance fragmentation.
- 5G latency reduction:Sub-20 millisecond streaming enables live dealer table expansion into previously bandwidth-constrained rural subscriber bases.
- Self-exclusion protocol mandates:UK Gambling Commission requirements build consumer trust metrics that accelerate deposit velocity among risk-averse demographics.
Market Restraints
- Tax rate divergence:Pennsylvania's 54% gross gaming revenue levy versus New Jersey's 15% creates margin compression that distorts competitive investment allocation.
- RNG certification bottlenecks:Limited accredited testing laboratories in Malta and Isle of Man extend platform launch timelines by 4-8 months.
- Payment processor concentration:Visa and Mastercard chargeback policies impose reserve requirements that constrain working capital for emerging operators.
Strategic Opportunities
- Brazil regulatory opening:Provisional Measure 1.185/2023 establishes federal licensing anticipated to unlock Latin America's largest addressable player base.
- Esports wagering convergence:Counter-Strike and League of Legends tournament integrity partnerships create differentiated product verticals with younger demographic capture.
- Alternative payment rails:Pix instant settlement and cryptocurrency custody solutions reduce friction in markets with underdeveloped card penetration.
Industry Challenges
- Responsible gambling engineering talent:Shortage of data scientists specializing in behavioral anomaly detection limits real-time intervention system deployment.
- Legacy platform migration:Flash-to-HTML5 conversion of back-catalog slot titles demands frontend redevelopment that diverts product roadmap resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Casino Market |
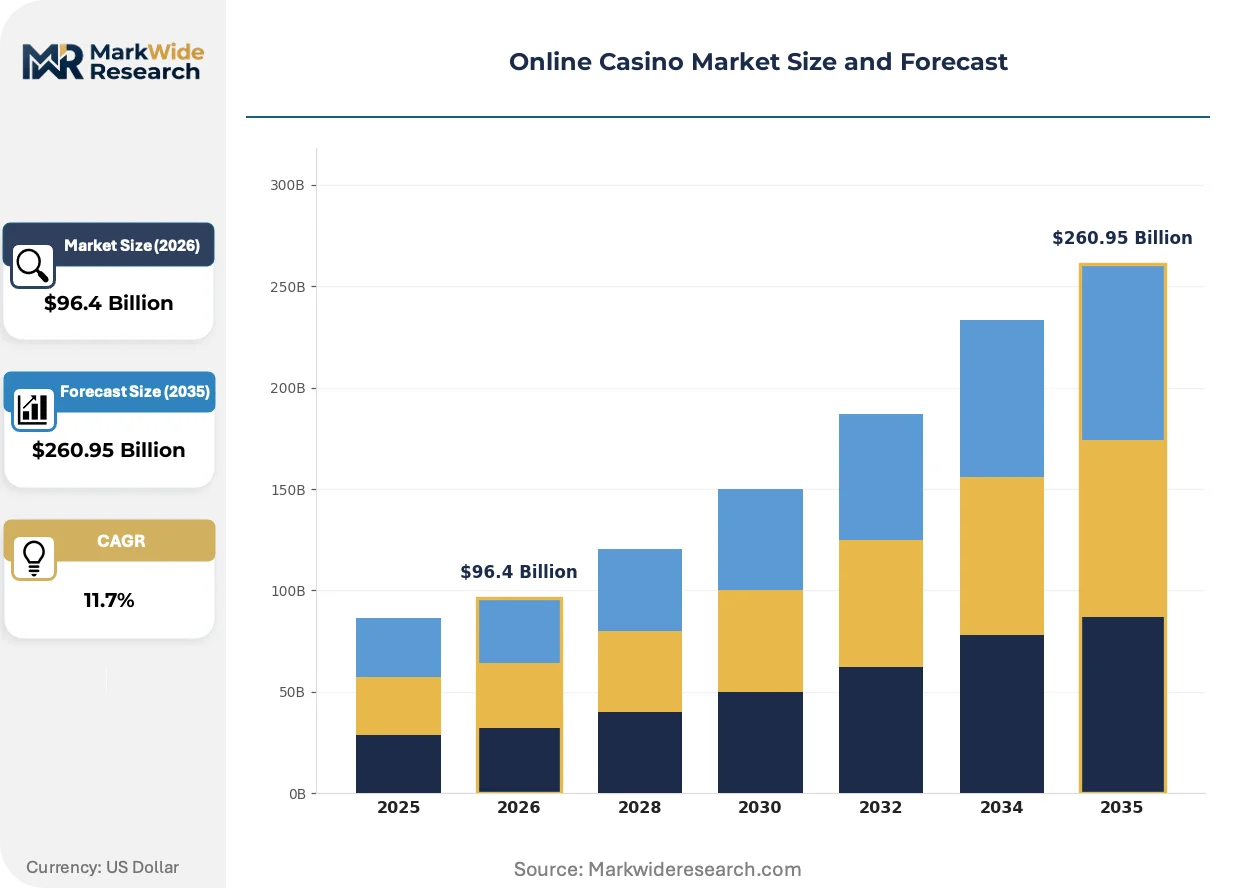
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $260.95 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Slots, Table Games, Live Dealer, Sports Betting Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cryptocurrencies Device Type: Desktop, Mobile, Tablet, Hybrid Customer Type: New Players, Loyal Customers, High Rollers, Casual Gamblers |
| Companies Covered | Flutter Entertainment, Bet365 Group Ltd., Entain plc, Caesars Entertainment, DraftKings, MGM Resorts International, Evoke plc, Betsson AB, Playtech plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Casino Market Strategic Shifts
Streaming infrastructure maturation and artificial intelligence deployment are reconfiguring how operators acquire, retain, and protect players across regulated jurisdictions.
Artificial intelligence risk engines are integrating real-time behavioral biometrics with transaction pattern analysis to identify problem gambling indicators before self-exclusion requests. Tier-one operators deploy these systems across 80% of active player sessions. The technology is integrating predictive intervention workflows that trigger cooling-off periods without human operator review.
Malta Gaming Authority technical standards for live dealer studios now mandate ISO 27001 certification for all streaming infrastructure providers. This creates compliance tiering that separates vertically integrated operators from white-label platform tenants. Studios in Romania and Bulgaria face 18-month certification backlogs that delay market entry.
Player acquisition economics are compressing as cost-per-qualified-deposit metrics rise across saturated state markets. Operators now prioritize cross-sell optimization over new player onboarding in mature jurisdictions like New Jersey. This behavioral pivot manifests in loyalty program restructuring that weights casino play toward sportsbook bonus eligibility.
Online Casino Market Segmentation
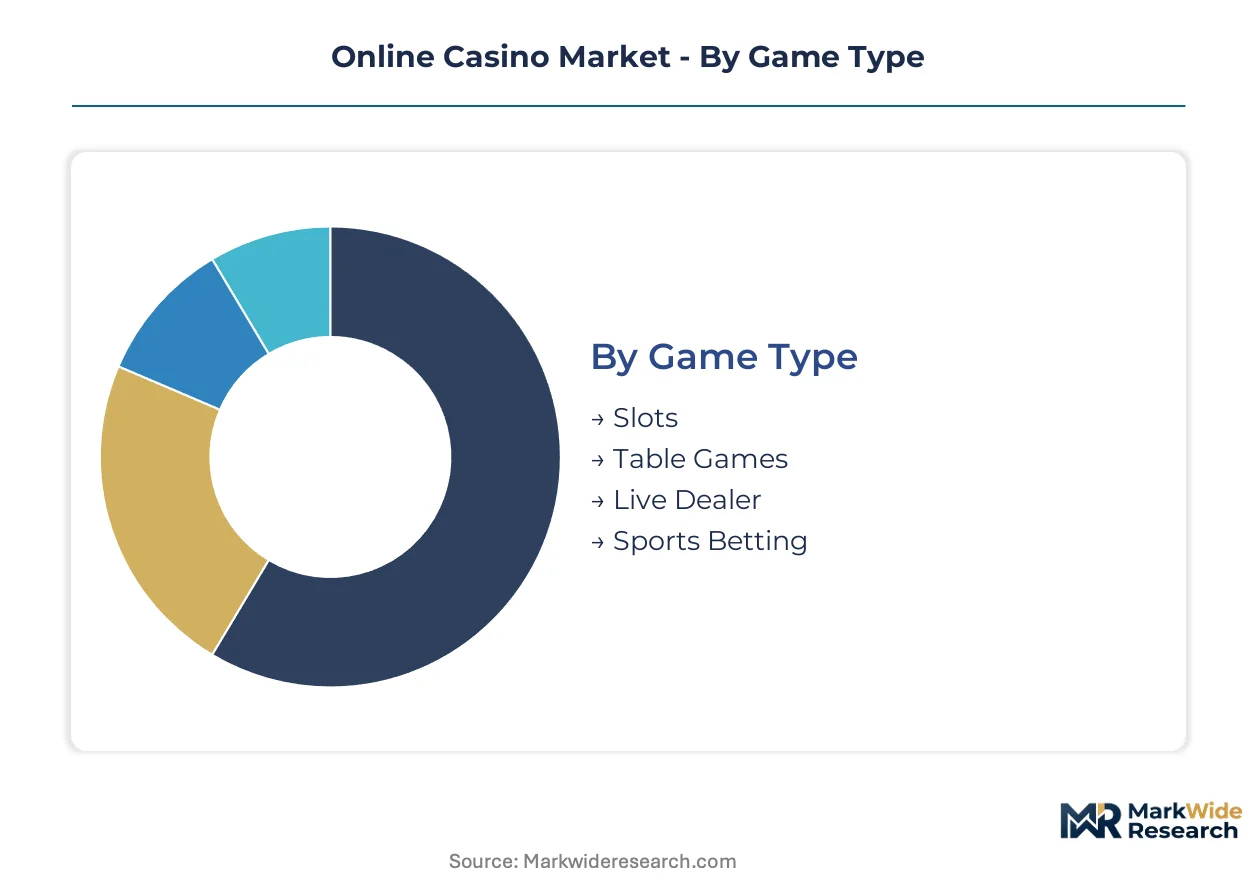
Segmentation in online casino markets reveals how player behavior, technology access, and payment infrastructure fragment addressable demand. Operators calibrate platform architecture, bonus mechanics, and compliance workflows against these dimensions to optimize unit economics across divergent player profiles.
Game Type:
Standalone game categories operate as independent revenue centers with distinct technology stacks, while embedded formats integrate across operator platforms through unified wallet systems.
- Slots:Random number generator engines power reel-spinning mechanics with return-to-player percentages typically fixed between 92-97%. Demand concentrates most intensely in Germany and the United Kingdom where high-frequency, low-stakes session patterns dominate player behavior. Regulatory mandates for independent RNG certification from Malta Gaming Authority-accredited laboratories extend deployment timelines.
- Live Dealer:Real-time video streaming connects players to physical gaming tables via sub-100 millisecond latency infrastructure. Expansion concentrates in bandwidth-improved rural United States markets where 5G rollout enables previously inaccessible demographics. ISO 27001 certification requirements for streaming studios create compliance tiering that favors vertically integrated operators.
- Table Games:Digital renditions of blackjack, roulette, and baccarat with automated dealing algorithms.
- Sports Betting:Odds-compilation engines integrated with real-time event data feeds for wagering on athletic competitions.
Volume placements concentrate in Slots; the faster expansion belongs to Live Dealer.
Payment Method:
Payment architecture selection directly shapes geographic market access and player conversion funnels, with cost-tier differentiation emerging between legacy rails and emerging alternatives.
- Credit Cards:Visa and Mastercard networks dominate in mature markets with established banking infrastructure. Deposit velocity remains highest in the United States where chargeback dispute resolution favors operators under federal Electronic Fund Transfer Act frameworks. Reserve requirements of 5-10% imposed by card networks constrain working capital for emerging market entrants.
- E-Wallets:PayPal, Skrill, and Neteller provide intermediary custody that shields player bank statements from direct gambling references. Adoption concentrates in the United Kingdom where Gambling Commission advertising restrictions make discreet funding mechanisms commercially valuable. Integration APIs from specialist providers reduce operator development overhead.
- Bank Transfers:Direct ACH and wire mechanisms with slower settlement but lower processor fees.
- Cryptocurrencies:Blockchain-settled transactions offering pseudonymity and reduced cross-border friction.
Transaction volume concentrates in Credit Cards; E-Wallets are climbing the fastest as privacy-sensitive demographics expand.
Device Type:
Hardware preference segmentation tracks infrastructure maturity and demographic cohort behavior, with mobile-native development now displacing desktop-first platform architecture.
- Mobile:Smartphone-optimized interfaces built on responsive HTML5 frameworks with touch-native controls. Session volume dominates in millennial and Gen Z demographics across United States state-licensed markets where 5G penetration exceeds 80% in metropolitan corridors. Flutter Entertainment and Entain plc have rebuilt core infrastructure around smartphone-native experiences rather than desktop adaptations.
- Desktop:Traditional browser-based and downloadable clients with expanded screen real estate for multi-table play. Retention concentrates among high-stakes poker specialists in Germany where complex tournament interfaces demand larger displays. Legacy Flash-to-HTML5 conversion demands continue diverting product roadmap resources.
- Tablet:Mid-size touch interfaces bridging mobile convenience with expanded visual field.
- Hybrid:Cross-platform account synchronization enabling seamless session handoff between devices.
Session volume concentrates in Mobile; Hybrid architectures are gaining share fastest as player expectations for continuity harden.
Customer Type:
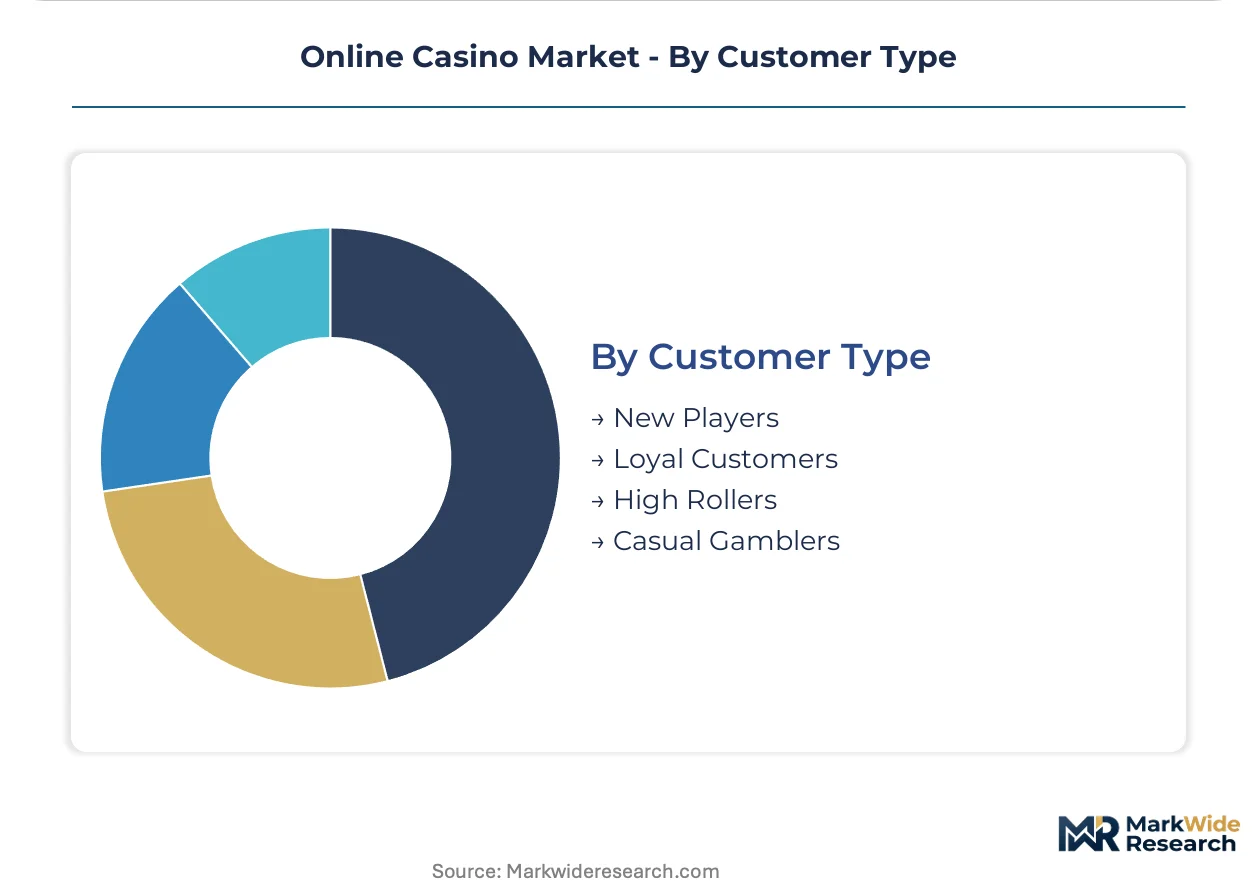
Player lifecycle segmentation determines acquisition spend allocation, retention mechanics, and responsible gambling intervention intensity across divergent risk and value profiles.
- New Players:First-time depositors acquired through paid media and affiliate partnerships with bonus-locked initial engagement. Conversion cost inflation concentrates in saturated New Jersey and Pennsylvania markets where cost-per-qualified-deposit metrics have compressed operator margins. Artificial intelligence risk engines now deploy real-time behavioral biometrics across 80% of active sessions to identify problem gambling indicators.
- High Rollers:VIP-tier players generating disproportionate revenue share with dedicated account management and customized limit structures. Concentration persists in London and Macau-linked digital operations where private streaming studios replicate land-based casino hospitality. Self-exclusion protocol mandates from UK Gambling Commission build trust metrics that sustain deposit velocity.
- Loyal Customers:Repeat depositors with established play patterns and elevated lifetime value projections.
- Casual Gamblers:Low-frequency, low-stake players with sporadic engagement and minimal bonus dependency.
Revenue concentration sits with Loyal Customers; High Rollers show the steepest expansion trajectory as VIP streaming infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server infrastructure and payment processing hubs cluster in Malta, Gibraltar, and the Isle of Man, anchoring operator licensing decisions across mature European markets and emerging Latin American jurisdictions.
United States
State-by-state licensing frameworks in New Jersey, Pennsylvania, and Michigan generate contiguous regulated corridors that reduce compliance fragmentation for multi-state operators. The Wire Act and state gaming commissions impose advertising restrictions and responsible gambling mandates including self-exclusion protocols. Atlantic City and Detroit host live dealer studios where 5G infrastructure expansion enables rural market penetration previously blocked by bandwidth constraints.
United Kingdom
High-frequency, low-stakes slot play dominates player behavior among millennial demographics with established digital banking relationships. UK Gambling Commission technical standards and advertising restrictions create compliance tiering that separates proprietary platform operators from white-label tenants. London anchors VIP-tier operations where private streaming studios replicate land-based casino hospitality for high-roller segments.
Germany
Complex tournament interfaces for poker and table games sustain desktop retention among high-stakes specialists despite mobile session volume dominance elsewhere. Interstate Treaty on Gambling implementation creates federal licensing harmonization that reduces operator market entry sequencing complexity. Hesse and Bavaria concentrate platform development talent where Flash-to-HTML5 conversion demands divert product roadmap resources.
Brazil
Pix instant settlement infrastructure reduces payment friction in a market with underdeveloped card penetration and strong mobile-first demographics. Provisional Measure 1.185/2023 establishes federal licensing anticipated to unlock Latin America's largest addressable player base. São Paulo anchors emerging operator headquarters where Portuguese-language live dealer studios target cross-border Spanish-speaking markets.
Canada
Provincial lottery corporation partnerships create regulated market access with lower tax rate exposure than US state markets. Financial Consumer Agency oversight and provincial gaming authority mandates shape deposit limit and self-exclusion protocol requirements. Ontario and Quebec concentrate affiliate marketing networks where cost-per-qualified-deposit inflation remains below saturated US state benchmarks.
Online Casino Market Competitive Environment
Global majors compete with regional champions across platform technology and regulatory licensing dimensions. Market structure consolidates around vertically integrated operators with proprietary infrastructure and specialist providers serving white-label tenants. Three archetypes dominate: captive technology developers, odds-compilation specialists, and streaming infrastructure operators. Competitive moves concentrate on M&A for regulatory licenses and technology licensing for rapid market entry.
Within the captive technology tier, Flutter Entertainment and Entain plc exemplify operators that have rebuilt core infrastructure around smartphone-native experiences rather than desktop adaptations. Bet365 Group Ltd. occupies a position emphasizing vertical control over risk management systems. These three companies represent the dominant competitive anchors across European and North American licensed jurisdictions.
| Leading Market Players |
|---|
| Flutter Entertainment |
| Bet365 Group Ltd. |
| Entain plc |
| Caesars Entertainment |
| DraftKings |
| MGM Resorts International |
| Evoke plc |
| Betsson AB |
| Playtech plc |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up platform specialists anchor supply-side ownership patterns, compressing vendor margins through consolidated procurement while enforcing pricing discipline across white-label tenant networks. This ownership structure concentrates technology licensing leverage in Malta and Gibraltar, feeding downstream pricing power into regulated market access fees.
Pricing Analysis
Warranty-bundled RNG certification and compliance guarantees separate premium-tier platform providers from unbundled economy vendors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 certification status and jurisdictional license breadth. Cost compression in economy tiers intensifies because Flash-to-HTML5 conversion overhead diverts product roadmap resources from margin recovery. Emerging operators show highest price sensitivity, while established multi-state incumbents absorb premium pricing for captive technology stacks.
Supply Chain Analysis
Regional distribution centers in Malta, Gibraltar, and the Isle of Man anchor hub-and-spoke patterns for server infrastructure and payment processing. Malta, Romania, and Bulgaria concentrate live dealer studio capacity, drawing from specialized streaming hardware, certified gaming equipment, and ISO-accredited cybersecurity labor pools. Single-source vulnerability in RNG testing laboratory accreditation extends platform launch timelines. Distribution runs through jurisdictional licensing corridors that gate market access before downstream operator deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform technology consolidation is accelerating as tax rate divergence and certification bottlenecks force subscale operators toward distressed exits or white-label absorption.
For Market Incumbents: Hedge regulatory fragmentation by building contiguous multi-state licensing corridors that reduce compliance overhead. Prioritize captive supply of live dealer streaming infrastructure to bypass ISO 27001 certification backlogs that delay market entry. Defend against emerging Pix-enabled Brazilian entrants through preemptive Portuguese-language studio investment. For New Entrants and Emerging Players: Launch via alternative payment rail integration targeting underpenetrated Latin American corridors where card penetration remains shallow. Brazil's federal licensing opening under Provisional Measure 1.185/2023 represents the most penetrable geography. Lead with esports wagering verticals to capture younger demographics ahead of established slot-centric incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-caps with proprietary RNG engines and existing Malta Gaming Authority licensing in Central and Eastern European jurisdictions. Long-term viability hinges on 5G infrastructure maturation enabling rural live dealer expansion. Monitor Brazil regulatory implementation velocity as the primary inflection indicator for Latin American portfolio allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Platform Development | Captive technology stacks at Flutter Entertainment and Entain plc reduce third-party licensing dependency. |
| Live Dealer Studio Certification | ISO 27001 compliance for streaming infrastructure creates tiered market access separating integrated operators. |
| Multi-State Licensing Corridors | Contiguous New Jersey-Pennsylvania-Michigan frameworks compress compliance fragmentation for scaling operators. |
| Alternative Payment Integration | Pix instant settlement and cryptocurrency custody reduce friction in Brazil's underdeveloped card markets. |
| Esports Wagering Convergence | Counter-Strike and League of Legends partnerships unlock differentiated verticals with Gen Z demographic capture. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across platform development executives, gaming commission licensing officers, payment processor risk managers, and live dealer studio operations directors. UK Gambling Commission technical standards, Malta Gaming Authority certification databases, and state-level gaming commission enforcement actions provided jurisdictional validation. Bottom-up player session volume estimates triangulated against top-down operator revenue disclosures.
Granularity-level modeling segmented the analysis window by game type, device architecture, payment rail, and customer lifecycle stage. CAGRs derived from historical state-market penetration curves adjusted for 5G rollout velocity and regulatory liberalization sequencing. Forecast inputs incorporated RNG certification backlog durations, tax rate differential impacts on operator margins, and streaming infrastructure latency improvement trajectories.
Regulatory reversal, payment processor policy shifts, and responsible gambling mandate intensification are the dominant revision risks. Forecasts reflect base-case assumptions regarding jurisdictional licensing continuity and technology certification throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Serious Games Market
Gaming
Global Online Board Games Market
Gaming
Slot Machine Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Europe Gaming Peripherals Market
Gaming
Game API Market
Gaming
VR Gaming Market
Gaming
MMORPG Gaming Market
Gaming
North America in-Game Advertising Market
Gaming
Global Game Testing Service Market
Gaming
Traditional Casual Games Market
Gaming
Global Online Adventure Games Market
Gaming
Game Applications Market
Gaming
Galgames Market
Gaming
Africa Gaming Market
Gaming
Gaming Gadgets Market