
 In-App Advertising Market | 2026-2036
In-App Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
In-App Advertising Market Intelligence
Programmatic guaranteed deals and revenue-sharing partnerships are narrowing the capital gap between independent publishers and platform-owned inventory. AppLovin Corporation leverages its integrated software stack to control both supply and demand paths. Meta Platforms sustains competitive pressure through its first-party data reservoir across messaging and social apps. Google anchors market infrastructure through its mediation and bidding tools that serve the majority of Android developers.
In-app advertising encompasses promotional content rendered within native software environments on mobile and connected devices, typically delivered through real-time bidding protocols or direct-sold insertion orders that leverage device identifiers, contextual signals, and behavioral cohorts for targeting. Its primary commercial purpose is to monetize free-to-use software while enabling advertisers to reach users during active engagement sessions. Video ads command premium rate structures due to completion-based pricing and brand safety controls, while native ads integrate with content feeds to sustain higher viewability scores. The gaming vertical generates outsized impression volumes through rewarded placements that exchange value for user attention.
The Federal Trade Commission scrutinizes dark patterns and deceptive ad disclosures in mobile interfaces, while the California Consumer Privacy Act imposes opt-out requirements on data sales that reshape audience targeting architectures. The European Union's Digital Services Act introduces algorithmic transparency mandates for large platforms that will force inventory classification and ad repository disclosures. Stakeholders must monitor regulatory fragmentation between privacy-first jurisdictions and markets permitting identifier-based targeting to determine where to concentrate technical compliance investments.
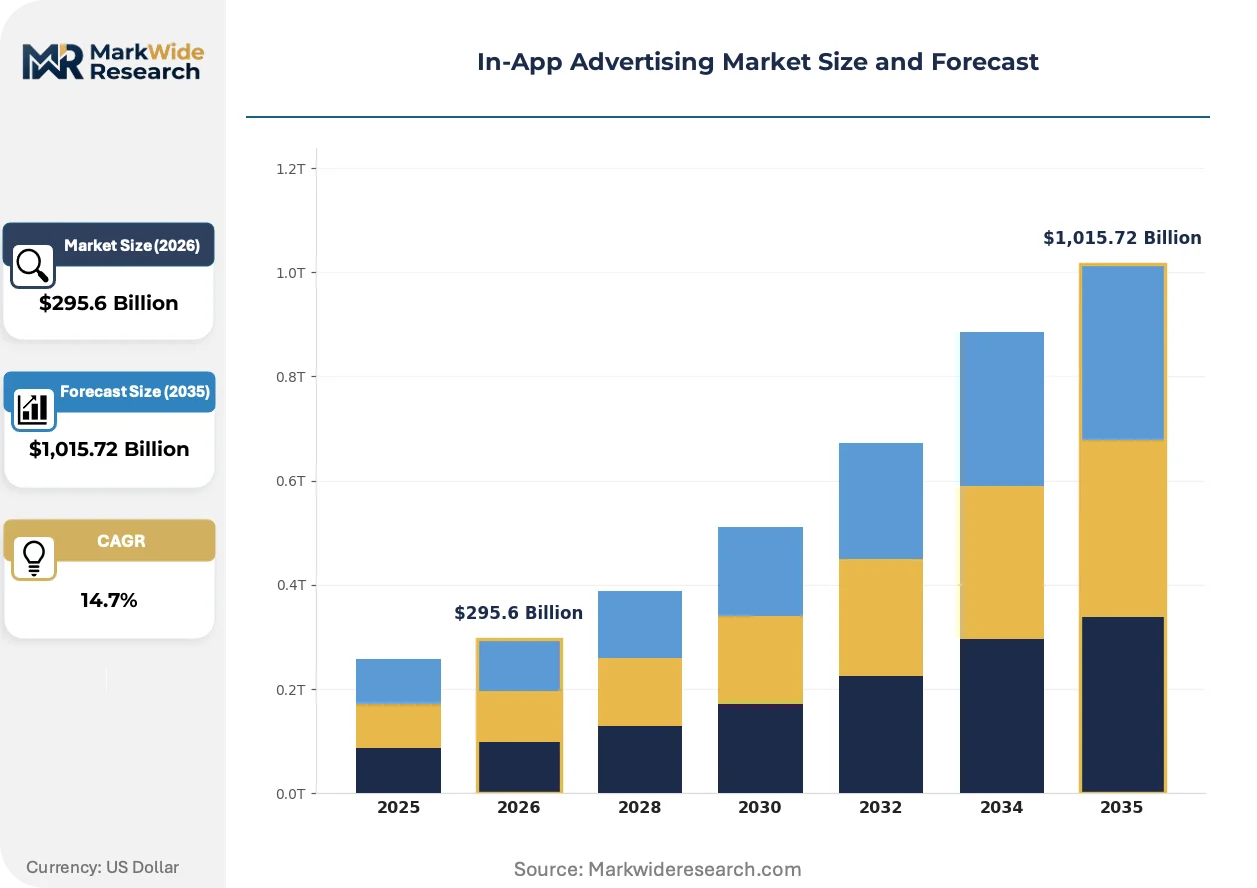
Market Dynamics
Apple's App Tracking Transparency framework and Google's Privacy Sandbox are fragmenting attribution methodologies, forcing publishers to rebuild targeting architectures around contextual signals and first-party data reservoirs rather than device identifiers.
Growth Catalysts
- Programmatic guaranteed deals:Brand advertisers are committing fixed budgets to premium gaming inventory through direct-sold insertion orders, stabilizing revenue predictability for mobile publishers.
- Rewarded video placements:Gaming developers exchange in-game currency for completed ad views, driving completion rates above standard interstitial formats.
- Privacy Sandbox adoption:Google's Topics API and Protected Audience API enable interest-based targeting without cross-app tracking, preserving addressability for Android developers.
Market Restraints
- Identifier deprecation:Apple's IDFA opt-in rates below 25% in major markets compress retargeting effectiveness and CPM premiums for iOS inventory.
- Supply concentration:Meta Platforms and Google control the majority of demand-side platform liquidity, constraining independent publishers' negotiating leverage.
- Creative production costs:Interactive and playable ad formats require specialized development resources that mid-tier publishers cannot sustain.
Strategic Opportunities
- Connected TV convergence:Mobile gaming studios are porting titles to smart TV platforms, extending addressable inventory into living room environments.
- Retail media networks:E-commerce apps with first-party purchase data are opening sponsored placement inventory to endemic and non-endemic advertisers.
- India's digital infrastructure:Unified Payments Interface penetration and affordable data pricing are accelerating app install volumes among price-sensitive consumers.
Industry Challenges
- SKAdNetwork complexity:Apple's deterministic attribution framework requires specialized engineering resources to implement conversion value schemas and postback optimization.
- Cross-platform measurement:Advertisers struggle to reconcile web and in-app conversion paths, complicating unified campaign planning and budget allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-App Advertising Market |
| Market Size in 2026 | $295.6 Billion |
| Market Size in 2035 | $1,015.72 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Banner Ads, Interstitial Ads, Video Ads, Native Ads Device Type: Smartphones, Tablets, Smart TVs, Wearables Vertical: Gaming, Retail, Entertainment, Education Engagement Model: Cost Per Click, Cost Per Impression, Cost Per Acquisition, Subscription |
| Companies Covered | Google (Alphabet Inc.), Meta Platforms, Apple Inc., AppLovin Corporation, Unity Technologies, InMobi, Chartboost Inc., Digital Turbine Inc., Liftoff Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-App Advertising Market Strategic Shifts & Innovations
Real-time bidding infrastructure is undergoing architectural transformation as privacy-preserving alternatives to device identifiers reach production scale across major mobile operating systems.
Contextual intelligence platforms are collapsing the precision gap left by identifier deprecation. These systems analyze app content, session patterns, and device signals to infer audience intent without personal data. Mobile gaming publishers in the United States and Western Europe are deploying these tools at scale. The technology is collapsing differentiation between identifier-based and privacy-first targeting efficacy.
The European Union's Digital Services Act introduces algorithmic transparency mandates for large platforms that will force inventory classification and ad repository disclosures. Platforms exceeding 45 million monthly active users must publish detailed information on content moderation and recommendation systems. Gaming and social app publishers operating across EU member states are restructuring compliance teams to meet these documentation requirements.
Brand safety verification is displacing basic viewability as the primary quality threshold for premium budgets. Advertisers now demand granular control over adjacent content categories, particularly in user-generated gaming environments. This shift is most pronounced in the United States, where major holding companies have consolidated preferred vendor lists to a handful of accredited measurement providers.
In-App Advertising Market Segmentation
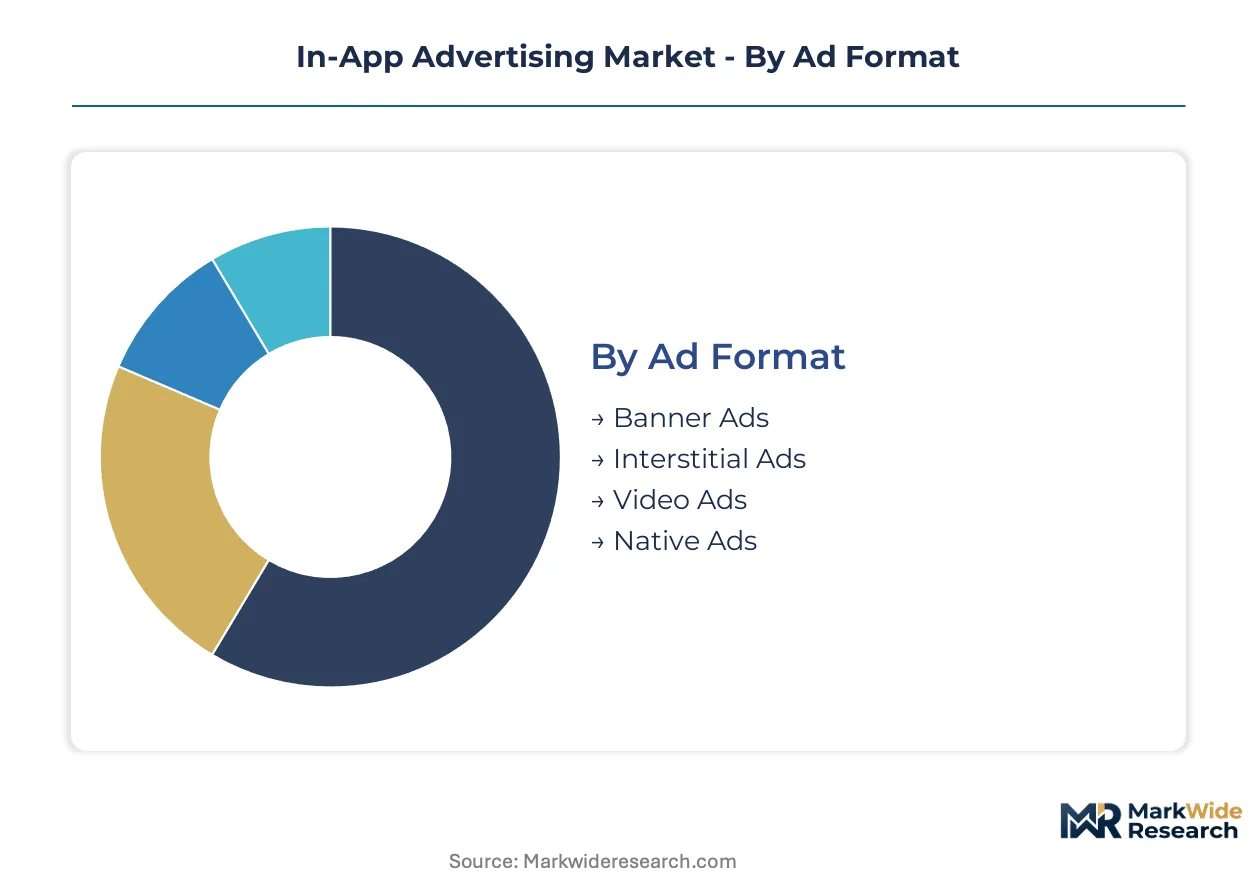
In-app advertising segmentation determines inventory valuation mechanics and buyer procurement patterns. Format characteristics dictate creative production requirements, while device type shapes addressable audience scale. Vertical alignment controls seasonality exposure, and engagement models define revenue predictability for publisher monetization strategies.
Ad Format:
Video and native formats refresh creative assets most frequently due to brand safety demands, while banner inventory cycles slower with standardized templates.
- Video Ads:Full-screen or rewarded placements that command completion-based pricing. Gaming publishers in the United States deploy these for rewarded currency exchanges, though SKAdNetwork attribution complexity raises technical implementation costs.
- Native Ads:Feed-integrated units that mimic surrounding content architecture. Retail apps in Western Europe favor these for sponsored product placements as identifier deprecation accelerates contextual targeting adoption.
- Interstitial Ads:Full-screen overlays displayed at natural transition points.
- Banner Ads:Persistent rectangular units anchored to screen edges.
Video Ads anchors the volume base while Native Ads gains share at the steepest rate.
Device Type:
Smartphone inventory turns over fastest due to session frequency, whereas Smart TV placements require longer campaign commitments from brand advertisers.
- Smartphones:Dominant addressable inventory with highest impression density per user. India's Unified Payments Interface penetration drives app install volumes among price-sensitive consumers, expanding Android addressable audiences.
- Smart TVs:Emerging inventory channel as mobile gaming studios port titles to living room platforms. The United States leads connected TV convergence with consolidated preferred vendor lists for brand safety verification.
- Tablets:Mid-tier engagement sessions with higher viewability completion rates.
- Wearables:Limited-format inventory constrained by screen dimensions and interaction models.
Smartphones dominate revenue contribution while Smart TVs climbs the fastest adoption curve.
Vertical:
Gaming inventory exhibits the highest turnover velocity through rewarded placements, while Education maintains longer campaign durations with institutional budget cycles.
- Gaming:Rewarded video placements exchange in-game currency for completed views. The European Union's Digital Services Act forces algorithmic transparency documentation for publishers exceeding 45 million monthly active users.
- Retail:First-party purchase data enables sponsored placement inventory for endemic and non-endemic advertisers. E-commerce apps in the United States leverage closed-loop attribution through internal transaction records.
- Entertainment:Streaming and content apps with subscription conversion objectives.
- Education:Institutional and consumer learning platforms with extended user lifecycles.
Gaming anchors the volume base while Retail expands most quickly through retail media network proliferation.
Engagement Model:
Cost Per Impression contracts cycle fastest with programmatic guaranteed deals, while Subscription models lock in longest revenue commitments.
- Cost Per Acquisition:Performance-based pricing tied to downstream conversion events. Apple's IDFA opt-in rates below 25% in major markets compress retargeting effectiveness for iOS inventory.
- Cost Per Impression:Viewability-verified billing standard for brand awareness campaigns. Google's Topics API and Protected Audience API preserve addressability for Android developers without cross-app tracking.
- Cost Per Click:Engagement-based pricing common in user acquisition campaigns.
- Subscription:Recurring revenue arrangements with premium inventory access.
Cost Per Impression anchors the volume base while Cost Per Acquisition gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border data flows and platform compliance costs dominate the trade balance in in-app advertising services. The United States maintains a surplus in demand-side platform exports while importing ad tech engineering talent from India and Eastern Europe. Regulatory fragmentation across privacy jurisdictions is reshaping where publishers concentrate technical infrastructure investments.
United States
Brand safety verification vendors and programmatic guaranteed deal infrastructure concentrate in New York and San Francisco. The FTC enforces dark pattern prohibitions and deceptive ad disclosure requirements through Section 5 authority. Los Angeles hosts mobile gaming studios expanding rewarded video inventory to capture entertainment advertiser budgets.
China
Domestic super-app ecosystems generate closed-loop advertising inventory independent of Western mediation tools. MIIT enforces data localization requirements under cybersecurity and personal information protection frameworks. Shenzhen's developer cluster produces hardware-integrated ad formats for OEM pre-installation channels.
Germany
Automotive and industrial advertisers drive demand for contextual targeting solutions as IDFA alternatives. The BfDI and state data protection authorities enforce GDPR consent requirements for behavioral profiling. Berlin's ad tech startups specialize in privacy-preserving measurement protocols for cross-border campaigns.
India
Unified Payments Interface penetration and affordable mobile data pricing accelerate app install volumes among price-sensitive consumers. TRAI maintains net neutrality frameworks that affect zero-rating and carrier billing integration for in-app purchases. Bangalore's developer ecosystem supplies engineering talent for global mediation and attribution platforms.
United Kingdom
Financial services and retail media advertisers demand granular inventory classification for brand safety compliance. The ICO enforces transparency requirements under GDPR and the UK Data Protection Act for algorithmic ad delivery. London's holding company headquarters consolidate preferred vendor lists to accredited measurement providers.
In-App Advertising Market Key Industry Players
On the supply side, the industry is bifurcated between integrated platform stacks and specialized point solutions. Consolidation pressure concentrates demand liquidity among three to four dominant intermediaries. Strategic archetypes include full-stack monetization platforms, standalone demand-side platforms, and publisher-facing mediation layers. Competitive moves center on M&A for audience data assets and strategic partnerships for cross-platform measurement.
Within the integrated platform tier, Google and Meta Platforms occupy positions as infrastructure anchors controlling both supply path and demand liquidity. AppLovin Corporation exemplifies the vertical software stack archetype, combining supply-side tools with demand-side algorithms. These three entities represent the dominant competitive anchors against which independent publishers and specialized vendors define differentiation strategies.
| Leading Market Players |
|---|
| Google (Alphabet Inc.) |
| Meta Platforms |
| Apple Inc. |
| AppLovin Corporation |
| Unity Technologies |
| InMobi |
| Chartboost Inc. |
| Digital Turbine Inc. |
| Liftoff Inc. |
| Others |
Cost & Logistics Intelligence
Programmatic inventory concentration in the United States and Western Europe funnels margin pools toward demand-side platforms with first-party data reservoirs, while publishers in emerging markets absorb pricing compression from identifier deprecation and attribution complexity.
Pricing Analysis
Brand advertisers anchor rate structures through programmatic guaranteed deals that stabilize CPM floors for premium gaming inventory. Three-tier pricing stratifies across premium video placements with brand safety verification, standard interstitial formats with basic viewability metrics, and remnant banner inventory sold through open auction. Pricing pressure stems from Apple's IDFA opt-in rates below 25 percent in major markets, which compresses retargeting premiums for iOS inventory. Mid-tier publishers exhibit highest price sensitivity due to creative production cost burdens for interactive formats.
Supply Chain Analysis
Cloud infrastructure providers in the United States, Ireland, and Singapore hold capacity concentration for real-time bidding infrastructure and ad-serving technology. Supply chains draw from specialized data center compute, low-latency networking equipment, and identity-resolution software components. Single-source vulnerability runs through Google and Meta Platforms' control of demand-side liquidity and mediation tools. Distribution runs through self-serve platforms for independent developers and direct enterprise sales for major publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in in-app advertising hinge on interoperability between privacy-preserving attribution frameworks and first-party data activation, with Apple's SKAdNetwork and Google's Privacy Sandbox forcing ecosystem-wide architecture rebuilds.
For Market Incumbents: Pre-empt regulatory fragmentation by consolidating compliance tooling across GDPR, CCPA, and Digital Services Act jurisdictions before algorithmic transparency mandates take effect. Build captive first-party data reservoirs through rewarded engagement loops that reduce dependence on device identifiers. Vertical integration into contextual intelligence platforms protects margin pools as identifier-based targeting erodes.
For New Entrants and Emerging Players: India's Unified Payments Interface penetration and affordable data pricing present underpenetrated app install volume among price-sensitive consumers. Target retail media network infrastructure for e-commerce apps with closed-loop purchase attribution. Pursue partnership-first go-to-market with regional mobile gaming studios seeking alternative monetization stacks beyond Google-Meta duopoly.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed contextual intelligence platforms and privacy-preserving measurement vendors. Five-to-ten year viability rests on sustained identifier deprecation across iOS and Android ecosystems. Signal to watch: adoption velocity of Google's Protected Audience API relative to Topics API as indicator of addressability preservation.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Attribution Integration | SKAdNetwork and Privacy Sandbox adoption determines iOS and Android addressability for performance advertisers. |
| Retail Media Network Expansion | First-party purchase data from e-commerce apps unlocks sponsored placement inventory for endemic and non-endemic brands. |
| Connected TV Convergence | Mobile gaming studios porting titles to smart TV platforms extend addressable inventory into living room environments. |
| Contextual Intelligence Platform Acquisition | Machine learning systems analyzing app content and session patterns replace device identifier-based audience inference. |
| Regulatory Compliance Infrastructure Buildout | Digital Services Act documentation requirements for algorithmic transparency force restructuring of EU-facing compliance teams. |
Research Approach
A spread of perspectives from mobile gaming publishers, demand-side platform product managers, brand safety verification vendors, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, App Annie usage data, hyperscaler capex disclosures, and FTC enforcement actions. Bottom-up publisher revenue estimates triangulated against top-down advertiser spend allocations.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included ad format, device type, vertical application, and engagement model. CAGRs derived from cohort-based growth rate analysis applied to baseline volume estimates. Industry-specific inputs incorporated SKAdNetwork adoption curves and Privacy Sandbox API rollout timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud infrastructure providers into ad tech middleware would shift outcomes. Regulatory enforcement intensity around dark pattern prohibitions and data localization mandates may accelerate compliance cost burdens. Quarterly review of identifier opt-in rate trajectories and programmatic guaranteed deal penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Europe OOH and DOOH Market