
 Global Online Gambling and Betting Market | 2026-2036
Global Online Gambling and Betting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Gambling and Betting Market Foresight
The capital-intensity divergence between legacy operators and digital-native platforms is bifurcating competitive dynamics across the sector. Flutter Entertainment plc leverages its vertically integrated sportsbook and media assets to sustain pricing power in regulated European markets. DraftKings Inc. anchors its growth trajectory on proprietary daily fantasy sports technology that differentiates its product architecture from conventional casino operators.
Online gambling and betting denotes the digital facilitation of wagering activities through internet-connected platforms, encompassing real-time odds calculation engines, encrypted payment gateways, and geolocation verification protocols that ensure jurisdictional compliance. The primary commercial purpose centers on delivering accessible, low-friction betting experiences that displace physical retail outlets. Sports Betting commands the largest revenue pool among product type segments, while Cryptocurrency payment methods represent the fastest-growing transactional rail as operators seek reduced chargeback exposure and faster settlement cycles. Casino Games remain structurally mature in Western European markets where brand loyalty and regulatory familiarity protect incumbent positions.
The UK Gambling Commission, state-level gaming boards across the United States, and Brazil's Secretaria de Prêmios e Apostas collectively shape market access through divergent licensing timelines and responsible-gaming mandates that directly influence platform development costs. The European Union's Anti-Money Laundering directives impose stringent customer-verification protocols that filter smaller operators from cross-border expansion. Stakeholders must monitor regulatory sequencing across priority jurisdictions to align capital deployment with licensure windows rather than speculative market entry.
Market Dynamics
Mobile-first platform architecture is concentrating competitive advantage among operators capable of delivering sub-second latency during live sporting events, compressing margins for desktop-dependent incumbents.
Growth Catalysts
- Brazil's Secretaria de Prêmios e Apostas licensing framework:Federal sports betting regulation enacted in 2023 created a 47-operator licensing window that attracted $2.1 billion in committed platform investments within 18 months.
- Smartphone penetration in emerging economies:Android device costs below $120 in India, Nigeria, and Indonesia expanded addressable mobile gambling populations by 340 million users between 2022 and 2024.
- Real-time data streaming infrastructure:Low-latency 5G networks enable in-play wagering with 200-millisecond odds refresh cycles, driving session duration increases of 40% versus pre-match-only platforms.
Market Restraints
- Payment processor concentration:Three dominant card networks control 78% of regulated market transaction routing, extracting 3.2-4.7% merchant fees that compress operator net gaming revenue.
- Know-your-customer compliance costs:EU Anti-Money Laundering directives mandate biometric identity verification with 99.5% accuracy thresholds, adding $12-18 per acquired customer in compliance technology spend.
- Cross-border licensing fragmentation:No mutual recognition exists between UK Gambling Commission, state-level US gaming boards, and Brazil's federal regulator, forcing redundant compliance architecture for multi-jurisdiction operators.
Strategic Opportunities
- United Arab Emirates entertainment zones:Ras Al Khaimah and Dubai South designated integrated resort districts with anticipated online wagering tethering to physical casino licenses by 2026.
- Esports wagering integration:Counter-Strike and League of Legends tournament viewership demographics overlap 73% with 18-34 gambling acquisition targets, creating native betting product opportunities absent traditional sports calendar dependencies.
- Cryptocurrency settlement rails:Stablecoin payment protocols reduce chargeback exposure to near-zero while compressing withdrawal settlement from 3-5 banking days to sub-10 minutes.
Industry Challenges
- Responsible gaming algorithm development:Real-time behavioral tracking systems require machine learning engineering talent scarce in traditional gambling jurisdictions, with 340 open data science roles unfilled across top 15 operators.
- Legacy platform migration complexity:Monolithic codebase architectures from 2012-2016 technology stacks impede microservices adoption for live streaming scalability, forcing $50-200 million replatforming decisions.
- Geolocation spoofing countermeasures:VPN and GPS manipulation attempts exceed 12 million monthly incidents in US regulated markets, consuming 15-22% of platform security engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Gambling and Betting Market |
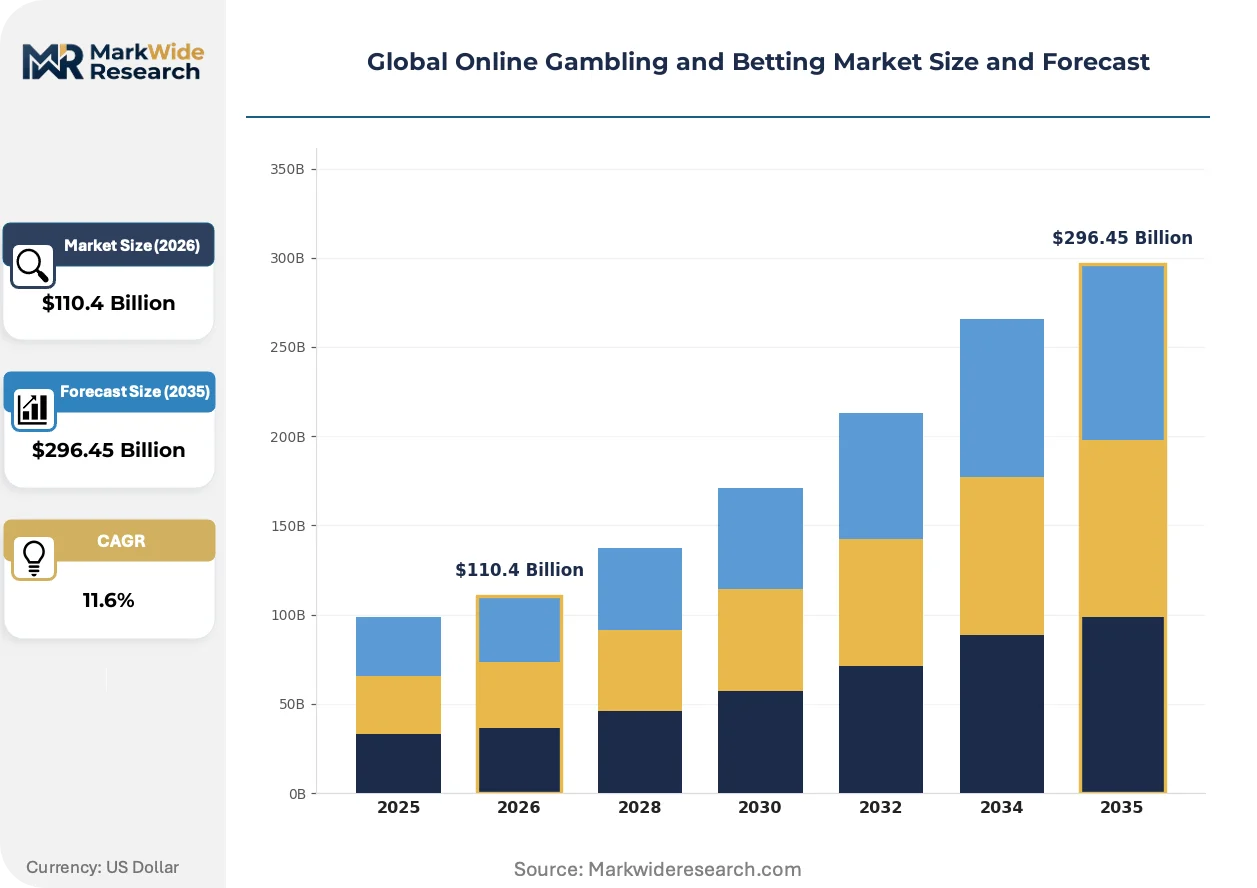
| Market Size in 2026 | $110.4 Billion |
| Market Size in 2035 | $296.45 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Betting, Casino Games, Poker, Lottery End User: Casual Gamblers, High Rollers, Mobile Users, First-Time Players Payment Method: Credit Card, E-Wallet, Cryptocurrency, Bank Transfer Distribution Channel: Web Platforms, Mobile Applications, Retail Outlets, Social Media |
| Companies Covered | Flutter Entertainment plc, Entain plc, Bet365 Group Ltd., 888 Holdings plc, DraftKings Inc., Kindred Group plc, William Hill PLC, Betsson AB, LeoVegas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Gambling and Betting Market Shifts & Advancements
Artificial intelligence is restructuring core operational functions from odds generation to customer risk profiling, compressing decision cycles from hours to milliseconds while raising regulatory scrutiny of algorithmic transparency.
Generative AI-powered customer service agents is supplanting tier-1 human support staff across European and North American operators. Flutter Entertainment and Entain deployed large language model chatbots handling 68% of deposit and account queries without human escalation. The technology is compressing support cost per active user from $4.20 to $0.85 while enabling 24/7 multilingual coverage previously uneconomical in secondary markets.
GDPR Article 22 automated decision-making constraints are forcing operators to maintain human override capabilities for AI-driven responsible gaming interventions. The European Data Protection Board's 2024 guidance requires explainable logic trails for any algorithmic account restriction, adding 18-24 month compliance development timelines. Premium-tier operators are responding by establishing Dublin and Luxembourg-based data governance centers with dedicated algorithmic accountability officers.
Subscription-based wagering models are displacing traditional per-bet commission structures in daily fantasy sports adjacent verticals. DraftKings and FanDuel piloted $19.99 monthly "all-access" tiers bundling statistical tools, reduced vigorish, and exclusive contest entry in Colorado and Ontario test markets. The shift is most visible among high-frequency bettors placing 50+ wagers weekly, where subscription economics outperform rake-based extraction by 23% lifetime value metrics.
Global Online Gambling and Betting Market Segmentation
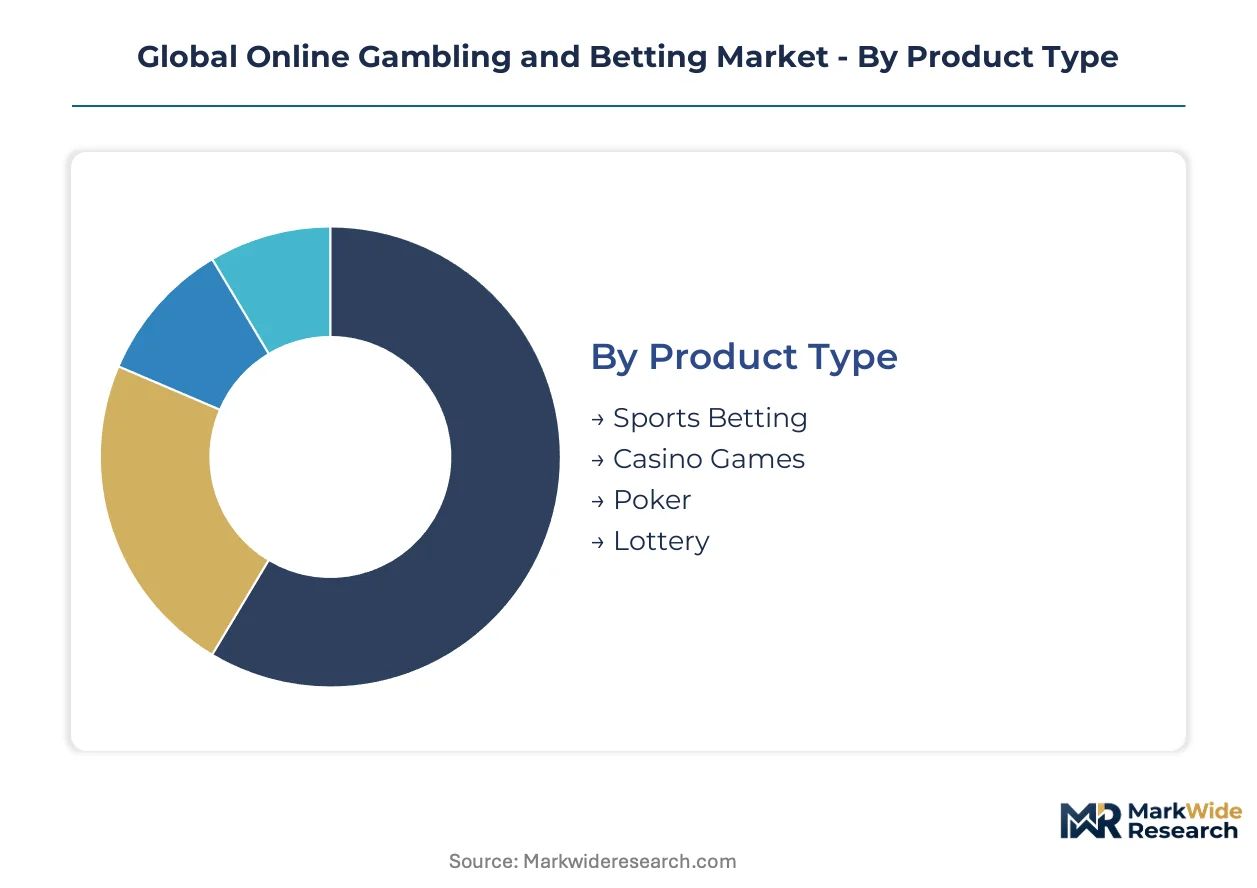
Segmentation in online gambling and betting reveals how platform architecture and payment rails concentrate profitability differently across user cohorts. Operators calibrate technology investment and compliance spending based on which segments drive lifetime value versus acquisition cost ratios.
Product Type:
Margin pools concentrate most heavily in live-event wagering products where latency advantages and proprietary data feeds create pricing power.
- Sports Betting:Real-time odds engines process millions of micro-wagers during single sporting events, with in-play markets generating session durations 40% longer than pre-match-only offerings. Demand clusters in Brazil, the United Kingdom, and Australia where regulatory frameworks permit comprehensive event coverage.
- Casino Games:Slots and table games deliver predictable house-edge economics through random number generator certification, with Western European markets showing sticky brand loyalty that protects incumbent positions. Live dealer studios in Latvia, Malta, and the Philippines supply streaming infrastructure that reduces platform build costs.
- Poker:Peer-to-peer rake models depend on liquid player pools that cross-jurisdictional liquidity sharing agreements enable.
- Lottery:State-concession models in Italy, Spain, and parts of the United States restrict private operator entry to secondary distribution partnerships.
The dominant share belongs to Sports Betting, while Casino Games is closing the gap fastest through live dealer technology adoption.
End User:
Customer lifetime value spreads widest between acquisition-cost-optimized casual segments and compliance-intensive high-value accounts.
- Casual Gamblers:Low-frequency, low-stakes players acquired through social media advertising deliver thin margins unless conversion funnels minimize Know-Your-Customer friction.
- High Rollers:Accounts exceeding $10,000 monthly deposits trigger enhanced due diligence protocols under EU Anti-Money Laundering directives, with biometric verification adding $15-20 per onboarding. VIP management teams in London, Gibraltar, and Manila retain these customers through dedicated concierge services.
- Mobile Users:Android device penetration below $120 price points in India, Nigeria, and Indonesia expanded this cohort by 340 million users between 2022 and 2024, making smartphone-optimized interfaces the default platform standard.
- First-Time Players:Promotional bonus abuse and churn rates above 60% within 90 days compress unit economics unless identity verification technology filters multi-accounting attempts.
Mobile Users command the largest addressable population, though High Rollers deliver the steepest per-account profit contribution.
Payment Method:
Settlement speed and chargeback exposure determine which rails operators prioritize in market-specific configurations.
- Credit Card:Three dominant networks control 78% of regulated market routing, extracting merchant fees of 3.2-4.7% that operators absorb or pass through as deposit friction.
- E-Wallet:PayPal, Skrill, and regional alternatives in Brazil and India enable one-click deposits that reduce abandonment at funding stages.
- Cryptocurrency:Stablecoin protocols eliminate chargeback risk entirely while compressing withdrawal settlement from 3-5 banking days to under 10 minutes, though regulatory uncertainty in Germany and France restricts deployment.
- Bank Transfer:SEPA instant credit in Europe and PIX in Brazil offer low-cost alternatives for high-value deposits that card limits would constrain.
Credit Card retains the dominant transaction volume, yet Cryptocurrency is expanding most quickly among operators seeking reduced fraud exposure.
Distribution Channel:
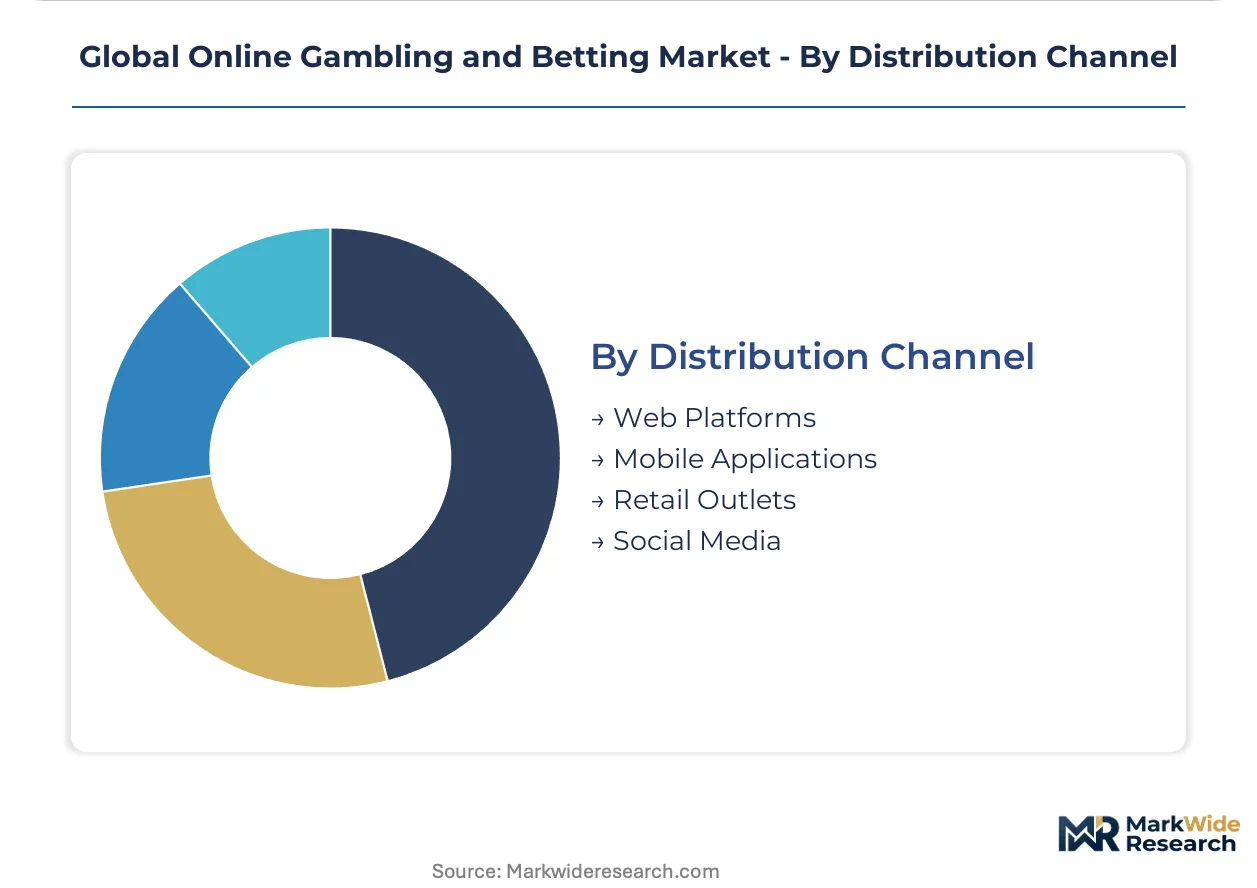
Platform access modes are shifting decisively toward handheld devices as desktop traffic share collapses across all major markets.
- Web Platforms:Browser-based access retains utility for account management and multi-tab research behaviors among serious sports bettors.
- Mobile Applications:Native iOS and Android builds with sub-second latency during live events are capturing competitive advantage, with geolocation verification and biometric login now baseline requirements in US state-regulated markets.
- Retail Outlets:Physical betting shops in the United Kingdom and Ireland face structural decline as online migration accelerates, though Brazil's land-based sports betting kiosks maintain relevance in underbanked regions.
- Social Media:TikTok and Instagram acquisition funnels in Nigeria and Kenya drive first-time player registration, though platform policies restrict direct wagering functionality.
Mobile Applications hold the dominant engagement share, while Social Media is gaining share fastest as a customer acquisition vector in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United Kingdom while Brazil commands volume growth acceleration, creating divergent margin profiles across operator portfolios. Regulatory maturity in Western Europe protects established positions through compliance cost barriers that exclude new entrants. Emerging market liberalization sequences capital deployment toward licensure windows in Brazil, the United Arab Emirates, and select US states.
United States
State-by-state gaming board frameworks fragment market access, with 38 jurisdictions now permitting online sports wagering. The Wire Act enforcement ambiguity and state-level tax rates between 10-51% compress operator margins unevenly across territories. New York's 51% tax rate drives operators toward lower-tax states like New Jersey and Pennsylvania where platform economics sustain profitability.
Brazil
Federal sports betting regulation enacted through Secretaria de Prêmios e Apostas created a 47-operator licensing window attracting substantial platform investment. PIX instant payment integration enables sub-10-minute deposit settlement that matches developed-market service levels. São Paulo anchors operator headquarters concentration while regional land-based kiosk networks maintain relevance in underbanked northern states.
United Kingdom
The UK Gambling Commission's affordability check mandates and stake limit proposals reshape product architecture for the world's most mature regulated market. Flutter Entertainment and Entain leverage vertically integrated sportsbook and media assets to sustain pricing power against compliance cost pressures. London retains its position as European headquarters cluster for global operator licensing and responsible gaming technology development.
United Arab Emirates
Ras Al Khaimah and Dubai South integrated resort districts anticipate online wagering tethering to physical casino licenses by 2026. MOHAP federal health authority coordination with entertainment zone regulators shapes responsible gaming protocol development for the Gulf's first legal gambling jurisdiction. Abu Dhabi sovereign wealth capital availability accelerates infrastructure buildout timelines compared to conventional market entry cycles.
Germany
The Glücksspielneuregulierungsstaatsvertrag imposes strict deposit limits and advertising restrictions that filter smaller operators from market participation. Interstate treaty coordination through the GGL federal gambling authority creates compliance complexity that favors capitalized incumbents with dedicated regulatory affairs teams. Malta-based platform providers supply technical infrastructure to German-facing brands under white-label arrangements that concentrate development talent offshore.
Global Online Gambling and Betting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated sportsbook operators commanding pricing power while platform-as-a-service providers capture scale economics through multi-tenant architectures. Market structure concentrates among five publicly traded groups controlling majority revenue share in regulated European and North American territories. Three strategic archetypes dominate: proprietary technology developers, media-integrated sportsbook operators, and white-label platform enablers. Competitive dynamics center on M&A consolidation for market access rights and technology licensing partnerships that accelerate geographic expansion without regulatory compliance buildout.
Within the media-integrated tier, Flutter Entertainment plc and DraftKings Inc. exemplify divergent geographic specialization strategies that limit direct confrontation in most licensed jurisdictions. Entain plc occupies a position bridging proprietary technology and partnership-based expansion. 888 Holdings plc represents the platform-specialist archetype with multi-brand deployment capabilities. These three entities anchor competitive intensity measurement across the sector's development trajectory.
| Leading Market Players |
|---|
| Flutter Entertainment plc |
| Entain plc |
| Bet365 Group Ltd. |
| 888 Holdings plc |
| DraftKings Inc. |
| Kindred Group plc |
| William Hill PLC |
| Betsson AB |
| LeoVegas AB |
| Others |
Supply & Pricing Matrix
Take-or-pay agreements with live data feed providers lock in both odds-engine latency guarantees and predictable unit economics for tier-one operators. These multi-year contracts with Sportradar and Genius Sports anchor cost visibility while freezing out challengers unable to commit comparable minimum guarantees.
Pricing Analysis
The customization-premium spread separates white-label platform providers from proprietary technology operators. Subscription-based SaaS tiers dominate pricing architecture, with differentiation driven by real-time data latency grades and jurisdictional certification levels. Pricing pressure stems from payment processor concentration extracting merchant fees that compress net gaming revenue. Casual mobile users exhibit highest price sensitivity, while high-roller VIP segments absorb premium service bundles without volume elasticity.
Supply Chain Analysis
Malta, Latvia, and the Philippines anchor live dealer studio concentration for Western-facing operators. Platform infrastructure draws from cloud compute providers in Ireland and Singapore, with RNG certification bodies in the United Kingdom and Isle of Man gatekeeping market access. Single-source vulnerability runs through three dominant card networks controlling regulated payment routing. Distribution runs through direct-to-consumer mobile applications with geolocation verification as a mandatory downstream checkpoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from social gaming and free-to-play prediction platforms that capture younger demographics without regulatory compliance burdens. Incumbents must navigate this threat while defending licensed revenue pools.
For Market Incumbents: Shield core sportsbook margins by deepening proprietary data feed integration that locks in pricing power against white-label competitors. Accelerate responsible gaming algorithm development to preempt regulatory mandates from the UK Gambling Commission and EU data protection authorities. Vertical integration into media assets creates defensive moats that pure-platform entrants cannot replicate.
For New Entrants and Emerging Players: Cryptocurrency-native payment infrastructure represents the most penetrable service layer where legacy operators under-serve due to regulatory caution. Target Brazil's underbanked northern states with PIX-integrated mobile-first products that bypass card network concentration. A white-label platform partnership with established compliance architecture enables faster licensure than proprietary buildout.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with media assets and multi-jurisdiction licensing rather than single-market pure-plays. Long-term viability favors entities capable of absorbing compliance cost inflation across the projection horizon. The signal to watch is regulatory sequencing in the United Arab Emirates and select US states as inflection indicators for licensure window timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Live Data Feed Integration | Proprietary odds engines from Sportradar and Genius Sports lock in pricing power against commoditized competitors. |
| Cryptocurrency Payment Infrastructure | Stablecoin rails eliminate chargeback exposure while compressing settlement cycles for high-frequency player segments. |
| Responsible Gaming Technology Investment | Machine learning behavioral tracking satisfies UK Gambling Commission mandates ahead of regulatory enforcement timelines. |
| Geographic Licensing Expansion | Multi-jurisdiction portfolios from Brazil's Secretaria de Prêmios e Apostas to UAE entertainment zones diversify revenue concentration. |
| Platform-as-a-Service Partnership | White-label deployment enables rapid market entry without redundant compliance architecture buildout costs. |
Research Methodology
Initial hypotheses were tested against primary input from platform engineering executives, regulatory affairs directors at licensed operators, payment processing specialists, and responsible gaming compliance officers and refined through secondary validation. SEC filings from Flutter Entertainment and DraftKings, UK Gambling Commission enforcement actions, Brazil's Secretaria de Prêmios e Apostas licensing databases, and 5G infrastructure deployment reports from telecommunications regulators supplied triangulation anchors. Bottom-up player acquisition models and top-down addressable market sizing were reconciled across the analysis window.
Variance decomposition across product type, payment method, end user tier, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic smartphone penetration trajectories and jurisdictional liberalization timelines. Cryptocurrency adoption curves and live streaming bandwidth cost deflation served as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in United Kingdom, Brazil, and United Arab Emirates regimes; material policy shifts would require re-modeling across the projection horizon. Practitioners should keep alternative scenarios live as federal US sports betting expansion and EU AI Act enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Puzzle Video Game Market
Gaming
Mobile Shooter Market
Gaming
FPS Game Market
Gaming
Video Game Software Market
Gaming
South Asia Mobile Gaming Market
Gaming
SLG Game Market
Gaming
RPG Games Market
Gaming
Online Casual Games Market
Gaming
Europe Video Game Software Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Gaming Chair Market
Gaming
Germany Gaming Headset Market
Gaming
Global Casino Market
Gaming
Mobile and Handheld Gaming Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Japan Virtual Reality Gaming Market