
 South Korea Virtual Reality Gaming Market | 2026-2036
South Korea Virtual Reality Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Virtual Reality Gaming Market Intelligence
Market Context with Strategic Players
South Korea is reshaping its domestic VR gaming ecosystem through heavy investment in Seoul-based content studios and Busan hardware incubators. Samsung Electronics leverages its display panel dominance to supply high-resolution AMOLED screens for headset manufacturers across the peninsula. Meta Platforms anchors its Asia-Pacific VR software development in Korean studios specializing in social multiplayer architectures. Sony Group competes through exclusive content licensing for its PlayStation VR2 platform within the Korean console segment.
Technical Definition and Structural Segments
South Korea Virtual Reality Gaming denotes immersive interactive entertainment systems employing head-mounted displays with sub-20ms motion-to-photon latency, six-degrees-of-freedom tracking, and stereoscopic rendering at 90Hz minimum refresh rates, primarily serving commercial entertainment venues and consumer households. Standalone platforms lead unit shipments by eliminating PC tethering complexity for Korean apartment-dwelling consumers. Mobile VR sustains the largest addressable base through smartphone-integrated viewers, though PC platforms capture the highest per-user revenue through premium hardware bundles.
Regulatory Frame and Forward-Looking Close
MFDS enforces ocular safety standards for head-mounted displays, while the Korea Communications Commission regulates age-appropriate content ratings and online service obligations for multiplayer VR titles. The Personal Information Protection Commission imposes strict biometric data handling rules for eye-tracking and facial capture features common in next-generation headsets. Stakeholders must monitor evolving KCC guidelines on virtual currency transactions within metaverse gaming environments.
Market Dynamics
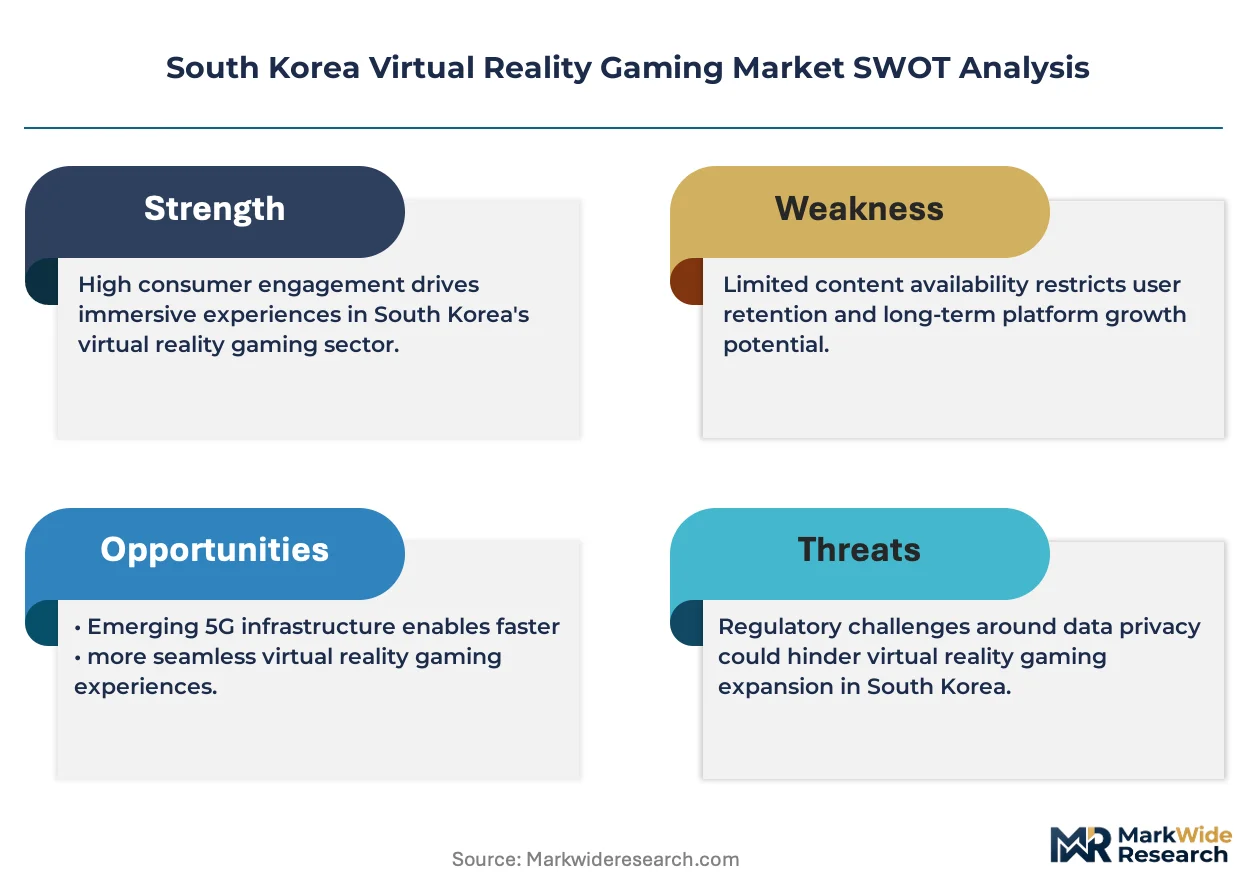
Seoul-based arcade operators and Busan hardware incubators are compressing VR deployment timelines, forcing content studios to accelerate multiplayer social architectures ahead of standalone headset refresh cycles.
Growth Catalysts
- MFDS Visual Safety Standards:Mandatory ocular safety certification for head-mounted displays creates consumer trust barriers that certified manufacturers exploit to differentiate premium hardware tiers.
- Multiplayer Social Architectures:Young adult demographics in Seoul and Busan demand synchronous co-located VR experiences, pulling location-based entertainment venues toward high-throughput installation models.
- Six-Degrees-of-Freedom Tracking:Sub-20ms motion-to-photon latency requirements are pushing domestic semiconductor foundries to specialize in low-latency sensor fusion chipsets.
Market Restraints
- AMOLED Panel Supply Concentration:Samsung Electronics dominates high-resolution display supply, creating single-source vulnerability for domestic headset assemblers during fab allocation cycles.
- Biometric Data Handling Friction:The Personal Information Protection Commission's strict eye-tracking and facial capture rules impose compliance costs that slow feature rollout in next-generation hardware.
- Smartphone-Integrated Viewer Substitution:Mobile VR sustains the largest addressable base through low-cost smartphone viewers, compressing pricing power for standalone premium platforms.
Strategic Opportunities
- Gwangju Digital Content Cluster:Underdeveloped studio capacity in southwestern provinces offers greenfield production facilities with lower real estate costs than Seoul.
- Metaverse Virtual Currency Framework:Evolving KCC guidelines on in-game transactions create regulatory clarity that enables compliant tokenized economies in persistent VR worlds.
- Haptic Feedback Convergence:Integration of force-feedback wearables with existing headset ecosystems opens immersive training applications for industrial end-users.
Industry Challenges
- Real-Time Engine Talent Scarcity:Domestic universities produce insufficient Unreal Engine specialists to staff Seoul content studios at required velocity.
- Hardware Certification Timelines:MFDS ocular safety testing protocols extend product launch windows by eight to fourteen months versus software-only releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Virtual Reality Gaming Market |
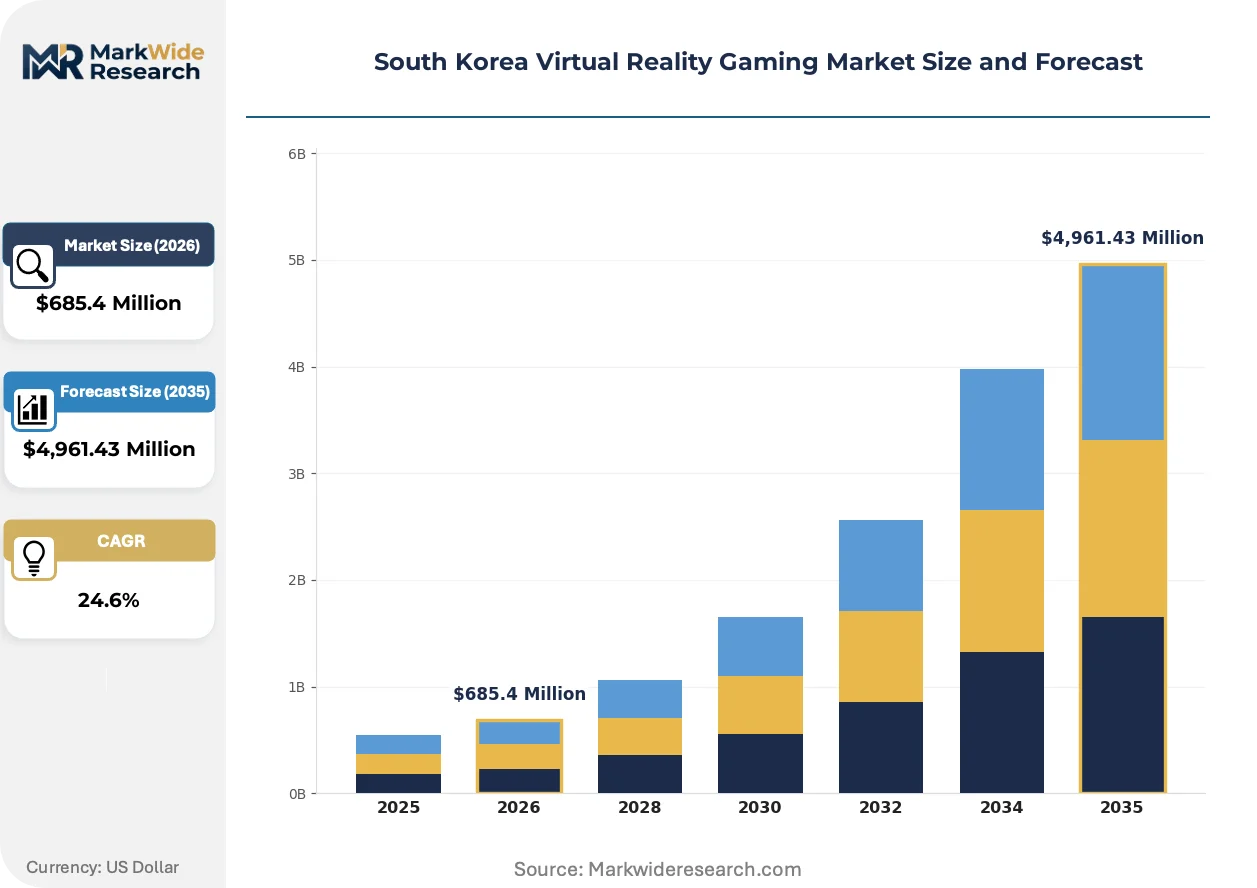
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,961.43 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: PC, Console, Mobile, Standalone Content Genre: Action, Adventure, Puzzle, Simulation User Demographic: Teens, Young Adults, Adults, Seniors Distribution Channel: Digital Download, Retail Stores, Subscriptions, Bundles |
| Companies Covered | Valve, Samsung Electronics, Sony Group, Apple, Microsoft, Meta Platforms, NVIDIA, Qualcomm, HTC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Virtual Reality Gaming Market Strategic Shifts & Innovations
Standalone platforms are eliminating PC tethering complexity while biometric sensors and persistent social worlds reshape how Korean consumers engage with immersive entertainment.
Foveated rendering using dynamic gaze tracking is collapsing the computational load required for high-fidelity VR experiences. Seoul-based arcade operators are adopting this technology to reduce GPU costs in high-throughput commercial installations. The compression of rendering overhead is enabling mid-tier hardware to deliver premium visual fidelity previously restricted to PC-tethered systems.
KCC's evolving content rating framework for multiplayer VR titles is tightening age-verification requirements for social metaverse platforms. Domestic publishers must now implement real-time identity verification for voice-enabled proximity chat features. The regulation most affects horror and combat genres popular with young adult demographics, forcing studios to bifurcate content libraries.
Location-based entertainment venues in Busan and Seoul are unbundling hardware ownership from content access through subscription-based usage models. Consumers now purchase time-credits rather than discrete game tickets, shifting revenue recognition toward recurring streams. This behavioral pivot concentrates in commercial districts with high foot traffic density and limited residential space for home VR setups.
South Korea Virtual Reality Gaming Market Segmentation
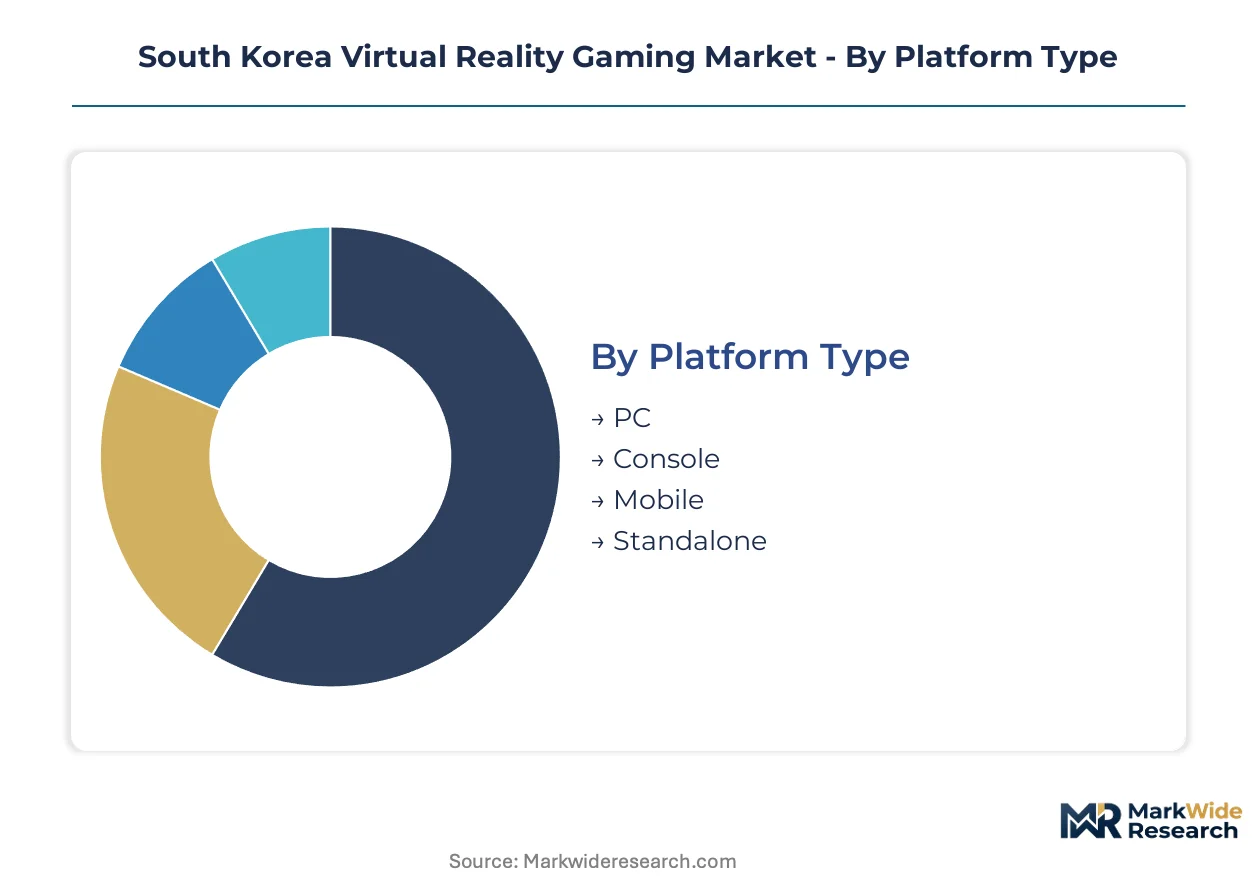
Platform configurations determine hardware refresh cycles and service revenue models across Seoul's arcade networks and Busan's hardware incubators. Content genres shape certification pathways under KCC rating frameworks, while demographic targeting influences multiplayer architecture investments.
Platform Type:
After-sales-service intensity varies sharply across platform categories, with PC-tethered systems demanding ongoing technical support that standalone devices rarely require.
- PC:Tethered configurations leverage high-end GPUs for photorealistic rendering at 90Hz minimum refresh rates. Demand concentrates in Seoul's PC bang culture venues where competitive multiplayer titles drive hourly revenue models and hardware upgrade cycles.
- Console:Sony's PlayStation VR2 dominates this segment through exclusive content licensing and standardized controller ecosystems. Busan family entertainment centers favor console deployments for their simplified setup protocols and reduced technical staffing requirements.
- Mobile:Smartphone-integrated viewers utilize existing device displays with clip-on optics for entry-level immersion.
- Standalone:Self-contained headsets with onboard processing eliminate PC dependency for apartment-dwelling consumers.
Standalone holds the largest share; momentum sits with PC platforms in commercial venues.
Content Genre:
Cost tier differentiation separates premium narrative experiences from high-volume arcade titles, with production budgets spanning an order of magnitude across genre categories.
- Action:Combat-focused mechanics with sub-20ms latency requirements stress-test motion tracking precision. Young adult demographics in Seoul's Hongdae district drive demand for competitive multiplayer shooters that monetize through cosmetic microtransactions.
- Adventure:Narrative-driven exploration titles prioritize environmental storytelling over reflex-based mechanics. Gwangju studios specialize in historical Korean settings that qualify for domestic content subsidies and cultural export programs.
- Puzzle:Spatial reasoning challenges suit shorter session lengths common in location-based entertainment venues.
- Simulation:Training and educational applications extend beyond entertainment into industrial end-use cases.
Action captures the highest revenue per user; puzzle titles are expanding most quickly in arcade deployments.
User Demographic:
Volume concentration among young adult cohorts shapes hardware design priorities for social presence features and voice communication integration.
- Teens:KCC age-verification requirements impose technical burdens on publishers targeting this segment with proximity chat features. School district regulations in Seoul limit weekday access to commercial VR venues, compressing demand into weekend windows.
- Young Adults:Synchronous co-located experiences dominate this demographic, with multiplayer social architectures driving location-based entertainment investment in Busan and Seoul commercial districts.
- Adults:Fitness and wellness applications attract users seeking structured exercise alternatives.
- Seniors:Low-mobility experiences with seated gameplay options address accessibility requirements.
Young Adults command the installed base; Adults show the steepest expansion trajectory in home fitness applications.
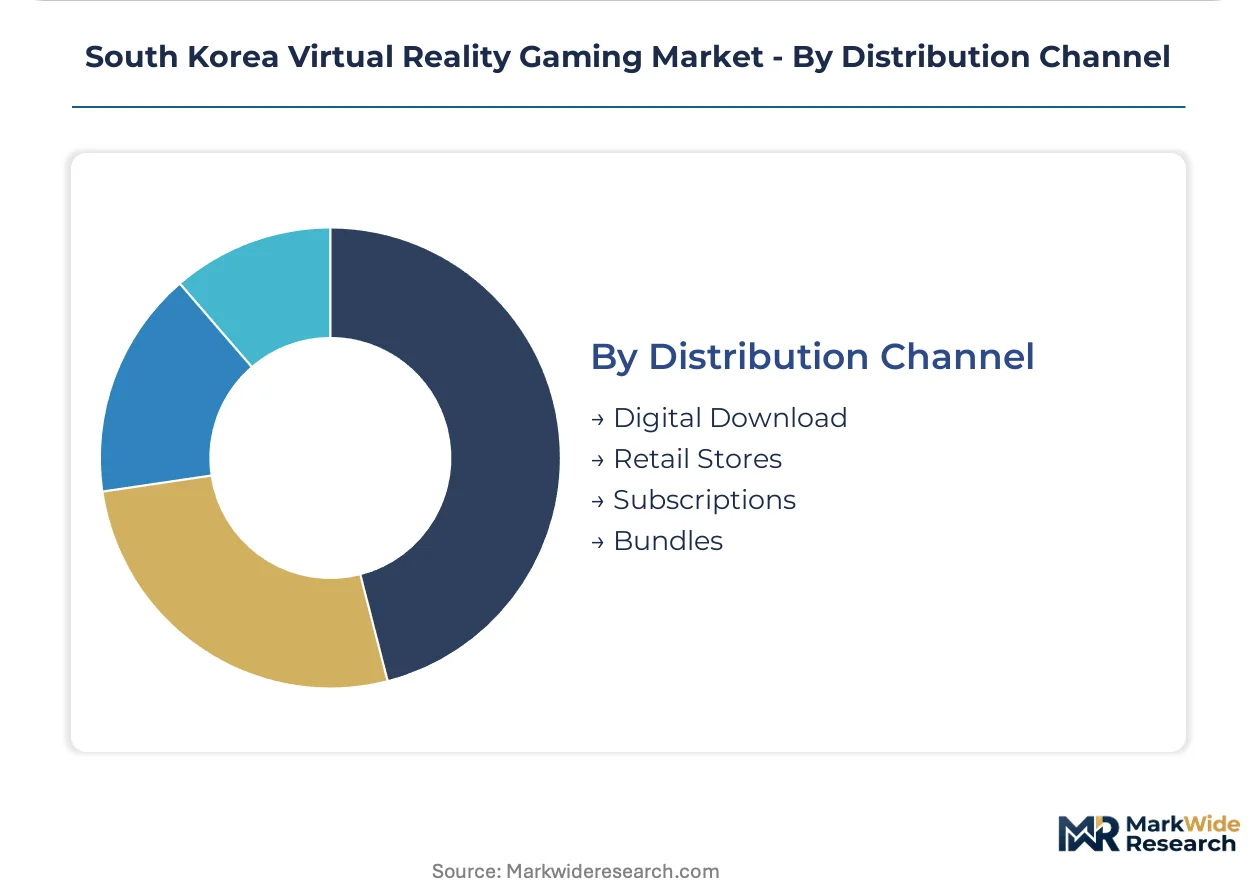
Distribution Channel:
Margin structures favor recurring revenue models over one-time transactions, reshaping how Korean publishers monetize content access.
- Digital Download:Direct-to-consumer storefronts bypass retail markups and enable dynamic pricing based on MFDS certification status. Seoul-based studios leverage digital distribution for rapid patch deployment and live service content updates.
- Retail Stores:Physical hardware bundles with packaged software maintain presence in electronics districts like Yongsan, though shelf space contracts as standalone headsets shift toward direct online sales.
- Subscriptions:Time-credit models at location-based venues generate predictable revenue streams.
- Bundles:Hardware-software combinations reduce consumer decision friction for first-time purchasers.
Digital Download leads transaction volume; Subscriptions are gaining share fastest in commercial entertainment venues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS anchors South Korea's regulatory framework for visual safety standards, while the Korea Communications Commission governs content ratings and online service obligations for multiplayer VR titles. Regional demand concentrates in metropolitan clusters with high youth density and established gaming infrastructure.
Seoul Capital Area
Young adult demographics drive synchronous co-located VR experiences across Hongdae and Gangnam commercial districts. The Korea Communications Commission enforces real-time identity verification for proximity chat features in social metaverse platforms. Seoul-based arcade operators compress deployment timelines through subscription-based time-credit models that shift revenue toward recurring streams.
Busan-Ulsan
Hardware incubators in Busan's tech corridors accelerate standalone headset refresh cycles through semiconductor foundry partnerships. MFDS ocular safety certification requirements extend product launch windows, forcing manufacturers to front-load compliance testing. Location-based entertainment venues favor console deployments for simplified setup protocols and reduced technical staffing requirements.
Daegu-Gyeongbuk
Industrial end-users in this southeastern manufacturing belt pursue haptic feedback convergence for immersive training applications. The Personal Information Protection Commission's biometric data handling rules impose compliance costs on eye-tracking feature rollouts. Daegu studios specialize in mid-tier hardware delivering premium visual fidelity through foveated rendering adoption.
Daejeon-Sejong
Government research institutes in this administrative capital cluster drive low-latency sensor fusion chipset development for six-degrees-of-freedom tracking. KCC guidelines on virtual currency transactions within metaverse gaming environments create regulatory clarity for compliant tokenized economies. Sejong-based policy incubation shapes national standards that propagate to commercial implementations nationwide.
Gwangju-Honam
Underdeveloped studio capacity in this southwestern region offers greenfield production facilities with lower real estate costs than Seoul. Domestic content subsidies and cultural export programs support historical Korean narrative settings in adventure genre development. Gwangju's emerging digital content cluster attracts publishers seeking alternative talent pools outside the capital's competitive labor market.
South Korea Virtual Reality Gaming Market Key Industry Players
Capability concentration sits with semiconductor and display specialists; scale advantage sits with platform-integrated ecosystem operators. The market structures around three tiers: component suppliers controlling critical AMOLED and sensor fusion supply, hardware assemblers bundling certified headsets with content libraries, and platform operators monetizing through software distribution and social service layers. Dominant competitive moves include exclusive content licensing for hardware lock-in and backward integration into display panel supply.
Among platform-integrated operators, Meta Platforms anchors Asia-Pacific VR software development through Seoul-based studios, while Sony Group exemplifies console-centric positioning through PlayStation VR2 exclusive content strategies. Samsung Electronics occupies a foundational position as the dominant AMOLED supplier for domestic headset manufacturers, representing the component-tier archetype that constrains pricing power across downstream assemblers.
| Leading Market Players |
|---|
| Valve |
| Samsung Electronics |
| Sony Group |
| Apple |
| Microsoft |
| Meta Platforms |
| NVIDIA |
| Qualcomm |
| HTC |
| Others |
Cost & Logistics Intelligence
Overcapacity in Gwangju display panel fabrication is compressing component pricing while forcing Seoul headset assemblers to absorb inventory risk through take-or-pay contracts with Samsung Electronics. This utilization imbalance simultaneously erodes AMOLED supplier margins and creates procurement leverage for downstream hardware bundlers.
Pricing Analysis
Seoul-to-Busan price spreads of 15-20% reflect differential MFDS certification timelines and local technical staffing costs. Three-tier pricing structure across premium, standard, and economy levels separates PlayStation VR2 bundles from mid-tier standalone headsets and entry-level smartphone viewers. Pricing pressure stems from mobile VR substitution compressing standalone device margins. Arcade operators show lowest price sensitivity due to hourly revenue models; apartment-dwelling consumers exhibit highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Foxconn and Pegatron concentrate contract manufacturing capacity for Korean headset OEMs across Shenzhen and Taipei facilities. Component sourcing draws from Taiwan for sensor fusion chipsets, South Korea for AMOLED panels, and Japan for precision optics. Single-source vulnerability concentrates in Samsung Electronics display supply during fab allocation cycles. Distribution runs through electronics retail districts like Yongsan for hardware, with digital storefronts handling software transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with underdeveloped studio capacity outside Seoul, as location-based entertainment demand pulls content investment toward Busan and Gwangju. Young adult demographics seeking synchronous co-located experiences are creating niche openings for regional multiplayer specialists.
For Market Incumbents: Pre-empt console-to-standalone substitution by accelerating backward integration into haptic wearable supply. Lock exclusive content licensing for PlayStation VR2 before MFDS certification timelines enable competitor hardware launches. Defend Seoul arcade network density through subscription time-credit models that raise switching costs for venue operators. For New Entrants and Emerging Players: Establish a beachhead in Gwangju adventure genre development where domestic content subsidies offset talent acquisition costs. Target Busan hardware incubators for semiconductor foundry partnerships that bypass Samsung Electronics panel allocation queues. Lead with historical Korean narrative settings to qualify for cultural export program support. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among location-based entertainment venue operators with subscription time-credit models. Long-term viability hinges on regulatory clarity for metaverse virtual currency frameworks under evolving KCC guidelines. Monitor MFDS certification backlog duration as inflection signal for hardware launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Licensing | PlayStation VR2 bundling locks console gamers into Sony's controller ecosystem. |
| Backward Integration | Captive AMOLED supply reduces Samsung Electronics allocation vulnerability for headset assemblers. |
| Geographic Expansion | Gwangju studio capacity lowers production costs versus Seoul's competitive labor market. |
| Platform Integration | Meta's Seoul-based studios anchor Asia-Pacific social multiplayer architecture development. |
| Regulatory Certification Investment | MFDS ocular safety pre-certification compresses product launch windows versus reactive testing. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with VR content studio heads, arcade network operators, semiconductor procurement managers, and MFDS certification specialists; and secondary validation through Korea Communications Commission filings, MFDS device registration databases, Seoul Metropolitan Government entertainment venue licensing records, and hyperscaler VR software development disclosures. Bottom-up unit economics from location-based entertainment venues triangulated against top-down hardware shipment aggregation.
Forecast inputs considered platform type refresh cycles, content genre production budgets, and demographic penetration curves across the projection horizon. Segmentation dimensions modeled include hardware configuration, content category, user age cohort, and distribution channel structure. CAGRs derived from logistic adoption curve fitting adjusted for regulatory certification lag effects and foundry capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in youth discretionary spending and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions about MFDS testing protocol stability and KCC content rating enforcement intensity. Quarterly review of arcade network subscription conversion rates and standalone headset inventory turns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Virtual Sports Market
Gaming
Global Esports Market
Gaming
Global NFT Gaming Market
Gaming
Gaming Gadgets Market
Gaming
Gaming Simulation Market
Gaming
VR Melee Games Market
Gaming
Europe Casino Gambling Market
Gaming
Global Tarot Cards Market
Gaming
VR Gaming Console Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Europe Gaming Peripherals Market
Gaming
FPS Game Market
Gaming
Mobile Game Controller Market
Gaming
China Casino Tourism Market
Gaming
GCC Gaming Headsets Market
Gaming
Mobile MOBA Games Market