
 H5 Games Market | 2026-2036
H5 Games Market Size, Share, and Industry Trends Forecast 2026-2036
H5 Games Market Insights
GDPR enforcement in Europe is recalibrating the cost-of-entry calculus for H5 game studios targeting cross-border audiences. Tencent leverages its WeChat mini-program ecosystem to dominate distribution within China's walled garden. NetEase anchors its competitive position through proprietary engine investments that reduce third-party platform dependency. Poki navigates browser-based fragmentation by sustaining direct publisher relationships across multiple European territories.
H5 games are browser-native interactive entertainment applications built on HTML5, CSS3, and JavaScript that execute without native app installation, typically requiring under 50MB of initial payload for instant playability across mobile and desktop browsers. Their primary commercial purpose is frictionless user acquisition through shareable links and social media embeds that bypass app store gatekeeping. The freemium monetization model leads revenue generation by converting casual engagement into microtransaction streams, while ad-supported formats capture value from price-sensitive segments in emerging markets. Puzzle and strategy game types concentrate the deepest margin pools due to extended session durations that maximize both in-app purchase opportunities and rewarded video ad inventory.
SAMR in China enforces real-name registration and playtime limits for minors, directly constraining game design and monetization architecture for titles distributed domestically. The EU AI Act and GDPR jointly reshape how H5 publishers deploy recommendation algorithms and process behavioral data across European user bases. Stakeholders must decide whether to architect separate compliance stacks for China's content regime versus Europe's privacy framework, or absorb the engineering overhead of a unified global build.
Market Dynamics
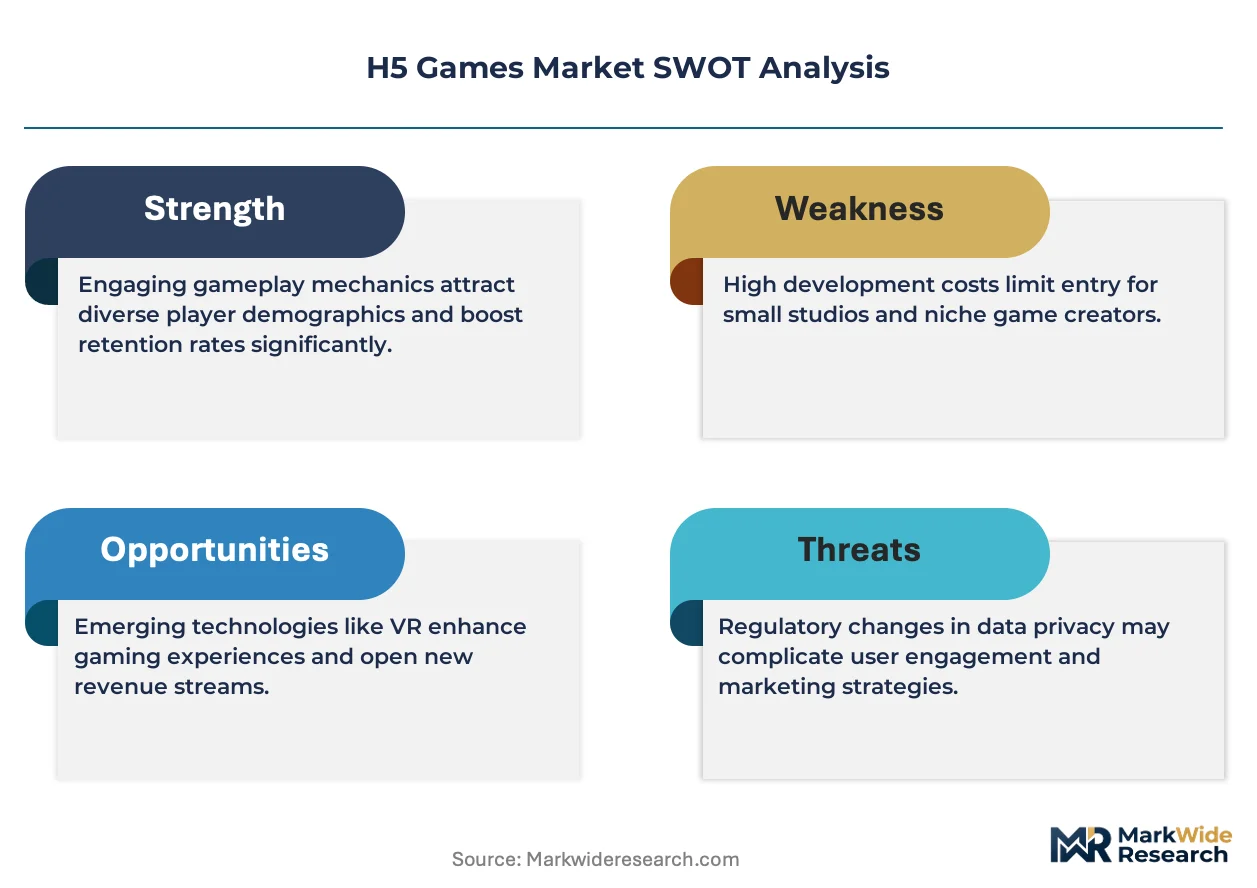
Browser-native instant playability is compressing user acquisition costs for H5 publishers while fragmenting distribution control across platform gatekeepers and social media embeds.
Growth Catalysts
- WeChat mini-program infrastructure:China's super-app ecosystem eliminates app store friction, enabling one-tap game launches that drive viral sharing mechanics and reduce customer acquisition spend.
- GDPR-compliant behavioral analytics:European publishers deploying privacy-preserving measurement tools unlock cross-border campaign optimization without triggering regulatory penalties.
- Rewarded video ad technology:Lightweight SDK integration lets Southeast Asian studios monetize price-sensitive audiences through opt-in advertising that preserves session flow.
Market Restraints
- SAMR minor protection mandates:China's real-name registration and playtime limits force architecture changes that reduce monetization depth for domestic titles.
- Engine licensing concentration:Dependency on third-party HTML5 rendering stacks creates vulnerability when platform owners deprecate feature support without notice.
- Bandwidth cost volatility:Emerging market publishers face margin pressure from CDN pricing fluctuations that scale directly with payload delivery volume.
Strategic Opportunities
- Indonesia's unbanked gamer population:Carrier billing and e-wallet penetration gaps create first-mover advantage for publishers building localized payment rails.
- EU AI Act algorithmic transparency:Publishers proactively disclosing recommendation logic gain competitive differentiation in European distribution negotiations.
- Progressive Web App convergence:Hybrid PWA-H5 architectures enable offline functionality that expands addressable moments beyond live connectivity windows.
Industry Challenges
- Cross-platform QA complexity:Fragmented browser engine implementations across iOS Safari, Android Chrome, and desktop variants multiply testing overhead for feature parity.
- Live operations talent scarcity:Shortage of data scientists fluent in both casual game balancing and ad mediation optimization constrains post-launch revenue optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H5 Games Market |
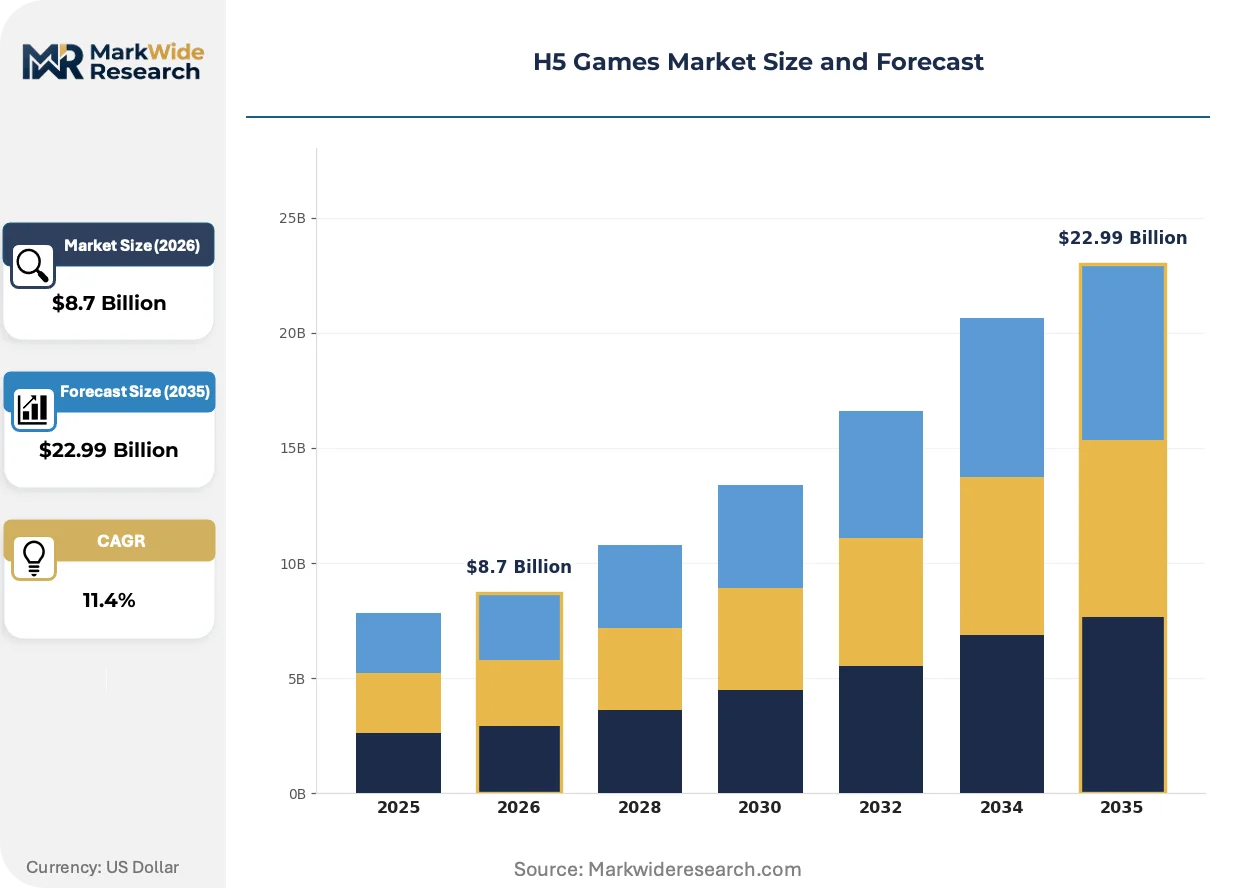
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Puzzle, Strategy, Adventure Monetization Model: Freemium, Subscription, In-App Purchases, Ad-Supported Platform: Mobile, Desktop, Browser, Social Media Target Audience: Teens, Adults, Casual Gamers, Hardcore Gamers |
| Companies Covered | China Mobile Games and Entertainment Group, Dalian Pantour, Tencent, Poki, Forgame, NetEase, Hoodinn Interactive Limited, Kongregate, Wuhu Sanqi Interactive Entertainment Network Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H5 Games Market Trends and Innovations
Instant cloud-streaming integration and privacy-preserving attribution are redefining how H5 titles acquire, retain, and monetize players without native app dependencies.
WebGPU rendering pipelines are absorbing graphics workloads previously reserved for native engines, enabling mid-core visual fidelity within browser constraints. Southeast Asian strategy publishers are piloting these stacks for 60fps tactical gameplay on entry-tier Android devices. The technology is absorbing development talent from native mobile studios and compressing the performance gap that previously justified app store distribution.
Europe's GDPR enforcement actions against behavioral profiling are forcing publishers to rebuild attribution around aggregated cohort analysis and differential privacy. The regulatory shift elevates compliance costs for cross-border campaigns while advantaging publishers with first-party data moats. French and German studios are responding by deepening direct publisher-to-player relationship infrastructure.
Vietnamese and Indonesian gamers are gravitating toward embedded social competition layers that transform solitary puzzle sessions into asynchronous tournament formats. Messaging app distribution channels are displacing standalone browser discovery as the primary acquisition path. This behavioral pivot is most visible in Ho Chi Minh City and Jakarta, where share-to-continue mechanics now drive majority of organic installs.
H5 Games Market Segmentation
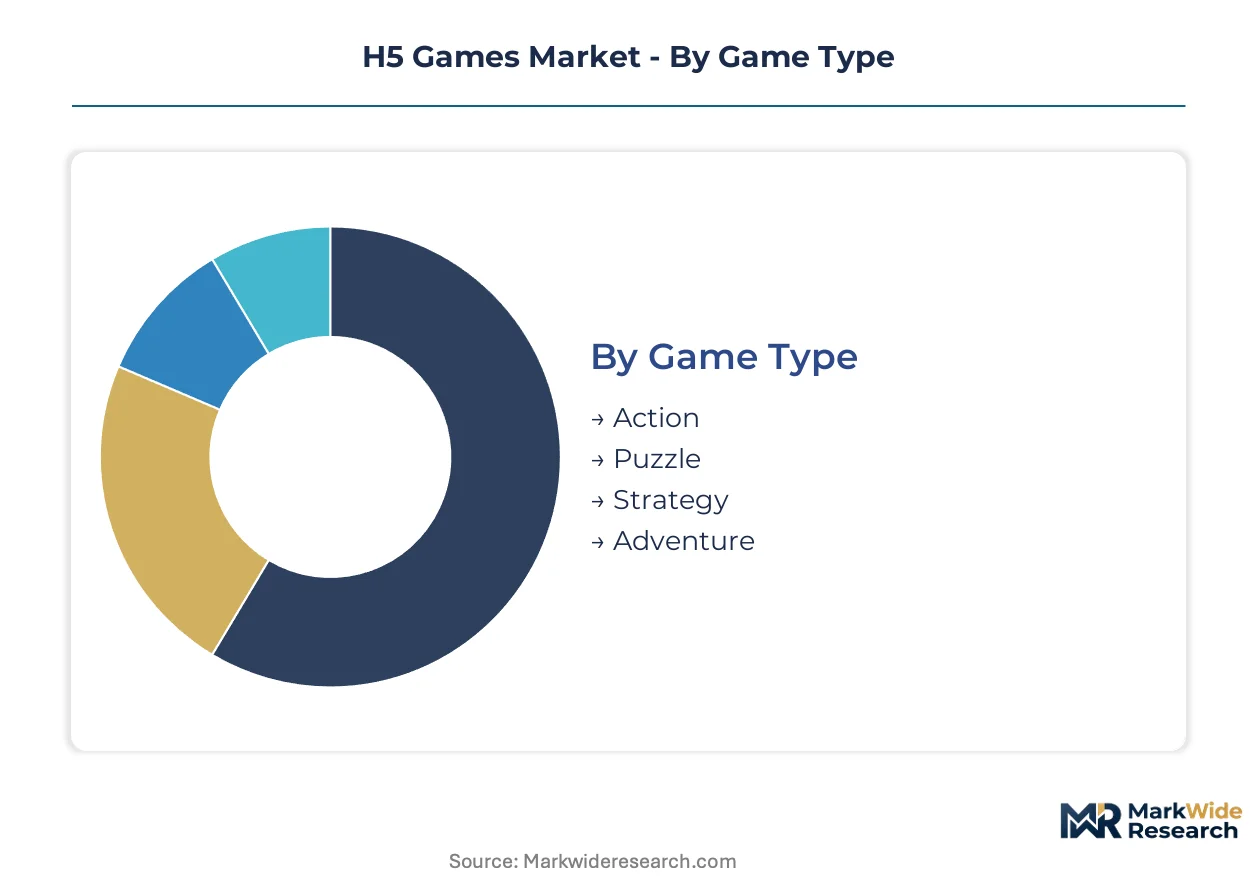
H5 game publishers architect revenue streams around distinct player behavioral profiles and technical delivery contexts. Segment boundaries determine monetization depth, session design, and distribution channel selection across browser-native deployments.
Game Type:
Standalone browser experiences command direct player relationships, while embedded social formats sacrifice margin for viral acquisition velocity.
- Puzzle:Grid-based and match mechanics dominate Southeast Asian commuter sessions, with Ho Chi Minh City and Jakarta clusters driving organic share-to-continue installs. Extended session durations maximize rewarded video inventory and microtransaction conversion.
- Strategy:Turn-based and tactical systems absorb WebGPU rendering investments from Vietnamese studios targeting 60fps gameplay on entry-tier Android devices. These titles anchor the deepest margin pools through persistent world mechanics.
- Action:Reflex-dependent gameplay requires sub-50ms input latency that fragments across Safari and Chrome engine implementations.
- Adventure:Narrative progression systems face bandwidth cost volatility in emerging markets where CDN pricing scales with payload volume.
Volume placements concentrate in Puzzle; the faster expansion belongs to Strategy.
Monetization Model:
Cost tier alignment separates high-ARPU whale-dependent architectures from mass-market ad mediation stacks.
- Freemium:Gated progression mechanics convert casual engagement into cosmetic and power-up microtransactions. European publishers deploy GDPR-compliant cohort analysis to optimize conversion funnels without behavioral profiling penalties.
- Ad-Supported:Rewarded video SDKs enable Indonesian and Vietnamese studios to monetize price-sensitive audiences through opt-in viewing that preserves session flow. Carrier billing gaps in unbanked populations reinforce this model's dominance.
- In-App Purchases:Direct item sales face SAMR minor protection mandates that constrain architecture depth for China-distributed titles.
- Subscription:Recurring revenue models demand persistent authentication infrastructure that multiplies compliance overhead across MIIT and GDPR jurisdictions.
Ad-Supported claims the widest player base; Freemium captures the steepest revenue per user trajectory.
Platform:
Application footprint determines whether titles execute as browser-native instant play or hybrid PWA architectures with offline functionality.
- Mobile:Touch-optimized interfaces dominate Indonesian and Vietnamese casual gamer populations, with browser-based instant playability compressing acquisition costs below app store gatekeeping thresholds.
- Social Media:WeChat mini-program infrastructure eliminates download friction for China domestic distribution, enabling one-tap launches that drive viral mechanics. This channel sacrifices data ownership for reach velocity.
- Desktop:Keyboard-mouse precision attracts hardcore strategy segments in European territories where GDPR elevates first-party data moat value.
- Browser:Direct URL distribution preserves publisher control over player relationships but fragments across Safari, Chrome, and Edge engine implementations.
Social Media embeds claim the fastest install velocity; Mobile browser delivers the broadest geographic penetration.
Target Audience:
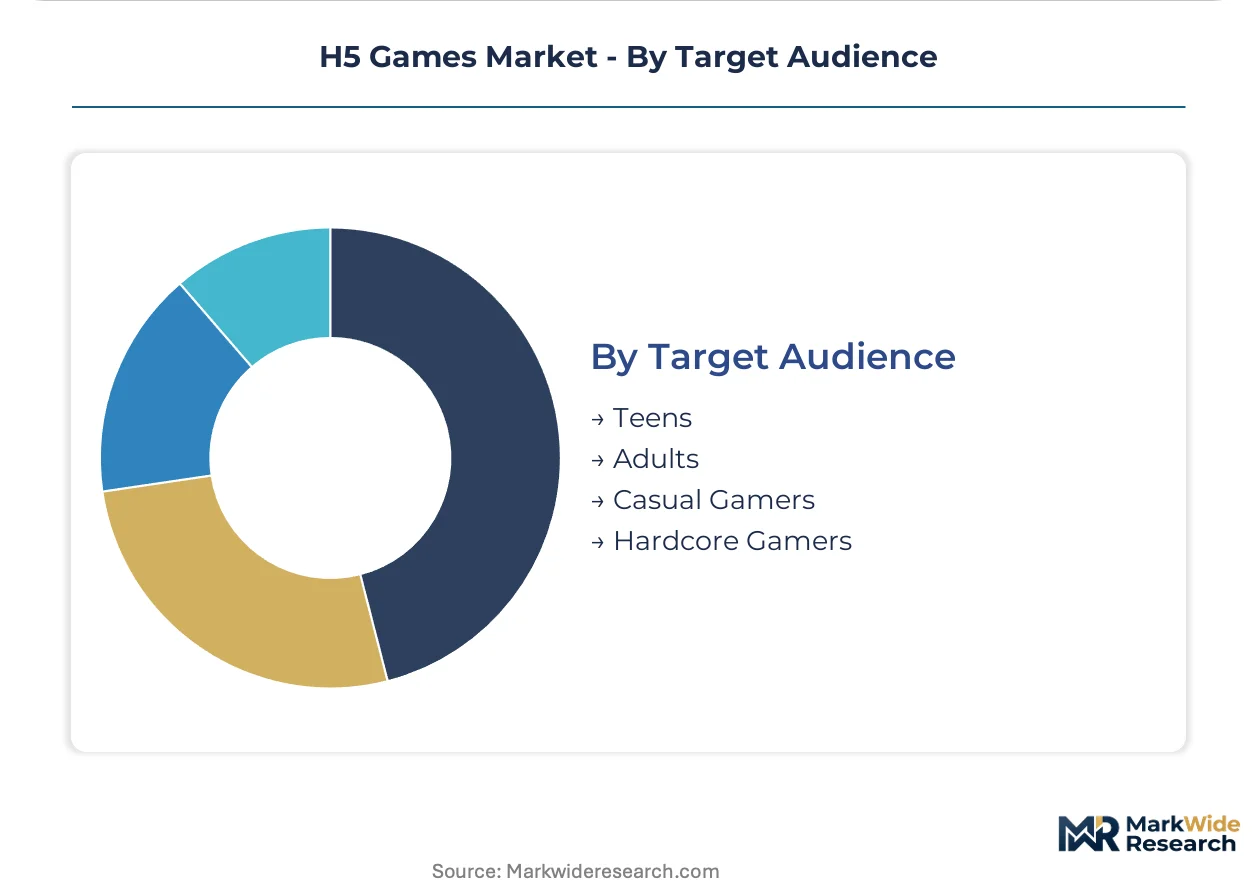
Customer type stratification aligns content maturity ratings with regulatory playtime enforcement and payment rail availability.
- Casual Gamers:Short-session puzzle engagement concentrates in Southeast Asian metropolitan clusters where messaging app discovery displaces standalone browser search. These players monetize through ad mediation and low-friction microtransactions.
- Adults:Employed demographics with established e-wallet access drive subscription and high-value IAP acceptance in European markets where GDPR-compliant attribution elevates acquisition costs.
- Teens:China's SAMR real-name registration and playtime limits force architecture changes that reduce monetization depth for domestic titles targeting this segment.
- Hardcore Gamers:Competitive ranking systems demand low-latency infrastructure that concentrates QA complexity across fragmented browser engine implementations.
Casual Gamers anchor the largest addressable base; Adults deliver the highest revenue per session.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the deepest demand pool for H5 games, with WeChat mini-program infrastructure driving viral distribution mechanics that compress customer acquisition costs below Western benchmarks.
China
Domestic publishers deploy titles through super-app ecosystems that eliminate app store friction entirely. SAMR enforces real-name registration and playtime limits for minors, constraining monetization architecture for youth-targeted content. Shenzhen and Beijing host the densest studio clusters, where Tencent and NetEase anchor proprietary engine investments that reduce third-party platform dependency.
Indonesia
Carrier billing gaps among unbanked populations reinforce ad-supported monetization dominance across Jakarta metropolitan gamer clusters. The country's national communications regulator maintains content classification requirements for browser-distributed titles. Bandung and Surabaya concentrate emerging studio formation, where localized payment rail development creates first-mover positioning for foreign publishers.
Vietnam
Ho Chi Minh City drives organic install velocity through messaging-app-embedded social competition layers that transform solitary puzzle sessions. The Ministry of Information and Communications applies licensing requirements to cross-border game distribution that affect foreign publisher market entry. Hanoi studios pilot WebGPU rendering investments targeting 60fps tactical gameplay on entry-tier Android devices.
Germany
GDPR enforcement elevates first-party data moat value for publishers deploying privacy-preserving attribution across European user bases. The Federal Network Authority oversees telecommunications frameworks affecting browser-based game delivery infrastructure. Berlin and Munich anchor compliance-focused studio operations, where differential privacy tooling development absorbs engineering talent from behavioral analytics vendors.
United States
Desktop browser segments attract hardcore strategy audiences where keyboard-mouse precision supports extended session monetization. The Federal Trade Commission monitors consumer protection in freemium game mechanics, particularly concerning minor-targeted microtransactions. San Francisco and Los Angeles maintain publisher presence focused on hybrid PWA-H5 architectures that expand offline functionality.
H5 Games Market Competitive Landscape
Chinese publishers anchor one tier through super-app ecosystem control; European and North American specialists hold differentiated positions in privacy-compliant attribution and browser-native distribution. Market structure concentrates around platform-integrated conglomerates and independent browser specialists, with limited mid-tier consolidation. Three archetypes dominate: super-app ecosystem operators, proprietary engine investors, and direct browser distribution platforms. Competitive moves center on vertical integration into rendering technology and geographic expansion through localized payment infrastructure.
Within the super-app ecosystem tier, Tencent exemplifies platform-integrated market power through WeChat mini-program infrastructure. Poki occupies a position among browser-native specialists sustaining direct publisher relationships across fragmented European territories. NetEase anchors the proprietary engine investment archetype, representing reduced third-party dependency through in-house technology development.
| Leading Market Players |
|---|
| China Mobile Games and Entertainment Group |
| Dalian Pantour |
| Tencent |
| Poki |
| Forgame |
| NetEase |
| Hoodinn Interactive Limited |
| Kongregate |
| Wuhu Sanqi Interactive Entertainment Network Technology Group |
| Others |
Pricing and Supply Chain Analysis
Mobile-first publishers concentrated in Southeast Asia's price-sensitive gamer populations anchor the dominant ad-supported pricing model, with carrier billing gaps forcing monetization architectures toward rewarded video SDKs rather than direct microtransaction stacks.
Pricing Analysis
Short lead-time deployment premiums apply to WeChat mini-program launches requiring rapid MIIT content review turnaround, while spot inventory discounts emerge for standardized browser-native titles. Three-tier pricing structure across premium proprietary engine investments, standard third-party SDK integrations, and economy ad mediation stacks separates Tencent's ecosystem control from independent Vietnamese studios. Cost compression in the economy tier intensifies as bandwidth volatility squeezes CDN-dependent publishers. Price-sensitive casual gamers in Indonesia and Vietnam drive the steepest discount pressure, while European GDPR-compliant publishers absorb premium attribution tooling costs.
Supply Chain Analysis
Logistics and freight cost volatility in cloud infrastructure provisioning concentrates supply chain risk for publishers dependent on AWS, Alibaba Cloud, and Tencent Cloud edge nodes across Asian delivery corridors. Engine licensing draws from concentrated Chinese and American technology stacks including Unity WebGL, Cocos Creator, and proprietary NetEase investments. Raw material dependencies center on JavaScript framework maintenance, WebGPU pipeline development, and ad mediation SDK integration. Single-source vulnerability in WeChat mini-program infrastructure creates chokepoint exposure for China-distributed titles. Distribution runs through fragmented browser engine implementations across Safari, Chrome, and Edge variants rather than consolidated app store gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where proprietary rendering engine control and first-party data infrastructure represent the decisive upstream levers separating ecosystem operators from margin-compressed independents.
For Market Incumbents: Deploy in-house WebGPU pipeline investments to reduce third-party engine licensing exposure and capture 60fps gameplay premiums on entry-tier Android devices. Consolidate direct publisher-to-player relationship infrastructure across European GDPR jurisdictions to defend first-party data moats against cohort-based attribution competitors. SAMR minor protection mandates and MIIT content review delays constitute the primary regulatory threat vectors requiring dual compliance stack architecture. For New Entrants and Emerging Players: Launch via messaging-app-embedded social competition layers targeting Ho Chi Minh City and Jakarta commuter clusters where share-to-continue mechanics drive organic install velocity. Indonesia's unbanked gamer population presents the most penetrable white-space opportunity, with localized carrier billing and e-wallet integration as the critical go-to-market angle. Vietnamese WebGPU rendering talent pools offer technical differentiation for mid-core strategy entrants. For Investors and Strategic Acquirers: The window for entry favors proprietary engine investors with GDPR-compliant attribution infrastructure and Southeast Asian payment rail development. Long-term viability hinges on controlling upstream rendering technology rather than downstream distribution relationships. Watch WebGPU adoption curves across Vietnamese studio outputs as the inflection signal separating technical leaders from SDK-dependent followers.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Engine Investment | NetEase and Tencent's in-house development reduces third-party platform dependency and licensing cost exposure. |
| GDPR-Compliant Attribution Buildout | French and German studios deploying differential privacy tooling gain competitive differentiation in European distribution negotiations. |
| Localized Payment Rail Development | Indonesian carrier billing and e-wallet integration creates first-mover advantage for publishers targeting unbanked populations. |
| WebGPU Rendering Pipeline Deployment | Vietnamese studios piloting 60fps tactical gameplay on entry-tier Android devices absorb native mobile development talent. |
| Hybrid PWA-H5 Architecture Rollout | San Francisco and Los Angeles publishers expand offline functionality to capture addressable moments beyond live connectivity windows. |
Research Methodology
SEC filings, MIIT content review disclosure databases, and App Annie mobile intelligence data formed the secondary backbone, supplemented by customs records tracking CDN infrastructure imports and hyperscaler capex disclosures. Primary interviews with HTML5 game studio CTOs, Southeast Asian ad mediation platform engineers, European data protection officers, and WeChat mini-program distribution managers validated quantitative assumptions. Bottom-up and top-down triangulation reconciled publisher revenue disclosures with platform-level engagement metrics.
Bottom-up modeling aggregated individual publisher revenue streams across game type, monetization model, and platform segments, while top-down validation calibrated against super-app ecosystem transaction volumes. Segmentation dimensions included deployment architecture, geographic regulatory cluster, player behavioral profile, and payment rail availability. CAGRs derived from cohort-based growth rate reconciliation across the projection horizon. Industry-specific forecast inputs incorporated WebGPU adoption velocity and GDPR enforcement action frequency.
MIIT regulatory tightening, GDPR penalty escalation, and CDN pricing volatility are the dominant revision risks that could compress publisher margins or accelerate platform consolidation. Forecasts reflect documented assumptions around super-app ecosystem penetration rates and browser engine performance parity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Gaming Accessories Market
Gaming
Global Online Simulation Games Market
Gaming
Connected Game Console Market
Gaming
Southeast Asia Gaming Market
Gaming
Online Casual Games Market
Gaming
Global Subscription-Based Gaming Market
Gaming
United States Gaming Market
Gaming
Game API Market
Gaming
VR Gaming Market
Gaming
Mobile Shooter Market
Gaming
Serious Games Market
Gaming
Racing Games Market
Gaming
FPS Game Market
Gaming
Russia in-Game Advertising Market
Gaming
Global Esports Market