
 Mobile Gaming Market | 2026-2036
Mobile Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Gaming Market Intelligence
The expansion of developer ecosystems in Southeast Asia is fragmenting the traditional studio landscape. Tencent Holdings Ltd. leverages its vast social media and payment infrastructure to maintain market leadership. Meanwhile, Supercell Oy specializes in creating highly polished, long-tail revenue titles with smaller development teams. NetEase Inc. competes by securing licenses for major intellectual properties and building a strong presence in the Japanese market.
Mobile gaming involves interactive entertainment software designed specifically for operation on portable electronic devices like smartphones and tablets. These games utilize device-native features such as touchscreens, accelerometers, and GPS for control and gameplay mechanics. The Freemium payment model dominates revenue generation, supported by a large base of Casual Gamers. While Action and Strategy games attract high-spending players, the Puzzle game type represents a mature and highly profitable segment.
Regulators including China's NMPA and Europe's authorities enforcing GDPR are scrutinizing data privacy and game monetization. NMPA's strict approval process for new titles directly controls market access in China, while GDPR compliance dictates user data handling practices for developers. Developer success will increasingly depend on navigating disparate regional rules on in-app purchases and loot box mechanics.
Market Dynamics
The proliferation of 5G networks enables global-scale game distribution, creating a central tension with divergent regional regulations. Developers must navigate complex compliance frameworks from China's NMPA to Europe's GDPR, shaping market access and monetization strategies.
Growth Catalysts
- 5G Network Expansion:Lower latency and higher bandwidth from 5G infrastructure enable more complex, high-fidelity game streaming and enhanced multiplayer experiences, particularly in developing markets with mobile-first internet access.
- Smartphone Penetration in India:The rapid adoption of affordable smartphones and low-cost data plans in India is creating a massive new audience of Casual Gamers, driving significant volume growth for the market.
- Cross-Platform Development Engines:Tools like Unity and Unreal Engine lower the barrier to entry for developers, fostering a vibrant ecosystem of independent studios and diversifying the game content available on mobile platforms.
Market Restraints
- Chinese Market Access Controls:China's NMPA imposes a strict and lengthy approval process for new game licenses, severely limiting market entry and creating significant revenue uncertainty for foreign and domestic publishers.
- App Store Commission Rates:High commission fees charged by platform holders like Apple's App Store and the Google Play Store compress developer margins, impacting the financial viability of smaller studios and freemium models.
- Competition from Cloud Gaming:The rise of cloud gaming services from major technology firms presents a substitution threat, offering console-quality experiences on mobile devices that could draw away high-spending players.
Strategic Opportunities
- Web3 and Blockchain Integration:The integration of blockchain for non-fungible tokens and play-to-earn models offers new monetization avenues and player engagement mechanics, particularly in markets with evolving regulatory frameworks.
- Localization for MENA Markets:Developing culturally and linguistically localized content for the Middle East and North Africa region represents a significant opportunity, tapping into a high-spending and engaged player base.
- Hyper-Casual Game Advertising:Leveraging hyper-casual games as platforms for brand advertising and user acquisition for other apps provides a revenue stream that is less dependent on direct in-app purchases from players.
Industry Challenges
- Intellectual Property Licensing Costs:Securing licenses for globally recognized intellectual properties from film, comics, and other media is increasingly expensive, creating a high barrier for studios without significant capital reserves.
- Navigating Global Privacy Laws:Maintaining compliance with a patchwork of data privacy regulations, including Europe's GDPR and California's CCPA, requires significant legal and technical investment, diverting resources from core game development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Gaming Market |
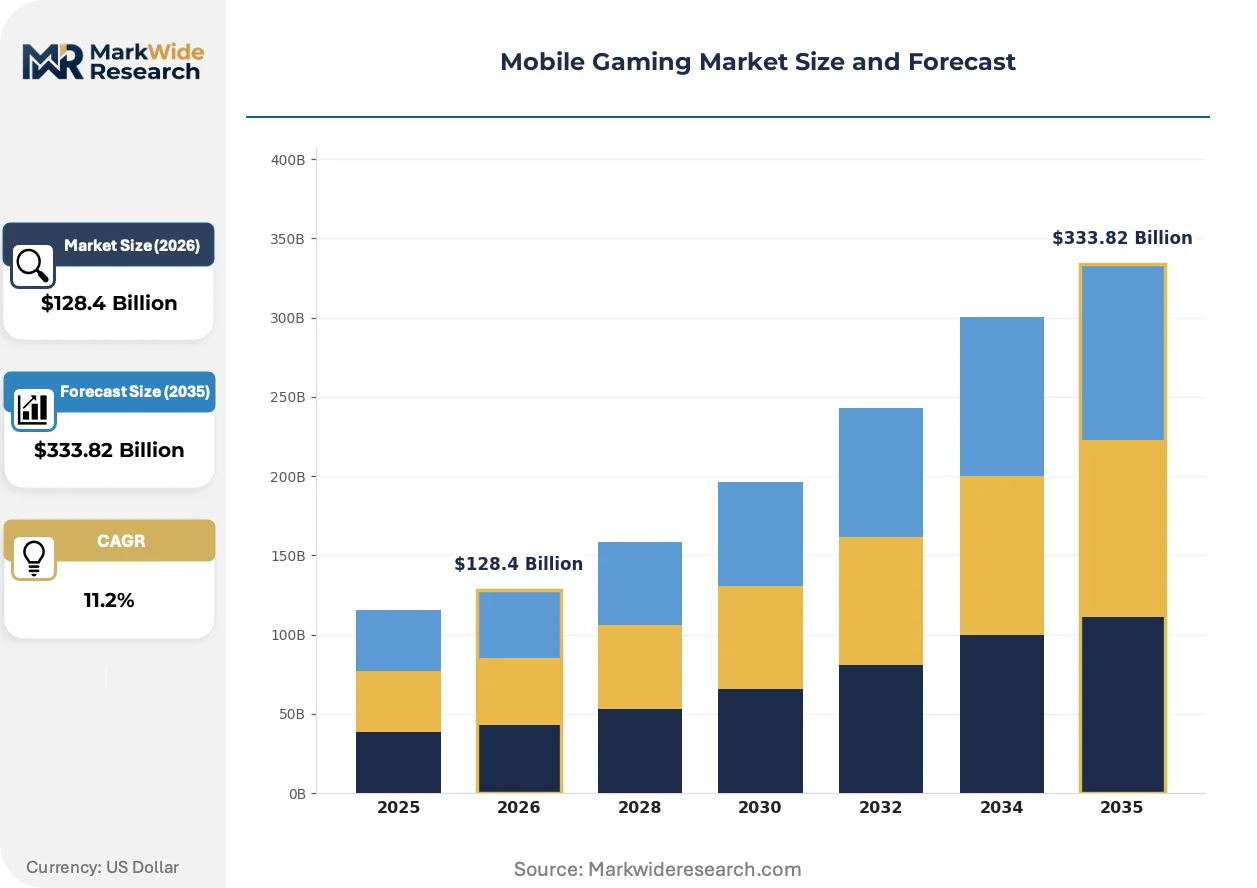
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $333.82 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Adventure, Puzzle, Strategy Payment Model: Freemium, Subscription, One-Time Purchase, In-App Purchase Device Type: Smartphones, Tablets, Handheld Consoles, Wearables Player Demographics: Casual Gamers, Hardcore Gamers, Competitive Players, Social Players |
| Companies Covered | Tencent Holdings Ltd., NetEase Inc., Electronic Arts Inc., Playrix Holding Ltd., Krafton Inc., Sea Ltd., Roblox Corporation, Scopely Inc., Supercell Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Gaming Market Strategic Shifts & Innovations
Technological advancements in game engines and hardware are colliding with a stricter regulatory climate around user data. This convergence is forcing developers to innovate business models beyond traditional in-app purchases and loot box mechanics to ensure sustainable revenue and compliance.
On-device machine learning models enable dynamic difficulty adjustment and procedural content generation directly on smartphones. Core and competitive gamers are adopting titles that use this for personalized experiences. This capability is rendering obsolete static, pre-programmed game loops and difficulty curves that fail to adapt to individual player skill levels.
European regulators, citing consumer protection and gambling laws, are increasing scrutiny of loot box mechanics in games. This pressure is compelling publishers to disclose odds or remove paid random-item mechanics entirely. The Strategy and Action game segments, which rely heavily on these monetization methods, are most affected and are exploring alternative cosmetic-only or battle pass models.
A behavioral shift towards community-centric gaming is evident, with players prioritizing social interaction and shared experiences. This trend de-emphasizes solitary gameplay in favor of titles with integrated social hubs, clan systems, and live events. The shift is most visible in the Asia-Pacific region, where social media integration within games drives both engagement and user acquisition.
Mobile Gaming Market Segmentation
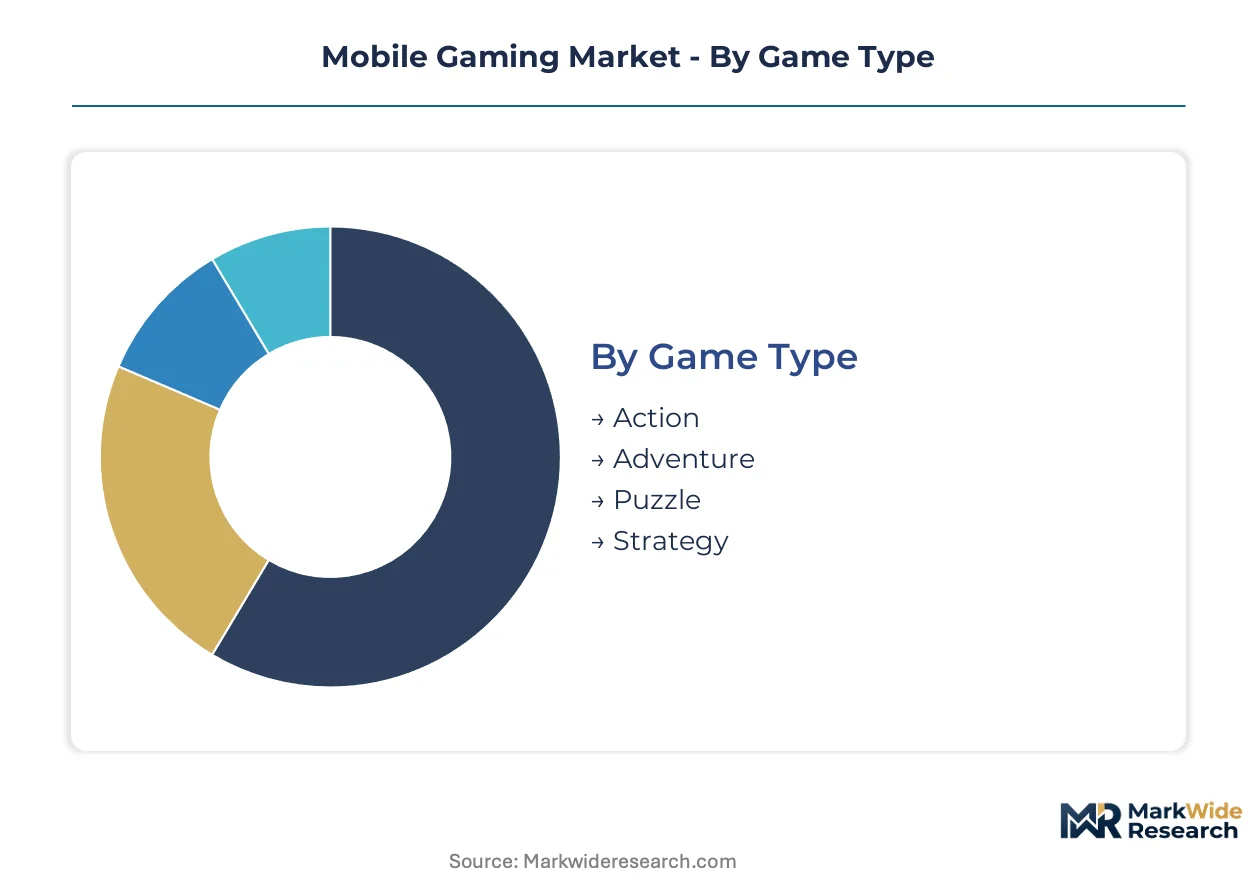
Mobile gaming segmentation provides a granular view of market dynamics, revealing distinct player behaviors, monetization preferences, and technological dependencies. Understanding these segments allows developers to tailor content, optimize distribution strategies, and navigate varied regulatory landscapes effectively.
Game Type:
The maturity spectrum across game types dictates revenue stability and innovation focus within the mobile gaming market.
- Puzzle:These games feature simple mechanics, intuitive interfaces, and broad appeal, often designed for short, engaging play sessions. Demand concentrates significantly in India, driven by smartphone penetration and accessible data plans among Casual Gamers.
- Strategy:Strategy games involve complex decision-making, resource management, and often real-time or turn-based combat, appealing to players seeking intellectual challenge. This type attracts high-spending players across Asia-Pacific, fueled by robust social interaction and competitive play features.
- Action:Action games emphasize fast-paced gameplay, real-time combat, and quick reflexes, appealing to competitive players globally.
- Adventure:Adventure titles offer narrative-driven experiences focusing on exploration, story progression, and puzzle-solving, attracting players seeking immersive single-player content.
Puzzle retains volume leadership; Strategy holds the steepest expansion curve.
Payment Model:
Revenue generation mechanisms vary significantly across payment models, influencing developer monetization strategies and player acquisition costs.
- Freemium:This model allows free game download and basic play, with optional purchases for additional content, features, or cosmetic items. It captures a global audience, particularly Casual Gamers, due to its low barrier to entry.
- In-App Purchase:These microtransactions enable players to buy virtual goods, currency, or content directly within a free or paid game. In-app purchases drive substantial revenue globally, especially from high-spending players seeking customization or progression acceleration.
- Subscription:Subscription services offer recurring payments for access to content libraries, premium features, or ad-free experiences, appealing to dedicated players in Europe.
- One-Time Purchase:Players make an upfront payment to own the full game, typically without further monetization, favored by consumers seeking complete, uninterrupted experiences.
Freemium models dominate player acquisition, while In-App Purchases drive the majority of market revenue.
Device Type:
Device type dictates player accessibility and the graphical fidelity of mobile gaming experiences across different hardware capabilities.
- Smartphones:These portable devices offer touch-enabled interfaces, integrated sensors, and ubiquitous connectivity, serving as the primary platform for mobile gaming. Smartphone penetration in India and global 5G network expansion drive immense demand for this segment.
- Tablets:Tablets provide a larger screen, enhanced graphics capabilities, and longer battery life compared to smartphones, enabling more immersive gameplay experiences. This segment sees strong demand in Europe and Asia-Pacific for casual and mid-core titles.
- Handheld Consoles:Dedicated gaming devices offering physical controls and optimized performance continue to appeal to traditional gamers seeking specialized experiences.
- Wearables:This emerging category utilizes smartwatches and other devices for simple, glanceable game experiences, often integrated with fitness tracking.
Smartphones command the largest user base, with tablets providing a premium experience for specific titles.
Player Demographics:
Player demographics define engagement levels and content preferences, influencing game design and monetization strategies.
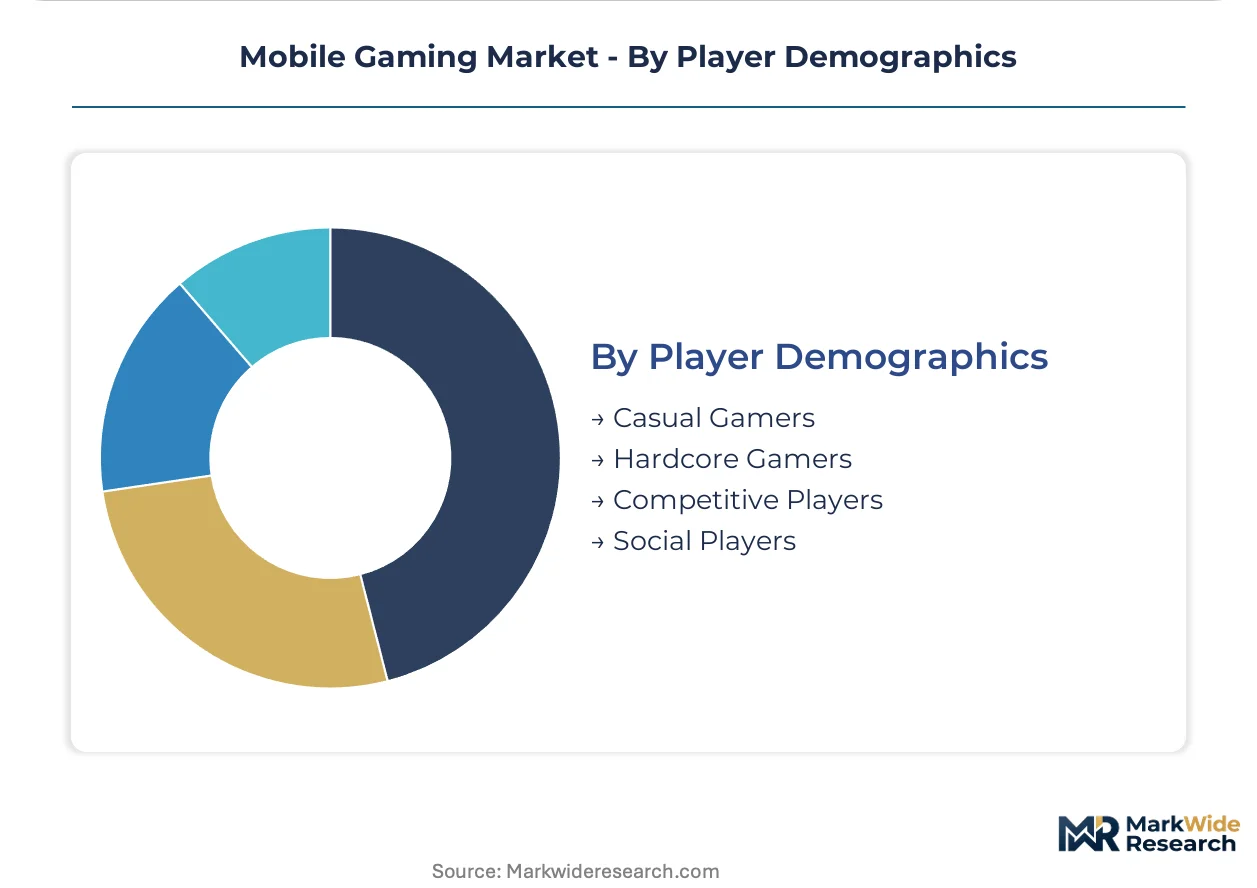
- Casual Gamers:These players engage with games intermittently, preferring simple mechanics and short play sessions without significant time commitment. This demographic constitutes a massive audience in India, driven by accessible smartphone ownership and low-cost data plans.
- Competitive Players:Competitive players seek high skill ceilings, direct player-versus-player interaction, and often participate in esports-like environments. Enhanced multiplayer functionalities and social media integration in Asia-Pacific drive engagement within this high-spending segment.
- Hardcore Gamers:Hardcore gamers invest significant time and money into complex titles, valuing deep gameplay mechanics, progression systems, and challenging content.
- Social Players:These players prioritize interaction with friends and community features within games, often driven by in-game events and shared experiences.
Casual Gamers represent the market's volume base, while Competitive Players drive significant revenue through specialized content.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mobile gaming market exhibits diverse consumption patterns across geographies. India leads in casual gaming adoption due to widespread smartphone penetration and affordable data. Meanwhile, Asia-Pacific markets like China and Japan focus on high-spending competitive players. European regions emphasize subscription models and premium tablet experiences for dedicated users.
India
Smartphone penetration and accessible data plans drive significant volume growth among casual gamers. The Telecom Regulatory Authority of India (TRAI) policies support affordable data, expanding the user base. Mumbai and Bengaluru hubs see a surge in local game development and user acquisition efforts.
China
Demand in China concentrates on competitive play and social interaction, leveraging vast digital ecosystems. China's NMPA imposes strict approval processes for new game titles, controlling market access. Shanghai remains a major center for game development, attracting significant domestic publisher investment.
Japan
Japanese players demonstrate high spending on titles with strong intellectual properties and deep gameplay mechanics. The Ministry of Economy, Trade and Industry (METI) oversees intellectual property rights, impacting licensing costs. Tokyo's gaming industry thrives with major publishers and specialized studios creating global franchises.
Germany
Demand in Germany leans towards immersive experiences on tablets and subscription-based content for dedicated players. GDPR compliance dictates stringent user data handling practices for all developers within the European Union. Berlin's vibrant tech ecosystem fosters innovation in mobile game development, particularly for mid-core titles.
United Arab Emirates
The United Arab Emirates represents a high-spending and engaged player base, with growing demand for culturally localized content. Digital economy initiatives and consumer protection regulations from MOHAP shape the market environment. Dubai emerges as a regional hub for gaming events and digital entertainment services.
Mobile Gaming Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the mobile gaming market. The landscape features large integrated technology companies alongside specialized game developers and independent studios. Global publishers leverage vast user bases and infrastructure, while niche players focus on specific genres or monetization models. Competitive moves include significant mergers and acquisitions, alongside strategic partnerships to expand geographic reach and diversify content portfolios, ensuring broad market penetration and sustained player engagement.
Integrated technology giants like Tencent Holdings Ltd. and China-based NetEase Inc. represent one end of the competitive spectrum. These companies leverage extensive social media and payment infrastructure, alongside securing major intellectual property licenses, to maintain market leadership and capture a broad audience across various game types. Conversely, Supercell Oy exemplifies a specialist approach, focusing on creating highly polished, long-tail revenue titles with smaller, agile development teams. This strategy appeals to specific player segments with deep engagement, often through innovative game mechanics and strong community building.
| Leading Market Players |
|---|
| Tencent Holdings Ltd. |
| NetEase Inc. |
| Electronic Arts Inc. |
| Playrix Holding Ltd. |
| Krafton Inc. |
| Sea Ltd. |
| Roblox Corporation |
| Scopely Inc. |
| Supercell Oy |
| Others |
Cost & Logistics Intelligence
Shanghai's robust game development capacity directly influences the global pricing power for mobile titles. This concentration of content creation, particularly for competitive play, allows major publishers to dictate market entry terms and monetization strategies across various regional markets.
Pricing Analysis
Hybrid monetization models, integrating freemium access with in-app purchases, define the mobile gaming market's pricing structure. Price differentiation stems from content depth and brand premium associated with licensed intellectual properties. Platform holder commissions create significant pricing pressure, impacting developer margins. Casual Gamers exhibit the highest price sensitivity, preferring free-to-play options, while Competitive Players demonstrate lower sensitivity for in-app purchases.
Supply Chain Analysis
China's NMPA regulatory controls directly impact the supply chain for mobile game content by limiting market access. Geographic development concentration sits in Shanghai, Tokyo, and Berlin, drawing from intellectual properties and game engine licenses. Single-source vulnerability for key intellectual properties represents a structural risk. Digital distribution via platform-specific app stores dominates the downstream model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile gaming market requires a strong substitution defense, as the rise of cloud gaming services presents a notable threat to established player bases.
For Market Incumbents: Harden core market positions by leveraging existing social media and payment infrastructure, particularly in Asia-Pacific markets. Incumbents must also secure major intellectual property licenses to counter rising content costs and cloud gaming threats. Investing in on-device machine learning for personalized experiences serves as a key lever against platform commoditization.
For New Entrants and Emerging Players: Build out niche content strategies focused on Web3 and blockchain integration for new monetization avenues. Localization for MENA markets represents a significant white-space target due to its high-spending player base. Hyper-casual games offer a penetrable segment for user acquisition, utilizing advertising models to generate revenue.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized developers with proven track records in high-engagement, long-tail revenue titles. Long-term viability hinges on studios capable of navigating diverse regulatory frameworks and adapting monetization strategies. Acquisition targets include firms innovating in Web3 integration or those with strong IP portfolios. Regulatory clarity on blockchain gaming and the sustained performance of alternative monetization models are key signals to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| IP Licensing & Co-development | Securing major intellectual properties reduces content risk and attracts established fan bases. |
| Regional Market Entry Strategy | Tailoring content and monetization for specific geographies like MENA unlocks high-spending player segments. |
| Blockchain/Web3 Integration | Exploring non-fungible tokens and play-to-earn models opens new player engagement and revenue streams. |
| Enhanced Multiplayer Functionalities | Improving social and competitive features drives engagement and player retention for core gamers. |
| Hyper-Casual Ad Network Development | Building advertising platforms within simple games diversifies revenue beyond in-app purchases. |
Research Approach
A standing panel of game developers, platform executives, and publishing strategists provided ongoing calibration for market trends and competitive dynamics. This approach combined primary interviews with industry stakeholders and secondary validation from sources like NMPA approval lists, App Store analytics, and public financial filings. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Scenario-bracketing across conservative and optimistic outlooks informed the market forecast across the analysis window. The analytical framework modeled segmentation dimensions including game type, payment model, device type, player demographics, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data extrapolation and projected adoption rates. Key forecast inputs included smartphone penetration rates and 5G network rollout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated technology giants or specialized developers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Material shifts in global privacy laws or platform monetization policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Africa Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
China Casino Tourism Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Casino Gaming Equipment Market
Gaming
Australia Gaming Accessories Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Chinese Gaming Industry Market
Gaming
GCC Gaming Headsets Market
Gaming
3D Gaming Technology Market
Gaming
Europe Serious Gaming Market
Gaming
Console Games Market
Gaming
Gaming Accessories Market
Gaming
Video Game Software Market