
 South Asia Mobile Gaming Market | 2026-2036
South Asia Mobile Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
South Asia Mobile Gaming Market Analytics
Market Context with Strategic Players
Cloud-based game streaming infrastructure is hardening as the dominant delivery substrate across South Asia, replacing device-native processing dependency for graphics-intensive titles. Tencent Holdings Ltd leverages its WeChat-integrated distribution architecture to anchor user acquisition costs below regional averages. Krafton dominates battle royale monetization through localized esports leagues and creator economy partnerships. Games24x7 sustains its position by specializing in skill-based real-money gaming formats that navigate India's state-level gambling regulation variance.
Technical Definition and Structural Segments
South Asia Mobile Gaming encompasses interactive software applications designed for smartphones and tablets, typically requiring operating system compatibility with Android or iOS, processor thresholds of 4GB+ RAM, and network latency below 150ms for real-time multiplayer functionality. The primary commercial purpose centers on delivering entertainment experiences while capturing recurring revenue through microtransactions, advertising impressions, or subscription renewals. Freemium monetization models generate the deepest revenue pools by converting non-paying users through tiered progression mechanics, while ad-supported formats maintain the broadest install base among price-sensitive segments. Action and Strategy game types concentrate the highest session duration metrics, creating superior inventory value for in-app advertising networks.
Regulatory Framework and Forward Outlook
India's TRAI governs data pricing and net neutrality provisions that directly shape platform accessibility, while BIS certification requirements for pre-installed gaming content affect device manufacturer bundling decisions. Bangladesh's BTRC and Pakistan's PTA impose content rating and payment gateway localization mandates that determine foreign publisher market entry feasibility. Stakeholders must monitor evolving real-money gaming classification disputes across Indian state jurisdictions, as these rulings will determine whether skill-based monetization models retain their current regulatory exemption status or face prohibition-level restrictions.
Market Dynamics
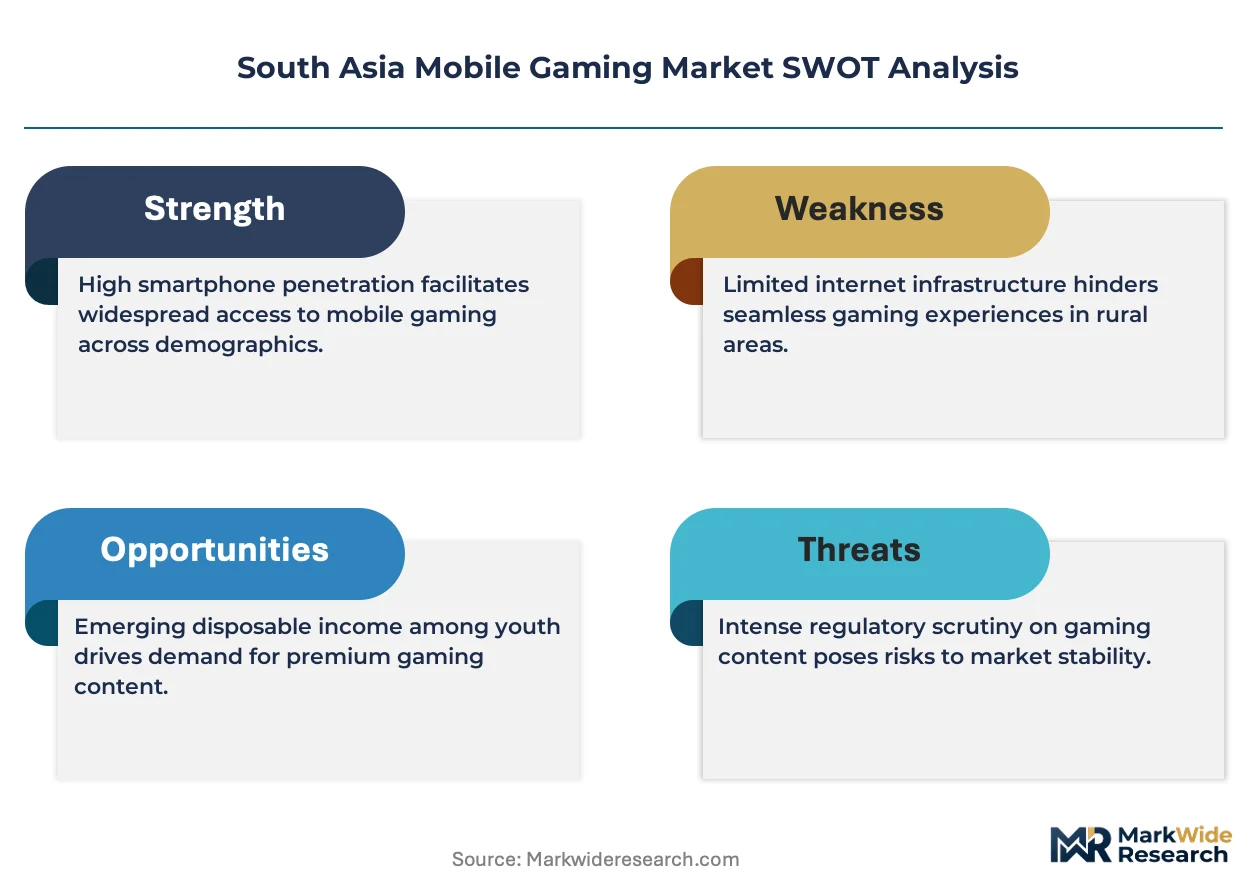
Cloud streaming infrastructure is compressing hardware dependency across South Asia, enabling graphics-intensive titles to run on sub-$100 smartphones and expanding addressable audiences beyond premium device owners.
Growth Catalysts
- TRAI Data Pricing Frameworks:India's regulatory caps on mobile data tariffs sustain platform accessibility for price-sensitive users. Low per-gigabyte costs enable sustained session durations essential for freemium monetization conversion.
- Skill-Based Gaming Formats:Real-money gaming categories operating under India's state-level skill exemptions generate recurring revenue pools. These formats attract high-engagement cohorts with superior lifetime value metrics.
- Localized Esports Infrastructure:Creator economy partnerships and tournament leagues deepen user retention. Bangladesh and Pakistan replicate India's league models to build domestic competitive ecosystems.
Market Restraints
- BIS Certification Requirements:India's mandatory pre-installed content standards create compliance friction for foreign publishers. Device manufacturer bundling decisions face extended approval timelines.
- Payment Gateway Localization:Bangladesh's BTRC and Pakistan's PTA mandate domestic payment rails. Foreign platforms must rebuild transaction stacks, delaying market entry by quarters.
- Network Latency Thresholds:Real-time multiplayer functionality demands sub-150ms latency. Rural 4G coverage gaps in India's hinterland and Pakistan's tribal belt exclude geographies from competitive gaming formats.
Strategic Opportunities
- Bangladesh Secondary Corridor:Underpenetrated relative to India, Bangladesh's rising smartphone penetration and youthful demographics offer first-mover positioning. BTRC's evolving content rating framework will clarify entry pathways.
- Cloud-Native Development:Convergence of 5G rollouts and edge computing infrastructure enables instant-play experiences. Studios can bypass app store friction through browser-based distribution.
- PLI Scheme Incentives:India's production-linked incentive schemes for electronics manufacturing reduce device costs. Cheaper 4GB+ RAM smartphones expand the hardware-eligible population.
Industry Challenges
- Real-Money Gaming Classification Disputes:Indian state jurisdictions issue conflicting rulings on skill versus chance distinctions. Platforms face operational suspension risk in Maharashtra, Telangana, or Andhra Pradesh depending on judicial interpretation.
- Localization Talent Scarcity:Vernacular content production for India's 22 scheduled languages requires native-speaking game writers and cultural consultants. Supply of qualified localization professionals lags demand from global publishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Asia Mobile Gaming Market |
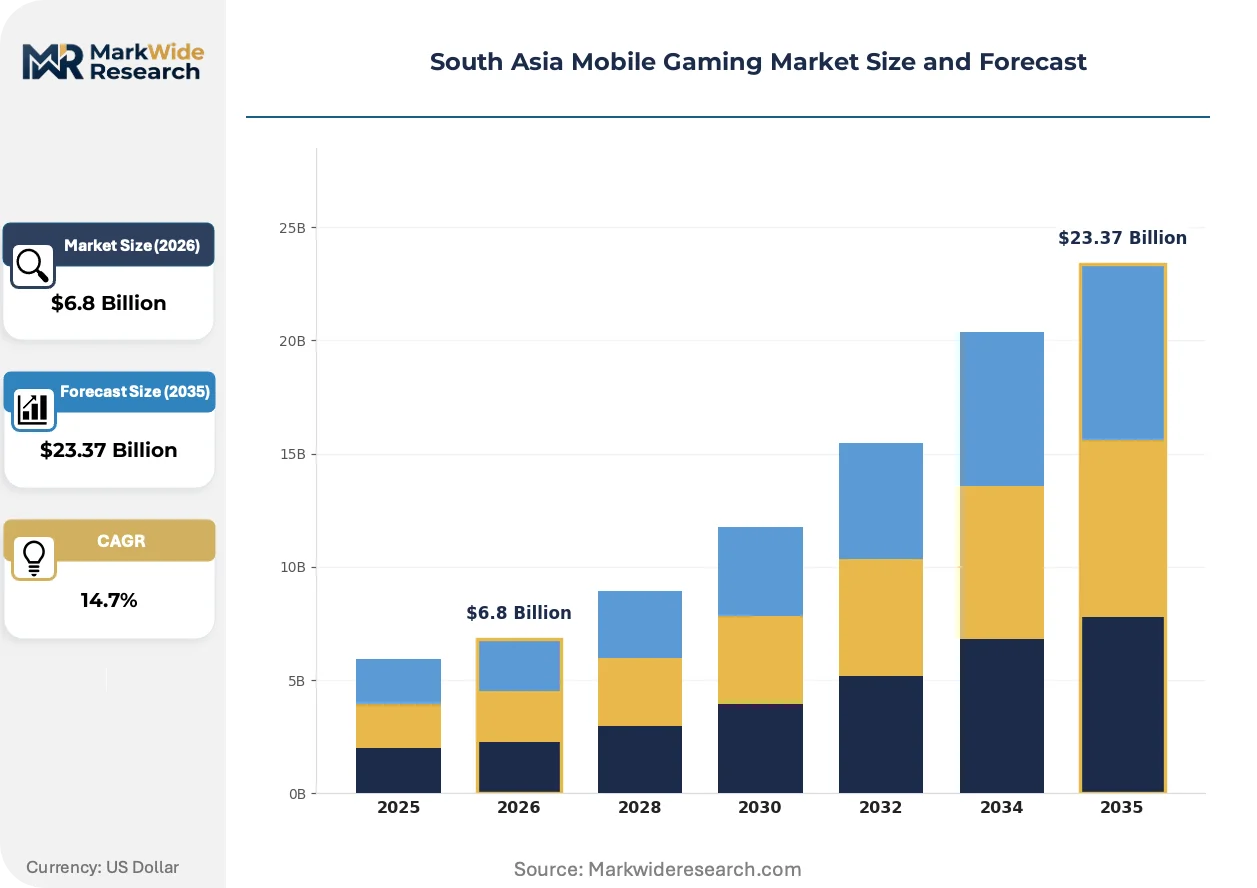
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.37 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Puzzle, Adventure, Strategy Monetization Model: In-App Purchases, Subscription, Freemium, Ad-Supported End User: Casual Gamers, Hardcore Gamers, Competitive Players, Families Platform: Android, iOS, Windows, Others |
| Companies Covered | IGG Inc., Games24x7, Tencent Holdings Ltd, Bandai Namco Entertainment Asia, Krafton, Netmarble Corporation, Asiasoft Corporation Public Company Limited, Lilith Games, Garena SEA Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Asia Mobile Gaming Market Evolving Landscape
Interactive entertainment delivery is fragmenting across multiple technical substrates, with streaming, instant-play, and progressive web applications competing to replace native app dominance.
Cloud-based game streaming is overtaking device-native processing as the primary delivery mechanism for mid-core and hardcore titles. Casual gamers in India's tier-2 and tier-3 cities adopt streaming-first access models to circumvent storage constraints on budget smartphones. This shift compresses hardware upgrade cycles and redirects consumer spending toward data plans rather than device replacement.
India's BIS digital content standards are tightening pre-installation requirements for gaming applications on domestically manufactured devices. Foreign publishers must now certify content through designated testing facilities before bundling agreements with OEMs. Chinese and Korean studios with established BIS relationships secure preferential placement on entry-level smartphones sold through offline retail channels.
Creator-led user acquisition is displacing traditional paid advertising as the dominant growth channel across South Asia. Gaming influencers on YouTube and localized short-video platforms drive install volumes with superior retention metrics versus performance marketing. Bangladesh and Pakistan demonstrate the highest conversion efficiency from creator codes to in-app purchases, reflecting trust-based purchasing behavior in emerging digital commerce environments.
South Asia Mobile Gaming Market Segmentation
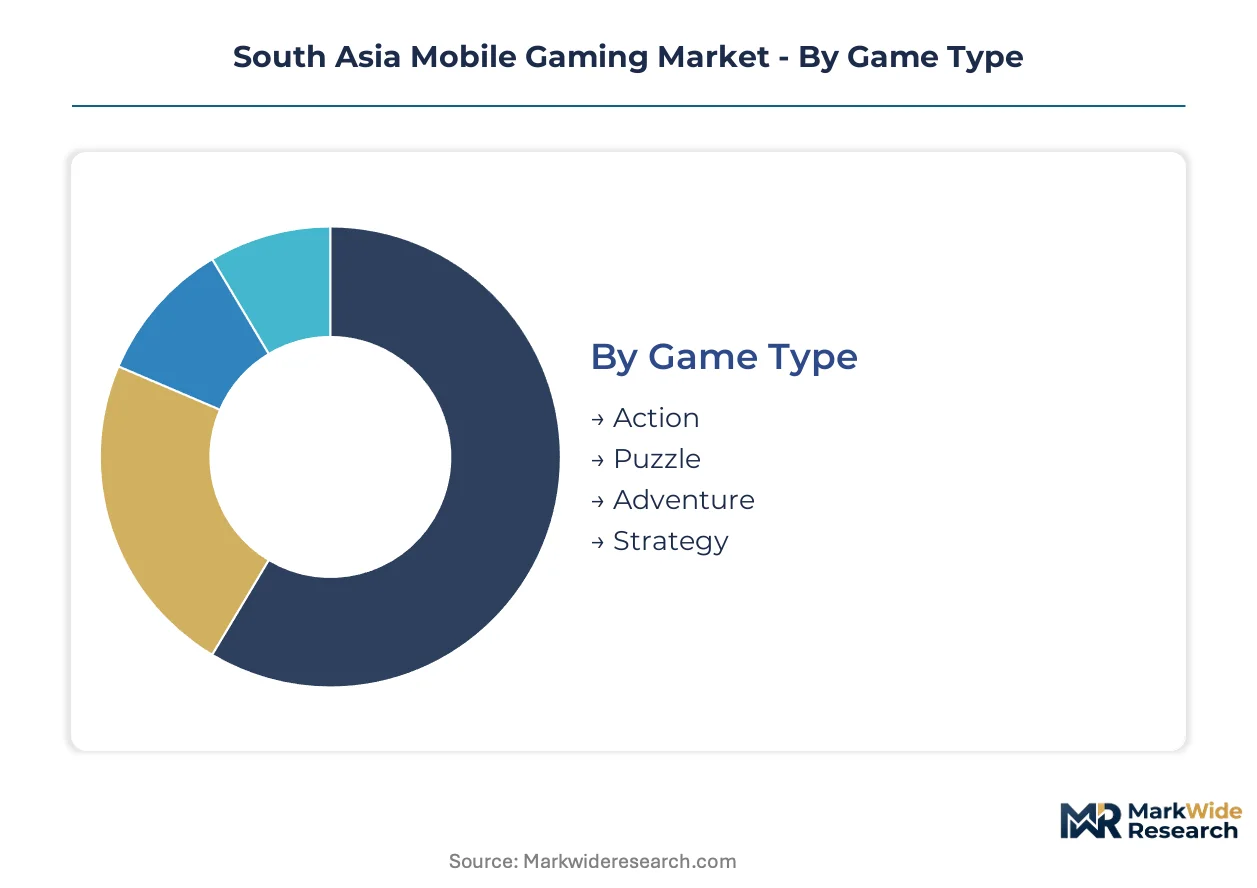
Segmentation in South Asia Mobile Gaming reveals distinct monetization viability thresholds across user engagement patterns. Platform choices and game type preferences directly determine customer acquisition costs and lifetime value calculations in this price-sensitive region.
Game Type:
Volume concentration favors low-complexity formats with broad demographic appeal, while premium monetization clusters around competitive mechanics with extended session depths.
- Action:Real-time combat mechanics and reflex-based gameplay dominate session duration metrics. Indian tier-1 cities and Bangladesh's Dhaka-Chittagong corridor concentrate demand, driven by esports tournament infrastructure and creator economy visibility.
- Strategy:Base-building and resource management systems generate the highest per-user revenue through progression gating. Pakistan's urban centers and India's state capitals show concentrated adoption, constrained by network latency requirements for synchronous multiplayer.
- Puzzle:Pattern-matching and logic challenges sustain broad install bases with minimal hardware demands. Mass-market penetration across rural India and Bangladesh's secondary towns leverages low data consumption.
- Adventure:Narrative-driven exploration formats with episodic content release schedules. Smaller addressable audience limited by storage constraints on sub-4GB RAM devices prevalent in tier-3 Indian markets.
Mature deployment sits with Action. Newer deployment is concentrated in Strategy.
Monetization Model:
Revenue architecture separates high-friction direct payment systems from frictionless indirect models adapted to local financial infrastructure.
- Freemium:Tiered access gates convert non-paying users through progression throttling and cosmetic differentiation. India's TRAI data pricing frameworks sustain the addressable base by keeping session costs negligible.
- In-App Purchases:Microtransaction stacks for virtual currency and power-ups. Bangladesh and Pakistan demonstrate conversion efficiency challenges due to payment gateway localization mandates from BTRC and PTA.
- Ad-Supported:Rewarded video and interstitial inventory monetizes price-sensitive segments. Dominant format across India's tier-2 and tier-3 cities where disposable income for digital entertainment remains constrained.
- Subscription:Recurring revenue through battle pass and premium tier unlocks. Limited penetration outside India's metropolitan centers due to credit card and UPI auto-debit adoption gaps.
Revenue maturity clusters in Freemium. Fastest share gains are occurring in Ad-Supported.
End User:
Engagement depth and spending propensity create four distinct cohorts with divergent platform requirements and content preferences.
- Casual Gamers:Intermittent session patterns with preference for single-thumb mechanics and offline functionality. Expanding most quickly across South Asia's first-time smartphone adopters in Bangladesh and Pakistan.
- Hardcore Gamers:Daily session commitments exceeding 90 minutes with tolerance for complex control schemes. India's metropolitan youth demographic concentrates demand, limited by device upgrade cycles.
- Competitive Players:Ranked ladder participation and tournament entry with esports career orientation. Geographic concentration in Indian cities with established gaming cafe infrastructure and low-latency 5G coverage.
- Families:Multi-generational household accounts with parental control requirements and educational content preferences. Emerging segment in India's nuclear family structures with shared device usage patterns.
Established engagement patterns define Hardcore Gamers. Demographic expansion is strongest in Casual Gamers.
Platform:
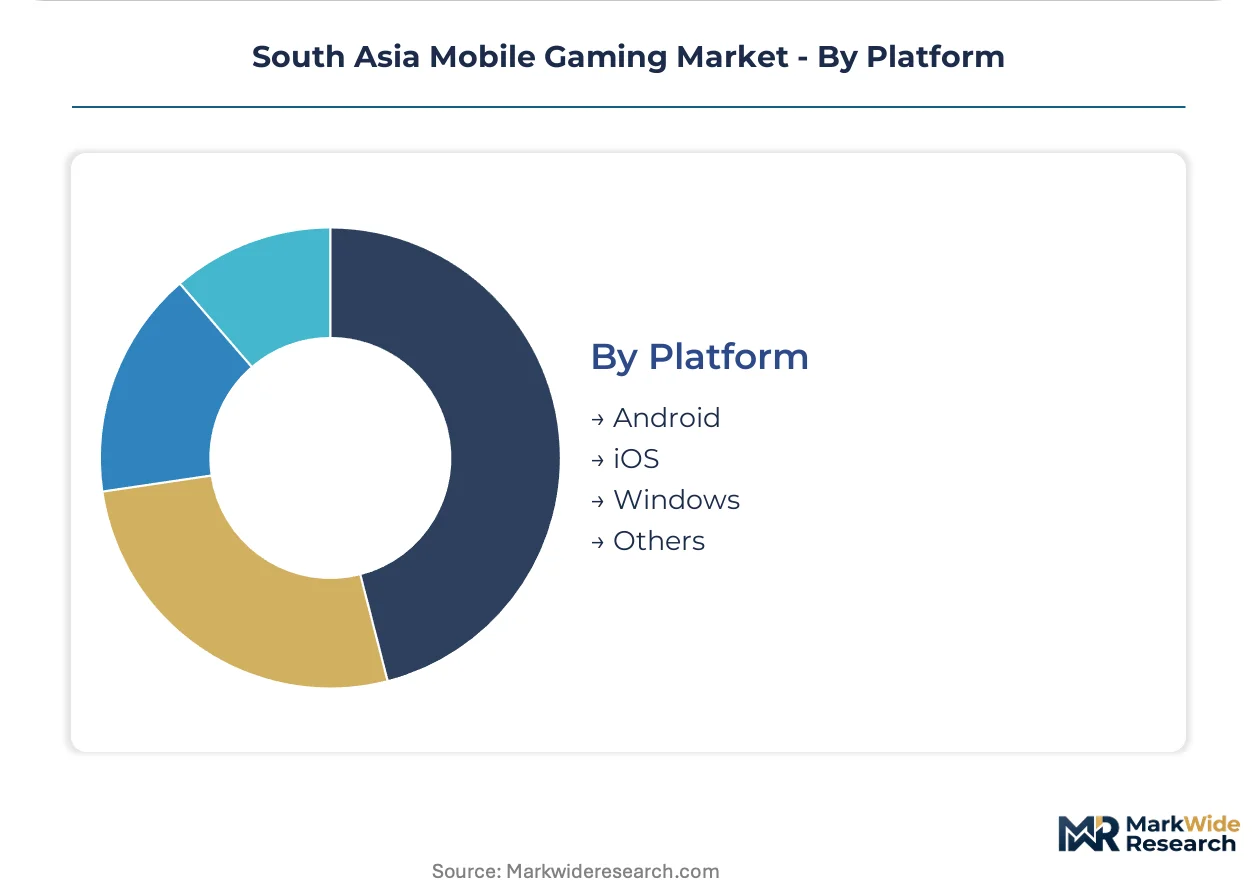
Operating system market structure reflects device affordability hierarchies and manufacturer distribution strategies across South Asian retail channels.
- Android:Open-source architecture enabling sub-$100 hardware with customizable OEM skins. Dominant platform across India, Bangladesh, and Pakistan due to Chinese manufacturer market penetration and PLI scheme incentives for domestic assembly.
- iOS:Premium device ecosystem with superior monetization metrics per user. Concentrated in India's top 10 urban agglomerations and expatriate-heavy segments in Bangladesh.
- Windows:Cross-platform continuity for hybrid tablet-laptop devices. Niche presence in enterprise-education crossover segments with institutional procurement in Indian schools.
- Others:KaiOS and proprietary feature phone operating systems with limited gaming functionality. Residual category concentrated in India's 2G-dependent rural hinterland awaiting network modernization.
Platform maturity resides with Android. Emerging platform experimentation clusters in Windows crossover devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the deepest demand pools across South Asia, with Bangladesh and Pakistan forming secondary growth corridors where infrastructure investments are compressing hardware dependency and expanding addressable audiences.
India
Metropolitan youth demographics and tier-2 city smartphone adoption drive volume expansion. TRAI data pricing caps sustain platform accessibility for price-sensitive users. Bangalore and Hyderabad anchor esports tournament infrastructure and gaming cafe networks.
Bangladesh
First-time smartphone adopters and youthful demographics create underpenetrated expansion potential. BTRC content rating frameworks determine foreign publisher entry feasibility. Dhaka-Chittagong corridor concentrates demand for low-complexity casual formats.
Pakistan
Urban centers generate concentrated adoption for strategy and action genres with extended session depths. PTA payment gateway localization mandates delay foreign platform market entry. Karachi and Lahore host competitive gaming infrastructure with creator economy visibility.
Sri Lanka
Tourism-dependent digital commerce patterns shape disposable income allocation for entertainment spending. Central Bank payment system regulations affect cross-border transaction processing. Colombo metropolitan area concentrates device upgrade cycles and premium tier adoption.
Nepal
Remittance-driven purchasing power and Indian content consumption habits influence platform preferences. Nepal Telecommunications Authority spectrum allocation affects 4G coverage expansion in Himalayan terrain. Kathmandu Valley represents the primary addressable market for cloud-streaming access models.
South Asia Mobile Gaming Market Competitive Landscape
Creator economy partnerships dominate the current landscape as publishers bypass traditional paid acquisition channels. The vendor base clusters around three strategic tiers: global platform operators with integrated distribution infrastructure, regional specialists in skill-based monetization formats, and emerging domestic studios leveraging localized content production. Competitive positioning hardens through exclusive tournament league sponsorships and influencer network exclusivity arrangements. Technology licensing agreements and payment stack localization represent the dominant tactical moves for market entry.
Within the integrated platform tier, Tencent Holdings Ltd and Krafton anchor competitive positioning through distribution infrastructure and esports ecosystem investments. Games24x7 occupies a specialist position navigating India's state-level regulatory variance for skill-based monetization. These three entities exemplify the divergent archetypes—global distribution leverage, genre-specific ecosystem depth, and regulatory arbitrage specialization—that define viable competitive strategies across South Asian price-sensitive and compliance-complex markets.
| Leading Market Players |
|---|
| IGG Inc. |
| Games24x7 |
| Tencent Holdings Ltd |
| Bandai Namco Entertainment Asia |
| Krafton |
| Netmarble Corporation |
| Asiasoft Corporation Public Company Limited |
| Lilith Games |
| Garena SEA Group |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cloud infrastructure specialists anchor supply behavior across South Asia's mobile gaming delivery stack, compressing server costs through centralized edge-node deployment while enforcing pricing discipline on per-gigabyte streaming rates. Their consolidated ownership of streaming middleware creates captive supply relationships with Indian OEMs, feeding back into device bundling economics that shape end-user access costs.
Pricing Analysis
Volume concentration in ad-supported formats compresses margins at the economy tier while freemium conversion mechanics sustain premium-tier profitability. Price differentiation hinges on data consumption efficiency and localization depth, with vernacular content commanding modest premiums over English-only deployments. Pricing pressure intensifies downward as TRAI-mandated data caps force platforms to absorb infrastructure costs rather than pass through to users. Casual gamers in Bangladesh and Pakistan's secondary cities exhibit highest price sensitivity, whereas India's metropolitan competitive players tolerate subscription premiums for low-latency access.
Supply Chain Analysis
Workforce availability constraints in India's Bangalore-Hyderabad corridor and Dhaka's emerging tech zones concentrate cloud infrastructure development talent, creating bottlenecks for real-time multiplayer backend scaling. Geographic supply concentration centers on India, Singapore, and South Korea for edge server deployment and game engine middleware. Raw material dependencies span semiconductor fabrication for 4GB+ RAM chipsets, lithium-ion cells for extended session battery life, and fiber-optic cable for latency-sensitive backhaul. Single-source vulnerability in Taiwan-sourced mobile processors creates exposure to trade restriction cascades. Distribution runs through OEM pre-installation agreements with Chinese and Indian device manufacturers, supplemented by over-the-top app store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud rendering capacity scarcity props pricing discipline across South Asia's streaming-first gaming transition, as insufficient edge-node deployment constrains simultaneous concurrent sessions below demand growth trajectories.
For Market Incumbents: Cement exclusive esports league sponsorships and creator economy lockups before regional competitors replicate India's tournament infrastructure. Defend against emerging domestic studios by deepening vertical integration into vernacular content production, capturing scarce localization talent through long-term employment contracts rather than project-based outsourcing. For New Entrants and Emerging Players: The premium-economy price-point gap in Bangladesh's underpenetrated Dhaka-Chittagong corridor offers white-space positioning for mid-tier freemium formats with localized payment integration. Target Pakistan's strategy-game segment where PTA payment localization delays have thinned foreign competition, entering through browser-based instant-play distribution to bypass app store friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian skill-based gaming specialists facing state-level regulatory overhang in Maharashtra or Telangana, where judicial uncertainty compresses valuations below intrinsic engagement metrics. Long-term viability hinges on regulatory arbitrage resolution rather than technology differentiation. Watch BIS certification queue lengths as inflection signal: extended approval timelines indicate tightening compliance barriers that favor incumbents with established OEM relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | Browser-based distribution bypasses TRAI data pricing friction for India's tier-3 cities. |
| Creator Economy Exclusivity Lockups | YouTube and Moj influencer codes drive superior retention versus performance marketing in Bangladesh. |
| Vernacular Localization Scale-Up | Native-speaking writer acquisition captures India's 22 scheduled language demand pools. |
| Esports League Sponsorship | Tournament infrastructure anchors daily active user commitments in Pakistan's urban centers. |
| Payment Stack Localization | BTRC and PTA-compliant domestic rails unlock Bangladesh and Pakistan microtransaction conversion. |
Research Methodology
Regulatory filings from TRAI, BTRC, and PTA, alongside BIS certification databases and OEM partnership disclosures, formed the secondary backbone for supply-side and compliance mapping. Primary interviews with cloud infrastructure architects, esports league operators, vernacular content localization studios, and Indian state gaming commission legal counsels validated demand assumptions and regulatory trajectory. SEC filings from Tencent, Krafton, and Netmarble provided disclosed regional revenue splits. Bottom-up smartphone shipment data by RAM tier and top-down data consumption metrics were triangulated against publisher-reported session duration benchmarks.
Historical trendline analysis of India's mobile data pricing compression and Bangladesh's smartphone penetration curves informed elasticity assumptions across the projection horizon. Segmentation modeling incorporated game type complexity tiers, monetization model conversion funnels, end-user engagement depth cohorts, and platform operating system share trajectories. CAGRs were derived from installed base expansion rates modulated by device replacement cycles and network coverage rollout schedules. Forecast inputs included PLI scheme subsidy impact on 4GB+ RAM device affordability and 5G spectrum allocation timelines from Nepal Telecommunications Authority.
Inputs from TRAI quarterly reports and Sensor Tower download estimates were available through the study window; gaps in real-money gaming state-jurisdiction enforcement data introduce uncertainty bands around skill-based monetization forecasts. Forecasts reflect documented assumptions regarding BIS certification processing efficiency and cloud edge-node deployment cadence. Material deviation in Indian state supreme court rulings on skill-versus-chance classification warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
SLG Game Market
Gaming
China Subscription-Based Gaming Market
Gaming
Game API Market
Gaming
Global Online Simulation Games Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Arcade Cabinet Market
Gaming
Gaming Software Market
Gaming
Europe Casino Gambling Market
Gaming
VR Gaming Controller Market
Gaming
North America Casino Gambling Market
Gaming
United Kingdom Online Gambling Market
Gaming
Gaming Hardware Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Casino Gaming Equipment Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Gaming Simulator Market