
 Mobile MOBA Games Market | 2026-2036
Mobile MOBA Games Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile MOBA Games Market Insights
Subscription-based battle pass systems is repositioning how mobile MOBA titles monetize recurring engagement rather than one-time purchases. Tencent Games leverages its WeChat and QQ ecosystem to sustain player retention across Honor of Kings and Arena of Valor. TiMi Studio Group anchors the technical pipeline for cross-platform engine optimization. Moonton competes aggressively in Southeast Asia through localized hero design and regional tournament infrastructure.
Mobile MOBA games are multiplayer online battle arena titles built for touchscreen interfaces, typically featuring 5v5 team combat with 10-20 minute match durations and touch-optimized control schemes including virtual joysticks and ability buttons. These games serve the commercial purpose of capturing fragmented leisure time on smartphones while building persistent player communities that generate recurring revenue. Battle arena formats dominate download volumes, while in-app purchases generate the deepest margin pools through cosmetic skin sales and seasonal content unlocks. Cross-platform deployment is expanding fastest as cloud gaming infrastructure reduces hardware barriers for competitive play.
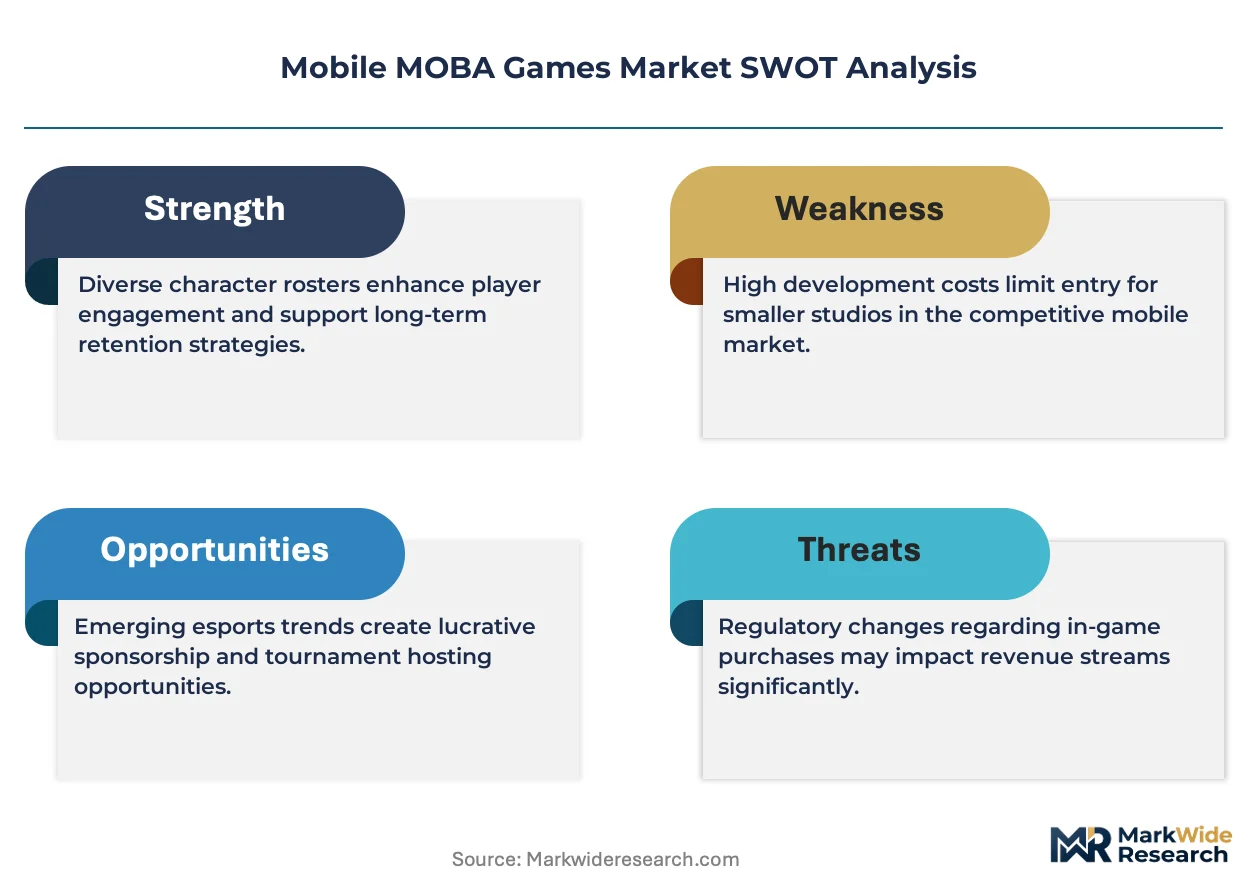
China's NMPA and MIIT enforce content approval and youth gaming time restrictions that directly shape product roadmaps and release cadences for domestic publishers. South Korea's GRAC rating system and the EU's GDPR data handling requirements create compliance layers that filter which titles enter those markets and how player data monetization operates. Stakeholders must monitor evolving classification standards and age-verification mandates as these frameworks increasingly determine market access velocity and monetization ceiling.
Market Dynamics
Cross-platform engine unification is compressing development cycles and collapsing the hardware barrier between mobile and PC esports ecosystems. Publishers now optimize single codebases across iOS, Android, and PC clients rather than maintaining fragmented builds.
Growth Catalysts
- Cloud gaming infrastructure:Low-latency edge servers in Indonesia and Brazil eliminate device performance constraints, expanding addressable audiences beyond flagship smartphone owners.
- MIIT content approval framework:China's streamlined green-channel process for competitive titles accelerates domestic release timelines and reduces regulatory uncertainty for publishers targeting the mainland market.
- 5G network densification:Sub-10ms latency in Southeast Asian urban clusters enables real-time skill-shot mechanics previously impossible on mobile networks.
Market Restraints
- GRAC classification delays:South Korea's Game Rating and Administration Committee mandates 30-90 day review windows that stall simultaneous global launches and fragment tournament scheduling.
- Input cost volatility:Live-service infrastructure costs surge with concurrent player loads, squeezing margin on free-to-play titles during viral adoption spikes.
- Technical limitation:Touchscreen precision caps mechanical skill expression compared to mouse-keyboard inputs, limiting competitive legitimacy in hardcore PC-dominant markets.
Strategic Opportunities
- Underpenetrated geography:India's Tier-2 and Tier-3 cities present untapped demand as affordable 5G handsets penetrate below metro price points.
- Regulatory tailwind:Vietnam's Ministry of Information and Communications esports recognition framework legitimizes professional player visas and unlocks stadium infrastructure investment.
- Technology convergence:AI-driven dynamic difficulty adjustment and procedural content generation reduce live-ops staffing intensity for mid-tier publishers.
Industry Challenges
- Netcode engineering scarcity:Specialized talent for rollback synchronization and lag compensation commands premium compensation, constraining studio expansion.
- Anti-addiction compliance:China's real-name verification and youth time-limit enforcement require persistent identity infrastructure that fragments account systems across regulatory zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile MOBA Games Market |
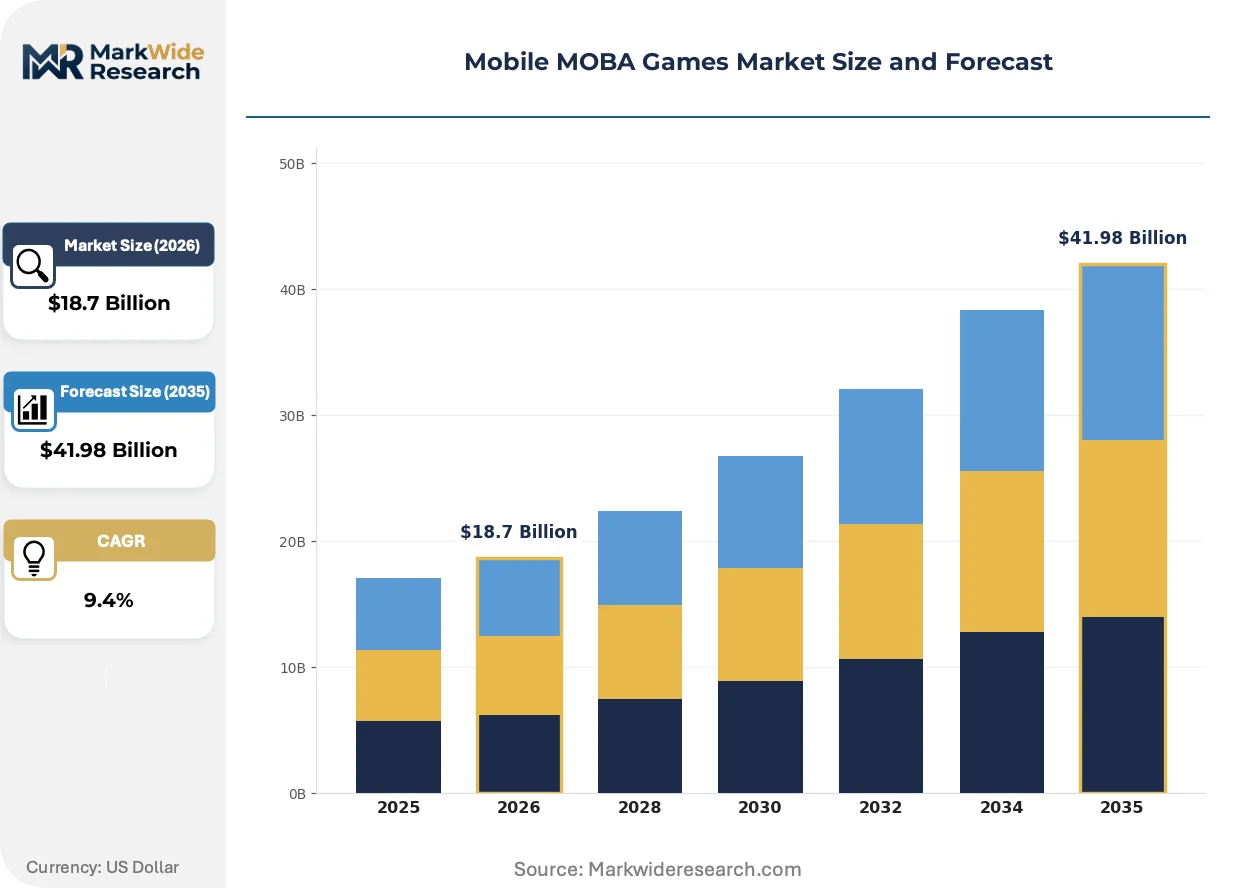
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Battle Arena, Hero Shooter, Strategy, Team-Based Player Base: Casual Gamers, Competitive Players, Esports Enthusiasts, Streamers Monetization Model: Free-to-Play, Subscription, In-App Purchases, Ad-Supported Platform: iOS, Android, Cross-Platform, Cloud Gaming |
| Companies Covered | Tencent Games, TiMi Studio Group, Moonton, Riot Games, NetEase, Garena, Supercell, FunPlus, VNG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile MOBA Games Market Trends and Innovations
Real-time rendering pipelines and AI-assisted matchmaking are collapsing the quality gap between mobile and PC competitive experiences. Publishers now prioritize engine efficiency over visual fidelity to sustain frame rates under thermal throttling.
Unified shader compilation across Metal, Vulkan, and OpenGL ES is unifying the technical foundation for cross-platform deployment. TiMi Studio Group and NetEase are consolidating engine teams around single-source asset pipelines that compile to multiple graphics APIs without manual porting. This compression of engineering overhead enables simultaneous feature parity across iOS, Android, and PC clients, eliminating the competitive disadvantage of delayed mobile updates.
GDPR age-verification mandates and China's MIIT youth protection rules are forcing publishers to rebuild account architectures around government-issued identity binding. The structural consequence is market bifurcation: compliant titles gain distribution access in regulated zones while non-compliant competitors face store delisting. European publishers are responding with privacy-preserving zero-knowledge proof systems that verify age without centralizing personal data.
Battle pass monetization is displacing gacha randomization as the dominant revenue architecture across Southeast Asian markets. Indonesian and Philippine players demonstrate higher lifetime value under predictable seasonal unlock models compared to probabilistic drop mechanics. This behavioral pivot rewards publishers with strong live-ops cadences and punishes those dependent on whale-dependent randomization economies, compressing competitive differentiation around content velocity rather than psychological manipulation design.
Mobile MOBA Games Market Segmentation
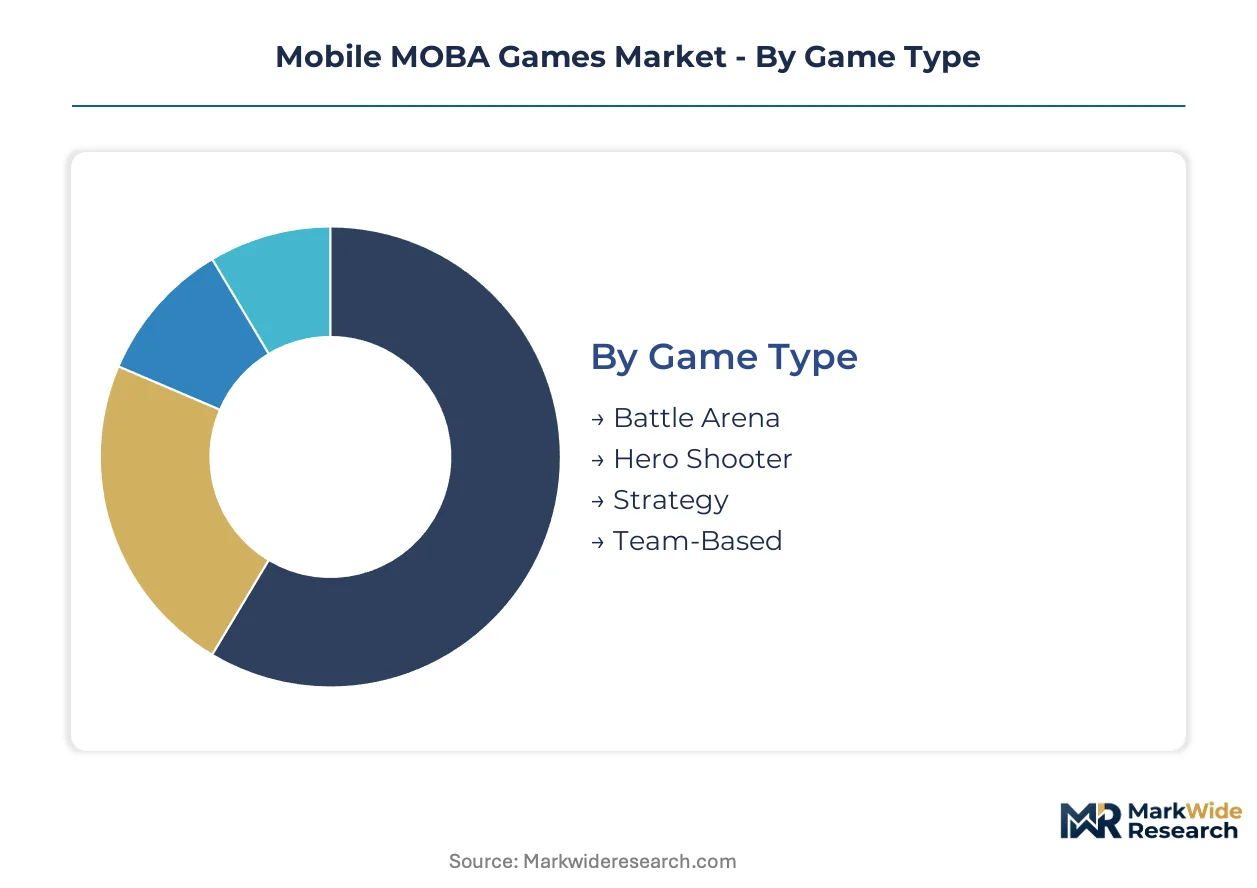
Mobile MOBA publishers calibrate product roadmaps around four intersecting dimensions that determine addressable audience, revenue architecture, and technical requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Game Type:
Technical specification defines the core loop complexity, match duration, and skill ceiling that attracts specific player psychographics.
- Battle Arena:Symmetrical 5v5 maps with three lanes and jungle objectives dominate download volumes across Indonesia and Brazil. Touch-optimized virtual joystick controls and 10-15 minute match durations align with fragmented smartphone leisure patterns.
- Hero Shooter:First-person perspective with ability-driven combat demands higher frame rate stability and precision aiming mechanics. Cloud gaming infrastructure in Southeast Asian urban clusters now renders this format viable on mid-tier handsets previously excluded.
- Strategy:Macro-focused resource management and base-building layers extend session lengths beyond 20 minutes. Appeals to aging PC strategy migrants seeking familiar depth on mobile.
- Team-Based:Objective-centric modes emphasizing coordination over individual mechanical skill. Lower barrier to entry attracts casual cohorts in Philippine and Vietnamese markets where social play motivation exceeds competitive drive.
Battle Arena leads on scale; Hero Shooter leads on momentum.
Player Base:
Engagement intensity and spending propensity stratify sharply across behavioral segments, forcing publishers to prioritize feature investment against lifetime value curves.
- Casual Gamers:Intermittent sessions under 30 minutes weekly, minimal competitive ranking interest. Monetization concentrates on impulse cosmetic purchases during limited-time events.
- Competitive Players:Daily ranked ladder participation with systematic skill improvement goals. Drives battle pass subscription velocity and seasonal content unlock rates in Latin American markets.
- Esports Enthusiasts:Tournament viewership and amateur competition participation create halo marketing effects. Indonesia's Ministry of Youth and Sports esports recognition framework legitimizes this cohort's professional pathway.
- Streamers:Content creators generating organic acquisition through platform distribution. Platform algorithm changes directly impact title virality and new player funnel efficiency.
Competitive Players generate deepest revenue per user; Streamers generate fastest user acquisition velocity.
Monetization Model:
Revenue architecture selection determines regulatory scrutiny intensity and player relationship durability across jurisdictions with divergent consumer protection frameworks.
- Free-to-Play:Zero entry barrier maximizes audience scale. China's MIIT youth protection rules restrict monetization depth for minor accounts, compressing whale-dependent economies.
- Subscription:Predictable recurring revenue through battle pass systems. Southeast Asian players demonstrate higher retention under seasonal unlock models versus probabilistic mechanics.
- In-App Purchases:Cosmetic skin sales and hero unlocks remain the dominant margin pool. South Korea's GRAC rating mandates disclosure of drop probabilities for randomized purchases.
- Ad-Supported:Rewarded video integration sustains engagement in price-sensitive Indian Tier-2 and Tier-3 markets. CPM rates fluctuate with platform privacy policy changes.
In-App Purchases anchor current revenue composition; Subscription models gain share fastest.
Platform:
Deployment target dictates engine optimization priorities, store policy compliance burdens, and addressable hardware spectrum.
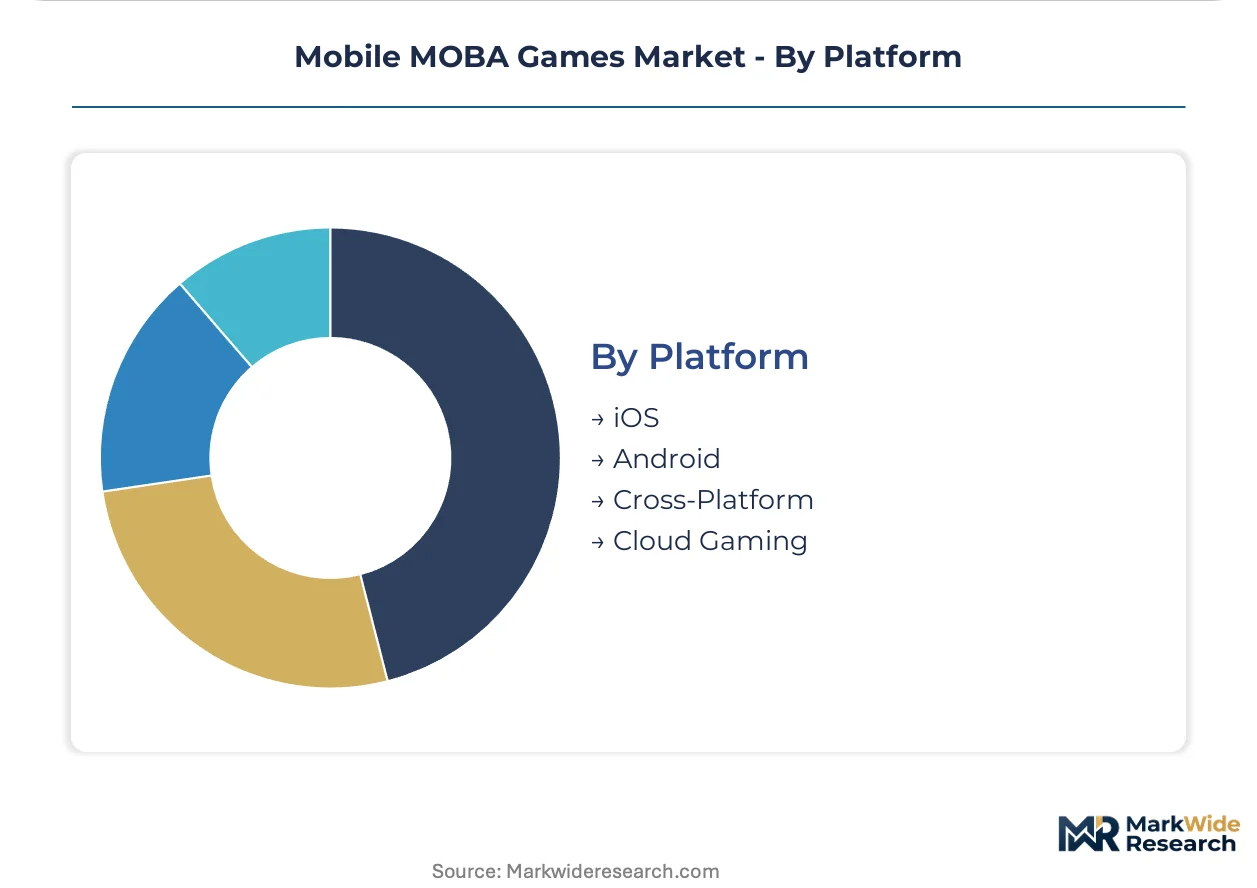
- iOS:Premium device owners with higher average revenue per user. Apple's App Store review guidelines and 30% commission structure shape feature release cadences.
- Android:Fragmented hardware ecosystem requiring extensive device-specific optimization. Google Play's billing system mandates create parallel compliance layers.
- Cross-Platform:Unified codebases across mobile and PC clients collapse development overhead. TiMi Studio Group's engine consolidation enables simultaneous feature parity.
- Cloud Gaming:Edge server infrastructure eliminates local hardware constraints. 5G densification in Brazilian and Indonesian urban corridors expands viable addressable audience.
Android leads on installed base; Cloud Gaming climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT approval velocity contrasts sharply with South Korea's GRAC review delays, creating divergent launch windows for identical titles. Publishers now sequence releases around regulatory throughput rather than marketing calendars.
China
NMPA green-channel prioritization accelerates competitive title approvals for Honor of Kings and Arena of Valor. MIIT youth gaming time restrictions compress monetization depth for minor accounts. Shenzhen's Tencent headquarters anchors cross-platform engine development teams optimizing WeChat ecosystem integration.
Indonesia
Mobile-first infrastructure and sub-$200 5G handset penetration drive battle arena dominance among 18-24 demographics. Ministry of Youth and Sports esports recognition legitimizes professional player visas. Jakarta's tournament infrastructure hosts MPL Indonesia, Southeast Asia's largest mobile MOBA circuit.
South Korea
GRAC's 30-90 day classification windows stall simultaneous global launches for titles targeting PC-mobile parity. High-speed fiber and 5G densification enable sub-10ms latency for skill-shot mechanics. Seoul's Pangyo Techno Valley clusters cloud gaming infrastructure providers serving real-time mobile esports.
Brazil
Cloud gaming edge servers eliminate flagship smartphone requirements for competitive play in São Paulo and Rio de Janeiro state clusters. ANVISA content classification operates faster than Asian counterparts. Localized Portuguese voice acting and carnival-themed cosmetic releases drive seasonal engagement spikes.
Vietnam
Ministry of Information and Communications esports framework unlocks stadium infrastructure investment in Ho Chi Minh City and Hanoi. 5G network rollouts in Da Nang and Hai Phong expand addressable audiences beyond metro centers. VNG Corporation's localized hero design pipeline competes directly with Chinese publishers for share.
Mobile MOBA Games Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated publishers commanding retention advantages over standalone studios. Market structure concentrates around three to five dominant platform holders with captive distribution. Strategic archetypes include ecosystem-anchored conglomerates, regional localization specialists, and cross-platform engine consolidators. Competitive moves center on regulatory pre-clearance investments and live-ops staffing scale rather than hardware differentiation.
Within the ecosystem-anchored tier, Tencent Games and TiMi Studio Group represent the dominant technical and distribution integration model. Moonton occupies a position exemplifying regional localization specialization through Southeast Asian tournament infrastructure and hero design adaptation. These three entities anchor the competitive spectrum from proprietary platform control to geographic niche dominance.
| Leading Market Players |
|---|
| Tencent Games |
| TiMi Studio Group |
| Moonton |
| Riot Games |
| NetEase |
| Garena |
| Supercell |
| FunPlus |
| VNG Corporation |
| Others |
Pricing and Supply Chain Analysis
Live-service infrastructure costs cascade from cloud compute provisioning through to player-facing subscription tiers, with Southeast Asian publishers absorbing edge server density investments to preserve free-to-play entry points while monetizing through cosmetic velocity in premium markets.
Pricing Analysis
Capacity additions in Indonesian cloud gaming clusters are reshaping price floors for competitive latency tiers. Battle pass subscription models dominate revenue architecture, with price differentiation resting on content velocity and exclusive skin rarity tiers. Pricing pressure stems from live-ops staffing intensity required to sustain seasonal unlock cadences. Casual gamers in Philippine and Vietnamese markets exhibit highest price sensitivity, while esports enthusiasts in Jakarta and São Paulo accept premium tiers for tournament access privileges.
Supply Chain Analysis
Refurbished device flows and secondhand smartphone refurbishment channels in India and Indonesia extend hardware lifecycles for price-sensitive battle arena players. Supply concentrates in Shenzhen for engine development, Ho Chi Minh City for localization pipelines, and Seoul for cloud infrastructure hardware. Raw material dependencies include semiconductor wafers from Taiwan, lithium-ion cells from South Korea, and rare earth components from China. Single-source vulnerability sits with TSMC advanced node allocation for flagship handset SOCs. Distribution runs through platform-holder app stores with 30% commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory pre-clearance investments create durable moats for compliant publishers while fragmenting account systems across youth protection jurisdictions.
For Market Incumbents: Hedge against GRAC classification delays by pre-positioning content assets for simultaneous multi-market submission. Defend retention advantages through WeChat and QQ ecosystem integration while accelerating cross-platform engine consolidation to collapse development overhead. Threat substitution from cloud gaming entrants demands persistent investment in netcode engineering talent pools. For New Entrants and Emerging Players: Begin with India's Tier-2 and Tier-3 cities where affordable 5G handset penetration outpaces established publisher localization. Target ad-supported monetization in price-sensitive segments before migrating proven cohorts to battle pass models. Go-to-market angle should leverage AI-driven dynamic difficulty adjustment to reduce live-ops staffing requirements against entrenched competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional localization specialists because tournament infrastructure and hero design adaptation create captive audiences resistant to platform-holder poaching. Five-to-ten year viability hinges on regulatory compliance architecture as market access velocity determines monetization ceilings. Acquisition target archetype: mid-tier studios with GRAC pre-clearance track records and Southeast Asian esports recognition frameworks. Signal to watch: MIIT green-channel approval velocity for competitive titles as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform Engine Consolidation | TiMi Studio Group's single-source asset pipelines collapse fragmentation between iOS, Android, and PC clients. |
| Regulatory Pre-Clearance Investment | GRAC and MIIT submission positioning accelerates market access velocity against delayed competitors. |
| Cloud Gaming Infrastructure Expansion | Edge server density in Indonesian and Brazilian urban corridors eliminates flagship smartphone barriers. |
| AI-Driven Live-Ops Automation | Procedural content generation reduces staffing intensity for mid-tier publishers competing on content velocity. |
| Esports Recognition Framework Lobbying | Vietnam's Ministry of Information and Communications legitimization unlocks stadium infrastructure investment. |
Research Methodology
Multiple input streams — publisher financial disclosures, platform-holder commission structure filings, and regional esports tournament viewership data — were reconciled against primary interviews with live-ops directors, cloud infrastructure procurement leads, and GRAC regulatory consultants. Secondary validation drew from MIIT content approval databases, NMPA green-channel priority listings, and Southeast Asian telecommunications capex reports. Bottom-up triangulation across individual title revenue estimates and top-down market sizing from platform aggregate disclosures anchored value projections.
Data-stream reconciliation applied analytical frameworks across game type, player base intensity, monetization model, and platform deployment dimensions. CAGRs derived from regression analysis of historical title lifecycle curves and forward projection of 5G handset penetration curves. Industry-specific inputs included cloud gaming latency threshold modeling and battle pass subscription renewal rate assumptions by geographic cluster.
Several conditions sit outside the modeled scope, including unannounced MIIT youth protection rule revisions and platform-holder commission structure changes. Forecasts reflect documented assumptions about regulatory throughput stability and hardware cost compression trajectories. Practitioners should monitor GRAC review window extensions and edge server deployment announcements in Indian Tier-2 cities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Racing Games Market
Gaming
Serious Games Market
Gaming
Mobile Game Controller Market
Gaming
Global Online Simulation Games Market
Gaming
Playstation Network (PSN) Market
Gaming
Puzzle Video Game Market
Gaming
China Gaming Headsets Market
Gaming
Mobile Game Software Market
Gaming
Social Gaming Market
Gaming
RPG Games Market
Gaming
Videogames Market
Gaming
VR Melee Games Market
Gaming
Game Engine Management Market
Gaming
Gaming Peripheral Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Animation, VFX & Game Market