
 Racing Games Market | 2026-2036
Racing Games Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Games Market Outlook
ESRB age rating certification is bifurcating market access between family-friendly arcade titles and mature simulation franchises. Electronic Arts Inc. leverages its EA Sports portfolio to sustain year-over-year engagement through licensed motorsport IP. Sony Interactive Entertainment LLC dominates exclusive first-party racing content on PlayStation platforms. Codemasters Software Company Limited specializes in premium simulation mechanics that anchor its reputation among enthusiast communities.
Racing games constitute interactive software products rendering real-time vehicle physics, track environments, and competitive timing systems across digital distribution channels. These titles employ proprietary physics engines processing tire grip coefficients, aerodynamic downforce, and surface friction parameters to replicate operational vehicle behavior. Simulation Racing commands premium pricing through hardware ecosystem integration, while Mobile platforms capture volume through Free-to-Play monetization with In-Game Purchases funding development cycles. Cloud Gaming represents the fastest-growing delivery vector as latency reduction expands addressable audiences beyond console ownership.
The ESRB in the United States, PEGI across European markets, and CERO in Japan enforce age-appropriate content classification that shapes marketing reach and platform distribution agreements. China's NPPA approval requirements further gate commercial release timelines for international publishers seeking access. Stakeholders must monitor evolving platform commission structures and regional content compliance timelines as determinants of profitable geographic expansion.
Market Dynamics
Cloud gaming infrastructure is compressing hardware barriers to entry, expanding addressable audiences beyond traditional console ownership while reshaping revenue distribution between platform operators and publishers.
Growth Catalysts
- Cross-platform play standards:Unified multiplayer frameworks eliminate ecosystem silos, enabling PlayStation, Xbox, and PC communities to compete within shared lobbies. This interoperability extends player retention curves and reduces churn across hardware generations.
- Free-to-Play monetization:Mobile platforms deploy battle pass systems and cosmetic microtransactions to fund continuous content pipelines without upfront purchase friction. This model captures volume in emerging markets where premium pricing faces resistance.
- Hardware ecosystem integration:Direct-drive wheel bases and load-cell pedal systems from Fanatec and Thrustmaster deepen simulation authenticity. Enthusiast communities invest in peripheral ecosystems that lock in franchise loyalty through proprietary mounting standards and force feedback protocols.
Market Restraints
- Latency physics in cloud delivery:Input lag thresholds above 50 milliseconds degrade competitive timing precision in online multiplayer formats. Network infrastructure disparities between urban fiber deployments and rural broadband create uneven experience quality.
- Licensed IP concentration:Motorsport federation agreements with Formula 1, WRC, and NASCAR concentrate authentic vehicle and track content within a handful of publisher portfolios. Independent developers face exclusion from premium simulation segments without multi-year licensing investments.
- Regional content approval timelines:China's NPPA review processes extend commercial release windows by 6-18 months for international titles. Publishers must maintain separate build branches to accommodate censorship requirements for violence and political content.
Strategic Opportunities
- India's underpenetrated console base:Mobile-first gaming culture creates whitespace for cloud streaming services to deliver premium racing experiences without hardware ownership. Local payment integration and regional server deployment address infrastructure gaps.
- Esports tournament infrastructure:FIA-certified virtual motorsport championships attract automotive manufacturer sponsorship and broadcast licensing. This convergence of physical and digital motorsport builds endemic advertising inventory unavailable in traditional gaming verticals.
- Automotive OEM co-development:Vehicle manufacturers seek digital showrooms and configurators within racing titles to engage pre-purchase consideration audiences. Porsche, BMW, and Mercedes-Benz embed unreleased concept vehicles in simulation franchises for market testing.
Industry Challenges
- Physics engine talent scarcity:Specialized expertise in tire thermodynamics, suspension kinematics, and aerodynamic simulation commands premium compensation. Studios compete for graduates from automotive engineering programs rather than conventional computer science pipelines.
- Multi-platform certification complexity:Separate technical compliance requirements for Sony, Microsoft, Nintendo, Apple, and Google storefronts multiply QA overhead. Day-one patch cycles strain release management resources across divergent hardware specifications.
- Live service operational demands:Continuous content calendars require dedicated server infrastructure, anti-cheat maintenance, and community management at scale. Player expectation for seasonal updates compresses development cycles and burns out creative teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Games Market |
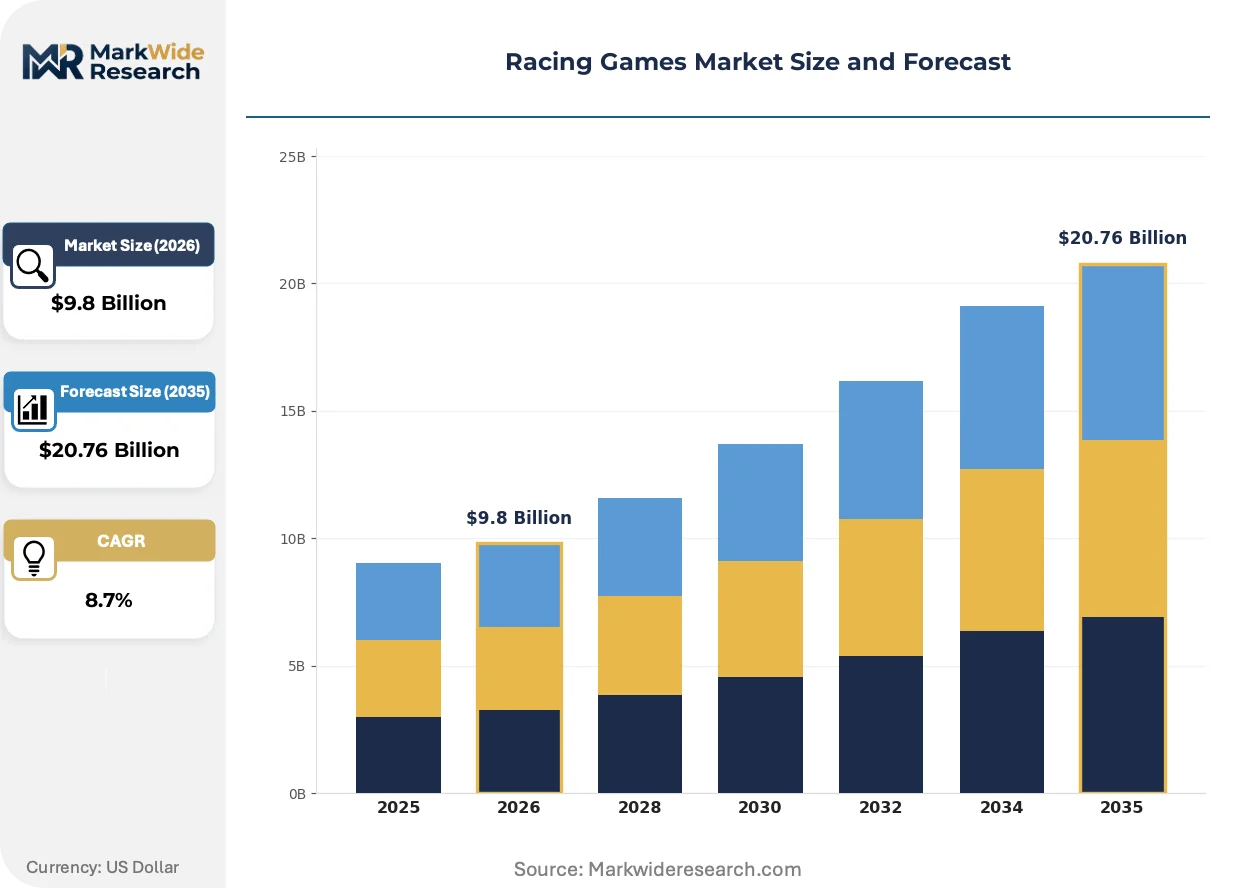
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Arcade Racing, Simulation Racing, Kart Racing, Rally Racing, Drag Racing Platform: Console, PC, Mobile, Cloud Gaming, Handheld Devices Monetization Model: Free-to-Play, Premium Purchase, Subscription-Based, In-Game Purchases, Advertisements Player Mode: Single Player, Multiplayer, Online Multiplayer, Local Co-op, Competitive eSports |
| Companies Covered | Electronic Arts Inc., Microsoft Corporation, Sony Interactive Entertainment LLC, Ubisoft Entertainment SA, Codemasters Software Company Limited, THQ Nordic GmbH, Gameloft SE, Take-Two Interactive Software, Inc., Tencent Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Games Market Strategic Shifts
Real-time ray tracing and AI-assisted upscaling are redefining visual fidelity benchmarks, while subscription bundling reshapes how players discover and commit to racing franchises across device categories.
Haptic feedback systems are miniaturizing from dedicated cockpit rigs into standard controller form factors. Sony's DualSense adaptive triggers and immersive vibration patterns transmit surface texture and traction loss through handheld interfaces. This democratization of tactile feedback compresses the authenticity gap between casual and enthusiast hardware tiers, enabling simulation-curious players to experiment without peripheral investment.
REACH chemical substance restrictions in the European Union are pressuring peripheral manufacturers to reformulate rubber compounds in racing wheels and pedal pads. Suppliers must document SVHC compliance across supply chains to maintain CE marking eligibility. German and French distributors now require full material disclosure for electronics accessories, affecting production timelines for Thrustmaster and Logitech G accessory lines.
Subscription bundling through Xbox Game Pass and PlayStation Plus Extra is displacing individual title purchases among discovery-oriented players. This procurement shift concentrates attention on launch window performance and day-one multiplayer population health. Japanese and South Korean markets exhibit the highest attachment rates for racing content within multi-genre subscription catalogs, driving publishers to prioritize service integration over standalone retail strategy.
Racing Games Market Segmentation
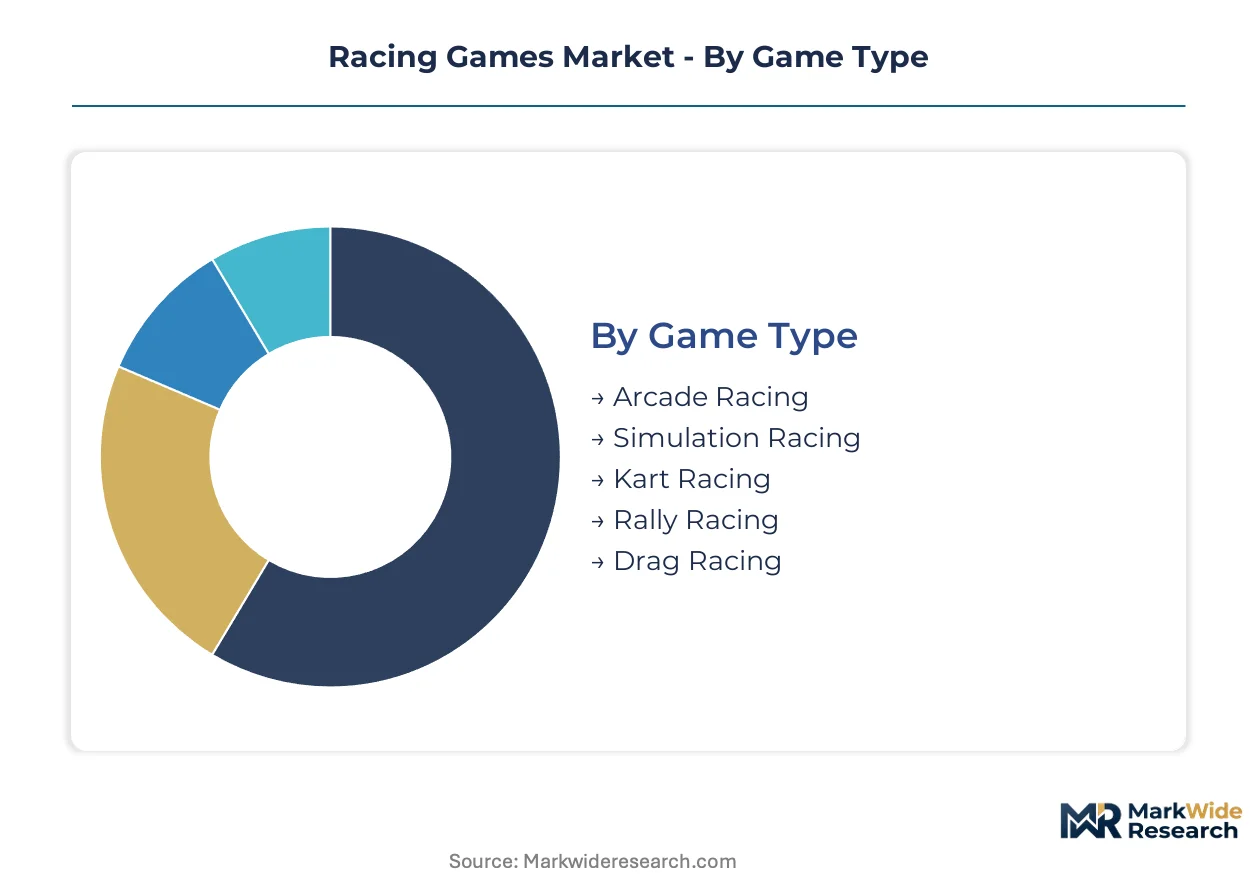
Segmentation in racing games determines hardware compatibility, content rating pathways, and monetization viability across distinct player communities. Each dimension carries regulatory and commercial implications that shape publisher resource allocation and geographic prioritization.
Game Type:
ESRB, PEGI, and CERO age classifications diverge sharply between arcade accessibility and simulation authenticity, dictating marketing channels and platform placement.
- Arcade Racing:Simplified physics models prioritize immediate accessibility and spectacle over mechanical fidelity. Demand concentrates in family-oriented households across the United States and Japan, where ESRB "Everyone" and CERO "A" ratings unlock mass retail distribution and platform feature placement.
- Simulation Racing:Proprietary tire thermodynamics and aerodynamic modeling replicate operational vehicle behavior at computational cost. Enthusiast communities in Germany and the United Kingdom drive hardware ecosystem investment, with KBA-recognized motorsport federations validating telemetry accuracy for esports certification.
- Kart Racing:Character-driven aesthetics and weapon-based mechanics attract younger demographics within PEGI "3" and "7" brackets.
- Rally Racing:Surface degradation physics and procedural stage generation serve niche endurance communities.
- Drag Racing:Straight-line acceleration timing and tuning depth appeal to automotive aftermarket enthusiasts.
Arcade Racing handles the majority of throughput; Simulation Racing is expanding most quickly on share.
Platform:
Cost tier stratification separates premium hardware ownership from frictionless access, reshaping revenue distribution and development prioritization.
- Console:Proprietary SDKs and certification pipelines from Sony, Microsoft, and Nintendo enforce technical compliance standards. First-party exclusivity agreements concentrate flagship simulation franchises on PlayStation and Xbox ecosystems, with Japan and the United States representing primary revenue concentration.
- Mobile:ARM-based chipsets and touch interfaces constrain physics complexity while enabling mass distribution. Free-to-Play monetization captures volume in India and Brazil, where premium console pricing faces resistance and local payment integration addresses banking infrastructure gaps.
- PC:Open hardware standards and modding communities sustain enthusiast longevity beyond console generations.
- Cloud Gaming:Latency-dependent streaming infrastructure is climbing the fastest as fiber deployment expands addressable audiences beyond hardware ownership.
- Handheld Devices:Nintendo Switch and emerging Steam Deck formats bridge portability with physical control fidelity.
Console maintains installed base dominance; Cloud Gaming is gaining share fastest on trajectory steepness.
Monetization Model:
Customer type segmentation separates upfront commitment from ongoing engagement, with regulatory scrutiny intensifying on randomized reward mechanics.
- Free-to-Play:Zero entry friction funded by cosmetic microtransactions and battle pass systems. Mobile-first emerging markets in Southeast Asia and Latin America concentrate volume, though China's NPPA approval requirements gate build branch maintenance for international publishers.
- Premium Purchase:Full upfront pricing sustains simulation franchises with dedicated hardware integration. Core enthusiast bases in Germany, the United Kingdom, and Australia absorb premium pricing for licensed motorsport authenticity.
- Subscription-Based:Xbox Game Pass and PlayStation Plus Extra integration displaces individual purchases among discovery-oriented players.
- In-Game Purchases:Itemized content unlocks face FTC and EU consumer protection scrutiny on disclosure transparency.
- Advertisements:Rewarded video placement funds casual tier development without direct player expenditure.
Free-to-Play commands player volume; Subscription-Based is climbing fastest on attach rate expansion.
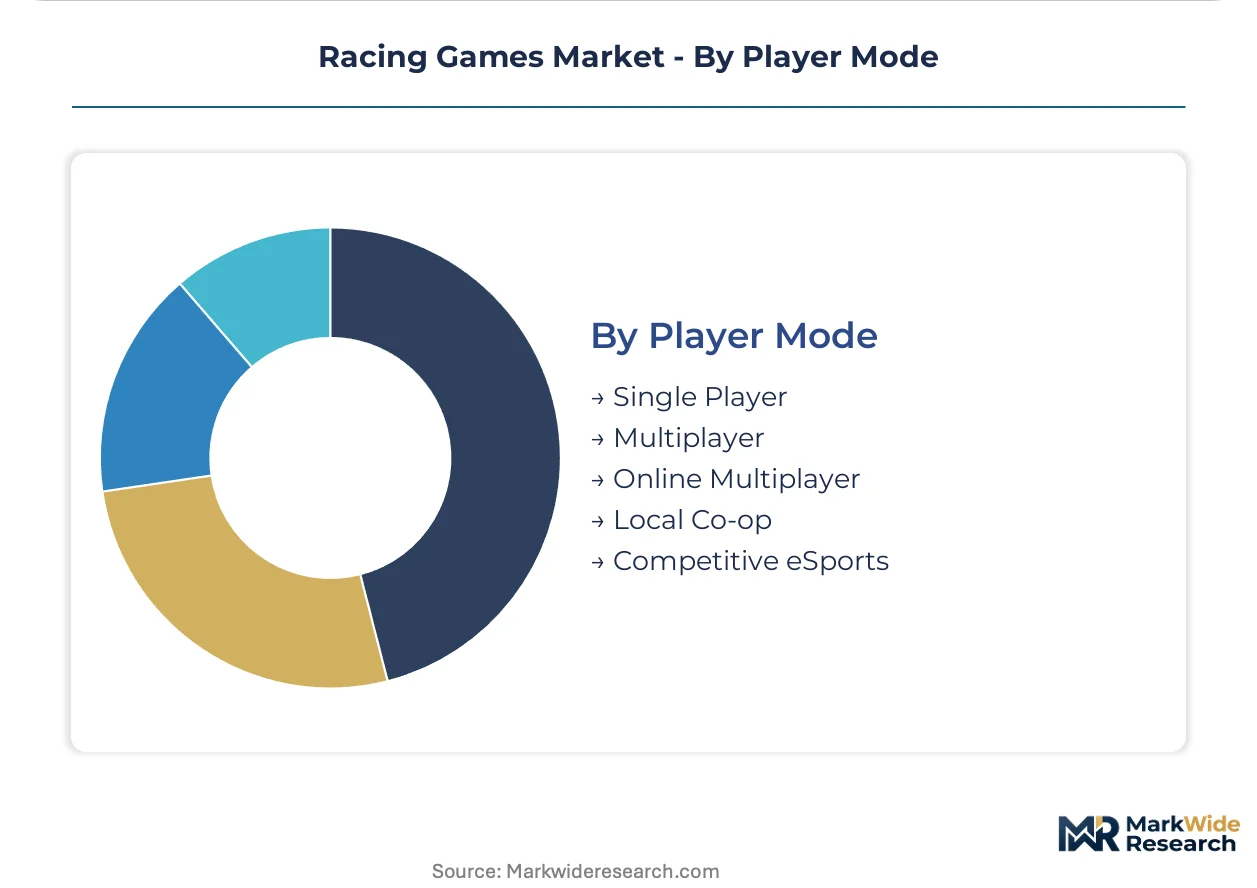
Player Mode:
Application context determines server infrastructure investment, anti-cheat rigor, and broadcast licensing potential across engagement depths.
- Online Multiplayer:Persistent server architecture and matchmaking algorithms sustain competitive population health. Cross-platform play standards from Sony, Microsoft, and Nintendo unify fragmented ecosystems, with the United States and South Korea exhibiting highest concurrent user density.
- Competitive eSports:FIA-certified tournament infrastructure attracts automotive OEM sponsorship and endemic advertising inventory. Broadcast licensing convergence with physical motorsport concentrates in Germany, Japan, and the United Kingdom.
- Single Player:Campaign narratives and AI opponent calibration serve narrative-driven discovery.
- Local Co-op:Split-screen and LAN configurations persist in emerging markets with inconsistent broadband reliability.
- Multiplayer:Hybrid online-offline frameworks accommodate infrastructure heterogeneity.
Online Multiplayer sustains daily active user bases; Competitive eSports shows steepest expansion trajectory on sponsorship inflow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Console and PC gaming communities in the United States, Japan, and Germany concentrate purchasing power for premium racing franchises. Mobile-first audiences in India and Brazil absorb free-to-play volume. Cloud gaming infrastructure expansion in South Korea and the United Kingdom reshapes addressable market boundaries beyond hardware ownership.
United States
ESRB age rating certification shapes marketing reach and platform distribution agreements for family-friendly arcade titles versus mature simulation franchises. The FTC monitors in-game purchase disclosure transparency and consumer protection in microtransaction mechanics. California and Washington State clusters house platform operators and major publisher headquarters driving cross-platform play standardization.
Japan
CERO content classification enforces age-appropriate distribution while PlayStation-first-party exclusivity concentrates flagship simulation franchises. METI industrial policy supports esports tournament infrastructure and virtual motorsport certification. Tokyo and Osaka metropolitan areas anchor developer talent pools specializing in proprietary physics engine architecture.
Germany
KBA-recognized motorsport federations validate telemetry accuracy for esports certification and enthusiast hardware ecosystem investment. REACH chemical substance restrictions pressure peripheral manufacturers to reformulate rubber compounds in racing wheels. Bavaria and Baden-Württemberg automotive engineering clusters supply physics simulation talent to Codemasters and specialized studios.
China
NPPA approval requirements extend commercial release windows by 6-18 months for international publishers seeking access to mobile and PC distribution. SAMR market regulation scrutinizes randomized reward mechanics and battle pass monetization structures. Shenzhen and Shanghai development hubs serve domestic publishers like Tencent adapting build branches for censorship compliance.
United Kingdom
PEGI age classifications across European markets diverge between arcade accessibility and simulation authenticity. The Competition and Markets Authority examines platform commission structures and subscription bundling practices. Cambridge and Guildford technology corridors host Codemasters and specialized simulation studios leveraging proximity to Silverstone motorsport infrastructure.
Racing Games Market Competitive Environment
Player mix skews toward integrated platform-publishers with exclusive content libraries and licensed motorsport IP portfolios. Market structure concentrates around first-party hardware-software ecosystems and multi-year federation licensing agreements. Strategic archetypes include platform-exclusive content holders, licensed motorsport specialists, and mobile-first free-to-play operators. Competitive moves center on exclusive IP acquisition and cloud infrastructure partnerships to compress latency thresholds.
Within the licensed motorsport specialist tier, Codemasters Software Company Limited and Electronic Arts Inc. exemplify premium simulation authenticity through multi-year Formula 1 and WRC federation agreements. Sony Interactive Entertainment LLC anchors the platform-exclusive archetype with first-party PlayStation racing franchises. Tencent Holdings Limited occupies the mobile-first position, leveraging domestic market scale and NPPA-compliant build branch expertise for free-to-play distribution in emerging markets.
| Leading Market Players |
|---|
| Electronic Arts Inc. |
| Microsoft Corporation |
| Sony Interactive Entertainment LLC |
| Ubisoft Entertainment SA |
| Codemasters Software Company Limited |
| THQ Nordic GmbH |
| Gameloft SE |
| Take-Two Interactive Software, Inc. |
| Tencent Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at cloud gaming data centers in the United States and South Korea compresses per-stream delivery costs while establishing price floors for premium simulation tiers. Scale economies in fiber infrastructure deployment reshape both supply concentration among platform operators and the pricing power available to licensed IP holders.
Pricing Analysis
Cost-plus contracts with cloud infrastructure providers index compute pricing to energy and bandwidth benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates full-fidelity simulation with hardware integration from cloud-streamed access and mobile ad-supported tiers. Pricing pressure stems from subscription bundling through Xbox Game Pass and PlayStation Plus Extra displacing standalone purchases. Mobile-first audiences in India and Brazil exhibit highest price sensitivity, while German and Japanese enthusiast communities absorb premium pricing for KBA-recognized telemetry accuracy.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for GPU and ARM-based chipsets powering physics engines and cloud encoding. Japan and Germany supply precision force-feedback motors and load-cell sensors for peripheral ecosystems. Rare earth magnet sourcing from Chinese processors creates single-source vulnerability for direct-drive wheel torque systems. Distribution runs through platform storefronts with 30% commission structures, though cloud streaming introduces direct publisher-subscriber relationships bypassing hardware retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming infrastructure expansion represents an early-cycle penetration story, with latency reduction below 20 milliseconds unlocking addressable audiences beyond console ownership thresholds.
For Market Incumbents: Secure exclusive federation licensing agreements with Formula 1, WRC, and NASCAR before renewal windows concentrate remaining authentic motorsport IP. Build captive cloud server capacity in Mumbai and São Paulo to preempt emerging platform competition. Vertical integration into haptic feedback controller manufacturing hedges REACH compliance costs for European peripheral distribution.
For New Entrants and Emerging Players: Esports tournament infrastructure gaps in India and Southeast Asia offer white-space entry points where incumbents under-serve local competitive communities. Target mobile-first free-to-play distribution with regional payment integration addressing banking infrastructure gaps. Pursue automotive OEM co-development partnerships for digital showroom placement ahead of vehicle launch cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors physics engine specialists with automotive engineering talent pipelines over content-agnostic platform operators. Five-to-ten-year viability hinges on cloud infrastructure cost curves and cross-platform standardization adoption rates. Monitor FIA-certified virtual motorsport championship viewership metrics as inflection indicators for endemic advertising inventory expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Motorsport IP Acquisition | Multi-year federation agreements with Formula 1 concentrate authentic vehicle and track content within publisher portfolios. |
| Cloud Infrastructure Partnership | Latency reduction below 20 milliseconds expands addressable audiences beyond traditional console ownership in fiber-deployed markets. |
| Automotive OEM Co-Development | Porsche and BMW embed unreleased concept vehicles in simulation franchises for digital showroom engagement and market testing. |
| Esports Tournament Certification | FIA-certified virtual motorsport championships attract automotive manufacturer sponsorship unavailable in traditional gaming verticals. |
| Peripheral Ecosystem Integration | Proprietary mounting standards and force feedback protocols from Fanatec and Thrustmaster lock in franchise loyalty through hardware investment. |
Study Parameters
The analysis maps arcade racing, simulation racing, and cloud gaming delivery sub-sectors, each validated through game development executives, platform engineering leads, and esports tournament operators. Primary interviews with physics engine architects, licensed IP negotiators, and peripheral manufacturing procurement heads combined with secondary validation from SEC filings, platform SDK documentation, and federation licensing disclosures. Bottom-up title-level revenue modeling and top-down market sizing triangulate volume estimates across the analysis window.
Consistency checks against hyperscaler cloud gaming capex disclosures and console hardware shipment databases validated projection outputs. The analytical framework segments by game type, platform, monetization model, and player mode across the projection horizon, with CAGRs derived from hardware adoption curves and subscription attach rate trajectories. Cloud infrastructure latency benchmarks and NPPA approval timeline distributions served as industry-specific forecast inputs.
Underlying assumptions cover fiber deployment pace in target markets, with deviation risk concentrated in regulatory approval delays and licensed IP renewal negotiations. Forecasts reflect these documented conditions. Recalibration cycles align with material shifts in cross-platform play standardization and cloud gaming subscriber growth metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Europe Serious Gaming Market
Gaming
Mobile Game Controller Market
Gaming
Russia in-Game Advertising Market
Gaming
China Casino Tourism Market
Gaming
Gaming Gadgets Market
Gaming
Australia Gaming Gadgets Market
Gaming
Africa Gaming Market
Gaming
VR Racing Gaming Market
Gaming
Videogames Market
Gaming
Social Gaming Market
Gaming
Europe Video Game Software Market
Gaming
Connected Game Console Market
Gaming
Latin America Mobile Gaming Market
Gaming
Serious Games Market
Gaming
Gaming Hardware Market
Gaming
North America Gaming Hardware and Accessories Market