
 LED Stadium Screens Market | 2026-2036
LED Stadium Screens Market Size, Share, and Industry Trends Forecast 2026-2036
LED Stadium Screens Market Outlook
Professional sports franchises is reorganizing procurement priorities around immersive fan experience rather than static information display. Daktronics anchors North American manufacturing scale for venue-integrated LED systems. Leyard leverages vertical integration across LED chip packaging and module assembly. Samsung competes through direct-view LED technology leadership in premium center-hung applications.
LED stadium screens are large-format direct-view display systems built from modular LED cabinets with pixel pitches typically ranging from 2.5mm to 20mm, engineered for outdoor durability, high brightness, and seamless scalability to dimensions exceeding 1,000 square meters. Their primary commercial purpose is to deliver live video replay, sponsorship content, and real-time data visualization to mass audiences in outdoor and indoor athletic venues. Fixed installations dominate revenue volume as permanent venue infrastructure, while transparent LED configurations represent the fastest-growing product type for architectural integration where sightline preservation matters. Mini-LED backlighting technology commands premium positioning in close-viewing applications such as courtside ribbon boards and tunnel displays.
FCC equipment authorization requirements govern RF emissions from wireless content distribution systems embedded in U.S. stadium screens, while OSHA fall-protection standards shape installation labor costs and contractor qualification for elevated rigging work. CE marking under EU electromagnetic compatibility directives controls market access for European venue projects, with RoHS material restrictions affecting LED module solder and phosphor compositions. Stakeholders must monitor evolving energy-efficiency thresholds from EPA ENERGY STAR and corresponding state-level rebate programs that increasingly influence municipal procurement decisions for publicly financed venues.
Market Dynamics
Professional sports franchises are reorganizing procurement priorities around immersive fan experience rather than static information display, compressing replacement cycles for legacy scoreboard systems and elevating specification requirements for pixel density, brightness uniformity, and content synchronization capabilities.
Growth Catalysts
- Perimeter LED Ribbon Boards:NCAA and NFL venues are mandating continuous digital ribbon installations to maximize sponsorship inventory and real-time statistics display.
- China GB Standards:Tightening electronic display safety and energy efficiency regulations are accelerating product refresh cycles as venues replace non-compliant legacy installations.
- Mini-LED Backlighting:Courtside and tunnel display applications are adopting fine-pitch modules for close-viewing clarity, creating premium specification tiers.
Market Restraints
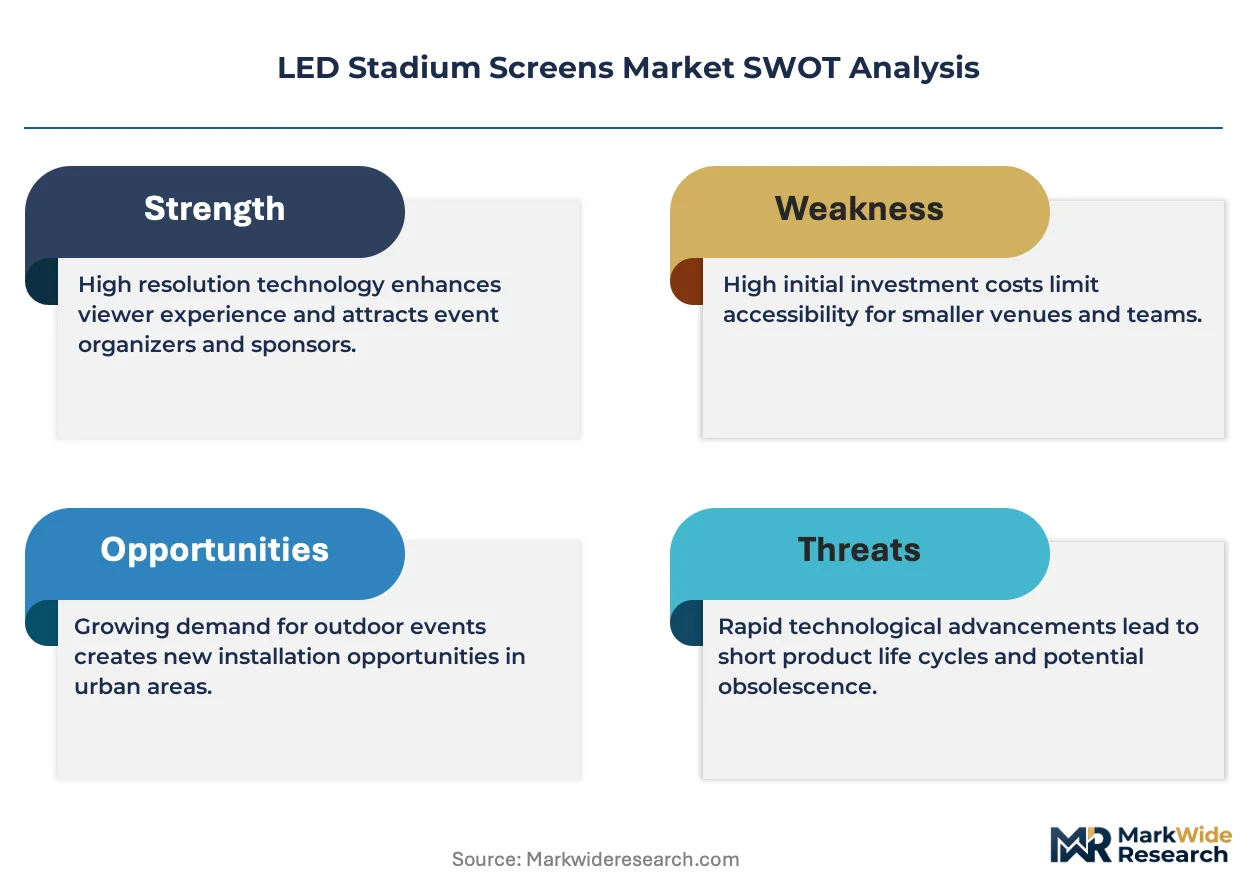
- Indium and Gallium Supply Concentration:LED chip phosphor materials face input cost volatility from concentrated rare earth processing capacity in China.
- Installation Labor Qualification:OSHA fall-protection standards for elevated rigging work constrain qualified contractor availability and extend project timelines.
- Projection Mapping Substitutes:Some indoor venues are evaluating laser projection systems for temporary or seasonal display needs, pressuring fixed LED commitments.
Strategic Opportunities
- Transparent LED Configurations:Architectural integration where sightline preservation matters is opening stadium facade and atrium applications previously unsuitable for solid displays.
- EPA ENERGY STAR Thresholds:Evolving efficiency benchmarks and corresponding state-level rebate programs are influencing municipal procurement decisions for publicly financed venues.
- 5G Content Distribution:Wireless broadcast infrastructure convergence is enabling real-time fan mobile interaction with center-hung displays, creating new sponsorship activation layers.
Industry Challenges
- RF Engineering Talent Gap:FCC equipment authorization requirements for embedded wireless systems demand specialized electromagnetic compatibility expertise that installation contractors struggle to source.
- Legacy Control System Integration:New LED installations must synchronize with existing venue automation, scorekeeping, and emergency alert networks, complicating commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Stadium Screens Market |
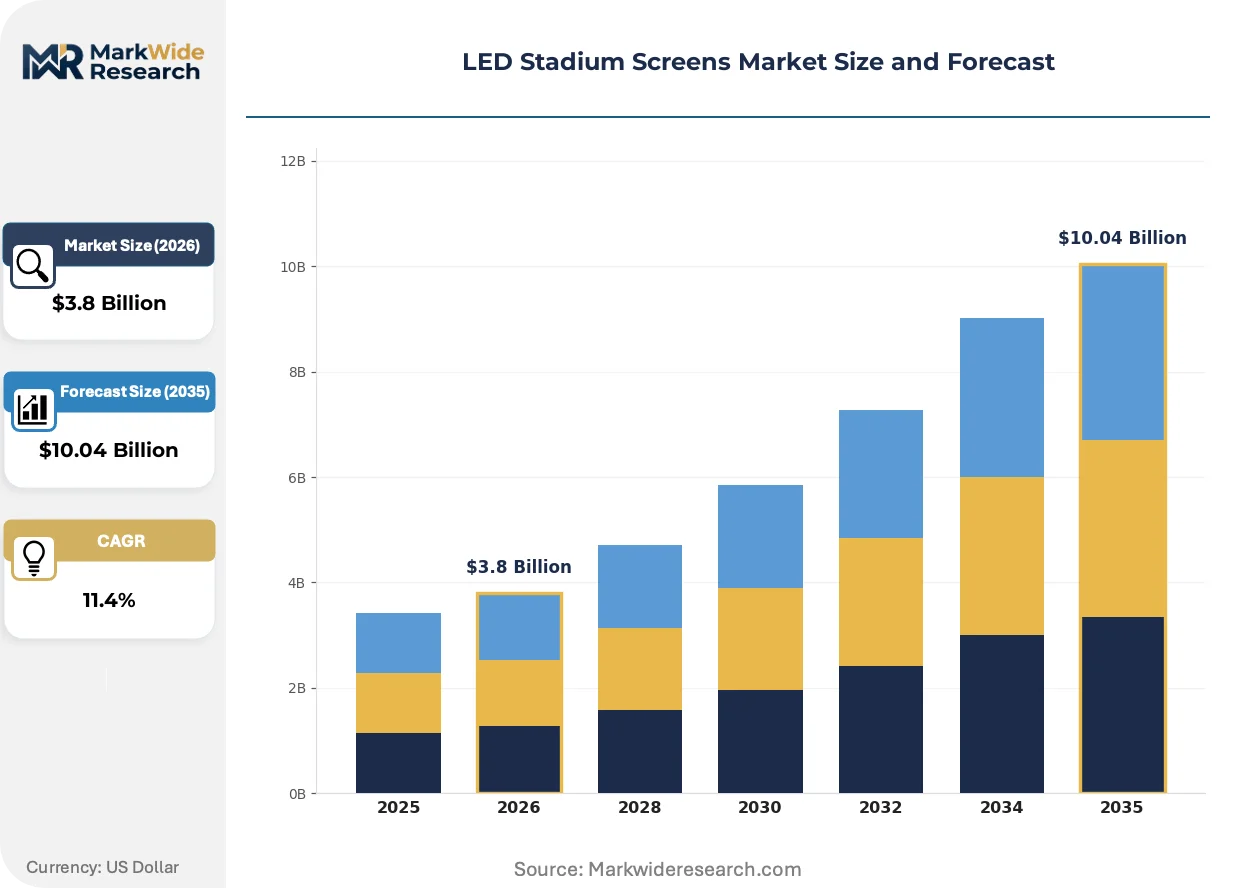
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Mobile, Transparent, Interactive Technology: OLED, Mini-LED, QLED, Direct View Application: Sports Events, Concerts, Advertising, Public Announcements End User: Stadiums, Arenas, Theme Parks, Educational Institutions |
| Companies Covered | Leyard, LG Electronics, Daktronics, INFiLED, Barco, Unilumin Group, Samsung, Planar Systems, Absen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Stadium Screens Market Strategic Shifts
Display technology evolution and regulatory pressure are compressing product lifecycles while fan experience expectations accelerate specification thresholds for brightness, refresh rates, and seamless content choreography across multiple screen surfaces.
Fine-pitch direct-view LED modules in the sub-4mm pixel pitch range are displacing traditional center-hung projection cubes and older 10mm+ LED installations in premium venue applications. Professional basketball and hockey franchises are specifying these configurations for courtside visibility. The structural consequence is a bifurcation between premium immersive venues and cost-constrained facilities maintaining legacy refresh cycles.
EU RoHS material restrictions are reshaping LED module supply chains by restricting lead solder and specific phosphor compositions in components bound for European venue projects. Manufacturers are reformulating surface-mount device assemblies and requalifying supplier bases. Sports venues in Germany, France, and the United Kingdom face extended procurement timelines as certification documentation requirements expand.
Leasing and service-based acquisition models are gaining traction among municipal venue authorities seeking to transfer obsolescence risk and align payments with event revenue generation. Traditional capital purchase arrangements are losing share to performance-guaranteed installations with bundled maintenance and content management. This shift is most visible in United States college athletic conferences where public university procurement offices face constrained debt capacity.
LED Stadium Screens Market Segmentation
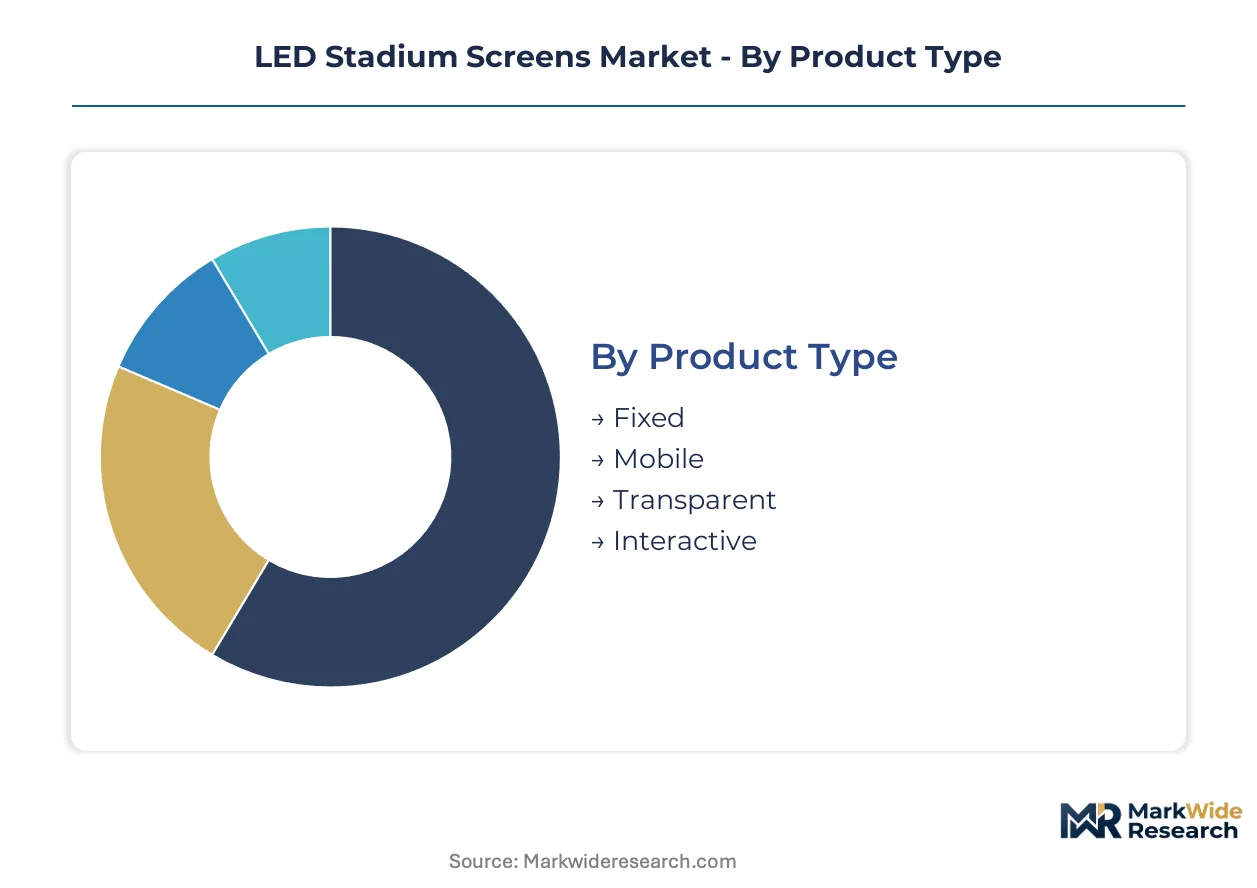
LED stadium screens fragment across four critical dimensions. Procurement channels diverge sharply between permanent venue infrastructure and temporary event rentals. Technology choices cascade into installation complexity and regulatory compliance requirements.
Product Type:
Channel mix splits between capital-intensive fixed installations and event-service mobile fleets, with architectural integration opening specialty routes.
- Fixed:Modular LED cabinets engineered for permanent mounting on stadium superstructures, center-hung catenary systems, and perimeter fascia. NFL and NCAA venues in the United States drive specification intensity for seamless video walls exceeding 1,000 square meters with 24/7 operational duty cycles.
- Transparent:Mesh LED configurations preserving sightlines through facade glass and atrium structures. Municipal venue authorities in Germany and France are specifying these for heritage building retrofits where solid displays violate preservation codes.
- Mobile:Trailer-mounted and modular ground-stack systems deployed for temporary events and seasonal venues. Rental fleet operators in the United Kingdom maintain these for festival circuits.
- Interactive:Touch-enabled and sensor-integrated displays for fan engagement zones. Theme park operators in Japan deploy these for gamified queue entertainment.
Fixed installations dominate installed base. Transparent configurations are where expansion concentrates.
Technology:
Cost tiers separate premium direct-view systems from value-positioned alternatives, with thermal management and pixel density driving specification divergence.
- Direct View:Fine-pitch LED modules with pixel densities below 4mm enabling close-viewing clarity without projection artifacts. Professional basketball and hockey franchises specify these for courtside ribbon boards where spectators sit within ten meters of the display surface.
- Mini-LED:Thousands of localized dimming zones delivering contrast ratios exceeding 1,000,000:1 for HDR content reproduction. Premium center-hung applications in Saudi Arabia and UAE venues adopt these for daylight visibility in desert climates.
- OLED:Self-emissive organic panels limited to indoor arena applications by brightness constraints and burn-in susceptibility. Concise indoor venues in South Korea deploy these for luxury suite entertainment.
- QLED:Quantum dot-enhanced LCD alternatives competing on cost for secondary display locations. Educational institutions in India specify these for budget-constrained gymnasium installations.
Direct View commands revenue concentration. Mini-LED is climbing the fastest.
Application:
Customer type stratification separates professional sports franchises with dedicated capital budgets from event promoters with variable revenue exposure.
- Sports Events:Live replay, real-time statistics, and sponsorship activation for professional and collegiate athletics. The United States accounts for disproportionate specification intensity given NFL media rights valuation and franchise revenue capacity.
- Concerts:Temporary and semi-permanent installations for touring productions and residency venues. European festival promoters in the Netherlands and Belgium drive mobile fleet utilization.
- Advertising:Perimeter ribbon boards and facade displays monetized through sponsorship inventory. Brazilian football clubs leverage these for regional brand partnerships.
- Public Announcements:Emergency alert and wayfinding systems integrated with municipal safety networks. Australian state governments mandate these for stadium evacuation compliance.
Sports Events anchor procurement volume. Concerts are gaining share fastest.
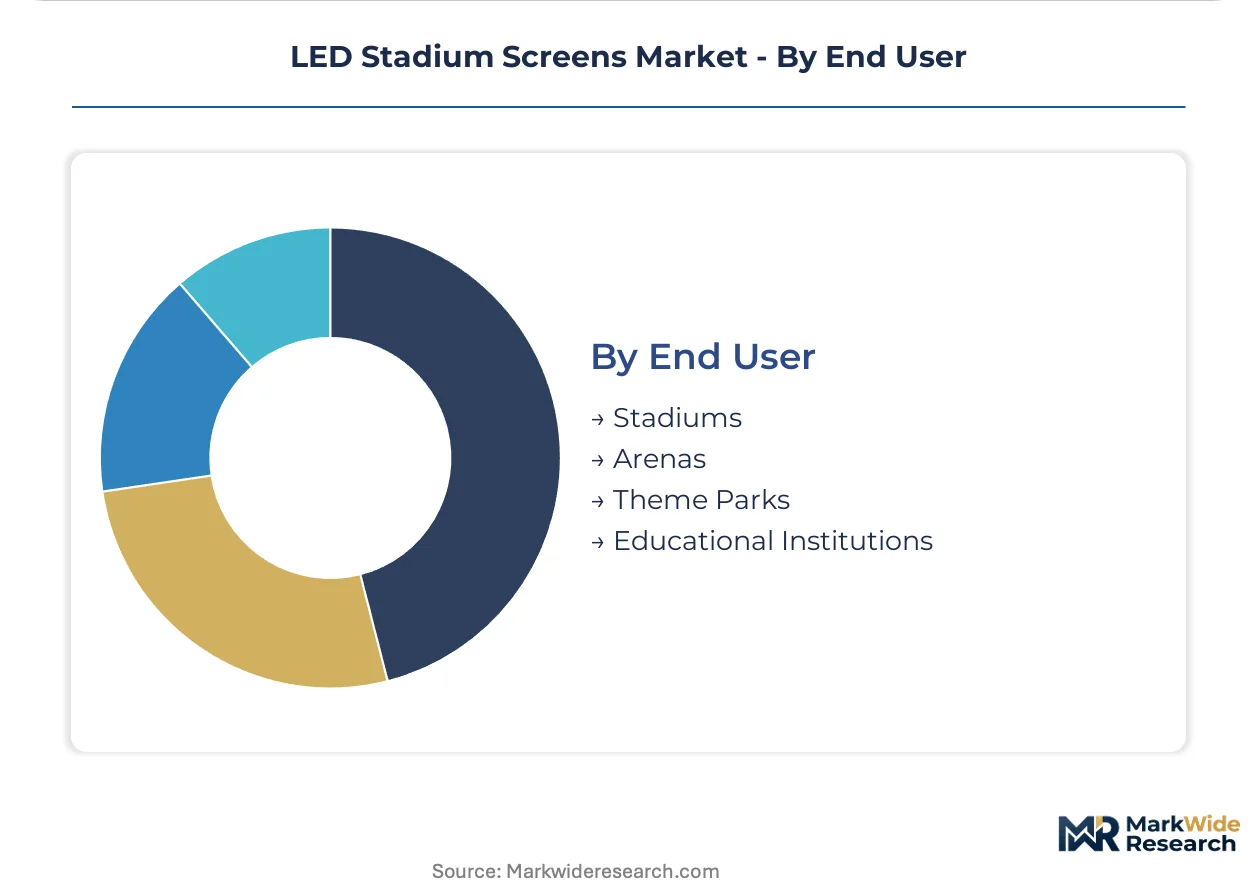
End User:
Volume concentration pools in professional sports infrastructure, with margin expansion concentrated in experience-driven entertainment venues.
- Stadiums:Outdoor professional sports venues with 30,000+ capacity requiring weather-hardened displays. China's tightening GB standards for electronic display safety are accelerating replacement cycles in legacy facilities.
- Arenas:Indoor multi-purpose venues hosting basketball, hockey, and concert configurations. Canadian municipal authorities are bundling LED upgrades with carbon reduction commitments under federal infrastructure programs.
- Theme Parks:Immersive entertainment complexes specifying curved and irregular display geometries. Operators in Florida and California deploy these for queue entertainment and nighttime spectacular backdrops.
- Educational Institutions:University athletic departments and high school facilities with constrained procurement timelines. Leasing models are penetrating this segment as public universities face debt capacity limits.
Stadiums dominate installed base. Theme Parks are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply LED display modules to venue projects across the United States, Germany, and Saudi Arabia, with export volumes concentrated through Shenzhen and Dongguan industrial corridors. Trade flows reflect divergent specification requirements between premium immersive venues and cost-optimized municipal installations.
United States
NFL and NCAA venues drive specification intensity for center-hung and perimeter ribbon board systems exceeding 1,000 square meters. FCC equipment authorization requirements govern RF emissions from wireless content distribution systems embedded in stadium infrastructure. Daktronics anchors manufacturing scale in South Dakota for venue-integrated LED systems serving domestic franchise clients.
China
GB standards for electronic display safety and energy efficiency are tightening compliance requirements and accelerating replacement cycles in legacy facilities. MIIT certification protocols control product market access for domestic venue projects and export-bound manufacturing. Shenzhen and Dongguan industrial clusters concentrate LED chip packaging and module assembly capacity for global supply.
Germany
Heritage building retrofit projects specify transparent LED configurations where solid displays violate preservation codes. CE marking under EU electromagnetic compatibility directives controls market access for venue installations, with RoHS material restrictions affecting LED module solder compositions. Munich and Frankfurt municipal venue authorities bundle LED upgrades with federal infrastructure carbon reduction commitments.
Saudi Arabia
Desert climate venues adopt premium center-hung configurations with enhanced daylight visibility specifications. SFDA and municipal building codes govern electronic display safety certification for entertainment venue infrastructure. Riyadh and Jeddah entertainment districts are commissioning immersive digital canvases for professional football and concert applications.
United Kingdom
Festival promoters and rental fleet operators drive mobile LED screen utilization for temporary event circuits. CE marking requirements under EU-UK Trade and Cooperation Agreement continuity provisions maintain regulatory alignment for display equipment. London and Manchester venue operators are evaluating leasing models to transfer obsolescence risk from capital-constrained municipal authorities.
LED Stadium Screens Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and technology integration depth. The vendor base organizes around three tiers: integrated display manufacturers controlling upstream LED chip supply, systems integrators specializing in venue-specific installation and content management, and rental service operators maintaining mobile fleet assets. Competitive positioning depends on captive production of fine-pitch modules, certification depth across multiple regulatory jurisdictions, and installed base relationships with franchise venue operators. M&A activity concentrates on vertical integration into LED chip packaging and strategic partnerships with wireless broadcast infrastructure providers.
Within the integrated manufacturing tier, Leyard and Unilumin Group represent Chinese vertical specialists with captive LED chip packaging and module assembly capacity. Daktronics exemplifies the North American systems integrator archetype with venue-specific engineering and installation capabilities. Samsung occupies a position on the premium technology vector through direct-view LED leadership in center-hung applications. These three anchors illustrate divergent strategic paths: upstream supply control, venue integration expertise, and display technology premiumization.
| Leading Market Players |
|---|
| Leyard |
| LG Electronics |
| Daktronics |
| INFiLED |
| Barco |
| Unilumin Group |
| Samsung |
| Planar Systems |
| Absen |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride chips replacing traditional silicon-based drivers in fine-pitch LED modules simultaneously concentrates upstream phosphor processing in Chinese industrial corridors and compresses margin structures for European and North American systems integrators lacking captive wafer supply.
Pricing Analysis
The technology-generation pricing gap between legacy 10mm pixel pitch installations, current 4mm direct-view standards, and emerging sub-2mm Mini-LED configurations stratifies procurement tiers across venue categories. Project-based pricing dominates fixed installations, with differentiation driven by FCC certification grade for U.S. deployments and volume scale for collegiate athletic conference bundles. Cost compression in standard-tier ribbon boards intensifies as Shenzhen manufacturers expand module export capacity. Municipal venue authorities exhibit highest price sensitivity, while professional sports franchises prioritize performance specifications over unit economics.
Supply Chain Analysis
Inventory lead times for fine-pitch LED driver ICs have extended substantially, forcing venue project managers to lock component orders before final architectural specifications. Supply concentrates in China, Taiwan, and South Korea for LED epitaxy wafers, surface-mount device assemblies, and thermal management substrates. Raw material dependencies include indium phosphide, gallium arsenide, and rare-earth phosphor compounds. Single-source vulnerability in Chinese rare-earth processing creates exposure to export quota fluctuations. Distribution runs through systems integrators with venue-specific engineering capabilities rather than direct manufacturer-to-venue relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED stadium screen procurement fragments across immersive premium venues, cost-optimized municipal facilities, and temporary event operators, creating distinct competitive arenas where no single vendor archetype dominates all three simultaneously.
For Market Incumbents: Shield installed base relationships with professional sports franchises by embedding proprietary content synchronization protocols that complicate competitive replacement. Acquire certification depth across FCC, CE marking, and China's GB standards to disqualify single-jurisdiction specialists from multinational venue operator RFPs. Prioritize backward integration into LED chip packaging to offset phosphor material cost volatility from concentrated Chinese processing. For New Entrants and Emerging Players: CE marking fast-track programs for transparent LED configurations unlock heritage building retrofit opportunities in Germany and France where preservation codes block incumbent solid-display vendors. Target municipal arena authorities in Canadian provinces bundling LED upgrades with federal carbon reduction infrastructure commitments. Deploy leasing-based acquisition models with bundled maintenance to bypass capital-constrained public university procurement offices. For Investors and Strategic Acquirers: China's tightening GB standards for electronic display safety and energy efficiency reshape the acquisition landscape toward vendors with pre-certified module platforms and established domestic venue relationships. Long-term viability centers on suppliers controlling upstream LED chip packaging rather than pure-play systems integration. Monitor EPA ENERGY STAR threshold evolution as the signal indicating which vendor portfolios align with municipal procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Packaging | Captive wafer supply insulates margin structures from Chinese rare-earth processing concentration. |
| Multi-Jurisdiction Certification Investment | Simultaneous FCC, CE marking, and GB compliance qualifies vendors for multinational venue operator contracts. |
| Transparent LED Product Line Expansion | Architectural integration capability opens German and French heritage building retrofits previously inaccessible. |
| Leasing and Service-Based Acquisition Models | Performance-guaranteed installations align with public university debt capacity constraints and transfer obsolescence risk. |
| 5G Content Distribution Infrastructure Partnership | Wireless broadcast convergence enables real-time fan mobile interaction and new sponsorship activation layers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with stadium operations directors, collegiate athletic conference procurement officers, LED systems integration engineers, and rental fleet asset managers. Secondary validation drew from FCC equipment authorization databases, CE marking compliance registries, MIIT certification protocols, SEC filings of listed display manufacturers, and venue infrastructure bond prospectuses. Bottom-up module shipment estimates triangulated against top-down venue construction pipeline analysis.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, technology tier, application category, and end-user archetype. CAGRs were derived from regression analysis of historical replacement cycle compression and specification threshold escalation. Industry-specific forecast inputs include NCAA and NFL venue capital expenditure disclosure trends, Chinese GB standard implementation timelines, and municipal infrastructure rebate program enrollment patterns.
The analysis sits within stated boundaries; outcomes outside sustained professional sports media rights valuation growth or stable Chinese rare-earth export policy would require recalibration. Forecasts reflect documented assumptions regarding venue construction pipeline continuity and regulatory threshold evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Transport Media Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
US Automatic Content Recognition Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Professional Dubbing Services Market
Digital Media
North America Photographic Services Market
Digital Media
Online Art Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Entertainment Transcription Market
Digital Media
Volumetric Video Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Information Short Video Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Mobile Entertainment Market