
 Game Applications Market | 2026-2036
Game Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Game Applications Market Intelligence
Asset-light publishing models and revenue-sharing partnerships is reconfiguring capital requirements for game studios entering the market. Tencent leverages its super-app ecosystem to sustain distribution control across Asia. Sony Interactive Entertainment anchors premium console experiences through exclusive intellectual property. Microsoft Gaming competes via cloud infrastructure integration that reduces hardware dependency for subscribers.
Game applications constitute interactive software programs designed for entertainment, featuring real-time rendering engines, networked multiplayer architectures, and monetization systems ranging from microtransaction APIs to subscription billing layers. Their primary commercial purpose centers on capturing and retaining user attention through progression mechanics and social connectivity. Mobile and cloud gaming segments are expanding fastest as 5G latency reductions and edge computing enable browser-based AAA experiences without local installation. Console platforms still dominate monetization yield per user, while freemium models on mobile capture the largest addressable player bases.
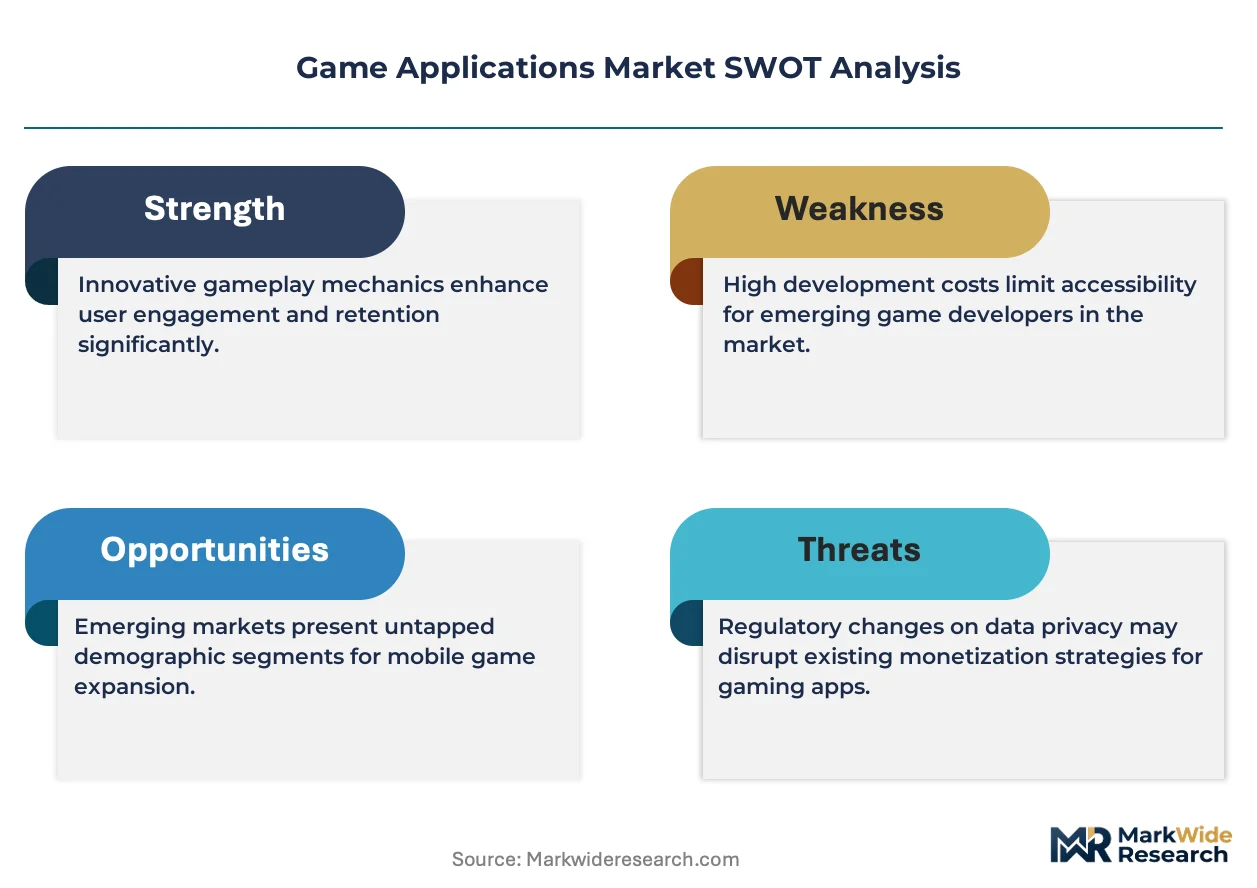
FCC content rating guidelines in the US, GDPR data processing rules enforced by European regulators, and China's MIIT real-name verification mandates collectively shape how game applications collect behavioral data and authenticate users. Compliance costs are diverting mid-sized studios toward third-party identity management providers rather than proprietary systems. Stakeholders must monitor evolving algorithmic transparency requirements that could force disclosure of matchmaking and engagement systems.
Market Dynamics
Cloud infrastructure economics are compressing hardware barriers to entry while data localization mandates from China's MIIT and the EU Digital Services Act force architectural redesigns of live-service game backends.
Growth Catalysts
- 5G edge deployment:Telecom operators in South Korea and Japan are subsidizing low-latency gaming nodes that enable browser-based AAA rendering without console hardware.
- GDPR Article 17 compliance tooling:Third-party identity management providers are capturing mid-sized studios abandoning proprietary user data systems due to European deletion-request automation costs.
- Freemium monetization APIs:Microtransaction infrastructure from payment processors is lowering revenue-model switching costs for mobile-first developers targeting Southeast Asian markets.
Market Restraints
- Silicon supply concentration:GPU foundry capacity in Taiwan creates bottlenecks for real-time rendering hardware essential to premium console and cloud streaming endpoints.
- MIIT real-name verification:China's Ministry of Industry and Information Technology mandates biometric authentication infrastructure that adds fixed compliance costs per active user.
- Energy input volatility:Data center power purchasing agreements in Germany and the Netherlands face renegotiation pressure from grid decarbonization timelines affecting cloud gaming unit economics.
Strategic Opportunities
- Indonesia underpenetration:Java and Sumatra exhibit smartphone penetration above 75 percent but paid-game conversion rates below regional averages, indicating latent monetization headroom.
- AI-assisted content moderation:The EU Digital Services Act's algorithmic transparency requirements are creating procurement demand for automated toxicity detection that reduces human moderator headcount.
- Cross-platform progression systems:Save-state synchronization across mobile, console, and PC endpoints is capturing session time from players with fragmented device ownership patterns.
Industry Challenges
- Live operations talent scarcity:Game-as-a-service economies require data science and behavioral psychology expertise that traditional single-release studios lack in-house.
- Multi-jurisdiction content rating:Simultaneous compliance with ESRB, PEGI, and China's content approval timelines delays synchronized global launches and fragments marketing spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game Applications Market |
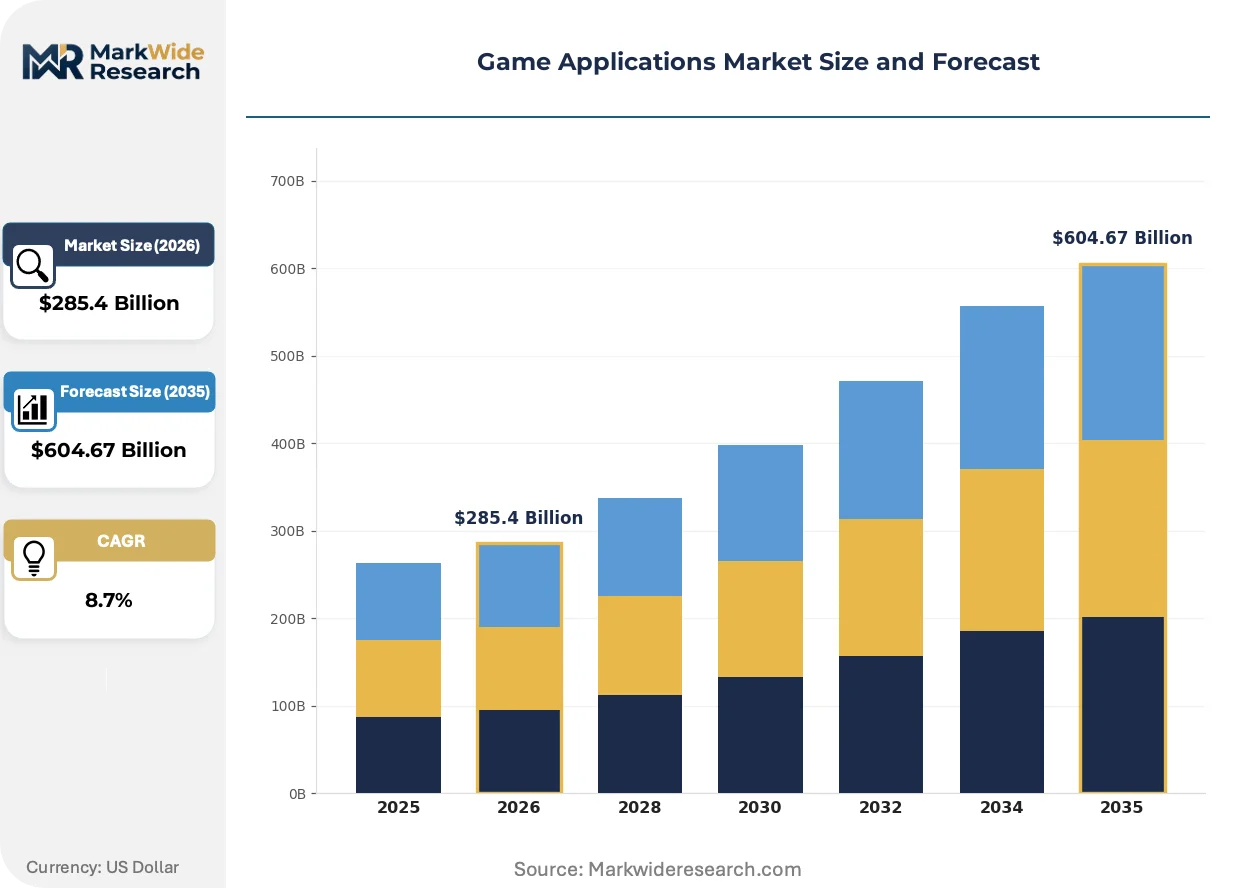
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $604.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Single-player, Multiplayer, Battle Royale, Puzzle Platform: PC, Console, Mobile, Cloud Gaming Monetization Model: Freemium, Subscription, Pay-to-Play, In-game Purchases Development Stage: Pre-production, Production, Beta, Released |
| Companies Covered | Tencent, Sony Interactive Entertainment, Microsoft Gaming, NetEase, Nintendo, Electronic Arts, Take-Two Interactive, Roblox Corporation, Ubisoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game Applications Market Strategic Shifts & Innovations
Rendering pipelines and distribution architectures are converging around infrastructure-as-a-service models that decouple creative production from capital-intensive hardware ownership.
Neural network-based upscaling is hybridizing traditional rasterization with inference-based frame generation, allowing developers to target lower native resolutions while maintaining perceived visual fidelity. Mobile and cloud gaming segments are adopting this most aggressively to compensate for thermal and bandwidth constraints. The technology is compressing the performance gap between premium console silicon and commodity mobile chipsets.
The EU Digital Services Act's algorithmic transparency mandates are forcing disclosure of engagement-optimization systems including matchmaking logic and reward scheduling. Studios operating in European markets must now document how their progression mechanics influence player retention. Mid-sized publishers are responding by externalizing these systems to specialized compliance vendors rather than maintaining proprietary black-box implementations.
Subscription fatigue among entertainment consumers is fragmenting purchasing patterns away from platform-agnostic monthly fees toward title-specific seasonal passes. This shift is most visible in North American and Western European markets where multiple overlapping gaming subscriptions have saturated household entertainment budgets. Publishers are responding with à-la-carte downloadable content roadmaps that front-load content drops within 90-day purchase windows.
Game Applications Market Segmentation
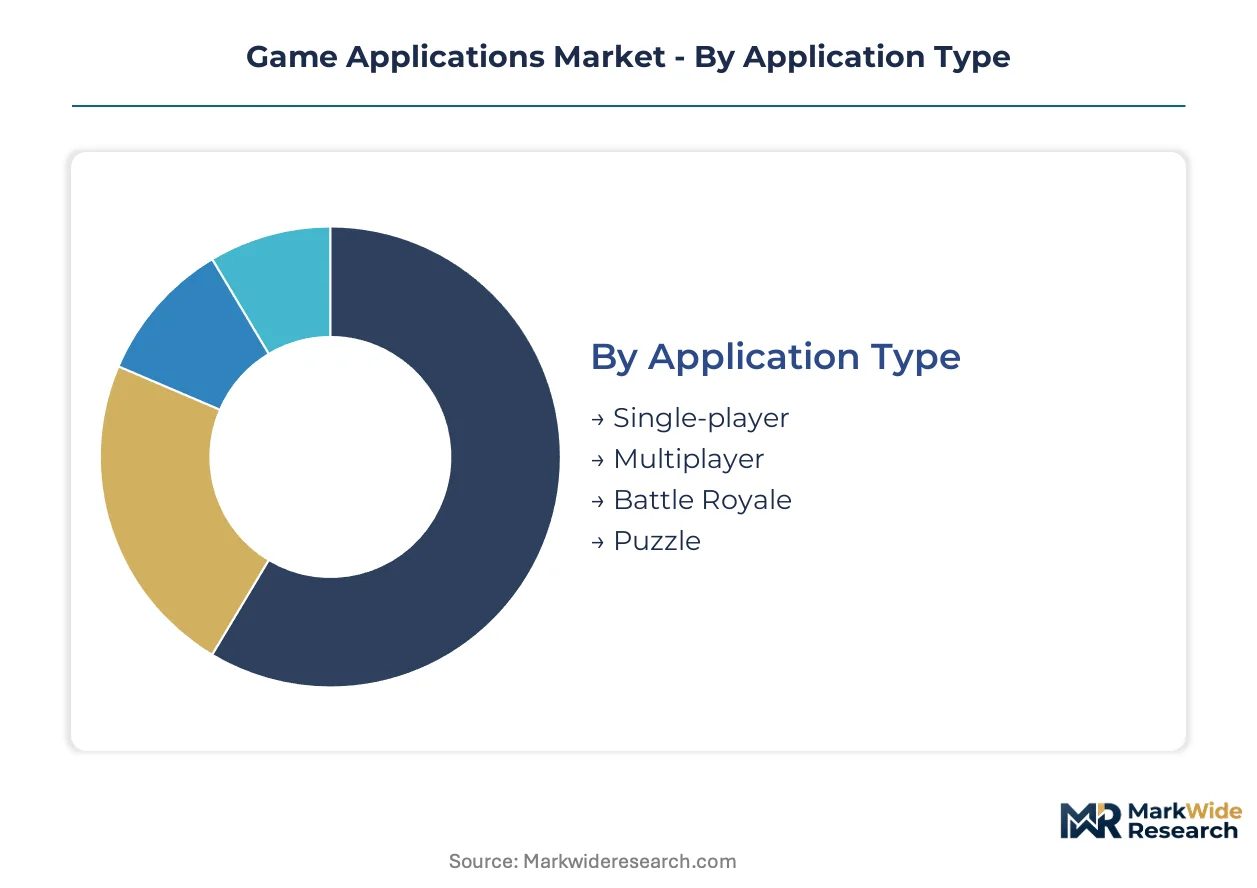
Game applications fragment across four structural dimensions that determine capital intensity, regulatory exposure, and revenue predictability. Each segmentation axis carries distinct margin profiles and compliance requirements that shape studio positioning strategies.
Application Type:
Player interaction patterns define technical architecture choices and server infrastructure spend.
- Multiplayer:Persistent session architectures require dedicated server meshing and anti-cheat systems. Demand concentrates in South Korea and Japan where 5G edge nodes subsidize low-latency competitive play. Studios face escalating live operations costs from player toxicity moderation.
- Battle Royale:Synchronous 100-player instances demand elastic cloud orchestration and predictive matchmaking algorithms. Southeast Asian markets drive volume through mobile-first deployment, though monetization yield trails console equivalents.
- Single-player:Narrative-driven content with finite development cycles and predictable post-launch support windows.
- Puzzle:Turn-based mechanics with minimal server overhead and strong retention through daily progression hooks.
Multiplayer commands the established base. The steepest expansion runs through Battle Royale.
Platform:
Hardware dependency determines distribution control and revenue share terms with gatekeepers.
- Mobile:Touch-optimized input schemes and thermal-constrained rendering pipelines dominate development priorities. Indonesia and Vietnam exhibit smartphone penetration above 75 percent with paid conversion rates below regional benchmarks, signaling latent monetization headroom. Freemium APIs from payment processors lower revenue-model switching costs.
- Cloud Gaming:Browser-based rendering eliminates local installation through edge-computed frame streaming. Telecom operators in South Korea and Japan subsidize low-latency nodes that enable AAA experiences without console hardware. GDPR Article 17 compliance tooling diverts mid-sized studios toward third-party identity providers.
- Console:Premium silicon-dependent experiences with highest monetization yield per user.
- PC:Open hardware ecosystem with direct distribution bypassing platform fees.
Mobile commands the established base. Cloud Gaming is climbing the fastest.
Monetization Model:
Revenue timing and predictability separate capital-efficient models from premium upfront economics.
- Freemium:Zero-entry-price acquisition with gated progression mechanics and cosmetic microtransactions. Southeast Asian developers leverage regional payment processor APIs to reduce revenue-model switching costs. Player lifetime value calculation requires behavioral data infrastructure that triggers GDPR compliance overhead in European markets.
- Subscription:Recurring revenue pools with platform-agnostic or title-specific structures. North American and Western European households exhibit fatigue from overlapping entertainment subscriptions, fragmenting purchasing toward seasonal passes. Publishers respond with à-la-carte downloadable content roadmaps front-loaded within 90-day windows.
- Pay-to-Play:Upfront purchase with finite content delivery and predictable support obligations.
- In-game Purchases:Transactional revenue from virtual goods with real-money trade restrictions varying by jurisdiction.
Freemium commands the established base. Subscription is gaining share fastest.
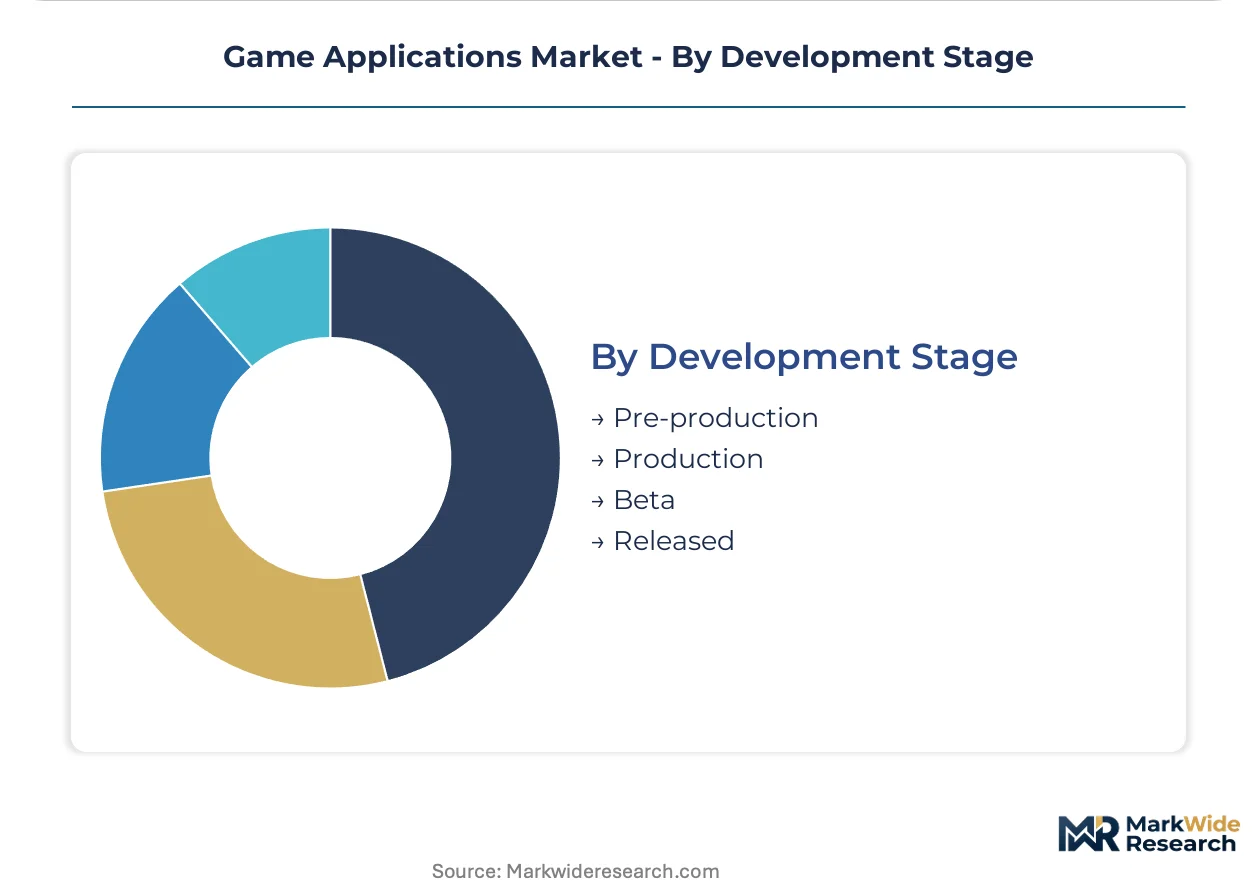
Development Stage:
Capital deployment timing and risk exposure shift dramatically across production phases.
- Released:Live-service operations demand data science and behavioral psychology expertise that traditional single-release studios lack in-house. Multi-jurisdiction content rating compliance with ESRB, PEGI, and China's approval timelines fragments marketing synchronization.
- Production:Asset creation at maximum headcount with milestone-dependent publisher financing.
- Beta:Server stress testing and economy tuning with limited monetization activation.
- Pre-production:Prototype validation with minimal burn rate and pivot flexibility.
Released titles command the established base. The steepest expansion trajectory runs through Production-stage projects targeting cloud-native deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese publishers extract 40% higher average revenue per user than Indonesian studios, yet Southeast Asian markets expand three times faster on volume metrics. This pricing-power asymmetry redirects capital flows toward emerging smartphone-first economies while mature markets defend yield through exclusive intellectual property.
United States
Console and cloud gaming subscription saturation drives publishers toward à-la-carte seasonal passes. FCC content rating guidelines shape how studios collect behavioral data and authenticate minors. Seattle and Austin anchor development clusters where live-service operations talent concentrates around data science and behavioral psychology expertise.
China
MIIT real-name verification mandates and gaming time restrictions for minors compress monetization windows for domestic publishers. SAMR antitrust enforcement limits super-app distribution control. Shenzhen and Hangzhou host the densest concentration of mobile-first studios adapting to biometric authentication infrastructure costs.
South Korea
Telecom operators subsidize 5G edge nodes that enable browser-based AAA rendering without local hardware. Game Rating and Administration Committee content approval timelines synchronize with esports tournament schedules. Seoul anchors competitive multiplayer development where low-latency infrastructure supports persistent session architectures.
Japan
Premium console experiences sustain highest monetization yield per user through exclusive intellectual property and character-driven franchises. METI digital content promotion programs support export-oriented localization. Tokyo and Osaka development clusters specialize in narrative-driven single-player content with finite production cycles.
Indonesia
Smartphone penetration exceeds 75 percent across Java and Sumatra while paid-game conversion rates lag regional benchmarks, signaling latent monetization headroom. Payment processor APIs reduce revenue-model switching costs for freemium developers. Jakarta and Bandung emerge as Southeast Asian publishing hubs targeting underpenetrated mobile-first demographics.
Game Applications Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical moats. The vendor base stratifies across three concentration levels: super-app ecosystems with distribution control, console manufacturers with premium silicon-dependent experiences, and cloud infrastructure operators reducing hardware dependency. Strategic archetypes include ecosystem bundlers, exclusive IP holders, and infrastructure-as-a-service providers. Competitive moves concentrate on cross-platform progression systems and live-service operations capability acquisition.
Within the ecosystem bundler tier, Tencent and NetEase exemplify super-app distribution control across Asian markets. Sony Interactive Entertainment occupies a position as the premium-tier exclusive IP anchor. Microsoft Gaming represents infrastructure-led displacement of hardware requirements through cloud integration. These three archetypes collectively illustrate how capital requirements reconfigure around asset-light publishing models and revenue-sharing partnerships.
| Leading Market Players |
|---|
| Tencent |
| Sony Interactive Entertainment |
| Microsoft Gaming |
| NetEase |
| Nintendo |
| Electronic Arts |
| Take-Two Interactive |
| Roblox Corporation |
| Ubisoft |
| Others |
Cost & Logistics Intelligence
GPU foundry concentration in Taiwan determines both the premium-to-economy pricing spread across rendering hardware tiers and the geographic shape of upstream procurement networks for cloud gaming infrastructure. Studios and platform operators face simultaneous cost compression from silicon scarcity and architectural redesign mandates from data localization rules.
Pricing Analysis
Enterprise entertainment buyers anchor subscription-based pricing structures across cloud gaming tiers. Three-tier pricing structure across premium, standard, and economy levels separates exclusive IP holders from infrastructure-as-a-service providers and asset-light mobile publishers. Price differentiation rests on latency guarantees and content library depth. Pricing pressure stems from subscription fatigue fragmenting household entertainment budgets toward title-specific seasonal passes. Mobile-first developers in Southeast Asian markets exhibit highest price sensitivity; console platform holders with exclusive IP show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for rendering hardware procurement. GPU foundry capacity concentrates in Taiwan, South Korea, and the United States. Advanced node silicon, memory modules, and thermal management components feed from concentrated Asian manufacturing bases. Single-source vulnerability in Taiwan Semiconductor Manufacturing creates chokepoints for real-time rendering endpoints. Distribution runs through platform-integrated super-app ecosystems and direct-to-developer cloud infrastructure APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward telecom operators and cloud infrastructure providers consolidating distribution control. Platform gatekeeper fragmentation among Asian super-apps and Western console ecosystems intensifies margin pressure on mid-sized studios.
For Market Incumbents: Harden exclusive IP portfolios through character-driven franchise extension and narrative universe expansion. Acquire live-service operations talent in data science and behavioral psychology to offset single-release studio capability gaps. Invest in cross-platform progression systems that capture fragmented device ownership patterns. Channel control through super-app ecosystem bundling remains the priority lever against infrastructure-as-a-service displacement.
For New Entrants and Emerging Players: Indonesia's underpenetrated mobile-first demographics offer the steepest volume expansion trajectory. Java and Sumatra smartphone penetration above 75 percent with paid conversion rates below regional benchmarks signals latent monetization headroom. Target freemium deployment through regional payment processor APIs to reduce revenue-model switching costs. White-space opportunity concentrates in AI-assisted content moderation tooling for EU Digital Services Act compliance.
For Investors and Strategic Acquirers: The EU Digital Services Act's algorithmic transparency mandates reshape the acquisition landscape toward compliance-vendor consolidation. Long-term viability favors studios with documented engagement-optimization systems and externalized matchmaking logic. Target acquisition archetype: mid-sized publishers with live-service infrastructure and Southeast Asian market presence. Watch for MIIT data governance rule expansion as signal for biometric authentication infrastructure demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Telecom operators in South Korea and Japan subsidize low-latency edge nodes that displace console hardware dependency. |
| Cross-Platform Progression System | Save-state synchronization captures session time from players with fragmented mobile-console-PC ownership patterns. |
| AI Content Moderation Deployment | Automated toxicity detection reduces human moderator headcount while satisfying EU Digital Services Act transparency requirements. |
| Live-Service Operations Acquisition | Data science and behavioral psychology expertise addresses talent scarcity constraining game-as-a-service economics. |
| Regional Payment Processor Integration | Freemium API adoption lowers revenue-model switching costs for mobile-first developers targeting Indonesian and Vietnamese markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with game studio executives, platform engineering leads, telecom infrastructure planners, regulatory compliance officers, and live-service operations directors. Secondary validation drew from SEC filings of platform holders, MIIT regulatory bulletins, EU Digital Services Act implementation guidance, 5G deployment disclosures from South Korean and Japanese carriers, and hyperscaler cloud gaming capex announcements. Bottom-up title-level revenue modeling and top-down market sizing triangulated across the analysis window.
Calibration against historical growth trajectories and technology diffusion patterns anchored the analytical framework. Segmentation dimensions modeled include application type, platform architecture, monetization model, and development stage alongside regional regulatory cluster differentiation. CAGRs were derived from installed base projections, average revenue per user assumptions, and content release cadence patterns. Neural network-based upscaling adoption curves and edge computing node deployment schedules served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, semiconductor capital expenditure cycles, or energy input costs would shift the trajectory. Forecasts reflect documented assumptions regarding 5G latency reduction timelines and cloud infrastructure unit economics. Regulatory enforcement intensity from China's MIIT, the EU Digital Services Act, and the US FCC content rating guidelines represents specific revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Shooter Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
United States Virtual Reality Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Mobile and Handheld Gaming Market
Gaming
VR Gaming Market
Gaming
Gaming Chair Market
Gaming
Global Esports Market
Gaming
Europe Casino Gambling Market
Gaming
North America Gaming Market
Gaming
Video Game Software Market
Gaming
Global Gaming Market
Gaming
Gaming Software Market
Gaming
Australia Gaming Accessories Market
Gaming
Online Strategy Games Market
Gaming
Global Trading Card Games Market