
 Lottery Market | 2026-2036
Lottery Market Size, Share, and Industry Trends Forecast 2026-2036
Lottery Market Analysis
Project finance tied to public-private lottery concessions is tilting competitive dynamics toward operators with balance-sheet capacity to underwrite long-term state contracts. Scientific Games leverages its integrated technology and instant-game manufacturing footprint to sustain pricing power across North American jurisdictions. Lottomatica anchors its position through exclusive multi-year licenses in key Italian regions, while INTRALOT competes on systems modernization contracts in emerging digital markets.
Lottery comprises state-authorized games of chance distributed through physical or electronic channels, utilizing certified random number generation, secure ticket validation, and centralized prize-pool management to generate public revenue. Instant Win products dominate volume due to low price points and impulse-driven retail placement, while Online Platforms represent the fastest-expanding distribution channel as mobile authentication and geolocation compliance technology mature. Draw Games retain mature, predictable margin pools in jurisdictions with established weekly participation rituals.
FDA oversight of gambling-adjacent marketing claims intersects with state-level gaming commissions and the SEC disclosure requirements affecting publicly traded operators like International Game Technology. The EU Green Deal's digital infrastructure funding indirectly shapes channel migration timelines for European lottery boards. Stakeholders must monitor how fragmented regulatory sovereignty across digital channels reshapes compliance investment and market entry sequencing.
Market Dynamics
Mobile-first participation protocols are compressing operator margins while expanding addressable participant bases, forcing legacy retail-dependent boards to accelerate digital infrastructure deployment or cede volume to agile platform providers.
Growth Catalysts
- State-level digital wagering frameworks:United States jurisdictions are rewriting licensing architectures to permit geolocation-verified mobile participation, opening captive revenue pools previously restricted to physical retail.
- Instant Win product innovation:Low-denomination scratch-format games with augmented-reality validation features are capturing impulse-driven purchasing in convenience retail channels across India and Brazil.
- Blockchain-based prize-pool transparency:Distributed ledger verification of random number generation is reducing audit friction and accelerating regulatory approval timelines in European Union member states.
Market Restraints
- Geolocation compliance cost structure:Multi-point identity verification and real-time location tracking requirements impose per-transaction infrastructure costs that erode margin on low-ticket purchases.
- State monopoly supplier concentration:Exclusive concession agreements in Italy, France, and Spain lock out competitive system providers and limit technology refresh cycles to political budget cycles.
- Substitute entertainment fragmentation:Skill-based gaming platforms and sports wagering applications are diverting discretionary entertainment expenditure from traditional draw-format participation.
Strategic Opportunities
- India state-board digital expansion:Kerala and Maharashtra lottery boards are tendering for integrated online distribution platforms, creating first-mover positioning for compliant technology providers.
- Second-chance promotional integration:Retail instant-ticket verification apps that funnel non-winning tickets into loyalty-program credit are deepening participant retention and cross-selling adjacent gaming products.
- EU AI Act compliance services:Automated responsible-gaming intervention systems that meet forthcoming algorithmic transparency mandates represent a contracted service opportunity for specialized analytics vendors.
Industry Challenges
- Legacy system integration complexity:Decades-old centralized draw management architectures resist API-based connectivity with modern mobile front-ends, forcing expensive middleware development or risky rip-and-replace decisions.
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 audit cycles for real-time payment processing systems extend 12-18 months, delaying market entry for new platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lottery Market |
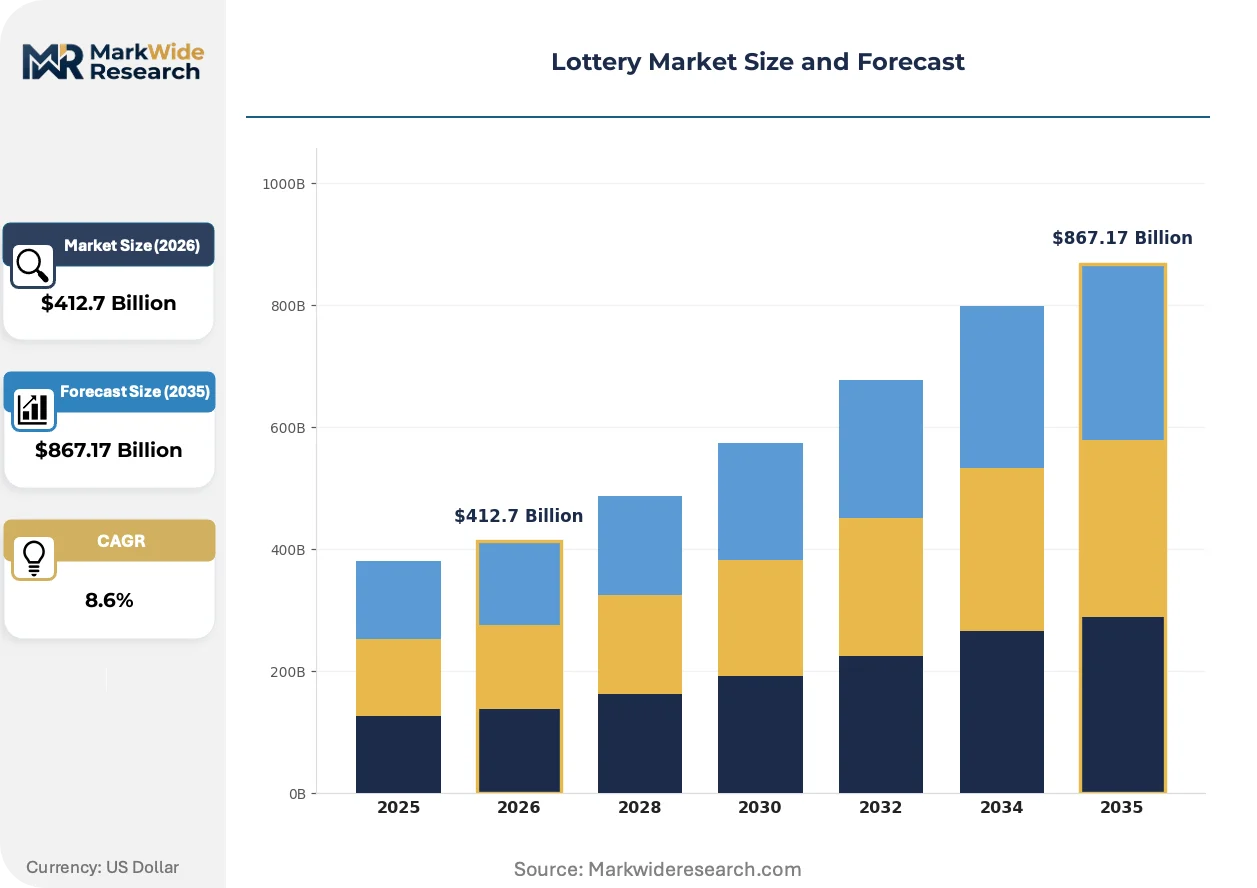
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $867.17 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Instant Win, Draw Games, Multi-State Games, Keno Customer Type: Regular Players, Occasional Players, Online Participants, Retail Buyers Distribution Channel: Retail Outlets, Online Platforms, Mobile Apps, Lottery Booths Ticket Price: Low Price, Medium Price, High Price, Premium Price |
| Companies Covered | International Game Technology, Scientific Games, Française des Jeux, Lottomatica, Camelot Group, INTRALOT, Sazka Group, Jumbo Interactive, Hong Kong Jockey Club, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lottery Market Emerging Trajectories
Random number generation hardware is migrating from proprietary closed systems to open-standard cryptographic modules, eroding incumbent supplier lock-in while accelerating jurisdictional approval for new market entrants.
Cloud-native draw management platforms are rendering obsolete on-premise server farms that require physical custody chains and manual failover procedures. State lottery boards in Australia and Canada are piloting these systems for disaster recovery redundancy. The shift is compressing capital deployment timelines from multi-year infrastructure builds to contracted service provisioning.
The EU Green Deal's digital infrastructure funding is channeling public investment toward energy-efficient data center certification for lottery system hosting. Operators seeking concession renewals must document carbon-intensity metrics alongside uptime guarantees. Mediterranean jurisdictions with aging server estates face accelerated refresh obligations to maintain license eligibility.
Younger demographics are abandoning weekly ritual participation in favor of on-demand instant-win mobile engagement with sub-60-second transaction cycles. Retail convenience channels are responding with dedicated lottery-dedicated touchscreen terminals that bypass traditional counter service. This behavioral pivot is most pronounced in urban Indian and Southeast Asian markets where smartphone penetration outpaces traditional banking access.
Lottery Market Segmentation
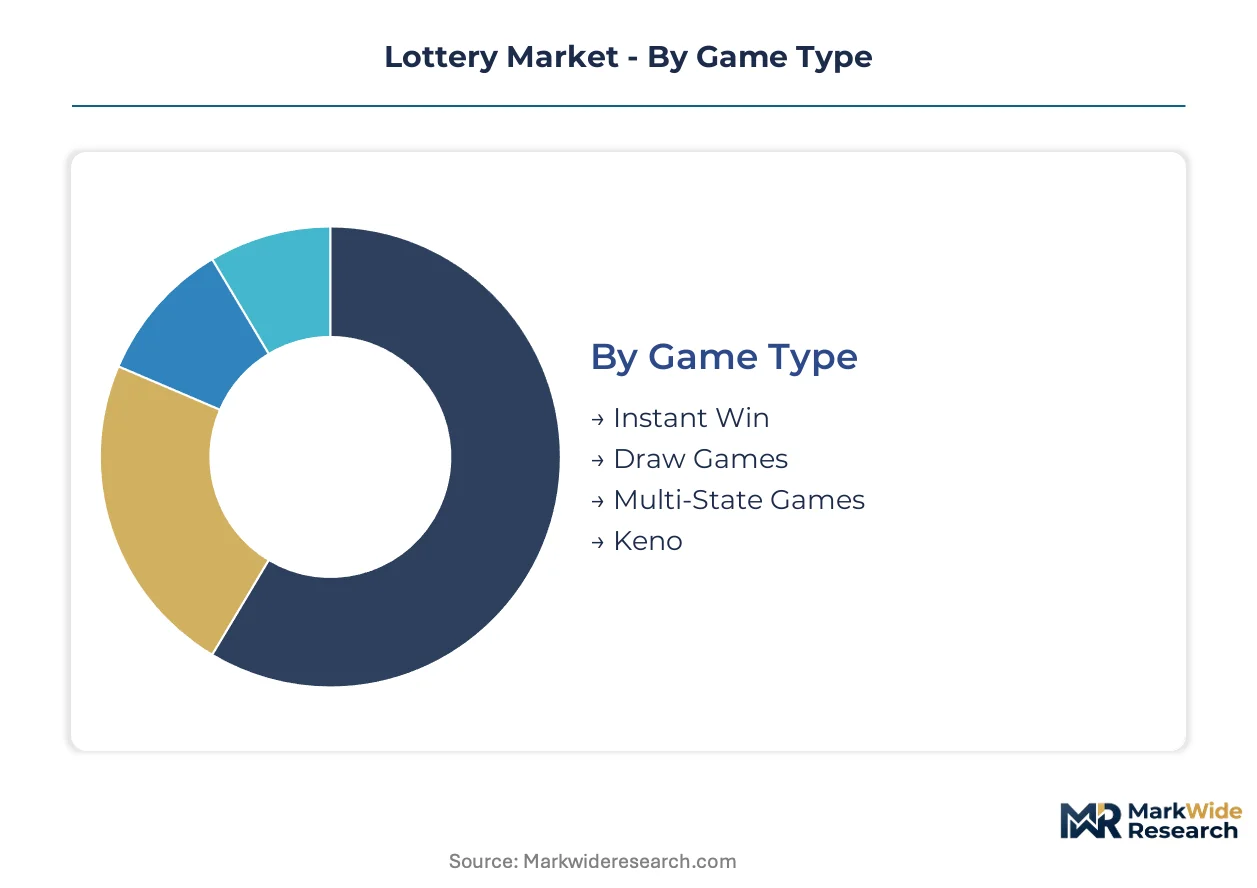
Lottery market segmentation reveals distinct operational rhythms across game formats and participant behaviors. Cycle-time differentials between instant-gratification products and ritual-driven draw formats shape inventory management, margin structures, and technology investment priorities for operators and state boards.
Game Type:
Transaction velocity separates high-frequency impulse formats from scheduled-event products with extended purchase windows and pooled jackpot accumulation periods.
- Instant Win:Scratch-format tickets with immediate prize reveal dominate retail foot traffic through low denomination entry points and impulse placement at convenience checkout counters. Kerala and Maharashtra state boards are expanding digital instant-win catalogs to capture smartphone-native participants migrating from physical ticket purchases.
- Draw Games:Scheduled number-selection formats with multi-day jackpot rollovers sustain predictable revenue baselines in mature North American and European jurisdictions where weekly participation rituals persist among aging demographic cohorts.
- Multi-State Games:Linked prize pools across jurisdictional boundaries generate outsized jackpot events that temporarily spike participation rates among normally disengaged buyer segments.
- Keno:Rapid-draw number formats with sub-hour result cycles occupy middle ground between instant gratification and scheduled anticipation, concentrated in casino-adjacent retail environments and digital lounge platforms.
Draw Games dominate installed base across legacy lottery states. Instant Win is where expansion concentrates.
Customer Type:
Engagement depth and channel preference stratify participants into distinct service-cost tiers, from high-touch retail relationships to low-friction digital self-service.
- Regular Players:Subscribed participation with automated number selection and recurring purchase patterns generates lowest per-transaction service costs for operators while demanding robust responsible-gaming monitoring systems under EU AI Act algorithmic transparency mandates.
- Occasional Players:Event-driven purchasing tied to jackpot threshold triggers or promotional second-chance campaigns requires targeted re-engagement infrastructure to prevent permanent churn to competing entertainment substitutes.
- Online Participants:Mobile-first account holders with geolocation-verified access represent the steepest expansion trajectory across US state-level digital wagering frameworks and Indian state board platform tenders.
- Retail Buyers:Cash-based counter purchasers with limited digital banking access sustain physical outlet networks in rural and underbanked geographies where smartphone penetration outpaces formal financial inclusion.
Retail Buyers anchor current volume. Online Participants are climbing the fastest.
Distribution Channel:
Capital intensity and regulatory compliance burden vary dramatically between physical custody chains and cloud-native digital provisioning.
- Retail Outlets:Convenience store and gas station counter networks with dedicated terminal infrastructure require ongoing hardware refresh cycles and physical security protocols for ticket stock management.
- Online Platforms:Browser-based account portals with integrated payment processing and geolocation verification impose per-transaction compliance costs that erode margin on low-ticket purchases.
- Mobile Apps:Native smartphone applications with biometric authentication and push-notification jackpot alerts concentrate development investment among operators competing for younger demographic engagement.
- Lottery Booths:Dedicated street-level kiosks with staffed service counters persist in high-footfall urban Indian and Southeast Asian markets as transitional infrastructure between pure retail and full digital migration.
Retail Outlets maintain widest geographic coverage. Mobile Apps are gaining share fastest.
Ticket Price:
Price-point stratification aligns with occasion-based purchasing psychology and discretionary entertainment budget allocation across income segments.
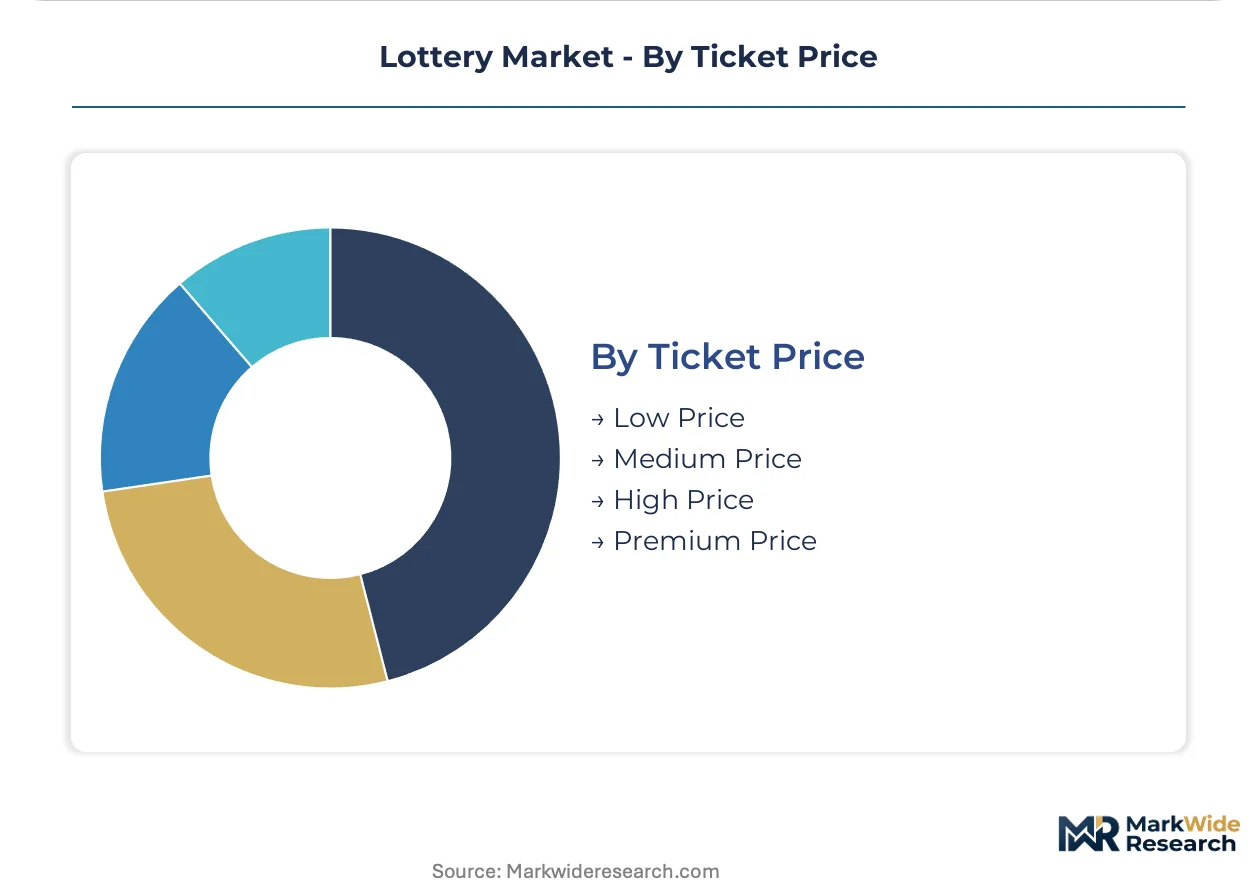
- Low Price:Sub-dollar entry tickets with modest prize tiers sustain volume-driven margin pools through impulse accessibility and minimal purchase deliberation.
- Medium Price:Mid-tier formats with enhanced prize structures and occasional promotional multipliers capture habitual players seeking elevated engagement without premium commitment.
- High Price:Elevated entry-cost products with correspondingly scaled prize pools target committed enthusiasts with demonstrated willingness to absorb higher per-transaction expenditure.
- Premium Price:Limited-release collector-format tickets with augmented reality validation features and experiential redemption options test price elasticity among novelty-seeking segments in Brazil and Indian metropolitan markets.
Low Price commands transaction volume leadership. Premium Price represents the emerging experimentation zone for product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State lottery boards in Kerala and Maharashtra anchor the fastest-growing participant bases, while established weekly draw rituals persist among aging cohorts in mature North American jurisdictions. Digital wagering frameworks are compressing channel-migration timelines across all geographies.
United States
State-level digital wagering frameworks in New Jersey and Pennsylvania permit geolocation-verified mobile participation, opening revenue pools previously restricted to physical retail. The SEC imposes disclosure requirements on publicly traded operators affecting capital-raising timelines. Scientific Games leverages its integrated technology footprint to sustain pricing power across North American jurisdictions.
Italy
Exclusive multi-year licenses in key Italian regions anchor Lottomatica's competitive position against challenger platform providers. The EU Green Deal's digital infrastructure funding shapes channel migration timelines for European lottery boards. Milan and Rome concentrate regulatory decision-making for concession renewals requiring carbon-intensity documentation.
India
Kerala and Maharashtra state lottery boards are tendering for integrated online distribution platforms, creating first-mover positioning for compliant technology providers. The RBI oversees payment processing frameworks for digital ticket purchases. Mumbai and Thiruvananthapuram anchor state-run lottery board headquarters driving digital distribution network expansion.
Australia
Cloud-native draw management platforms are rendering obsolete on-premise server farms requiring physical custody chains. The country's national gaming regulator mandates responsible-gaming intervention systems aligned with algorithmic transparency expectations. Sydney and Melbourne concentrate pilot programs for disaster recovery redundancy in lottery system hosting.
Brazil
Low-denomination scratch-format games with augmented-reality validation features capture impulse-driven purchasing in convenience retail channels. ANVISA intersects with state-level gaming commissions on gambling-adjacent marketing claims. São Paulo and Rio de Janeiro anchor metropolitan markets testing price elasticity among novelty-seeking segments.
Lottery Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented concession architectures. State monopoly supplier concentration in Italy, France, and Spain locks out competitive system providers and limits technology refresh cycles. Three archetypes dominate: integrated technology-and-manufacturing conglomerates, exclusive license-holding regional operators, and systems modernization contractors for emerging digital markets. Competitive moves concentrate on exclusive concession bidding and cloud-native platform deployment.
Within the integrated technology tier, Scientific Games and International Game Technology occupy positions spanning instant-game manufacturing and systems provisioning across multiple jurisdictions. Lottomatica exemplifies the exclusive license-holder archetype through its anchored position in Italian regional concessions. INTRALOT sits within the systems modernization contractor category, competing for digital infrastructure contracts in emerging markets where legacy architectures resist API-based connectivity.
| Leading Market Players |
|---|
| International Game Technology |
| Scientific Games |
| Française des Jeux |
| Lottomatica |
| Camelot Group |
| INTRALOT |
| Sazka Group |
| Jumbo Interactive |
| Hong Kong Jockey Club |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic fiber-optic cable routes carry the bulk of geolocation verification traffic between European lottery data centers and North American compliance servers, with latency-sensitive authentication costs cascading into per-transaction pricing tiers that separate premium mobile platforms from economy retail terminals. This infrastructure geography concentrates supplier negotiating leverage among cloud-hosting providers certified under EU Green Deal carbon-intensity standards, while downstream price differentiation reflects the cost burden of multi-point identity verification systems.
Pricing Analysis
Cost-plus contracts with quarterly indexation to SOC 2 audit fee schedules dominate systems modernization agreements between state lottery boards and technology providers. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native platform operators from legacy terminal maintenance vendors and bare-bones ticket stock suppliers. Pricing pressure stems from geolocation compliance infrastructure costs that erode margins on sub-dollar instant-win transactions. Retail Buyers exhibit highest price sensitivity due to cash-based purchasing constraints, while Online Participants absorb premium pricing for frictionless mobile authentication.
Supply Chain Analysis
Extended payment terms stretching to 180 days characterize supplier-finance arrangements for cryptographic hardware modules sourced from Taiwan, Germany, and the United States. Random number generation chipsets, secure ticket substrate materials, and cloud-hosting services feed from concentrated vendor pools subject to ISO 27001 certification bottlenecks. Single-source vulnerability in specialized thermal printing equipment for instant-ticket production threatens continuity for regional lottery boards. Distribution runs through state-authorized terminal networks and licensed cloud service providers under exclusive concession frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-as-a-service revenue layers for responsible-gaming compliance and second-chance promotional integration are expanding faster than hardware terminal deployments, positioning recurring service contracts as the primary value-capture mechanism. This service-attach dynamic favors operators with embedded analytics capabilities over pure manufacturing specialists.
For Market Incumbents: Pre-empt challenger entry by securing exclusive multi-year cloud-hosting concessions in Indian state board tenders before cybersecurity certification timelines lock out late entrants. Consolidate position through backward integration into instant-game design studios that control proprietary content catalogs. Vertical control over augmented-reality validation features represents the critical defensive lever against platform-agnostic competitors.
For New Entrants and Emerging Players: Establish a beachhead in Kerala and Maharashtra digital distribution tenders where legacy system integration complexity has delayed incumbent modernization. Target white-space opportunities in EU AI Act compliance services for algorithmic transparency mandates affecting automated responsible-gaming interventions. Lead with blockchain-based prize-pool verification as a differentiated regulatory-acceleration offering.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies seeking to divest non-core lottery technology divisions amid portfolio rationalization pressures. Long-term viability hinges on recurring revenue attachment rates rather than one-time systems sales. Monitor state-level digital wagering framework enactment velocity as the primary inflection signal for platform valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | State boards in Australia and Canada are piloting disaster-recovery-redundant draw management systems. |
| Exclusive Concession Bidding | Lottomatica anchors market position through multi-year licenses in key Italian regions requiring carbon documentation. |
| Blockchain Transparency Integration | Distributed ledger verification reduces audit friction and accelerates regulatory approval timelines in EU member states. |
| Mobile App Development Investment | Native smartphone applications with biometric authentication concentrate competition for younger demographic engagement. |
| Second-Chance Promotional Integration | Retail instant-ticket verification apps deepen participant retention through loyalty-program credit funneling. |
Methodological Framework
Cross-validation between primary interviews with lottery board procurement directors, platform engineering leads, and regulatory compliance officers and secondary sources including SEC filings, state gaming commission tender documents, and EU Green Deal infrastructure funding disclosures anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical concession award patterns and technology refresh cycles shapes the analytical framework across the projection horizon. Segmentation dimensions include game format, participant behavior archetype, distribution channel capital intensity, and jurisdictional regulatory cluster. CAGRs derive from modeled participation rate trajectories and per-capita expenditure elasticity, with digital channel penetration curves and responsible-gaming compliance cost inflation as primary industry-specific inputs.
Stress conditions across geolocation compliance cost inflation, state budget cycle delays, and substitute entertainment diversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory framework adoption timelines and technology certification velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Online Strategy Games Market
Gaming
Virtual Sports Market
Gaming
Cloud Gaming Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Global Subscription-Based Gaming Market
Gaming
MMORPG Gaming Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Global Game Testing Service Market
Gaming
Galgames Market
Gaming
Gaming Console Market
Gaming
Serious Games Market
Gaming
Australia Gaming Gadgets Market
Gaming
PC Games Market
Gaming
3D Gaming Technology Market