
 Global Battle Royale Games Market | 2026-2036
Global Battle Royale Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battle Royale Games Market Analysis
Multi-source engine licensing is decoupling development costs from proprietary technology stacks. Epic Games leverages its Unreal Engine to anchor a dual-revenue architecture spanning tool licensing and first-party titles. Tencent sustains geographic dominance through minority stakes in studios across North America, Europe, and Asia. Krafton specializes in the PC-to-mobile adaptation pipeline that defines regional release strategies.
Battle royale games are multiplayer online shooters where up to one hundred players compete to be the last combatant standing on a shrinking map, with servers handling sixty-tick simulation rates to minimize latency. Their primary commercial purpose is to maximize player lifetime value through recurrent engagement loops rather than upfront purchase. Mobile platforms occupy the largest addressable base, while battle pass monetization captures the most predictable revenue stream with lower churn than ad-supported models. Cloud gaming represents the smallest segment but carries the highest infrastructure barrier to entry.
The ESRB in the United States, PEGI across European markets, and China's NPPA collectively shape content eligibility, age-gating requirements, and monetization disclosure standards that determine catalog availability. GDPR and evolving state-level data privacy laws in the US constrain cross-border player analytics and personalized pricing architectures. Stakeholders must monitor regulatory divergence between permissive and restrictive jurisdictions when allocating server infrastructure and live-service staffing.
Market Dynamics
Mobile esports tournaments are drawing sustained investment from telecom operators, reshaping how battle royale titles monetize through carrier billing partnerships and zero-rating data bundles.
Growth Catalysts
- MIIT youth gaming restrictions:China's tightening time limits for minors have pushed studios toward battle pass and cosmetic monetization models that maximize revenue per engaged adult hour rather than playtime volume.
- Cloud gaming infrastructure:5G network rollouts in South Korea and Japan are compressing latency barriers, enabling console-quality battle royale experiences on mid-tier smartphones without local hardware upgrades.
- Esports tournament pipelines:Telecom operators in Southeast Asia are underwriting prize pools and streaming rights, creating predictable revenue streams that subsidize player acquisition costs for publishers.
Market Restraints
- Server infrastructure costs:Sixty-tick simulation rates for battle royale matches demand specialized low-latency hosting, concentrating operational expenditure among hyperscale cloud providers in North America and Western Europe.
- GDPR data localization:Cross-border player analytics and personalized pricing architectures face compliance friction, fragmenting user databases and raising engineering overhead for live-service operations.
- Content rating divergence:ESRB, PEGI, and NPPA age-gating requirements create catalog eligibility gaps, forcing region-specific build pipelines that extend release timelines and inflate quality assurance budgets.
Strategic Opportunities
- Brazil's unbanked gamer population:Pix instant payment integration and carrier billing penetration in Latin America's largest market unlock subscription and microtransaction revenue from demographics excluded from traditional card-based commerce.
- AI-driven matchmaking:Machine learning skill-rating systems are converging with behavioral prediction models to reduce churn through dynamic difficulty adjustment and personalized social group formation.
- India's PLI scheme for electronics manufacturing:Localized smartphone production incentives are expanding addressable device ownership among price-sensitive consumers, creating first-time battle royale audiences in tier-two and tier-three cities.
Industry Challenges
- Live-service engineering talent scarcity:The specialized skill set combining netcode optimization, anti-cheat systems, and seasonal content pipelines concentrates among veterans of established studios, constraining new entrant staffing.
- Cross-platform certification complexity:Simultaneous release across iOS, Android, PlayStation, Xbox, and PC requires navigating distinct technical certification timelines that compress content update cycles and strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battle Royale Games Market |
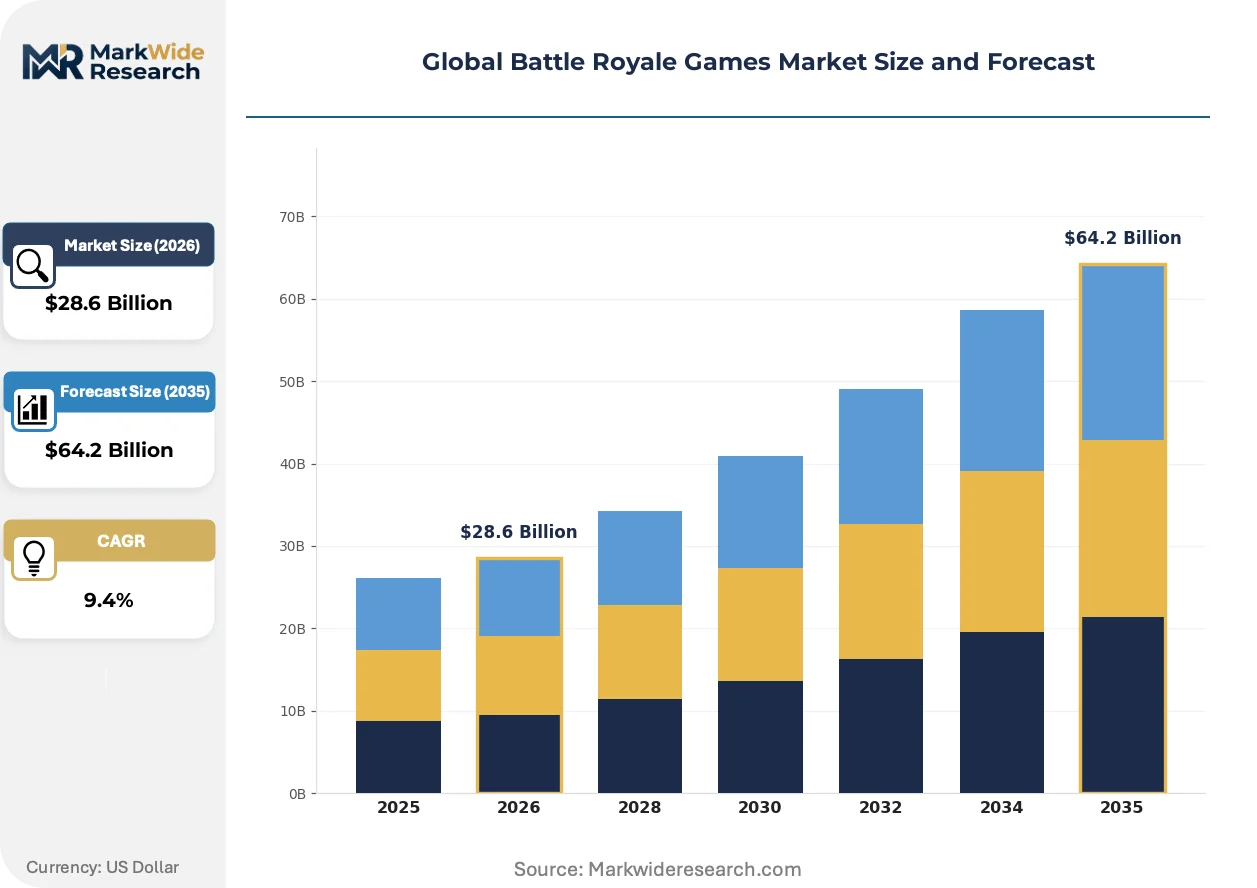
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Cloud Gaming Game Type: Free-to-Play, Paid, Multiplayer, Solo Monetization Model: In-Game Purchases, Battle Pass, Sponsorship, Ads Player Demographics: Teens, Young Adults, Adults, Casual Gamers |
| Companies Covered | Tencent, Electronic Arts, Epic Games, NetEase Games, Take-Two Interactive, Activision Blizzard, Riot Games, Microsoft Gaming, Krafton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battle Royale Games Market Emerging Trajectories
Unreal Engine licensing is decoupling development costs from proprietary technology stacks, enabling mid-size studios to compete on content velocity rather than capital-intensive engine investment.
Artificial intelligence-powered procedural content generation is converging with traditional handcrafted map design, compressing the seasonal update cycle from quarterly to monthly drops. Krafton and Tencent subsidiary studios are adopting hybrid pipelines that blend ML-generated terrain with manual balancing passes. This convergence is enabling smaller teams to maintain competitive content cadence against established live-service operations.
China's NPPA continues tightening approval timelines and monetization disclosure standards, forcing publishers to front-load compliance documentation and abandon opaque loot box mechanics. Studios with existing greenlit titles gain structural advantage as new entrants face extended queue times for commercial launch authorization. The PC-to-mobile adaptation segment bears the heaviest documentation burden given cross-platform revenue recognition complexity.
Battle pass subscription models are displacing ad-supported monetization among competitive player segments, particularly in Brazil and Mexico where carrier billing integration reduces payment friction. Publishers are unbundling cosmetic tiers into time-limited seasonal structures that create artificial scarcity and compress purchase decision windows. This behavioral shift is most visible in mobile-first markets where session length constraints favor predictable monthly expenditure over unpredictable reward chasing.
Global Battle Royale Games Market Segmentation
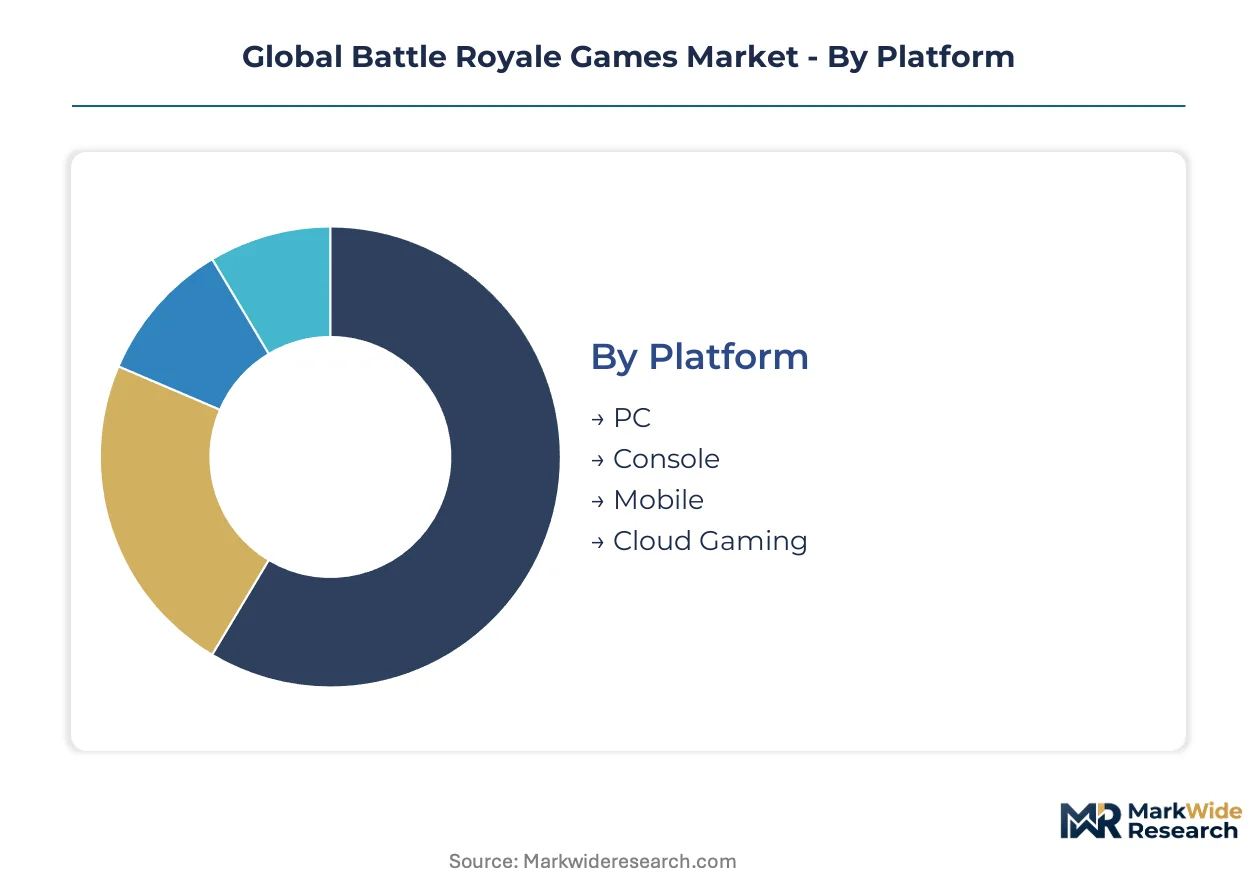
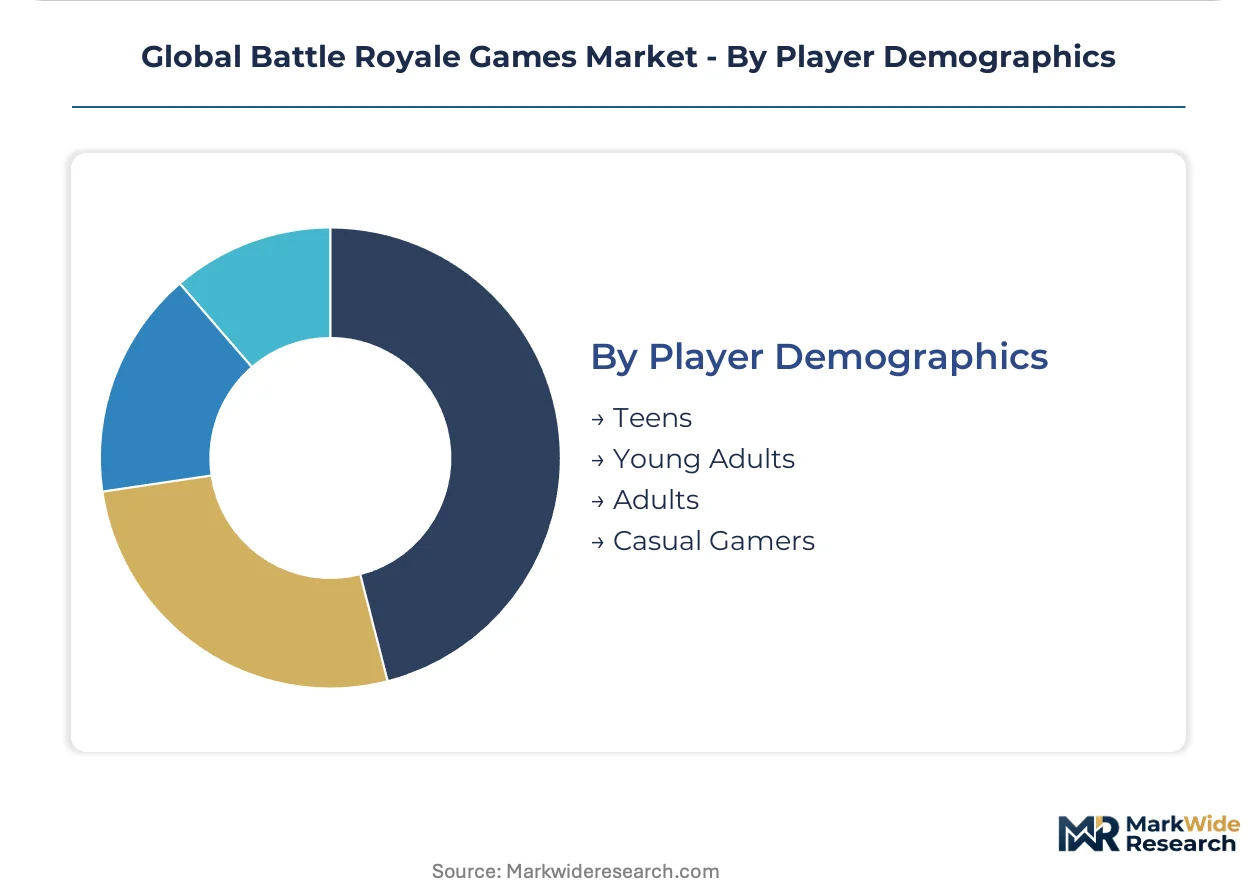
Battle royale market segmentation reveals how hardware refresh cycles, payment infrastructure maturity, and regulatory age-gating collectively determine addressable revenue pools. Platform and monetization splits expose where infrastructure investments yield the highest lifetime value capture.
Platform:
Hardware upgrade cadences and network latency requirements fragment development priorities across device categories.
- PC:High-refresh-rate displays and dedicated GPUs enable sixty-tick server synchronization that competitive players demand. North American and Western European esports circuits anchor monetization through premium cosmetic tiers and tournament entry fees.
- Console:Controller-native input schemes and standardized hardware generations reduce optimization overhead for studios. Sony PlayStation and Microsoft Xbox certification timelines compress seasonal content pipelines.
- Mobile:Mid-tier smartphones in India and Brazil drive volume through touch-optimized control schemes and carrier billing integration. 5G rollouts in South Korea and Japan are narrowing the fidelity gap with console experiences.
- Cloud Gaming:Edge server proximity determines latency feasibility, concentrating viable deployments near hyperscale data centers in Japan and South Korea. Subscription bundling with telecom operators masks infrastructure costs from end users.
Volume placements concentrate in Mobile; the faster expansion belongs to Cloud Gaming.
Game Type:
Entry cost structures and social mechanics orientation shape player acquisition economics and retention engineering.
- Free-to-Play:Zero upfront friction maximizes addressable audience in price-sensitive markets like Brazil and India. Revenue depends entirely on battle pass conversion and cosmetic attachment rates among engaged cohorts.
- Paid:Upfront purchase filters for committed players with higher session value and lower churn. Premium positioning aligns with PC and console platforms where hardware investment signals spending willingness.
- Multiplayer:Squad-based social loops drive viral acquisition through friend-group network effects. China's NPPA restrictions on youth gaming time have compressed average squad session lengths.
- Solo:Skill-expression focus attracts competitive players seeking ranked ladder progression. Matchmaking algorithm quality directly determines retention in this mechanically demanding format.
Free-to-Play commands absolute volume; Paid is gaining share fastest among adult demographics with disposable income.
Monetization Model:
Revenue predictability and regulatory scrutiny intensity vary sharply across pricing architectures.
- In-Game Purchases:Direct cosmetic sales bypass chance-based mechanics that trigger gambling regulation in European markets. Item shop rotation cadences create artificial scarcity that compresses purchase decision windows.
- Battle Pass:Seasonal subscription structures deliver the most predictable revenue stream with measurable churn rates. Brazil's Pix instant payment integration and Southeast Asian carrier billing have reduced payment friction for this model.
- Sponsorship:Brand integration revenue concentrates in established titles with broadcast-ready esports viewership. Telecom operators in Southeast Asia underwrite prize pools that subsidize player acquisition costs.
- Ads:Rewarded video placement generates revenue from non-paying users but introduces session interruption that elevates churn. This model dominates in markets with underdeveloped card-based payment infrastructure.
Battle Pass structures anchor revenue stability; Sponsorship is climbing the fastest as esports viewership professionalizes.
Player Demographics:
Age-gating enforcement and disposable income distribution determine monetization ceiling per cohort.
- Teens:China's MIIT time restrictions and Europe's GDPR parental consent requirements fragment access and data collection capabilities. Studios have shifted toward cosmetic-only monetization to avoid pay-to-win accusations.
- Young Adults:Peak competitive engagement hours and highest battle pass conversion rates define this cohort. University-aged players in the United States and South Korea drive seasonal content consumption velocity.
- Adults:Disposable income concentration supports premium cosmetic tiers and limited-time event spending. This demographic shows lowest price sensitivity to battle pass price increases.
- Casual Gamers:Irregular session patterns favor ad-supported or low-commitment monetization over subscription structures. Mobile platforms capture this audience through shortened match formats.
Young Adults generate the highest revenue per user; Adults are expanding most quickly as aging player cohorts retain platform loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unreal Engine licensing fees and cloud infrastructure investments concentrate development capital in jurisdictions with established hyperscale data center clusters and favorable digital trade frameworks.
United States
Esports tournament pipelines and premium cosmetic monetization anchor revenue in coastal tech corridors. The ESRB enforces age-gating and loot box disclosure standards that shape catalog eligibility. Seattle and Los Angeles host the densest concentrations of live-service engineering talent and anti-cheat system vendors.
China
MIIT youth gaming restrictions and NPPA approval queues compress playtime volumes for minors while elevating adult revenue-per-hour targets. Studios front-load compliance documentation for cross-platform titles. Shenzhen and Hangzhou anchor the PC-to-mobile adaptation pipeline that defines regional release sequencing.
South Korea
5G network rollouts and edge server proximity enable console-fidelity cloud gaming on mid-tier smartphones. The MFDS and KCC regulate data localization for player analytics. Seoul anchors esports infrastructure investment from SK Telecom and KT Corporation that underwrites prize pool sustainability.
Japan
Mobile esports viewership and gacha monetization heritage create receptive audiences for battle pass seasonal structures. METI guidelines on consumer protection influence disclosure requirements for chance-based mechanics. Tokyo and Osaka concentrate publisher headquarters and arcade-to-mobile adaptation expertise.
Brazil
Pix instant payment integration and carrier billing penetration unlock microtransaction revenue from previously unbanked demographics. ANVISA and consumer protection agencies monitor age verification enforcement. São Paulo anchors Latin America's fastest-growing demand concentration for mobile-first battle royale titles.
Global Battle Royale Games Market Vendor Landscape
Technology licensing dominates the current landscape, with engine providers extracting rents from studios competing on content velocity rather than proprietary tool investment. The vendor base stratifies across three tiers: integrated platform holders with captive distribution, specialized live-service operators with netcode expertise, and mid-size studios licensing third-party infrastructure. Strategic archetypes include dual-revenue engine licensors, geographic portfolio diversifiers through minority equity stakes, and PC-to-mobile adaptation specialists. Competitive moves concentrate on M&A for live-service engineering talent and strategic partnerships with telecom operators for zero-rating distribution.
Within the integrated platform tier, Tencent and Microsoft Gaming exemplify archetypes of geographic diversification through studio equity stakes and captive cloud infrastructure deployment. Epic Games occupies a distinct position as both first-party publisher and engine licensor, extracting value from the same technology stack through dual revenue architectures. Krafton represents the adaptation specialist archetype, anchoring expertise in PC-to-mobile pipeline execution that defines regional release strategies for competitive shooters.
| Leading Market Players |
|---|
| Tencent |
| Electronic Arts |
| Epic Games |
| NetEase Games |
| Take-Two Interactive |
| Activision Blizzard |
| Riot Games |
| Microsoft Gaming |
| Krafton |
| Others |
Supply Flow & Price Mechanics
Premium-engine-licensing tiers bifurcate sharply from proprietary-technology stacks, compressing development costs for mid-size studios while concentrating pricing power among Unreal Engine and Unity licensors who extract per-title royalties. This divergence manifests in supply chains where hyperscale cloud providers in North America and Western Europe dominate low-latency server hosting, while carrier billing partnerships in Brazil and Southeast Asia reshape downstream monetization economics.
Pricing Analysis
Live-service warranty bundling separates premium support tiers from standard engine licensing, with Epic Games and Unity offering dedicated netcode optimization assistance and anti-cheat integration at elevated rates. Three-tier pricing structure across premium, standard, and economy levels tracks content velocity commitments and seasonal update cadences. Cost compression in mid-tier mobile development is intensifying because telecom operators demand revenue-sharing concessions for zero-rating distribution. Price-sensitive indie studios in India and Brazil gravitate toward royalty-deferred licensing, while AAA publishers in the United States and South Korea absorb premium tiers for dedicated account management.
Supply Chain Analysis
Cross-border data transit costs and edge server proximity requirements concentrate hyperscale infrastructure investment in Japan, South Korea, and the United States. Netcode optimization talent draws from established studios in Seattle, Los Angeles, and Seoul, creating single-source vulnerability for live-service engineering. Distribution runs through platform-holder certification pipelines—Apple App Store, Google Play, Sony PlayStation, and Microsoft Xbox—each extracting platform fees that compound with engine royalties. Supply chain risk centers on regulatory fragmentation: China's NPPA approval queues and Europe's GDPR data localization mandates force redundant server deployments that inflate operational overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races dominate competitive positioning, with publishers pursuing captive cloud infrastructure and in-house engine development to escape per-title licensing burdens. The upstream lever of netcode optimization talent acquisition determines live-service viability.
For Market Incumbents: Acquire specialized live-service engineering teams with sixty-tick server synchronization expertise. Consolidate anti-cheat system vendors in North America and Western Europe before talent scarcity elevates compensation premiums. Defensive moves should prioritize backward integration into edge server deployments near hyperscale data centers, insulating against hyperscaler pricing power. Threats from emerging cloud-native entrants with serverless architectures demand preemptive capacity commitments. For New Entrants and Emerging Players: Telecom operators in Southeast Asia and Latin America represent the most penetrable channel partnership tier for zero-rating distribution deals. White-space targets concentrate in Brazil's unbanked gamer population and India's tier-two cities where localized smartphone production expands device ownership. Carrier billing integration and Pix instant payment adoption unlock subscription revenue without card-based commerce infrastructure. Go-to-market positioning should emphasize compressed seasonal content cycles enabled by AI-assisted procedural generation. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-holder acquisition of adaptation specialists with proven PC-to-mobile pipelines. Long-term viability hinges on regulatory arbitrage capabilities—studios with existing NPPA greenlit titles command structural premiums as approval queues extend. Acquisition target archetypes include mid-size studios with hybrid ML-handcrafted content pipelines and established telecom partnerships. The signal to watch is MIIT enforcement intensity: further youth gaming restrictions would accelerate adult-demographic monetization specialization.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Service Engineering Acquisition | Netcode optimization talent in Seattle and Seoul commands scarcity premiums that determine update cadence competitiveness. |
| Carrier Billing Partnership Expansion | SK Telecom and KT Corporation zero-rating bundles in South Korea reduce player acquisition costs below platform-holder fees. |
| AI-Assisted Content Pipeline Deployment | Machine learning terrain generation compresses seasonal drops from quarterly to monthly against established live-service operations. |
| Edge Server Infrastructure Buildout | Proximity to hyperscale data centers in Japan and South Korea determines cloud gaming latency feasibility for mid-tier smartphones. |
| Regulatory Compliance Front-Loading | NPPA documentation preparation for cross-platform titles accelerates commercial launch authorization amid extended approval queues. |
Methodological Framework
Independent corroboration across live-service engineering directors, platform certification leads, and telecom partnership managers underwrites the qualitative findings. Primary interviews with anti-cheat system vendors in North America, mobile esports tournament organizers in Southeast Asia, and regulatory affairs specialists navigating China's NPPA complemented secondary validation. Secondary sources include SEC filings from publicly traded publishers, Sensor Tower mobile revenue estimates, hyperscaler capex disclosures for cloud infrastructure, and MIIT regulatory bulletins. Bottom-up triangulation across individual title performance metrics and top-down validation against aggregate platform revenue disclosures anchored the market sizing.
Comparable-period anchoring to historical mobile esports investment cycles and console hardware refresh cadences structured the projection horizon. The analytical framework models platform splits, monetization model adoption curves, and geographic regulatory clusters across the analysis window. Segmentation dimensions include deployment architecture, player demographic cohorts, and regional payment infrastructure maturity. CAGRs derive from installed base growth in Brazil and India, 5G penetration trajectories in East Asia, and battle pass conversion rate benchmarks from established titles. Forecast inputs incorporate cloud gaming latency compression curves and AI content generation adoption slopes.
Caveats apply where MIIT enforcement intensity, GDPR data localization rulings, or hyperscaler pricing adjustments could materially shift the outlook. Forecasts reflect assumptions about carrier billing penetration in unbanked markets and NPPA approval velocity for cross-platform titles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Africa Gaming Market
Gaming
Europe Casino Gambling Market
Gaming
Global Gaming Headset Market
Gaming
Mobile Gaming Market
Gaming
AAA Games Market
Gaming
Global Trading Card Games Market
Gaming
SLG Game Market
Gaming
VR Gaming Market
Gaming
Galgames Market
Gaming
Gaming Gadgets Market
Gaming
Global Online Gambling and Betting Market
Gaming
Board Games Market
Gaming
VR Gaming Controller Market
Gaming
FPS Game Market
Gaming
Gaming Software Market
Gaming
Flat Gaming Monitors Market