
 United States Gaming Accessories Market | 2026-2036
United States Gaming Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gaming Accessories Market Analytics
Domestic peripheral manufacturing is decoupling from sole reliance on overseas assembly, with specialty producers building modular capacity in Nevada and Arizona. Logitech International SA leverages its Swiss-American engineering footprint to sustain premium keyboard and mouse development from its Newark, California headquarters. Turtle Beach Corporation anchors its audio specialization through San Diego-based acoustic R&D, while Razer Inc. competes via aggressive positioning in the streamer peripheral segment with its Irvine, California operations.
United States gaming accessories encompass input devices, audio equipment, and display peripherals engineered for sub-millisecond latency, mechanical switch actuation forces between 45-60 grams, and driver diameters optimized for spatial audio positioning in competitive environments. Controllers and headsets capture the largest revenue pools due to console ecosystem bundling and voice-chat dependency in squad-based titles. Keyboards and mice represent the fastest-expanding margin category as mechanical switch customization and ultralight sensor technology attract professional gamers and content creators. End-user segmentation shows professional gamers and esports teams concentrating spending in premium and luxury tiers, while casual gamers sustain volume through budget and mid-range channels.
FCC equipment authorization mandates electromagnetic compatibility testing for wireless controllers and headsets, while California's Proposition 65 requires chemical disclosure labeling on plastic components and cables sold into the state. The Consumer Product Safety Commission monitors battery safety in wireless peripherals, and the FTC enforces advertising claims around performance specifications. Stakeholders must monitor evolving state-level right-to-repair legislation and its impact on aftermarket controller modification businesses, as repair access rules could reshape warranty structures and spare parts distribution economics.
Market Dynamics
Console refresh cycles and FCC equipment authorization timelines are compressing product development windows, forcing peripheral makers to synchronize hardware launches with platform ecosystem updates while absorbing electromagnetic compatibility testing costs that favor scaled manufacturers.
Growth Catalysts
- Esports venue construction:Dedicated arenas in California, Texas, and Washington state are outfitting broadcast-ready peripheral suites that standardize sponsor equipment specifications and drive bulk procurement of matching controller and headset inventories.
- REACH chemical disclosure alignment:California's Proposition 65 labeling requirements for plasticizers and flame retardants are pushing domestic assemblers toward pre-certified component sourcing that accelerates time-to-market for West Coast distribution.
- Mechanical switch customization:Hot-swappable keyboard architectures let end-users replace actuation mechanisms without soldering, extending product lifecycles and creating aftermarket revenue streams for switch manufacturers.
Market Restraints
- Rare earth magnet dependence:Precision driver assemblies in high-fidelity headsets rely on neodymium supply chains concentrated in Chinese processing facilities, exposing audio specialists to export quota volatility and tariff exposure.
- FCC authorization backlog:Wireless peripheral submissions face electromagnetic compatibility review queues that stretch development timelines, disadvantaging smaller vendors lacking pre-certified radio module partnerships.
- Silicon sensor allocation:Optical mouse sensor dice compete with automotive lidar and smartphone camera modules for foundry capacity, constraining ultralight gaming mouse production during semiconductor supply crunches.
Strategic Opportunities
- Right-to-repair legislative tailwinds:State-level repair access mandates advancing in New York, Minnesota, and Oregon could legitimize aftermarket controller modification businesses and create spare parts distribution channels currently operating in warranty gray zones.
- Cloud gaming latency tolerance:Streaming platform subscribers accept higher input lag than dedicated hardware users, opening peripheral tiers optimized for casual responsiveness rather than sub-millisecond competition-grade specifications.
- Biometric sensor convergence:Heart rate and galvanic skin response modules from fitness wearable supply chains are migrating into stress-monitoring gaming chairs and grip-sensitive controllers for streamer content generation.
Industry Challenges
- Acoustic engineering talent scarcity:Spatial audio algorithm development for competitive positioning requires signal processing specialists whose expertise concentrates in defense and automotive sectors, forcing gaming audio vendors to bid against non-consumer employers.
- Battery safety certification timelines:Lithium-polymer cells in wireless peripherals face Consumer Product Safety Commission testing protocols that add months to product launches, compressing margin recovery windows before next-generation platform releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gaming Accessories Market |
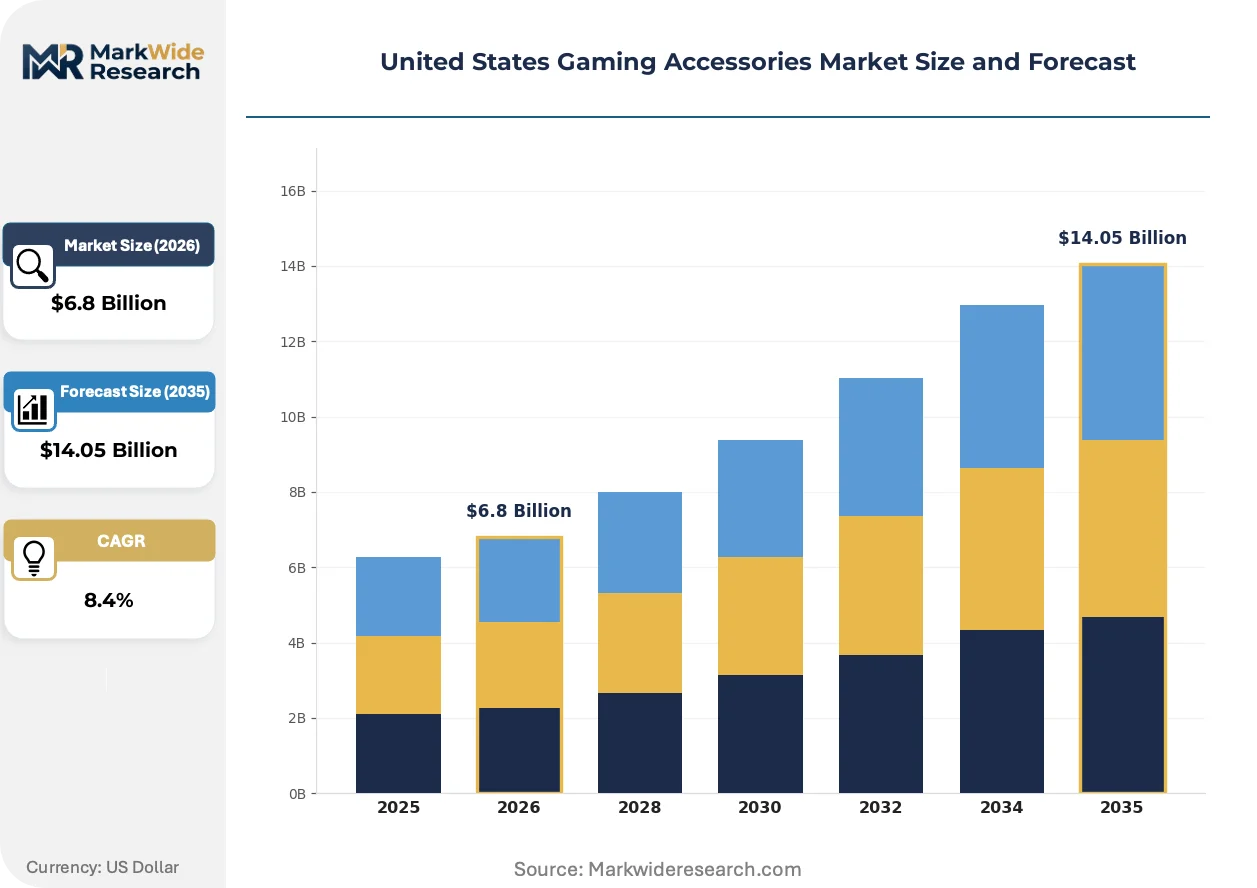
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Headsets, Keyboards, Mice End User: Casual Gamers, Professional Gamers, Streamers, eSports Teams Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, Wholesale Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Logitech International SA, Turtle Beach Corporation, Razer Inc., Corsair Gaming Inc, HyperX, SteelSeries, PowerA, Performance Designed Products LLC, Mad Catz Global Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gaming Accessories Market Evolving Landscape
Peripheral architectures are fragmenting between modular, upgradeable platforms and sealed, ecosystem-locked designs as manufacturers place diverging bets on hardware longevity versus replacement frequency.
Low-latency wireless protocols are unifying previously separate controller, headset, and keyboard connectivity standards. Esports teams and competitive leagues are mandating single-protocol tournament environments to eliminate interference variables. This convergence is compressing the RF engineering vendor landscape and concentrating certification expertise among firms with pre-validated hardware reference designs.
California's Proposition 65 enforcement against brominated flame retardants in cable jacketing is forcing domestic re-sourcing of PVC compounds. Peripheral assemblers in Nevada and Arizona are qualifying alternative halogen-free formulations that satisfy disclosure thresholds while maintaining flexibility specifications. The compliance burden falls heaviest on budget-tier producers lacking material science partnerships to absorb reformulation costs.
Streamer-led purchasing is displacing traditional retail discovery for gaming peripherals. Content creators unbox and benchmark hardware for audiences who replicate their configurations, compressing brand marketing effectiveness and elevating affiliate commission structures as the dominant customer acquisition channel. This pattern concentrates demand spikes around major influencer endorsements and fragments inventory planning predictability.
United States Gaming Accessories Market Segmentation
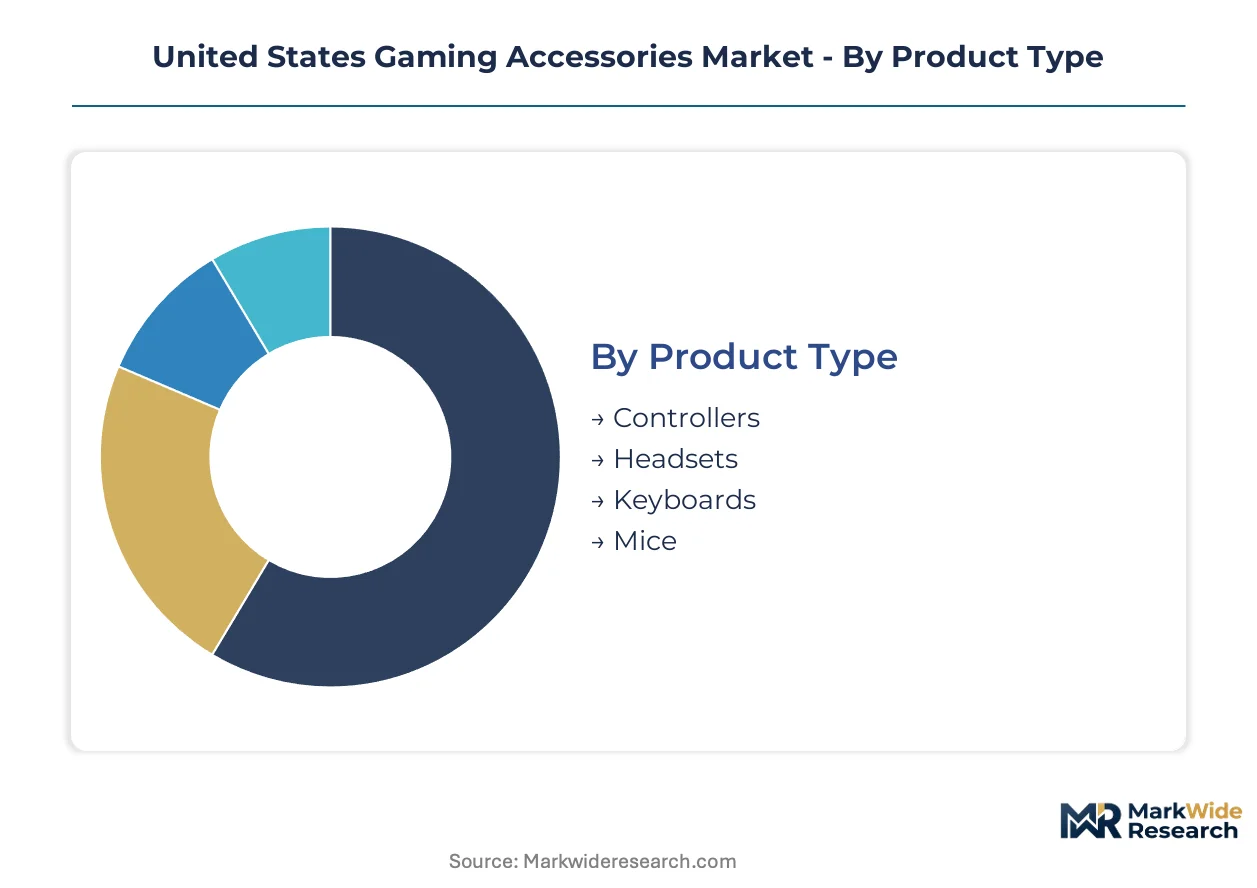
Segmentation in the United States gaming accessories market reveals how hardware specifications, purchasing behavior, and channel economics fragment across distinct user communities. Understanding these divides helps manufacturers align R&D investments with margin profiles and distribution leverage.
Product Type:
Customization intensity varies sharply across this category, from sealed console controllers to modular mechanical keyboards with hot-swappable switches.
- Controllers:Console ecosystem bundling drives volume concentration in Xbox and PlayStation-compatible variants. FCC equipment authorization requirements for wireless models compress development timelines for third-party manufacturers competing against first-party peripherals.
- Headsets:Spatial audio positioning algorithms and neodymium driver assemblies differentiate competitive-grade models from mass-market alternatives. California's esports venues and Texas streaming studios anchor demand for broadcast-quality microphone arrays and noise cancellation.
- Keyboards:Mechanical switch actuation forces between 45-60 grams and hot-swappable PCB architectures define enthusiast specifications. Aftermarket switch revenue streams extend product lifecycles beyond traditional replacement cycles.
- Mice:Ultralight sensor technology and sub-millisecond polling rates target professional gamers in Washington state's console ecosystem hubs.
Most installed capacity flows through controllers. Expansion is steepest in keyboards.
End User:
Spending concentration tilts toward users who monetize gameplay through competition or content creation rather than pure recreation.
- Casual Gamers:Budget-tier procurement through mass retail channels sustains volume baselines. Price sensitivity limits attachment rates for premium peripherals outside gift-purchase occasions.
- Professional Gamers:Sub-millisecond latency requirements and sponsor-mandated equipment standardization drive premium-tier concentration. Esports league contracts enforce peripheral uniformity across tournament environments.
- Streamers:Aesthetic customization and affiliate commission structures shape purchasing decisions, with hardware unboxing content directly influencing audience replication behavior.
- eSports Teams:Bulk procurement of matching peripheral suites for training facilities and broadcast appearances creates predictable enterprise-grade demand cycles tied to venue construction.
Professional gamers command the highest per-capita spend. Streamers are expanding most quickly as an addressable segment.
Distribution Channel:
Channel selection determines margin recovery speed and inventory risk exposure across product refresh cycles.
- Online Retail:Amazon and specialized gaming hardware platforms dominate discovery for enthusiast-tier specifications. Review aggregation and comparison tools accelerate decision compression for technical buyers.
- Brick-and-Mortar:Best Buy and Micro Center locations in California, Texas, and Washington state provide hands-on switch testing and immediate fulfillment for latency-sensitive purchases.
- Direct Sales:Manufacturer-controlled storefronts capture full margin on limited-edition collaborations and customization services, bypassing platform commission structures.
- Wholesale:Esports venue outfitters and collegiate gaming program procurement offices source through distributor relationships for standardized peripheral deployments.
Online retail channels carry the heaviest transaction volume. Direct sales channels show the steepest expansion trajectory as manufacturers build captive customer databases.
Price Tier:
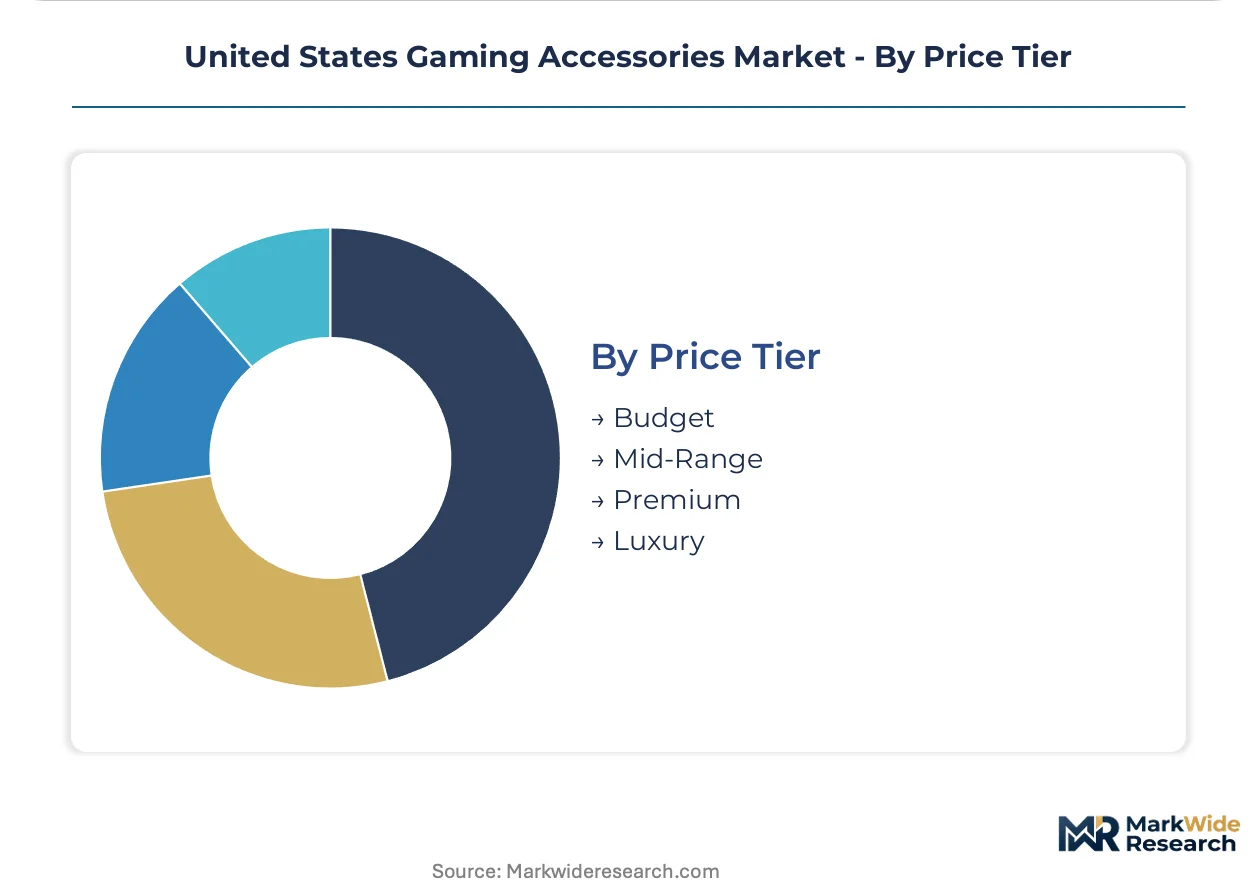
Margin architecture stratifies across tiers with minimal overlap in component sourcing and certification burden.
- Budget:Plasticizer and flame retardant compliance with California Proposition 65 disclosure thresholds consumes disproportionate cost structure for domestic assemblers lacking material science partnerships.
- Mid-Range:Wireless connectivity and basic mechanical switch implementations satisfy mainstream enthusiast requirements without boutique customization premiums.
- Premium:Low-latency wireless protocol integration and tournament-grade specifications attract professional gamers and esports team procurement.
- Luxury:Limited production runs, artisan keycap materials, and influencer collaboration branding command price multiples detached from functional performance metrics.
Mid-range tiers absorb the majority of unit volume. Premium tiers gain share fastest as streaming culture elevates peripheral visibility to lifestyle signaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's esports infrastructure outpaces Texas's influencer-driven procurement velocity, while Washington state's console ecosystem concentration creates distinct demand profiles across the United States gaming accessories landscape.
California
Esports venue construction in Los Angeles and San Francisco drives bulk procurement of broadcast-ready peripheral suites for tournament standardization. FCC equipment authorization requirements for wireless controllers compress development timelines for third-party manufacturers distributing through West Coast channels. San Diego anchors acoustic R&D specialization, with audio vendors qualifying halogen-free cable formulations to satisfy Proposition 65 disclosure thresholds.
Texas
Streamer-led purchasing patterns concentrate in Austin and Dallas, where content creator affiliate networks shape hardware discovery and replication behavior. The state's right-to-repair legislative momentum in Houston and San Antonio could legitimize aftermarket controller modification businesses currently operating in warranty gray zones. Dallas-Fort Worth distribution hubs expedite fulfillment for latency-sensitive peripheral replacements.
Washington
Console ecosystem bundling in Seattle and Redmond sustains volume concentration for Xbox-compatible controller variants. FTC advertising enforcement around performance specifications affects marketing claims for peripherals targeting the region's professional gamer density. Bellevue hosts specialized procurement offices for esports team peripheral standardization across training facilities.
Nevada
Modular assembly capacity expansion near Las Vegas reduces sole reliance on overseas production for domestic peripheral manufacturing. California's Proposition 65 chemical disclosure rules push Nevada-based assemblers toward pre-certified component sourcing to accelerate West Coast distribution timelines. Reno logistics corridors support just-in-time inventory positioning for Southwest retail channels.
Arizona
Specialty producers building mechanical keyboard assembly lines in Phoenix qualify alternative PVC compounds free of brominated flame retardants. The state's proximity to California distribution networks reduces compliance burden transit costs for budget-tier manufacturers lacking material science partnerships. Tucson emerging as a secondary hub for wireless peripheral electromagnetic compatibility pre-testing.
United States Gaming Accessories Market Competitive Landscape
California producers anchor premium-tier engineering; Asian manufacturing specialists hold cost-optimized volume positions. The vendor base stratifies across three tiers: scaled multinationals with FCC pre-certification partnerships, mid-cap domestic assemblers with modular Nevada capacity, and boutique artisans serving luxury customization segments. Dominant competitive moves include backward integration into switch manufacturing and strategic partnerships with esports leagues for tournament equipment standardization.
Within the premium peripheral tier, Logitech International SA exemplifies Swiss-American engineering consolidation through its Newark headquarters positioning. Turtle Beach Corporation anchors audio specialization archetypes from its San Diego acoustic R&D base. Razer Inc. occupies the aggressive streamer-segment positioning vector through Irvine, California operations. These three entities represent distinct competitive postures: multinational scale leverage, acoustic engineering depth, and influencer-channel velocity respectively.
| Leading Market Players |
|---|
| Logitech International SA |
| Turtle Beach Corporation |
| Razer Inc. |
| Corsair Gaming Inc |
| HyperX |
| SteelSeries |
| PowerA |
| Performance Designed Products LLC |
| Mad Catz Global Limited |
| Others |
Value Network & Pricing Analysis
Backward integration into mechanical switch manufacturing anchors both supply security and premium pricing power for keyboard specialists, while FCC pre-certification partnerships compress margin recovery timelines for wireless peripheral assemblers competing at volume tiers.
Pricing Analysis
Capacity additions in Nevada and Arizona are reshaping price floors for domestically assembled peripherals, forcing overseas-dependent competitors into sharper discounting to maintain shelf presence. Three-tier pricing structure across premium, standard, and economy levels separates tournament-grade specifications with sub-millisecond latency guarantees from mass-market alternatives, with customization intensity and electromagnetic compatibility certification grade as the primary price differentiation drivers. Pricing pressure stems from rare earth magnet cost volatility in headset driver assemblies, with budget-tier manufacturers absorbing disproportionate impact. Casual gamers exhibit highest price sensitivity, while esports team procurement contracts demonstrate inelastic demand for standardized equipment suites.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese processing facilities, with secondary concentration in Japanese specialty metal refiners and emerging Australian extraction projects. Optical mouse sensor dice draw from Taiwanese foundry capacity, while mechanical switch components source from both German precision engineering houses and Chinese mass-production facilities. Single-source vulnerability concentrates in FCC-certified radio module supply, where pre-validated reference designs concentrate among three dominant vendors. Distribution runs through Amazon and specialized gaming hardware platforms for enthusiast tiers, with Best Buy and Micro Center anchoring brick-and-mortar fulfillment in California, Texas, and Washington state clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States gaming accessories market reads as a late-cycle quality story, with streamer-led purchasing and esports venue construction shifting demand toward premium specifications with visible brand differentiation.
For Market Incumbents: Anticipate margin compression from modular assembly capacity expansion in Nevada and Arizona by accelerating backward integration into switch manufacturing and securing exclusive FCC pre-certification partnerships. Defensive consolidation through captive acoustic R&D talent pools in San Diego and Irvine protects against signal processing specialist poaching by defense and automotive sectors. Channel control through direct-to-consumer storefronts captures full margin on limited-edition collaborations.
For New Entrants and Emerging Players: Aftermarket controller modification businesses operating in warranty gray zones represent an underserved buyer archetype with expanding legitimacy as right-to-repair legislation advances in New York, Minnesota, and Oregon. Cloud gaming subscribers accepting higher input latency than dedicated hardware users create a penetrable segment for peripherals optimized for casual responsiveness rather than competition-grade specifications. Go-to-market through streamer affiliate networks bypasses traditional retail discovery costs.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap domestic assemblers with modular Nevada capacity because California Proposition 65 compliance burdens disproportionately impact budget-tier competitors lacking material science partnerships. Long-term viability over a five-to-ten year window favors targets with established FCC equipment authorization pipelines and esports league standardization contracts. The signal to watch is state-level right-to-repair enforcement velocity as a demand inflection indicator for spare parts distribution channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Switch Manufacturing | Captive mechanical switch production secures margin control against neodymium price volatility and foundry allocation constraints. |
| FCC Pre-Certification Partnership Expansion | Pre-validated radio module relationships compress electromagnetic compatibility review timelines and disadvantage smaller competitors. |
| Esports League Standardization Contracts | Tournament equipment mandates create predictable bulk procurement cycles and lock out non-certified peripheral alternatives. |
| Halogen-Free Cable Formulation Qualification | Proposition 65-compliant PVC compounds from Arizona assemblers accelerate West Coast distribution without disclosure burden. |
| Streamer Affiliate Network Development | Influencer-channel revenue concentration displaces traditional marketing effectiveness and fragments inventory planning predictability. |
Research Methodology
Direct dialogue with peripheral engineering leads, esports team equipment managers, streaming content creators, and Nevada-based assembly operators grounded qualitative assessment, cross-referenced against FCC equipment authorization databases, California Proposition 65 enforcement records, SEC 10-K filings from listed gaming hardware vendors, and esports venue procurement disclosures. Bottom-up unit economics from component bill-of-materials analysis triangulated against top-down market sizing from retail channel audit data.
Segment-level projections across product type, end user archetype, distribution channel, and price tier fed into analytical framework spanning the projection horizon, with CAGRs derived from historical refresh cycle patterns and console ecosystem launch timelines. Forecast inputs incorporated semiconductor foundry capacity allocation trends for optical sensor dice and rare earth magnet export quota trajectories from Chinese processing facilities.
Underlying measurement precision varies by segment; professional gamer and esports team procurement carry tighter precision than casual gamer volume estimates due to sponsor contract disclosure requirements. Forecasts reflect assumptions around console refresh cycle synchronization and FCC authorization backlog resolution. A small set of triggers including right-to-repair legislative velocity and cloud gaming subscriber conversion rates warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Russia in-Game Advertising Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
Germany Gaming Headset Market
Gaming
Gaming Hardware Market
Gaming
Galgames Market
Gaming
Metaverse in Gaming Market
Gaming
Social Gaming Market
Gaming
Global Esports Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
Australia Gaming Gadgets Market
Gaming
Europe Gaming Peripherals Market
Gaming
Online Casino Market
Gaming
Casino Gaming Equipment Market
Gaming
Europe Serious Gaming Market
Gaming
Advanced Digital Gaming Market