
 China in-Game Advertising Market | 2026-2036
China in-Game Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
China in-Game Advertising Market Insights
China's eastern coastal digital infrastructure build-out is reshaping ad delivery latency benchmarks for interactive formats. Tencent leverages its WeChat ecosystem to sustain cross-platform user identity graphs that power precision targeting. miHoYo anchors premium rewarded inventory within its Genshin Impact title architecture. NetEase competes through proprietary ad-tech stacks embedded across its RPG portfolio.
In-game advertising denotes the placement of commercial messages within interactive entertainment software, delivered through SDK integrations that render interstitial, video, banner, or rewarded formats based on real-time bidding protocols and player session telemetry. Its primary commercial purpose converts non-paying player attention into advertiser-funded revenue streams that subsidize free-to-play game economics. Rewarded video formats command premium eCPM rates due to opt-in completion mechanics that guarantee engagement depth. Mobile platform inventory dominates volume flows given China's smartphone-first gaming demography. Freemium monetization models generate the largest addressable player bases for ad insertion.
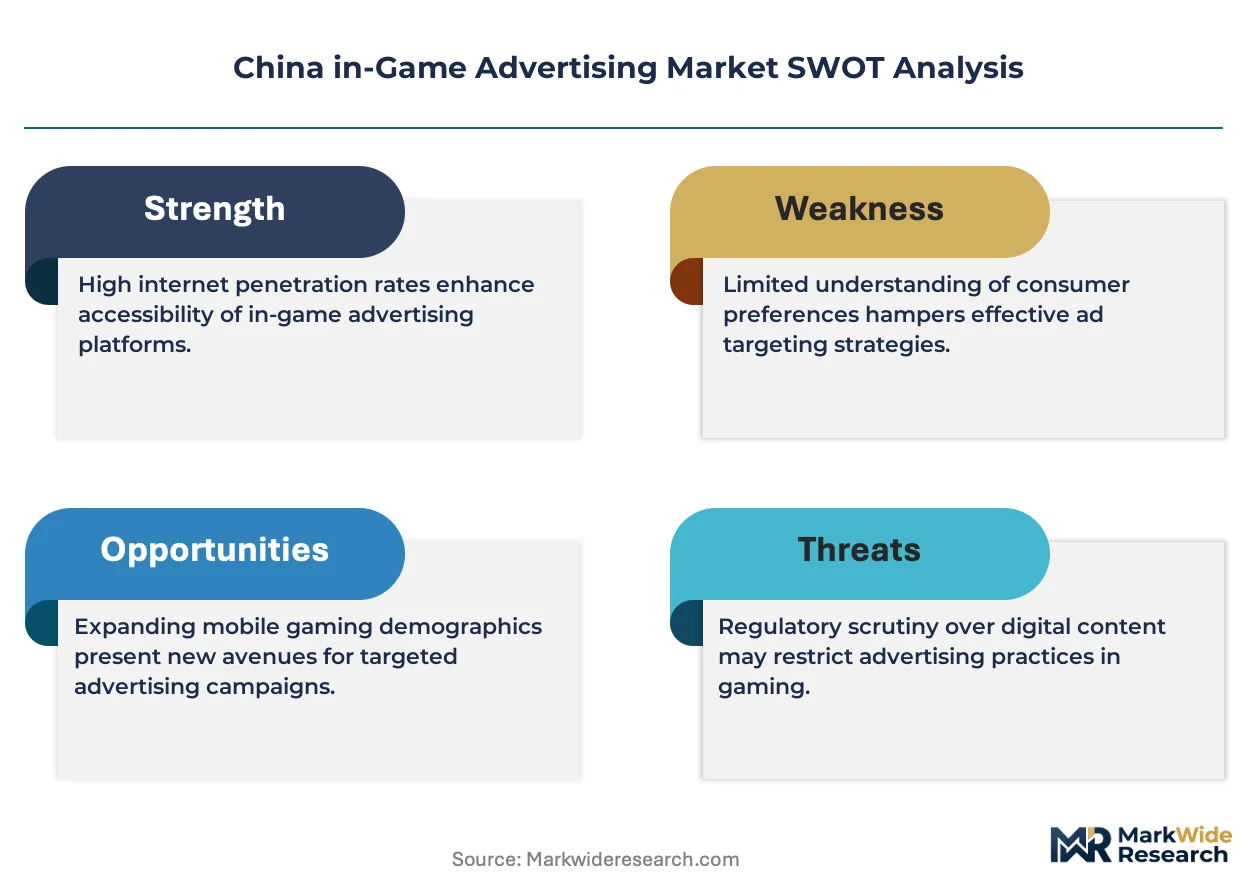
SAMR's advertising law enforcement and MIIT's data security governance jointly constrain cross-app tracking architectures that underpin Western programmatic models. The National Radio and Television Administration reviews creative content for ideological compliance before campaign activation. GB standards for personal information protection mandate explicit consent layers that lengthen ad load times. Stakeholders must weigh localization investment against the fragmentation of China's provincial internet regulatory interpretations.
Market Dynamics
Programmatic ad integration by tier-one mobile publishers is compressing traditional direct sales cycles while MIIT's data security governance forces reconstruction of identity-based targeting architectures.
Growth Catalysts
- Rewarded video mechanics:Opt-in completion guarantees in Genshin Impact and comparable titles command premium advertiser commitments unavailable through interstitial alternatives.
- WeChat ecosystem graphs:Cross-platform user identity resolution enables precision cohort targeting without violating SAMR's cross-app tracking constraints.
- Eastern coastal infrastructure:Shanghai and Beijing developer clusters benefit from sub-50ms latency benchmarks that unlock interactive ad format viability.
Market Restraints
- GB standards compliance:Explicit consent layer mandates lengthen ad load times by 300-800 milliseconds, degrading completion rates in bandwidth-constrained sessions.
- Provincial regulatory fragmentation:Divergent internet regulatory interpretations across Guangdong, Zhejiang, and Jiangsu provinces multiply localization investment requirements.
- Identifier deprecation:Loss of persistent device identifiers forces reliance on probabilistic fingerprinting with degraded match rates versus Western programmatic benchmarks.
Strategic Opportunities
- Lower-tier city expansion:Chengdu and Xi'an developer ecosystems remain underpenetrated for rewarded video inventory relative to saturation in Shanghai and Beijing.
- Cloud gaming convergence:5G edge computing deployments enable server-side ad rendering that bypasses device-level identifier restrictions entirely.
- Dual carbon mandate alignment:Carbon-neutral data center certification opens preferential placement within state-backed game publishing initiatives.
Industry Challenges
- Creative compliance velocity:National Radio and Television Administration content review cycles average 72 hours, compressing campaign launch windows for time-sensitive advertiser commitments.
- SDK integration complexity:Proprietary ad-tech stacks at major publishers require bespoke adapter development, fragmenting technical resource allocation across incompatible protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China in-Game Advertising Market |
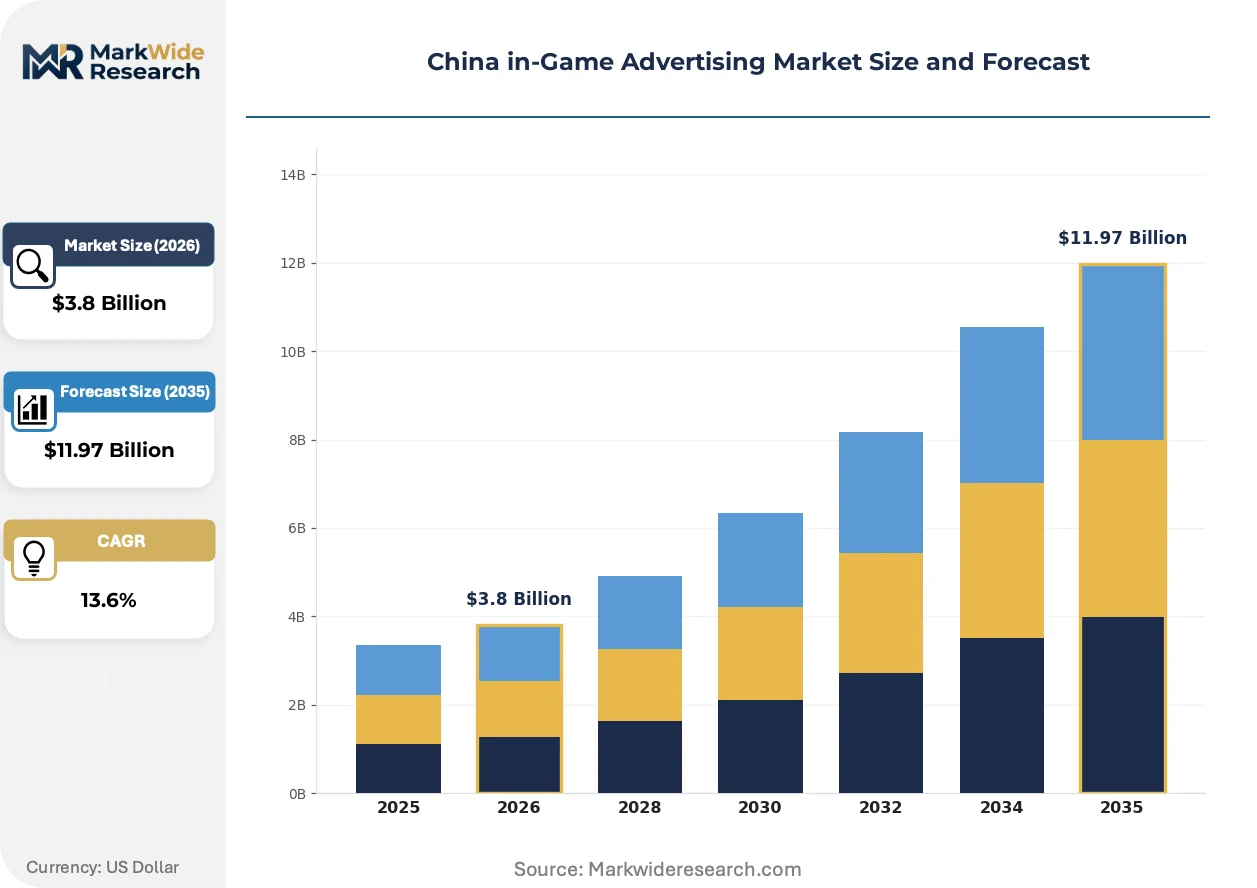
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Interstitial, Video, Banner, Rewarded Game Genre: Action, Puzzle, Sports, RPG Platform: Mobile, PC, Console, Cloud Monetization Model: Freemium, Premium, Subscription, In-App Purchases |
| Companies Covered | Tencent, NetEase, miHoYo, Perfect World, Huya, Douyu, Bilibili, iDreamSky, Shunrong, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China in-Game Advertising Market Trends and Innovations
Server-side rendering architectures are displacing client-side SDK dependencies as the dominant technical paradigm for ad insertion, while regulatory pressure on data residency accelerates domestic cloud infrastructure commitments.
Edge computing nodes deployed within China Mobile and China Unicom networks are collapsing the latency differential between interactive playable ads and static video formats. Mid-core RPG publishers in Hangzhou and Shenzhen are adopting these nodes for real-time bidding auctions that complete within 100 milliseconds. The compression of rendering latency is collapsing the format hierarchy that previously reserved interactive units for premium inventory tiers.
SAMR's 2024 advertising law enforcement circulars mandate pre-campaign creative archival with jurisdictional data residency requirements. This industrial consequence forces multinational advertisers to maintain separate creative asset pipelines for China versus other markets. RPG and strategy game categories with complex narrative content face the most severe compliance timeline extensions.
Advertiser procurement patterns are consolidating around outcome-based engagement guarantees rather than impression-volume commitments. Brand safety verification vendors are displacing traditional media buying agencies as the primary interface to publisher inventory. This behavioral shift is most visible among fintech and automotive advertisers operating in Shanghai's Lujiazui financial district.
China in-Game Advertising Market Segmentation
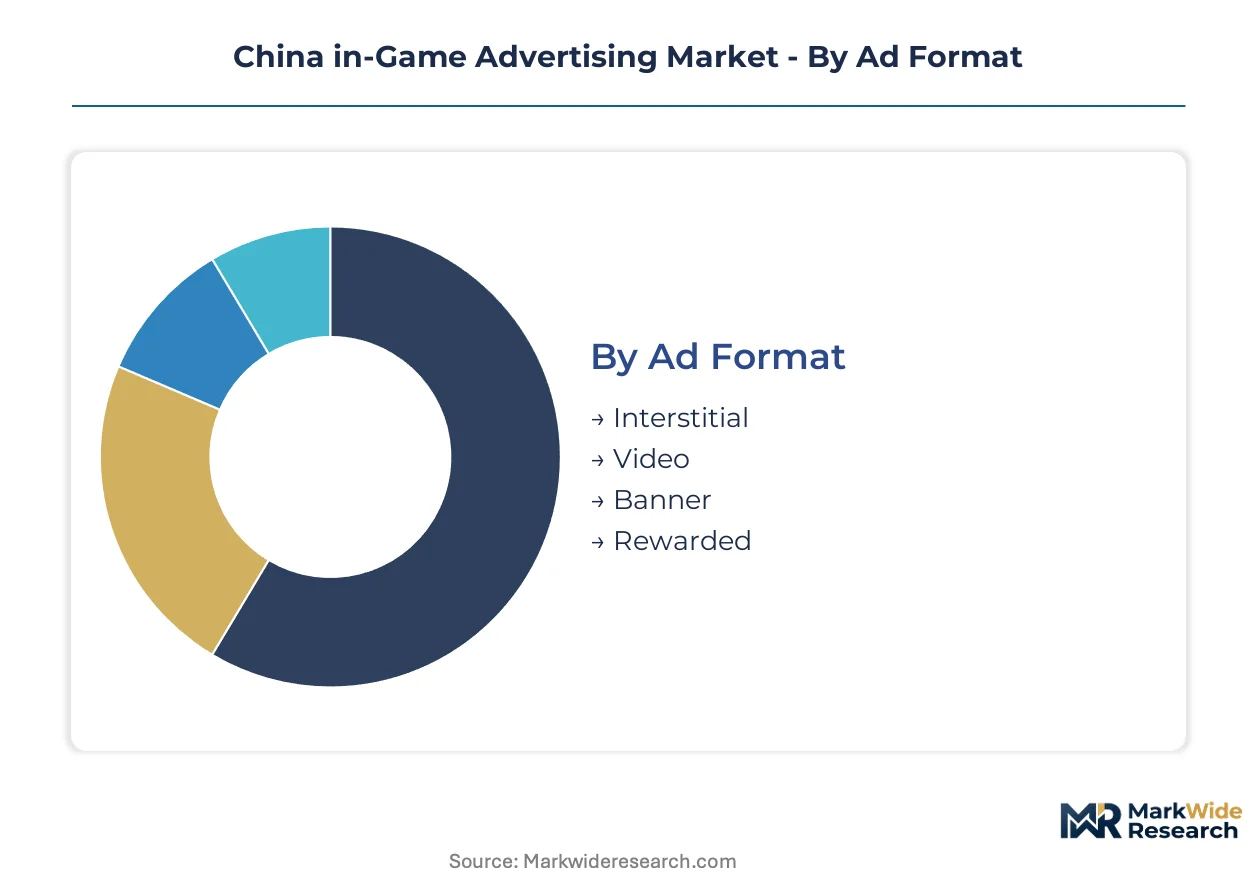
Ad format stratification determines inventory pricing hierarchies and creative compliance burdens across China's tier-one developer clusters. Platform fragmentation forces divergent technical architectures that reshape SDK integration economics for publishers targeting Shanghai versus lower-tier city audiences.
Ad Format:
Cost tier differentiation separates premium opt-in inventory from interruptive placements that trade eCPM efficiency for player retention risk.
- Rewarded:Opt-in video completion mechanics deliver guaranteed engagement depth. miHoYo deploys these units within Genshin Impact to capture advertiser commitments from fintech brands in Shanghai's Lujiazui district. SAMR's consent layer mandates extend load times but preserve premium rate cards.
- Video:Non-skippable mid-roll placements interrupt session flow at natural narrative breaks. Beijing RPG studios concentrate demand here for brand awareness campaigns targeting male demographics aged 18-35. Completion rates degrade under GB standards compliance latency.
- Interstitial:Full-screen transitional units trigger between game levels or match completions. Hyper-casual publishers in Shenzhen favor this format for volume-based arbitrage against low acquisition costs.
- Banner:Persistent display units anchored to screen periphery deliver continuous impression volume. Sports and puzzle genres integrate these for baseline monetization of non-paying player bases.
Rewarded holds installed capacity. Video is rotating up the share rankings.
Game Genre:
Application context dictates session length profiles that reshape ad frequency capping strategies and creative format viability.
- RPG:Extended session architectures support multiple ad insertion points without churn elevation. NetEase embeds proprietary ad-tech across its portfolio to capture recurring engagement from narrative-committed players. National Radio and Television Administration content review applies most stringently to fantasy narrative assets.
- Action:Competitive multiplayer sessions demand sub-50ms latency benchmarks that restrict interactive format deployment. Tencent's WeChat ecosystem integration enables cross-platform identity resolution for precision targeting within Honor of Kings.
- Puzzle:Casual session fragmentation favors high-frequency banner and interstitial rotation. Chengdu developers underpenetrate rewarded video relative to Beijing saturation.
- Sports:Licensed IP content triggers additional compliance layers for athlete likeness and stadium branding. Seasonal event calendars compress campaign launch windows.
RPG commands the deepest advertiser commitments. Action is climbing the fastest on 5G edge infrastructure deployment.
Platform:
Volume concentration tracks China's smartphone-first gaming demography while emerging channels reshape technical delivery paradigms.
- Mobile:Dominant inventory flow driven by 900 million-plus smartphone gamers. MIIT's data security governance forces reconstruction of identity-based targeting architectures across iOS and Android SDK integrations.
- Cloud:Server-side rendering bypasses device-level identifier restrictions entirely. China Mobile edge nodes enable real-time bidding auctions completing within 100 milliseconds.
- PC:Client-based MMO architectures sustain longer session durations with lower ad frequency tolerance. Steam China compliance adds distribution friction.
- Console:Niche addressable base constrained by hardware import regulations and content licensing delays. PlayStation and Nintendo Switch presence remains sub-scale.
Mobile holds installed capacity. Cloud is rotating up the share rankings.
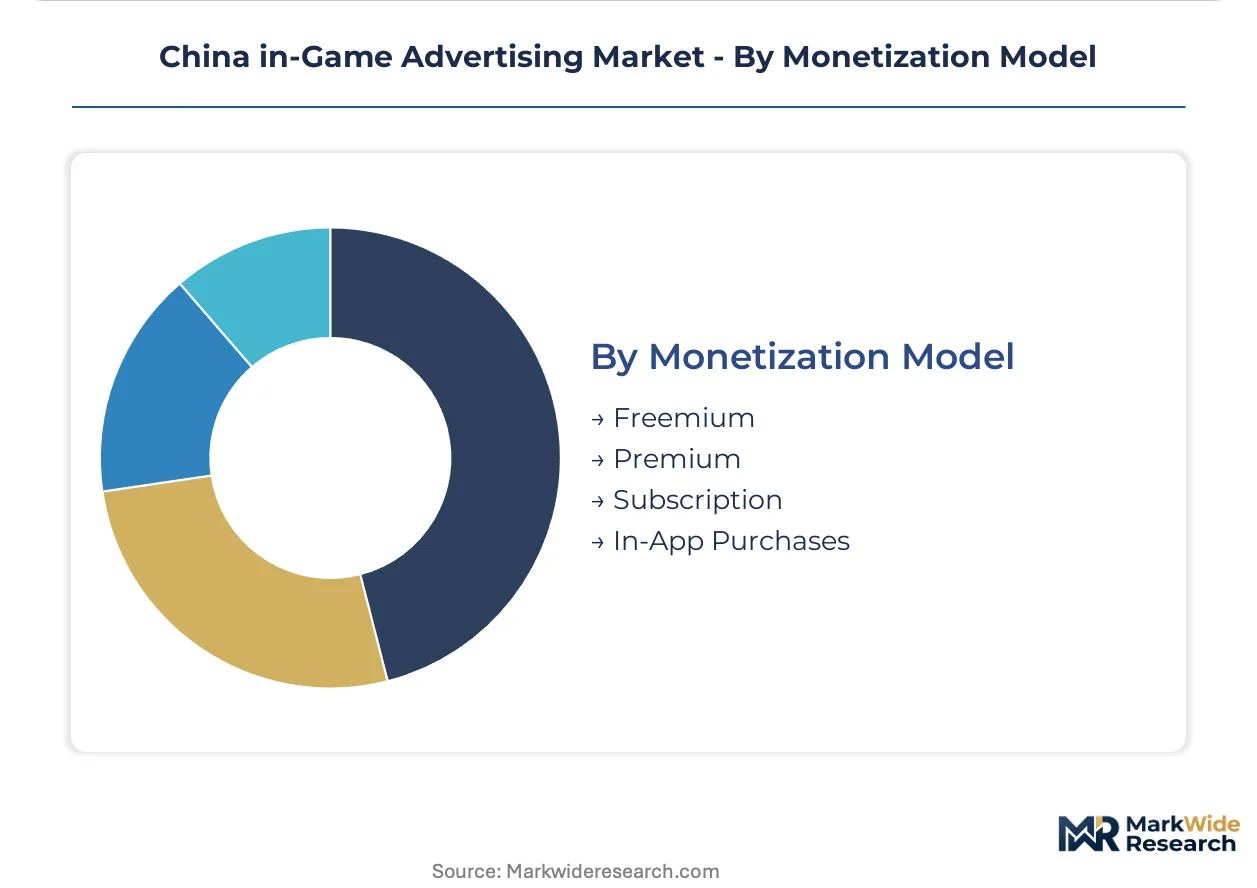
Monetization Model:
Customer type segmentation separates attention-funded from transaction-funded revenue streams with divergent ad load tolerance thresholds.
- Freemium:Largest addressable player base subsidized entirely by advertiser-funded revenue. Tier-one cities show rewarded video saturation while Chengdu and Xi'an ecosystems remain underpenetrated.
- In-App Purchases:Hybrid models reserve premium inventory tiers for non-paying cohorts while suppressing ads for whale segments. Precision segmentation demands robust first-party data graphs.
- Subscription:Ad-free commitments remove inventory from programmatic pools. NetEase and Tencent deploy these for VIP retention in competitive RPG categories.
- Premium:Upfront purchase models eliminate ad insertion entirely. Niche presence in narrative-driven single-player content.
Freemium holds installed capacity. In-App Purchases is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's in-game advertising market concentrates in three coastal megaclusters where developer density, data infrastructure, and regulatory proximity intersect. Eastern provinces generate the dominant share of rewarded video inventory and programmatic ad technology deployment.
Yangtze River Delta
Shanghai anchors the nation's highest-density rewarded video ecosystem, with miHoYo and NetEase headquarters driving premium inventory creation. SAMR's advertising law enforcement applies most stringently here, forcing 72-hour creative compliance cycles. Pudong and Zhangjiang Hi-Tech Park host the majority of domestic ad-tech engineering talent.
Pearl River Delta
Shenzhen's hyper-casual publisher clusters favor interstitial and banner volume plays against low user acquisition costs. MIIT's data security governance has forced reconstruction of identity-based targeting architectures across local SDK integrations. Nanshan district concentrates the technical adapter development teams serving proprietary publisher stacks.
Beijing-Tianjin-Hebei
Beijing's RPG studios concentrate non-skippable video demand for male demographic brand awareness campaigns. National Radio and Television Administration content review cycles compress campaign launch windows for time-sensitive advertiser commitments. Zhongguancun software parks house the cross-platform identity graph engineering teams powering WeChat ecosystem integration.
Sichuan-Chongqing
Chengdu's developer ecosystem remains underpenetrated for rewarded video relative to coastal saturation, creating expansion headroom. GB standards for personal information protection mandate explicit consent layers that lengthen ad load times. Tianfu Software Park anchors western China's largest concentration of puzzle and casual game studios.
Shandong Peninsula
Qingdao and Jinan's emerging cloud gaming infrastructure leverages 5G edge computing for server-side ad rendering. Dual carbon mandate alignment opens preferential placement within state-backed publishing initiatives for carbon-neutral data center operators. Local deployments bypass device-level identifier restrictions through China Mobile edge node integration.
China in-Game Advertising Market Competitive Landscape
Platform-holding conglomerates and genre-specialized developers split the market along inventory control and creative format specialization vectors. Tencent's WeChat ecosystem integration and miHoYo's premium rewarded architecture exemplify divergent strategic positioning. Three archetypes dominate: ecosystem-integrated platforms with cross-app identity graphs, genre-specialized studios with proprietary ad-tech stacks, and broadcast-gaming hybrids with live-streaming ad insertion capabilities. Competitive moves center on SDK protocol exclusivity and edge computing infrastructure preemption.
Within the ecosystem-integrated tier, Tencent and NetEase occupy positions that exemplify contrasting approaches to regulatory-constrained targeting. miHoYo represents the genre-specialized archetype through its Genshin Impact premium inventory concentration. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Tencent |
| NetEase |
| miHoYo |
| Perfect World |
| Huya |
| Douyu |
| Bilibili |
| iDreamSky |
| Shunrong |
| Others |
Pricing and Supply Chain Analysis
Shanghai and Beijing developer clusters concentrate rewarded video inventory capacity, compressing eCPM spreads between premium opt-in placements and interruptive formats as supply saturation intensifies buyer negotiation leverage across tier-one cities.
Pricing Analysis
SAMR's advertising law enforcement dictates the pricing tier structure across China's in-game advertising ecosystem. Three-tier pricing separates premium rewarded video from standard non-skippable mid-roll and economy banner inventory. Price differentiation rests on completion guarantee mechanics and consent-layer latency tolerance. Pricing pressure stems from GB standards compliance extending ad load times by 300-800 milliseconds, degrading completion rates. Hyper-casual publishers in Shenzhen exhibit highest price sensitivity; miHoYo and NetEase command least due to proprietary ad-tech captive demand.
Supply Chain Analysis
Extended payment terms from tier-one publishers to SDK adapter developers now stretch 90-120 days, straining technical resource allocation across fragmented protocol requirements. Supply concentrates in China for creative compliance review, ad-tech engineering, and edge node deployment. Raw material dependencies span server-side rendering infrastructure, 5G edge computing hardware, and jurisdictional data residency certification. Single-source vulnerability runs through National Radio and Television Administration content review cycles averaging 72 hours. Distribution runs through programmatic exchanges, direct publisher sales teams, and brand safety verification vendors displacing traditional media buying agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's in-game advertising market constitutes a high-growth disruption as 5G edge computing and server-side rendering architectures displace client-side SDK dependencies, compressing latency benchmarks below 50 milliseconds for interactive format viability.
For Market Incumbents: Insulate proprietary ad-tech stacks through exclusive SDK protocol development that fragments technical resource allocation across incompatible publisher requirements. Deepen backward integration into edge computing infrastructure preemption with China Mobile and China Unicom node deployment. Counter cloud gaming convergence threats by locking carbon-neutral data center certification for preferential state-backed publishing placement.
For New Entrants and Emerging Players: Chengdu and Xi'an developer ecosystems represent the most penetrable entry point for rewarded video inventory expansion relative to coastal saturation. Cloud gaming server-side rendering architectures bypass device-level identifier restrictions entirely, opening targeting capability gaps for new ad-tech providers. Pursue outcome-based engagement guarantee procurement patterns consolidating among fintech and automotive advertisers in Shanghai's Lujiazui district.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors genre-specialized studios with proprietary ad-tech stacks over ecosystem-integrated platforms facing regulatory targeting constraints. Long-term viability hinges on first-party data graph depth and cross-platform identity resolution capability absent persistent device identifiers. Monitor SAMR advertising law enforcement circulars and MIIT data security governance amendments as primary inflection signals for valuation compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Preemption | China Mobile and China Unicom node deployment collapses latency below 50ms for interactive ad formats. |
| Server-Side Rendering Architecture Migration | Bypasses MIIT device-level identifier restrictions through cloud gaming convergence pathways. |
| Carbon-Neutral Data Center Certification | Dual carbon mandate alignment secures preferential placement within state-backed publishing initiatives. |
| Proprietary SDK Protocol Exclusivity | Fragments technical resource allocation across incompatible publisher stacks, raising rival switching costs. |
| Outcome-Based Engagement Guarantee Offering | Aligns with fintech and automotive advertiser procurement consolidation away from impression-volume commitments. |
Research Methodology
A standing panel of mobile game publishers, programmatic ad-tech engineers, brand safety verification vendors, and National Radio and Television Administration compliance consultants provided ongoing calibration. Primary interviews with Shanghai and Beijing developer cluster executives combined with secondary validation from MIIT policy circulars, SAMR enforcement disclosures, China Mobile infrastructure deployment records, and App Annie mobile advertising intelligence. Bottom-up inventory flow modeling triangulated against top-down market sizing across ad format, game genre, platform, and monetization model dimensions.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation modeling spanning rewarded video, non-skippable mid-roll, interstitial, and banner formats; RPG, action, puzzle, and sports genres; mobile, cloud, PC, and console platforms; plus freemium, in-app purchase, subscription, and premium monetization models. CAGRs derived from cohort-based adoption curve analysis incorporating 5G penetration rates, edge node deployment timelines, and regulatory compliance cost trajectories as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on mobile gaming, advertiser budget allocation to digital channels, or 5G infrastructure capex cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, edge computing deployment velocity, and cross-platform identity graph technical feasibility. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile and Handheld Gaming Market
Gaming
Mobile Game Controller Market
Gaming
Shooter Game Market
Gaming
Flat Gaming Monitors Market
Gaming
Racing Games Market
Gaming
AAA Games Market
Gaming
Board Games Market
Gaming
Mobile Game Software Market
Gaming
MMORPG Gaming Market
Gaming
China Casino Tourism Market
Gaming
RPG Games Market
Gaming
Advanced Digital Gaming Market
Gaming
Social Gaming Market
Gaming
Chinese Gaming Industry Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Gaming Simulation Market