
 Europe Online Gambling Market | 2026-2036
Europe Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Gambling Market Intelligence
Buyer concentration across Europe's online gambling sector is restructuring as casual bettors fragment across mobile-first platforms while high rollers consolidate with premium live dealer operators. Flutter Entertainment PLC leverages its multi-brand portfolio to dominate regulated markets across the United Kingdom, Ireland, and continental Europe. Entain PLC sustains technology leadership through proprietary platform architecture and in-house game development studios. Betsson AB anchors its position in Nordic and Baltic markets through localized payment integration and multilingual customer support.
Europe online gambling encompasses remote wagering activities conducted via internet-connected devices, encompassing real-money gaming platforms that utilize random number generators, live video streaming infrastructure, and encrypted financial transaction protocols to facilitate bets on chance-based and skill-based games. The primary commercial purpose centers on delivering entertainment wagering services to licensed jurisdictions while generating tax revenue for national treasuries and compliance fees for regulatory authorities. Sports betting commands the largest share of gross gaming revenue across the region, driven by football wagering volumes and in-play betting functionality. Mobile apps represent the fastest-expanding platform type, displacing desktop websites as younger demographics prefer smartphone-native interfaces with biometric authentication and push-notification promotions.
The European Gaming and Betting Association coordinates industry standards across member states while national regulators including the UK Gambling Commission, Spelinspektionen in Sweden, and Germany's Joint Gambling Authority enforce localized licensing conditions, advertising restrictions, and player protection mandates. The EU AI Act introduces algorithmic transparency requirements for automated betting recommendations and risk-scoring systems, compelling operators to document decision logic for regulatory audits. Stakeholders must monitor the divergence between harmonized EU digital regulations and nation-specific gambling monopolies or tax frameworks that fragment market access conditions.
Market Dynamics
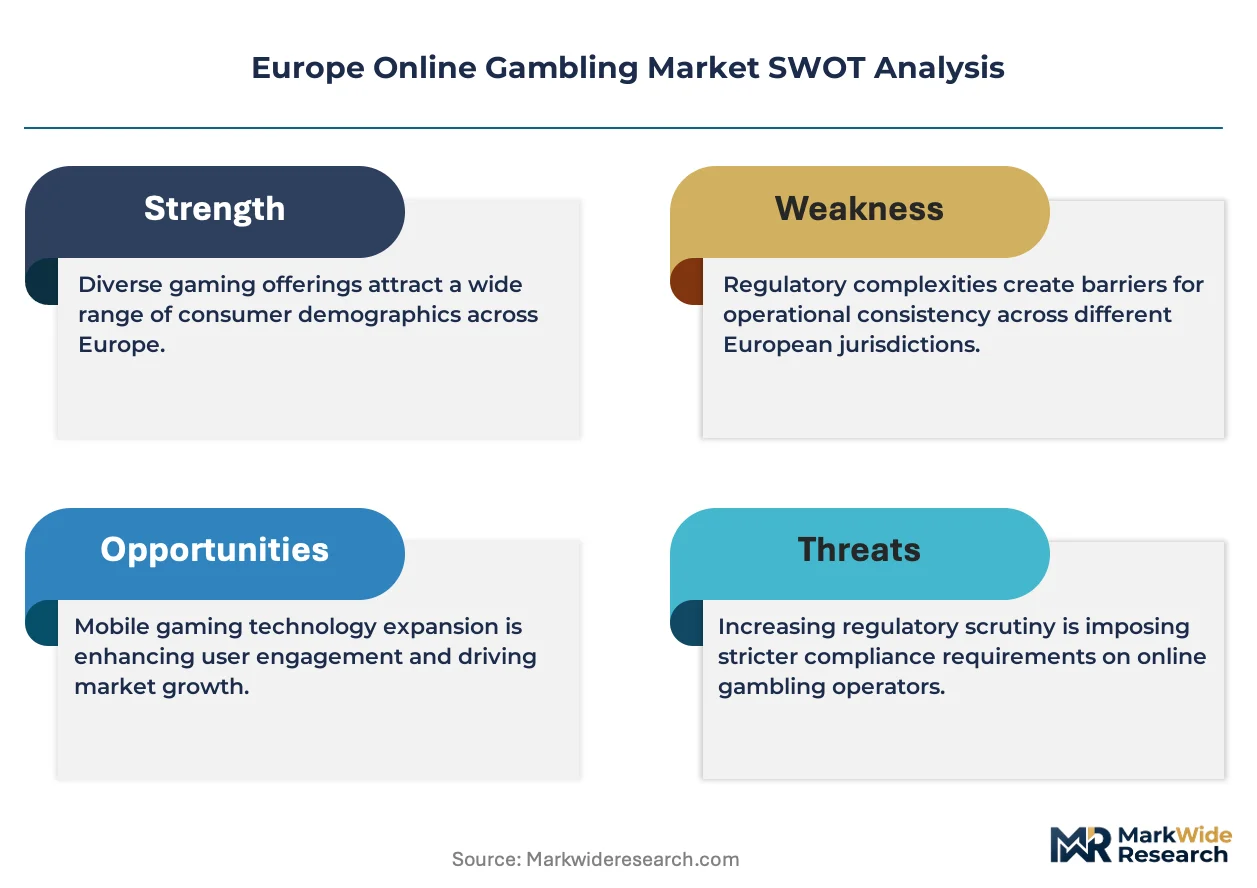
Mobile-first sports betting platforms are fragmenting casual bettors across Germany, Spain, and Italy while AI-driven personalization engines reshape operator acquisition costs and lifetime value calculations.
Growth Catalysts
- Germany's State-Level Licensing Framework:The Joint Gambling Authority's Interstate Treaty on Gambling creates a regulated channel for licensed operators to serve Europe's largest national market with legal certainty.
- Live Video Streaming Infrastructure:Low-latency streaming technology enables real-time in-play betting on football matches, compressing bet placement windows and multiplying wagering frequency per user session.
- EU AI Act Algorithmic Transparency:Mandated documentation of automated betting recommendation logic forces operators to build auditable risk-scoring systems, creating competitive differentiation for compliant platforms.
Market Restraints
- Advertising Restrictions:Sweden's Spelinspektionen and the UK Gambling Commission enforce strict marketing limits on television and social media, elevating customer acquisition costs for operators dependent on mass-market reach.
- Payment Processing Concentration:Nordic and Baltic markets rely heavily on localized banking integration through Trustly and region-specific instant payment rails, creating vendor lock-in and geographic expansion friction.
- Player Protection Mandates:Mandatory deposit limits, cooling-off periods, and self-exclusion registry integration compress operator margins while requiring continuous compliance infrastructure investment.
Strategic Opportunities
- Italy's Underpenetrated Mobile Segment:The Agenzia delle Dogane e dei Monopoli's licensing regime still shows desktop-heavy usage patterns, creating white space for smartphone-native platforms with biometric authentication.
- Convergence of AI and Responsible Gaming:Machine learning models detecting at-risk gambling behavior in real time enable operators to satisfy regulatory mandates while preserving high-value customer relationships through intervention rather than exclusion.
- Spain's Emerging Esports Betting Vertical:The Dirección General de Ordenación del Juego's framework for skill-based wagering opens regulatory pathways for video game competition markets untapped by traditional sportsbook operators.
Industry Challenges
- Cross-Border Compliance Talent Scarcity:Operators struggle to recruit legal and technical staff fluent in the divergent requirements of the UK Gambling Commission, Germany's Joint Gambling Authority, and Nordic national regulators simultaneously.
- Legacy Platform Migration Complexity:Established operators with proprietary technology stacks face multi-year re-architecture projects to implement real-time AI transparency logging required by EU AI Act audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Gambling Market |
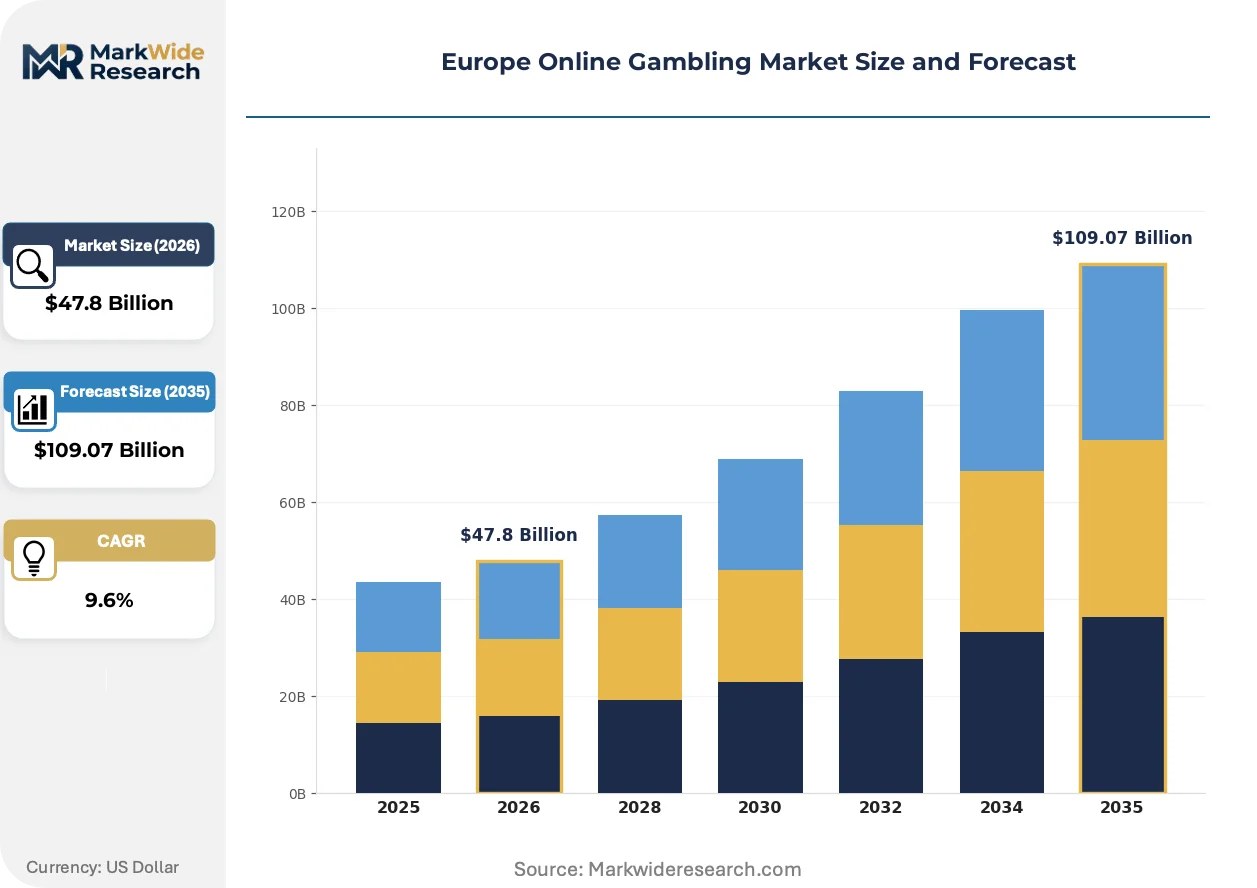
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $109.07 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile Apps, Desktop Websites, Virtual Reality Casinos, Live Dealer Games Game Type: Slots, Poker, Sports Betting, Bingo Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cryptocurrencies Customer Segment: Casual Gamblers, High Rollers, Professional Players, Occasional Bettors |
| Companies Covered | Flutter Entertainment PLC, LeoVegas AB, Betsson AB, Kindred Group, Unibet, Entain PLC, Evoke PLC, Superbet, Bet365 Group Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Gambling Market Strategic Shifts & Innovations
Algorithmic personalization and biometric authentication are compressing the gap between casual and premium player experiences while regulatory technology investments consume an expanding share of operator R&D budgets.
Native mobile applications with push-notification promotional engines are overtaking responsive web platforms as the dominant interface for sports betting across younger demographics in Italy and Spain. These apps leverage device-level biometric authentication to reduce friction in deposit and withdrawal workflows. The structural consequence is a bifurcation where smartphone-native operators capture casual bettors while desktop-anchored incumbents retain aging high-value players.
The EU AI Act's algorithmic transparency requirements are compelling operators to rebuild automated recommendation systems with documented decision trees auditable by national regulators. Industrial consequence includes elevated compliance costs concentrated in machine learning engineering teams. Sports betting platforms with in-play odds adjustment algorithms face the steepest re-architecture burden, with UK-licensed operators responding through partnerships with specialized RegTech vendors.
Casual bettors are consolidating wagering activity onto multi-brand platform portfolios that share unified wallet infrastructure and cross-product loyalty programs. Aggregator-style apps displace single-operator relationships as the preferred entry point for price-sensitive users. This pattern is most visible in Germany, where Flutter Entertainment's multi-brand architecture enables bettor migration between sportsbook and casino products without account re-verification friction.
Europe Online Gambling Market Segmentation
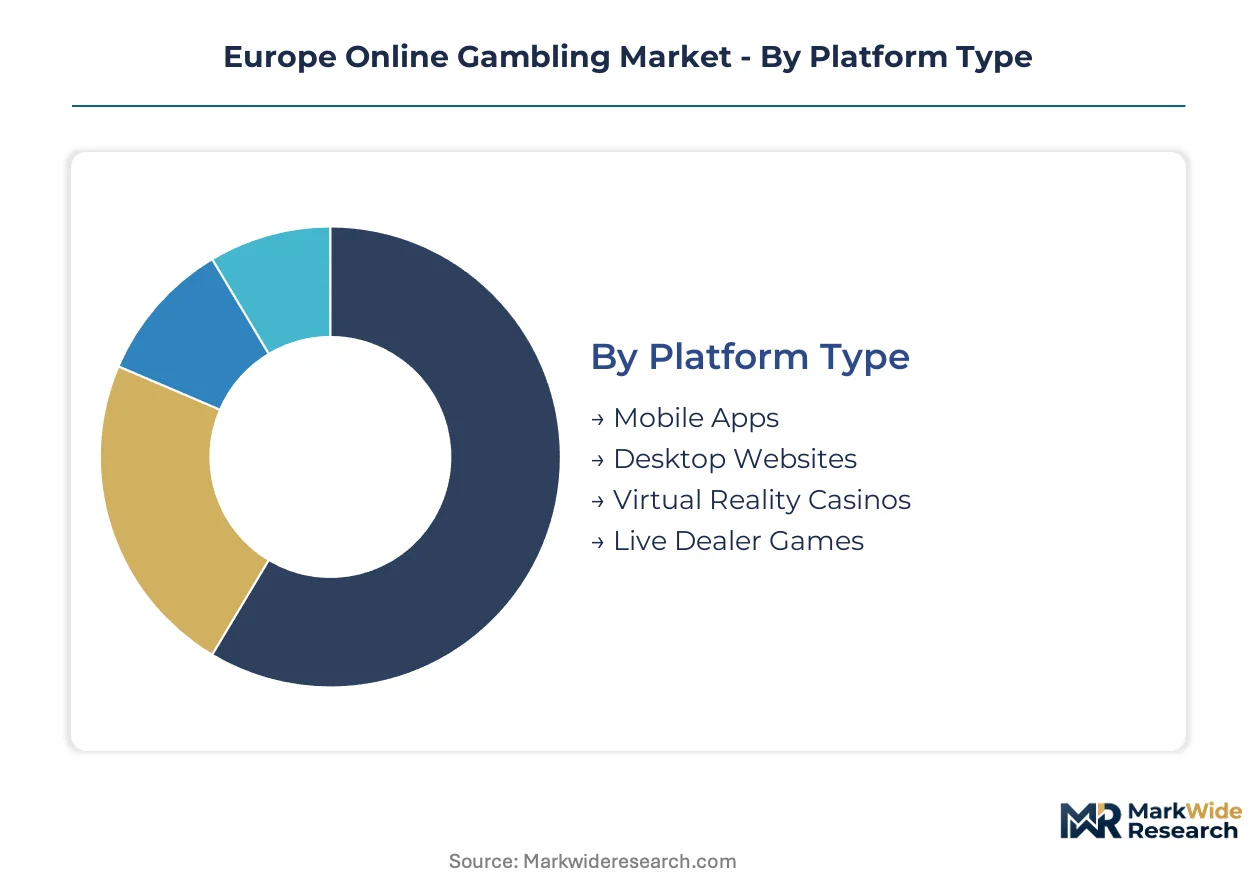
Platform architecture and wagering modality choices determine operator capital allocation, compliance burden, and customer lifetime value across Europe's regulated jurisdictions. Segmentation reveals where technology investments concentrate and where regulatory arbitrage creates margin differentiation.
Platform Type:
Supply concentration clusters around mobile-native infrastructure as operators redirect development resources from legacy desktop stacks toward smartphone-optimized experiences with biometric authentication and push-notification engines.
- Mobile Apps:Native smartphone applications dominate new customer acquisition across Germany, Italy, and Spain with streamlined KYC workflows and one-tap deposit functionality. Younger demographics in Mediterranean markets prefer these interfaces, compressing session initiation times and elevating in-play betting frequency per user.
- Desktop Websites:Responsive web platforms retain aging high-value players and professional bettors requiring multi-window analytics and advanced statistical tools. Nordic markets show stickier desktop usage patterns due to established player habits and complex sportsbook interface preferences.
- Virtual Reality Casinos:Immersive 3D environments with spatial audio and gesture-based controls remain experimental, limited by hardware penetration and regulatory uncertainty around player protection in immersive environments.
- Live Dealer Games:Real-time video streaming infrastructure connects physical casino studios to remote players, commanding premium table minimums and higher operator margins through authentic human croupier interaction.
Today's leader: Mobile Apps. Tomorrow's challenger: Live Dealer Games.
Game Type:
Margin profiles diverge sharply between chance-based automated products and skill-influenced wagering formats, with sports betting carrying the heaviest regulatory compliance costs per euro of gross gaming revenue.
- Sports Betting:Football wagering volumes drive the largest share of operator revenue across the United Kingdom and Germany, with in-play functionality multiplying bet frequency through micro-event markets. The Joint Gambling Authority's advertising restrictions elevate customer acquisition costs for mass-market sportsbook operators.
- Slots:Random number generator-based reel games generate the highest operator margins with minimal human staffing requirements. Swedish and Finnish markets show particular concentration in branded content licensed from entertainment intellectual property holders.
- Poker:Peer-to-peer card platforms require substantial liquidity pools and sophisticated anti-collusion detection systems, limiting viable operators to those with established multi-national player networks.
- Bingo:Community-oriented number games attract predominantly female demographics in the United Kingdom and Ireland, with chat functionality driving social retention metrics distinct from other verticals.
Sports Betting commands current revenue leadership. Slots demonstrate the steepest margin expansion trajectory.
Payment Method:
Geographic payment infrastructure fragmentation forces operators to maintain localized banking integrations, with Nordic markets demanding instant account-to-account transfers unavailable through standard card networks.
- Credit Cards:Visa and Mastercard processing dominates in Southern European markets with established chargeback dispute frameworks and familiar consumer trust patterns.
- E-Wallets:PayPal, Skrill, and Neteller penetration concentrates in the United Kingdom and Ireland, offering intermediary privacy layers that appeal to recreational bettors.
- Bank Transfers:Trustly and region-specific instant payment rails anchor Nordic and Baltic market transactions with lower processing fees and direct bank authentication.
- Cryptocurrencies:Bitcoin and stablecoin acceptance remains marginal due to European Banking Authority guidance and national regulator skepticism toward volatile-value deposit instruments.
E-Wallets lead transaction volume in mature markets. Bank Transfers are expanding most quickly in newly regulated jurisdictions seeking reduced payment friction.
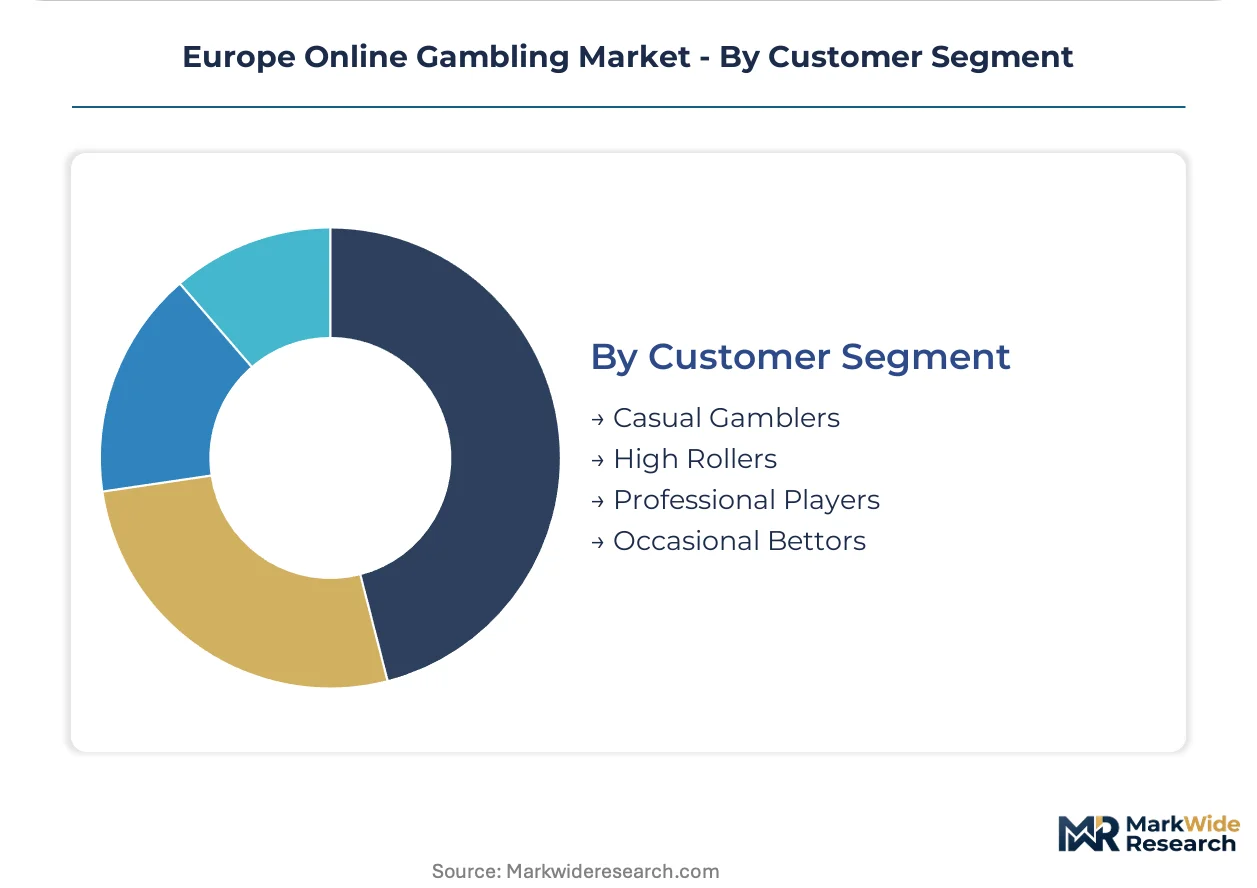
Customer Segment:
Acquisition economics and responsible gaming obligations scale inversely across the wagering intensity spectrum, with high rollers demanding personalized account management while casual players trigger automated intervention thresholds.
- Casual Gamblers:Low-stakes recreational players placing occasional bets on major football tournaments represent the largest addressable population across Italy and Spain. Mobile-first platforms with gamified loyalty mechanics capture this segment through reduced deposit minimums and social sharing features.
- High Rollers:VIP players wagering substantial sums command dedicated relationship managers, customized credit lines, and exclusive live dealer table access. The United Kingdom's self-exclusion registry and affordability checks have compressed this segment's growth trajectory.
- Professional Players:Advantage bettors employing statistical models and arbitrage strategies strain operator risk management systems, with many platforms imposing stake limits or account closures on consistently profitable customers.
- Occasional Bettors:Event-driven wagerers activating around World Cup or Grand National occasions require minimal retention investment but show elevated churn between major sporting calendars.
Casual Gamblers anchor current volume. Professional Players face mounting platform restrictions that redirect their activity toward exchange-based wagering models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's state-level licensing framework generates larger operator compliance investments than Italy's mobile-lagging market, while Nordic jurisdictions enforce stricter advertising constraints than Mediterranean counterparts.
Germany
Football wagering volumes and in-play betting functionality drive operator revenue concentration in Europe's largest national market. The Joint Gambling Authority enforces Interstate Treaty provisions on deposit limits and advertising windows. Düsseldorf hosts compliance infrastructure clusters serving multi-brand platform portfolios seeking legal certainty.
United Kingdom
Self-exclusion registry integration and affordability checks compress high-roller segment growth while elevating responsible gaming technology spending. The UK Gambling Commission mandates algorithmic transparency for automated betting recommendations ahead of EU AI Act alignment. London anchors Flutter Entertainment's multi-brand architecture and cross-product loyalty program development.
Italy
Desktop-heavy usage patterns among Agenzia delle Dogane e dei Monopoli licensees create white space for smartphone-native platforms with biometric authentication. Mediterranean advertising restrictions remain less stringent than Nordic counterparts, permitting broader television and social media reach. Milan concentrates payment processor integration hubs serving Southern European card networks.
Sweden
Spelinspektionen marketing limits on television and social media elevate customer acquisition costs for mass-market sportsbook operators. Trustly and region-specific instant payment rails anchor transaction infrastructure with lower processing fees than card alternatives. Stockholm clusters RegTech vendor partnerships addressing EU AI Act audit documentation requirements.
Spain
Dirección General de Ordenación del Juego frameworks for skill-based wagering open regulatory pathways for video game competition markets. Esports betting verticals attract younger demographics underserved by traditional football-focused sportsbooks. Barcelona hosts live streaming technology development for low-latency in-play odds adjustment systems.
Europe Online Gambling Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Europe's regulated jurisdictions, producing a tiered structure where multi-brand portfolios share unified wallet infrastructure against standalone mobile-native platforms. Three archetypes dominate: technology-integrated conglomerates with proprietary platform architecture, Nordic-focused operators with localized payment expertise, and mobile-first specialists with gamified retention mechanics. Competitive moves concentrate on M&A consolidation for market access rights and geographic expansion into newly licensed state frameworks.
Within the technology-integrated tier, Flutter Entertainment PLC and Entain PLC exemplify multi-brand conglomerates leveraging cross-product loyalty programs and in-house development studios. Betsson AB anchors Nordic and Baltic positioning through localized banking integration. These three entities occupy distinct archetype positions: Flutter represents portfolio diversification scale, Entain embodies proprietary platform investment, and Betsson concentrates geographic specialization with multilingual support infrastructure.
| Leading Market Players |
|---|
| Flutter Entertainment PLC |
| LeoVegas AB |
| Betsson AB |
| Kindred Group |
| Unibet |
| Entain PLC |
| Evoke PLC |
| Superbet |
| Bet365 Group Ltd |
| Others |
Cost & Logistics Intelligence
Horizontal integration across payment processor networks anchors operator pricing power while compressing margins for standalone platforms lacking unified wallet infrastructure. The dominance of multi-brand conglomerates with captive loyalty programs forces smaller operators toward aggressive promotional pricing to sustain player acquisition.
Pricing Analysis
Capacity additions in Germany's licensed operator pool are reshaping price floors for customer acquisition bonuses and free-to-play entry incentives. The market runs on a hybrid transactional-loyalty pricing structure where gross gaming revenue shares fund cross-platform retention mechanics. Price differentiation rests on regulatory compliance tier and geographic licensing cost, with UK Gambling Commission-mandated affordability checks elevating operational overhead. Pricing pressure stems from Spelinspektionen advertising restrictions that force reliance on costly affiliate channels. Casual gamblers show highest price sensitivity to deposit minimums, while high rollers demonstrate inelastic demand for bespoke account management.
Supply Chain Analysis
Domestic-content mandates in Germany's Interstate Treaty on Gambling are reshaping sourcing toward locally hosted server infrastructure and native-speaking compliance personnel. Supply concentrates in Malta, Gibraltar, and the Isle of Man as licensing jurisdictions anchoring platform development. Raw material dependencies include low-latency video streaming bandwidth, random number generator certification services, and biometric authentication APIs. Supply chain risk centers on single-source vulnerability in Nordic instant payment rails through Trustly. Distribution runs through mobile application stores and direct-to-consumer web platforms, with aggregator-style apps displacing single-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's online gambling sector hinges on AI-driven personalization engines reducing customer acquisition costs while premium live dealer tiers capture high-value player spend.
For Market Incumbents: Acquire proprietary game development studios to reduce third-party content licensing fees and differentiate against emerging mobile-native entrants. Consolidate compliance infrastructure across multi-brand portfolios to amortize EU AI Act documentation costs. Threats from algorithmic transparency mandates favor operators with captive machine learning engineering teams. Capacity addition in Spain's esports betting vertical offers defensive positioning against football-centric competitors. For New Entrants and Emerging Players: White-label platform providers offer the fastest path to regulatory compliance without multi-year licensing delays. Italy's underpenetrated mobile segment presents the most penetrable geography for smartphone-native interfaces with biometric authentication. A direct-to-consumer acquisition model leveraging social media influencer partnerships bypasses television advertising restrictions in Nordic markets. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with localized payment integration because regulatory fragmentation prevents pan-European scale from single platforms. Long-term viability across the analysis window favors operators with demonstrated compliance track records in multiple jurisdictions. Acquisition target archetype: mobile-first platforms with gamified retention mechanics in Mediterranean markets. The signal to watch is Germany's Joint Gambling Authority licensing renewal patterns as market access inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Investment | EU AI Act compliance infrastructure creates audit-ready differentiation against non-compliant competitors. |
| Multi-Brand Portfolio Consolidation | Unified wallet architecture across Flutter Entertainment's holdings reduces player churn between verticals. |
| Localized Payment Integration | Trustly and region-specific instant rails anchor Nordic market retention through reduced friction. |
| Live Dealer Studio Expansion | Real-time streaming infrastructure commands premium table minimums and elevates operator margins. |
| Esports Betting Vertical Development | Spain's Dirección General de Ordenación del Juego framework opens skill-based wagering pathways. |
Research Approach
Multiple input streams — regulatory filing analysis, operator financial disclosures, and technology vendor interviews — were reconciled to construct market estimates. Primary discussions with platform engineering directors, compliance officers at licensed operators, payment processor executives, and regulatory affairs specialists informed operational cost structures and licensing timelines. Secondary validation drew from UK Gambling Commission enforcement reports, Spelinspektionen market data, Germany's Joint Gambling Authority licensing registers, and European Gaming and Betting Association industry statistics. Bottom-up sizing of operator revenue pools triangulated against top-down macroeconomic wagering penetration benchmarks.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to platform type, game vertical, and geographic jurisdiction dimensions. The analytical framework modeled mobile app versus desktop website adoption curves, sports betting versus casino margin profiles, and payment method mix evolution throughout the forecast period. CAGRs were derived from regression analysis of licensed market revenue disclosures and unlicensed market erosion estimates. Forecast inputs incorporated player protection mandate compliance costs and AI transparency infrastructure spending as margin compression factors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization efforts and advertising restriction tightening. The analysis reflects assumptions on licensing framework stability, payment rail continuity, and technology vendor pricing. Specific risks that could revise forecasts include Germany's Interstate Treaty amendment cycles, EU AI Act enforcement variance across member states, and Nordic instant payment rail consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East and Africa Animation Market
Digital Media
Adult Animation Market
Digital Media
VFX Market
Digital Media
Sound Effects Services Market
Digital Media
Digital Content Locker Market
Digital Media
Media Coding Service Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Da Vinci Systems Market
Digital Media
3D Animation Market
Digital Media
Indonesia Digital Media Market
Digital Media
Online Movie Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Digital Content Creator Market
Digital Media
Digital Media Market
Digital Media
LED Stadium Screens Market