
 Food Sterilization Equipment Market | 2026-2036
Food Sterilization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Sterilization Equipment Market Intelligence
The shift toward continuous-flow high-pressure processing (HPP) systems is bifurcating the market from traditional batch autoclaves. JBT Corporation leverages its extensive portfolio in both thermal and non-thermal processing solutions. Tetra Pak International S.A. specializes in integrated aseptic sterilization lines for liquid foods and beverages. Meanwhile, Allpax Products focuses on retort and autoclave systems for the North American canning industry.
Food sterilization equipment comprises systems designed to eliminate or inactivate microorganisms such as bacteria, yeasts, and molds in food products. These systems operate using thermal methods, often exceeding 121°C, or non-thermal technologies like high-pressure processing which can reach up to 600 MPa. The primary purpose is to ensure food safety and extend product shelf life without refrigeration. While thermal sterilizers like autoclaves command a significant share, high-pressure processing equipment is a rapidly expanding product type, with packaged foods and beverage sterilization constituting the largest application segments.
Compliance with regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictates equipment design and validation protocols. In Asia, standards such as China's GB standards and requirements from Japan's Ministry of Health, Labour and Welfare influence market access. Equipment manufacturers must decide between optimizing high-throughput thermal systems for cost efficiency or investing in novel non-thermal technologies to meet demand for minimally processed foods.
Market Dynamics
The fundamental dynamic shaping the food sterilization equipment market is the technical and economic divergence between high-throughput thermal systems and advanced non-thermal technologies, driven by conflicting demands for cost efficiency in bulk processing and quality preservation in premium foods.
Growth Catalysts
- Packaged Food Expansion:Consumer demand for convenience foods with extended shelf life, particularly in China's rapidly urbanizing regions, is creating sustained demand for both retort and aseptic sterilization systems.
- Regulatory Modernization:Stricter food safety mandates, including the US FDA's Food Safety Modernization Act (FSMA), compel manufacturers to invest in equipment with superior process control and validation capabilities to prevent microbial contamination.
- Non-Thermal Technology Maturation:The commercial availability of continuous-flow high-pressure processing (HPP) systems offers a viable alternative to thermal methods for heat-sensitive products, unlocking growth in the premium beverage and ready-meal segments.
Market Restraints
- High Capital Outlay:The significant upfront investment required for non-thermal equipment, such as HPP systems, acts as a major barrier for small and medium-sized food processors.
- Throughput Limitations:Non-thermal technologies, while preserving quality, often have lower processing volumes compared to traditional thermal autoclaves, creating a bottleneck for high-volume producers.
- Energy Consumption:Thermal sterilization systems, particularly large-scale autoclaves and retorts, are energy-intensive, exposing operators to volatile energy costs and increasing pressure to meet sustainability targets.
Strategic Opportunities
- Emerging Market Penetration:Food processing industries in Southeast Asian nations represent an underpenetrated market for modern sterilization equipment, offering significant growth potential as local food safety standards rise.
- Plant-Based Product Sterilization:The expansion of the plant-based food sector creates an opportunity for equipment optimized for the unique textures and formulations of products like dairy-free milks and meat analogues.
- Process Intelligence Integration:Incorporating AI and machine learning algorithms into sterilization controls can enable predictive maintenance and real-time process optimization, creating a new value proposition for equipment vendors.
Industry Challenges
- Specialized Skills Shortage:A lack of technicians and engineers qualified to operate, validate, and maintain complex HPP and aseptic systems constrains the adoption and efficient use of these advanced technologies.
- Legacy System Integration:Integrating modern, continuous-flow sterilizers into existing factory layouts built around older, batch-based processing lines presents significant engineering and operational complexity for food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Sterilization Equipment Market |
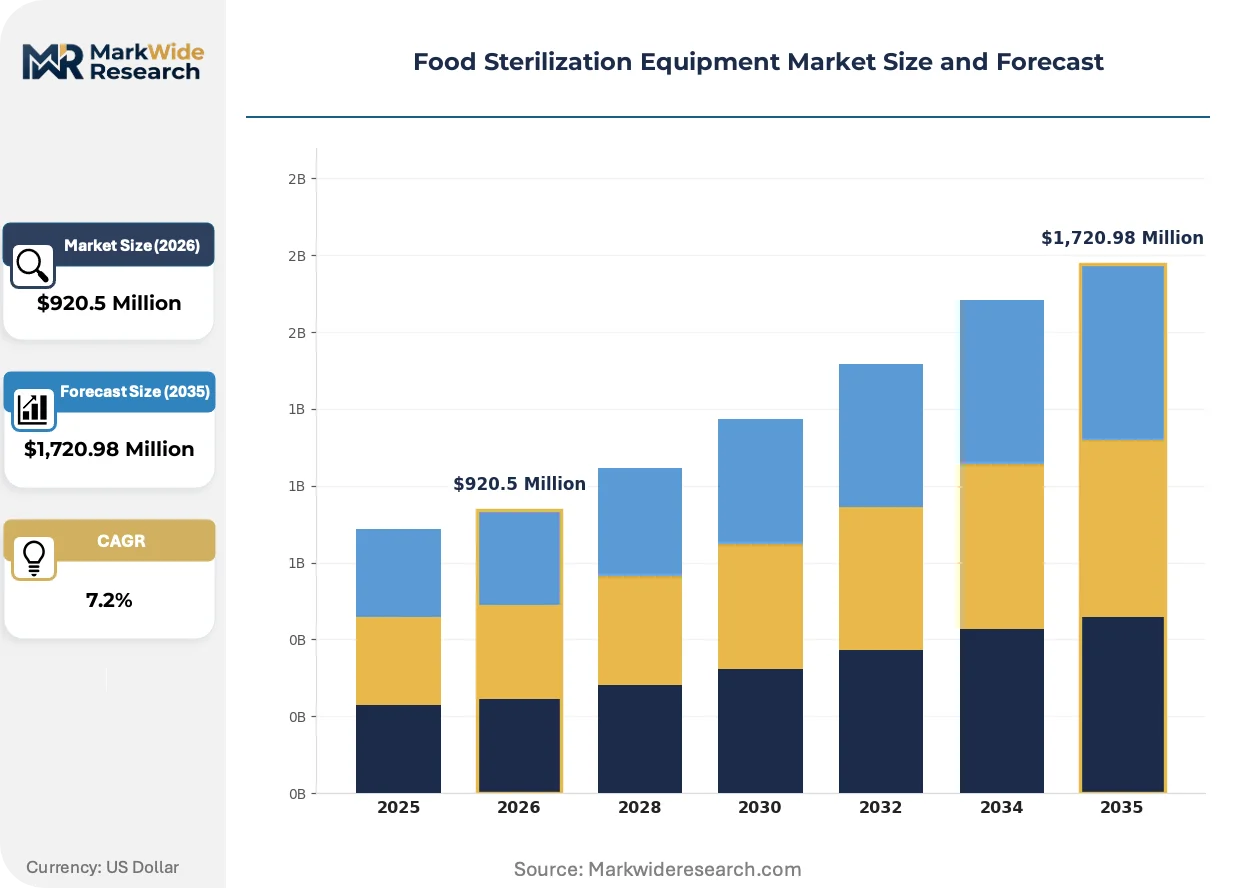
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,720.98 Million |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autoclaves, UV Sterilizers, Microwave Sterilizers, High-Pressure Processing, Thermal Sterilizers Technology: Gamma Radiation, Electron Beam, Pulsed Light, Ozone Treatment, Infrared Sterilization Application: Meat Processing, Dairy Preservation, Beverage Sterilization, Seafood Treatment, Packaged Foods End User: Food Processing Plants, Canning Facilities, Beverage Manufacturers, Packaging Operators, Specialty Food Producers |
| Companies Covered | DE LAMA S.P.A., Surdry, JBT Corporation, Steriflow, Ventilex, Allpax Products, HISAKA WORKS, Tetra Pak International S.A., Cosmed Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Sterilization Equipment Market Strategic Shifts & Innovations
Innovation in the food sterilization equipment market is shaped by the dual objectives of achieving microbiological safety while meeting consumer expectations for minimally processed foods. This is driving parallel advancements in both mature thermal technologies and novel non-thermal alternatives.
High-pressure processing (HPP) is a non-thermal method that uses intense hydrostatic pressure to inactivate pathogens and spoilage microorganisms. The technology is seeing rapid adoption in the premium juice, deli meat, and ready-to-eat meal segments. This method is displacing traditional thermal pasteurization for high-value products where the preservation of flavor, color, and nutritional content provides a distinct competitive advantage.
Regulatory frameworks, such as China's GB standards for food safety, are becoming increasingly stringent regarding process verification and equipment hygiene. This evolution forces manufacturers to engineer systems with improved clean-in-place (CIP) capabilities and more precise monitoring of critical control points like temperature and pressure. The dairy and beverage industries, in particular, are upgrading their lines to meet these heightened compliance requirements.
A notable behavioral shift is the move by food processors to prioritize equipment that provides comprehensive data for traceability. This trend de-emphasizes purchase decisions based solely on capital cost and throughput, placing a premium on systems with integrated sensors and software that generate an auditable data trail. This is most apparent in the European Union, where food safety and origin verification are critical for gaining access to premium retail channels.
Food Sterilization Equipment Market Segmentation
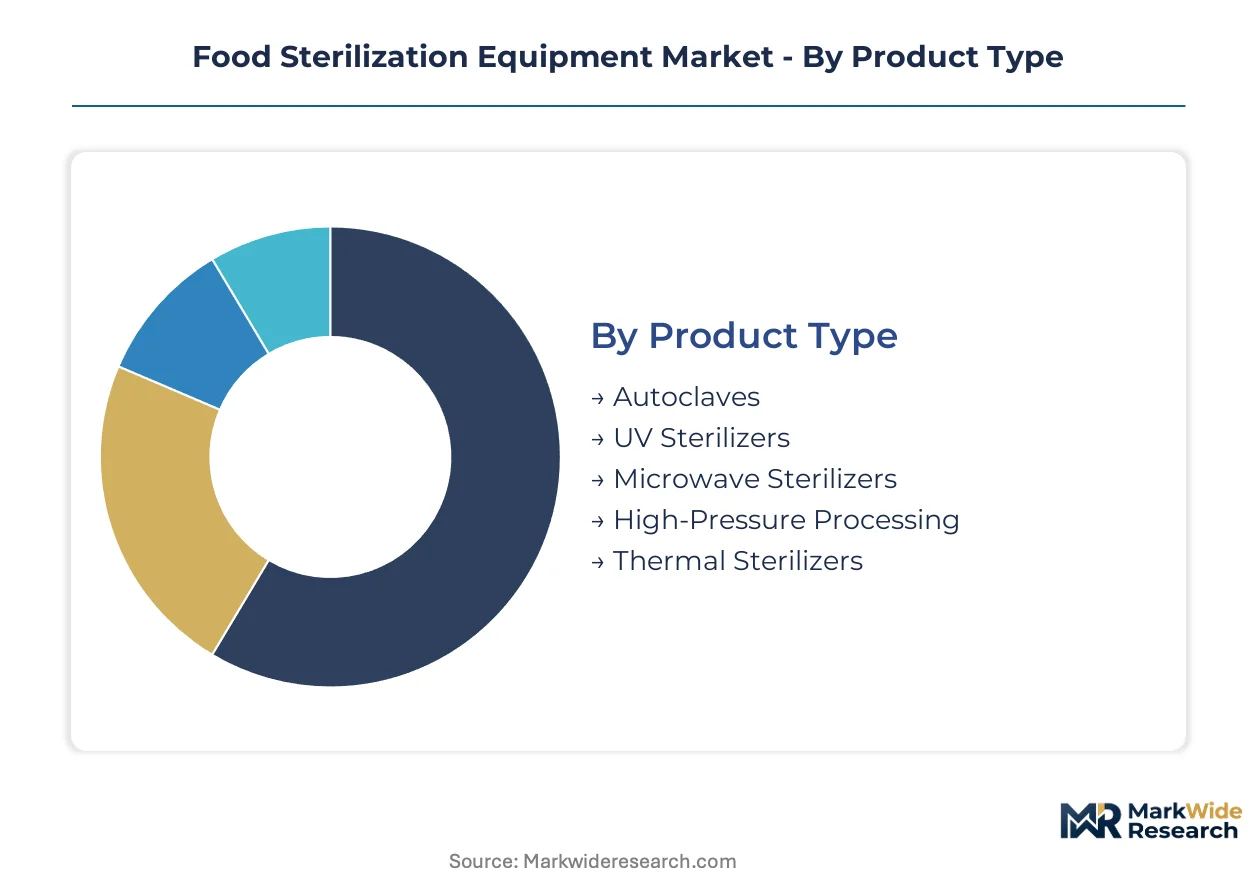
Understanding the segmentation within the food sterilization equipment market is crucial for identifying areas of concentrated demand and technological evolution. This segmentation reflects the diverse requirements for ensuring food safety and extending product shelf life across various food categories and processing scales. Regulatory compliance and consumer preferences significantly influence equipment selection across these distinct segments.
Product Type:
Regulatory frameworks influence the selection of food sterilization equipment, with specific product types offering varied compliance pathways for microbial control.
- High-Pressure Processing:This non-thermal method uses intense hydrostatic pressure, up to 600 MPa, to inactivate pathogens and spoilage organisms. Demand concentrates in premium juice and ready-to-eat meal segments, driven by consumer preference for minimally processed foods.
- Thermal Sterilizers:These systems apply heat, often exceeding 121°C, to achieve microbiological safety and extend product shelf life. Food processing plants utilize thermal sterilizers extensively for bulk packaged foods, ensuring compliance with global food safety standards.
- Autoclaves:These batch-based thermal systems sterilize food products using pressurized steam at high temperatures.
- UV Sterilizers:Ultraviolet light systems inactivate microorganisms on surfaces or in liquids without heat, suitable for certain beverage applications.
- Microwave Sterilizers:Microwave technology uses electromagnetic radiation to generate heat internally within food products for sterilization purposes.
Thermal Sterilizers handle the majority of throughput; High-Pressure Processing is the fastest mover on share.
Technology:
Distinct technological approaches address varied sterilization challenges, each optimized for specific food matrices and desired outcomes.
- Electron Beam:This non-thermal technology utilizes accelerated electrons to break down microbial DNA, offering precise and rapid sterilization. Food processors in the packaged goods sector leverage electron beam technology for its efficiency and minimal impact on product quality.
- Pulsed Light:Short, intense bursts of broad-spectrum light inactivate microorganisms on food surfaces and packaging materials. This technology finds application in sterilizing delicate produce and pre-packaged items, extending their shelf stability.
- Gamma Radiation:Gamma rays penetrate deep into products to eliminate pathogens and insects, commonly used for spices and dried foods.
- Ozone Treatment:Ozone gas acts as a powerful oxidizing agent to sterilize water and food surfaces, providing a chemical-free disinfection method.
- Infrared Sterilization:Infrared radiation heats surfaces rapidly, enabling sterilization of conveyor belts and certain food items with minimal energy consumption.
Innovation in this technology segment focuses on enhancing microbial reduction while preserving product sensory attributes.
Application:
The scale and specific requirements of food processing operations dictate the most suitable sterilization applications.
- Packaged Foods:This segment represents the largest application area for sterilization equipment, ensuring safety and extending the shelf life of diverse ready-to-eat meals, snacks, and processed items. Consumer demand for convenience in China and other urbanizing regions drives significant investment here.
- Beverage Sterilization:Equipment in this application ensures microbial safety for liquid products like juices, milk, and soft drinks, often utilizing aseptic processing lines. Tetra Pak International S.A. specializes in integrated aseptic sterilization lines for liquid foods.
- Meat Processing:Sterilization equipment ensures pathogen reduction and shelf life extension for various meat products, including deli meats and prepared meals.
- Dairy Preservation:Systems sterilize milk, yogurt, and other dairy products, preventing spoilage and meeting stringent hygiene standards.
- Seafood Treatment:Equipment sterilizes fish and shellfish products, crucial for safety and extending market reach, particularly for export.
The expansion of packaged foods applications remains a primary driver for equipment demand within this category.
End User:
Different end-user profiles necessitate varied sterilization equipment configurations, aligning with their production scales and product portfolios.
- Food Processing Plants:These large-scale facilities represent the primary end-users, requiring diverse sterilization solutions for a wide range of products, from raw ingredients to finished goods. They invest in high-throughput thermal systems and increasingly non-thermal options to meet regulatory mandates.
- Beverage Manufacturers:Companies producing juices, dairy drinks, and other liquid consumables utilize specialized aseptic and thermal sterilization lines. These manufacturers prioritize equipment ensuring product integrity and extended shelf stability without refrigeration.
- Canning Facilities:These operations rely heavily on retort and autoclave systems for sterilizing canned fruits, vegetables, and meats.
- Packaging Operators:Sterilization equipment ensures hygiene for packaging materials before they come into contact with food products.
- Specialty Food Producers:Smaller-scale producers of niche or premium foods often adopt non-thermal technologies to preserve unique product characteristics.
The shift towards specialized processing needs from specialty food producers is influencing investment patterns in advanced non-thermal equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The food sterilization equipment market shows varied regional dynamics, with manufacturing capabilities and demand drivers concentrated in key industrial hubs. A significant portion of equipment demand focuses on Asia, particularly China, due to its expanding domestic food processing sector. This regional concentration influences technological advancements and regulatory compliance requirements across the industry.
China
Packaged food expansion and rising consumer demand for convenience drive equipment sales in China. The country's GB standards for food safety compel manufacturers to invest in advanced sterilization systems. Food processing clusters in the Yangtze River Delta actively adopt continuous-flow HPP systems for high-value products.
United States
Demand for extended shelf-life products and stringent food safety mandates propel equipment upgrades in the United States. The US FDA's Food Safety Modernization Act (FSMA) requires superior process control and validation capabilities. California's specialty food producers increasingly integrate non-thermal technologies to preserve product quality.
Germany
European consumer preferences for minimally processed foods stimulate investment in non-thermal sterilization technologies within Germany. Compliance with EFSA guidelines dictates equipment design, emphasizing hygiene and precise monitoring. The Bavaria region, a hub for food machinery manufacturers, develops advanced aseptic processing lines.
Vietnam
Modernization of food processing industries across Vietnam creates new demand for sterilization equipment. Rising local food safety standards drive investment in both thermal and non-thermal solutions. Ho Chi Minh City's burgeoning food and beverage sector actively seeks integrated sterilization systems.
Japan
Consumer expectations for product quality and strict food safety regulations shape the sterilization equipment market in Japan. Requirements from Japan's Ministry of Health, Labour and Welfare influence market access for advanced systems. The Kanto region's beverage manufacturers prioritize aseptic sterilization lines for liquid foods.
Food Sterilization Equipment Market Key Industry Players
Concentration sits with specialized equipment manufacturers offering integrated processing lines for large-scale food producers. The market exhibits a tiered structure, with established players providing comprehensive solutions and niche firms innovating specific non-thermal technologies. Strategic archetypes include diversified industrial conglomerates and specialized aseptic system providers. Competitive moves involve portfolio diversification into non-thermal solutions and geographic expansion into emerging markets.
On the diversified industrial solutions vector, JBT Corporation exemplifies a provider with an extensive portfolio spanning both thermal and non-thermal processing. Tetra Pak International S.A., a Swedish-Swiss multinational food packaging and processing company, occupies a position as a specialist in integrated aseptic sterilization lines for liquid foods and beverages. Meanwhile, Allpax Products, a US-based manufacturer, anchors the segment focused on retort and autoclave systems for the North American canning industry. These companies represent different approaches to serving the varied demands of the food sterilization equipment market.
| Leading Market Players |
|---|
| DE LAMA S.P.A. |
| Surdry |
| JBT Corporation |
| Steriflow |
| Ventilex |
| Allpax Products |
| HISAKA WORKS |
| Tetra Pak International S.A. |
| Cosmed Group |
| Others |
Cost & Logistics Intelligence
China's GB standards, influencing market access and equipment design, gate both supply qualification for advanced sterilization systems and price differentiation across the food sterilization equipment market. This regulatory framework necessitates significant investment in compliance, which manufacturers reflect in their pricing strategies.
Pricing Analysis
The US FDA's Food Safety Modernization Act (FSMA) dictates the pricing tier structure for equipment with superior process control and validation capabilities. Pricing in this market often follows a contract-based long-term offtake model, particularly for large-scale integrated lines. Price differentiation drivers include the customization level for specific food matrices and the inclusion of comprehensive after-sales service packages. Pricing softness reflects intense competition among thermal system manufacturers, especially for standardized autoclaves. Small and medium-sized food processors exhibit the highest price sensitivity, often seeking more cost-effective, batch-based solutions.
Supply Chain Analysis
Strategic stockpiling of critical components balances against just-in-time delivery for highly customized systems within the food sterilization equipment supply chain. Geographic supply concentration for advanced manufacturing centers on Germany, China, and the United States. Key raw material dependencies include specialized stainless steel alloys for pressure vessels, precision instrumentation, and advanced control system electronics. A structural risk involves single-source vulnerability for highly specialized non-thermal processing components. Distribution primarily runs through direct sales channels and specialized integrators serving large food processing plants and beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A significant shortage of technicians and engineers qualified for complex HPP and aseptic systems limits market expansion. This capability gap creates both operational bottlenecks and strategic opportunities for specialized firms.
For Market Incumbents:Compound investment in R&D for continuous-flow HPP systems to counter the maturation of non-thermal technologies. Diversify product portfolios by acquiring niche firms specializing in process intelligence integration to enhance predictive maintenance capabilities. Expand manufacturing footprints in Southeast Asian nations to penetrate underpenetrated markets, leveraging existing thermal system expertise. Focus on developing modular, scalable solutions to meet varied processing needs.
For New Entrants and Emerging Players:The service-layer gap in validating and maintaining advanced non-thermal equipment presents a significant opportunity. Target plant-based product sterilization as a white-space segment, developing equipment optimized for unique textures and formulations. Penetrate the Southeast Asian market by offering integrated, energy-efficient thermal and non-thermal solutions. Emphasize a value proposition centered on real-time process optimization and data traceability for minimally processed foods.
For Investors and Strategic Acquirers:The US FDA's FSMA reshapes the acquisition landscape, favoring companies with proven validation and process control capabilities. The food sterilization equipment market offers strong growth potential over the next decade, driven by regulatory compliance and consumer demand shifts. Acquisition targets should be niche firms innovating specific non-thermal technologies or advanced process intelligence solutions. A critical signal to watch is the commercialization of continuous-flow non-thermal systems with lower capital outlay requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Non-Thermal Solutions | Broadens market reach and addresses consumer demand for minimally processed, high-quality foods. |
| Geographic Expansion into Southeast Asia | Captures new demand from modernizing food processing industries in emerging markets. |
| Investment in Process Intelligence Integration | Enhances equipment value proposition through predictive maintenance and real-time operational optimization. |
| Development of Energy-Efficient Thermal Systems | Addresses operator concerns regarding volatile energy costs and sustainability targets. |
| Strategic Partnerships for Specialized Skill Development | Mitigates the industry-wide shortage of qualified technicians for advanced sterilization technologies. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from comprehensive market reports. Primary research involved discussions with food processing plant managers, beverage manufacturers, equipment engineers, and regulatory compliance officers. Secondary sources included US FDA filings, EFSA reports, China GB standards, and industry association publications, ensuring a robust data foundation. Bottom-up and top-down triangulation methods validated all data points.
The analytical framework modeled market dynamics across the analysis window, segmenting by product type, technology, application, and end-user. This approach captured granular shifts in demand and supply. Compound annual growth rates were derived from historical data and projected market shifts, incorporating factors like consumer demand for convenience and evolving regulatory enforcement trends. Quantitative models assessed the impact of technological advancements and regional economic development on market expansion.
Underlying assumptions cover technological advancements and regulatory stability, with deviation risk concentrated in volatile energy costs and geopolitical trade policies. Practitioners should keep alternative scenarios live as adoption rates and regulatory landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Optical Sorter Market