
 Global Fermenters Market | 2026-2036
Global Fermenters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fermenters Market Analysis
Market Context with Strategic Players
A shift from single-source equipment procurement toward multi-vendor validation strategies is rebalancing capital deployment across biopharma facilities. Lonza Group AG leverages its integrated CDMO footprint to anchor demand for high-volume industrial-scale systems, while Sartorius AG sustains technology leadership through membrane-aerated and single-use stirred-tank platforms. Thermo Fisher Scientific competes on global service density, extending calibration and qualification networks that reduce facility downtime for multi-product sites.
Technical Definition and Structural Segments
A fermenter is a closed bioreactor vessel engineered to maintain sterile conditions while controlling temperature, pH, dissolved oxygen, and agitation to cultivate microorganisms or mammalian cells for industrial metabolite production, with working volumes spanning laboratory-scale glass vessels to stainless-steel industrial tanks exceeding 50,000 liters. Stirred-tank designs dominate current installed base due to proven scalability and mixing efficiency across pharmaceutical applications, while airlift configurations capture fastest-growing interest in shear-sensitive cell culture where bubble-free oxygen transfer preserves viability. Pilot-scale systems concentrate margin pools as contract manufacturers demand flexible capacity bridging clinical and commercial production without full industrial capital commitment.
Regulatory Frame and Forward-Looking Close
FDA process validation guidance, EMA GMP Annex 1 revisions on contamination control, and ISO 14644 cleanroom classification standards collectively elevate equipment qualification burdens and accelerate replacement cycles in licensed facilities. The EPA's emerging bioprocess waste-stream monitoring requirements in the United States and China's NMPA biologics manufacturing inspections are expanding demand for closed-system fermenters with integrated sampling and automated clean-in-place protocols. Stakeholders must monitor regulatory divergence between FDA's risk-based inspection framework and EMA's tightened environmental monitoring rules when configuring multi-region supply strategies.
Market Dynamics
Single-use bioprocessing technology is fragmenting capital deployment patterns across pharmaceutical manufacturing, forcing stainless-steel incumbents to defend installed base through hybrid retrofit programs while contract manufacturers prioritize disposable capacity for multi-product flexibility.
Growth Catalysts
- EMA GMP Annex 1 contamination control mandates:European biologics facilities face accelerated replacement cycles for open-system fermenters, driving demand for closed-system designs with integrated sampling ports.
- Cell and gene therapy pipeline expansion:Viral vector production requires shear-sensitive cultivation platforms, pulling investment toward low-turbulence airlift and oscillating fermenter configurations.
- China NMPA biologics manufacturing inspections:Domestic CDMOs are scaling GMP-compliant capacity to serve international sponsor demand, concentrating orders for automated clean-in-place systems.
Market Restraints
- Specialized alloy supply concentration:Pharmaceutical-grade 316L stainless steel and electropolished finishes depend on German and Japanese metallurgical suppliers, exposing lead time volatility.
- Single-use polymer cost structure:Film-grade polyethylene and silicone tubing face petrochemical feedstock price swings that compress margins on disposable bioreactor bags.
- Skill scarcity in aseptic processing:Qualified fermentation scientists and GMP validation engineers concentrate in established biopharma clusters, constraining facility expansion in emerging production regions.
Strategic Opportunities
- India CDMO capacity buildout:PLI scheme incentives for biopharma manufacturing are attracting greenfield investments in Bangalore and Hyderabad, creating demand for pilot-scale flexible systems.
- Precision fermentation for food proteins:Alternative protein startups require novel metabolite-optimized platforms, opening white space beyond traditional pharmaceutical applications.
- Digital twin integration:Convergence of process analytical technology with AI-driven predictive control enables remote qualification and reduced on-site validation labor.
Industry Challenges
- Multi-vendor qualification complexity:Facilities integrating stirred-tank hardware from Sartorius with automation from Siemens face extended FAT/SAT timelines and documentation reconciliation.
- Legacy system interoperability:Brownfield sites retrofitting 1990s-era stainless vessels with modern SCADA layers encounter protocol mismatches that delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fermenters Market |
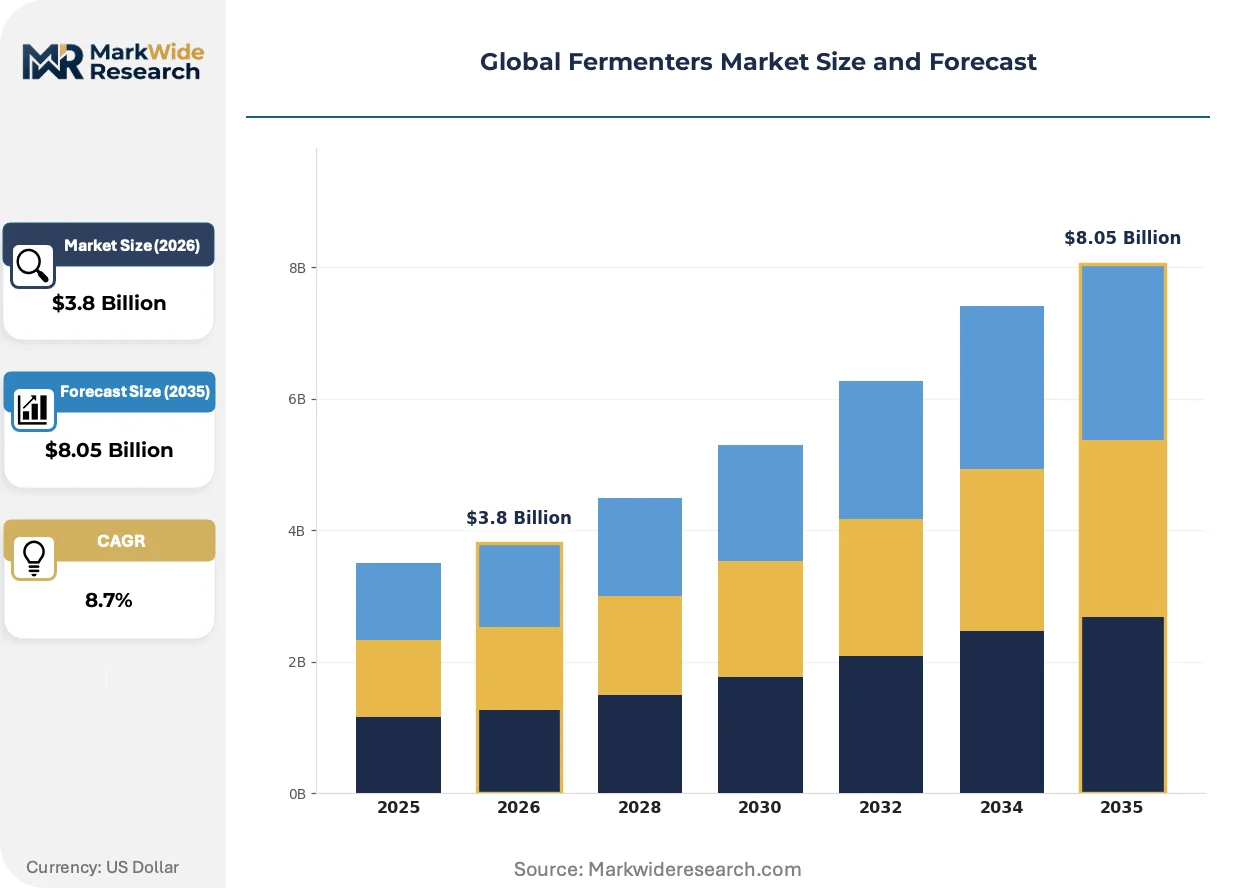
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Airlift, Bubble Column, Continuous Fermenter Application: Food Production, Pharmaceuticals, Biofuels, Wastewater Treatment End User: Industries, Laboratories, Research Institutions, Agriculture Size: Laboratory Scale, Pilot Scale, Industrial Scale, Custom Scale |
| Companies Covered | Eppendorf AG, Lonza Group AG, Sartorius AG, PBS Biotech, Cytiva, Merck KGaA, Applikon Biotechnology, Solaris Biotech, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fermenters Market Emerging Trajectories
Continuous processing architectures are compressing batch cycle times and challenging traditional fed-batch dominance, while modular facility designs enable rapid capacity redeployment across therapeutic modalities.
Single-use stirred-tank platforms are decentralizing biologics manufacturing from centralized mega-sites to distributed regional supply networks. Mid-size CDMOs in Singapore and Ireland are adopting 2,000-liter disposable systems for commercial antibody production. This technology is decentralizing supply chain risk by enabling multi-source manufacturing without stainless-steel capital lock-in.
EPA bioprocess waste-stream monitoring requirements are tightening effluent control for antibiotic and hormone fermentation discharge. US-based facilities must install real-time metabolite detection and automated diversion systems. Bulk active pharmaceutical ingredient manufacturers in Puerto Rico and North Carolina are retrofitting anaerobic digestion pretreatment to meet emerging NPDES permit conditions.
Equipment-as-a-service contracting is displacing traditional capital purchase models among emerging biotech sponsors. Leasing arrangements with bundled validation and maintenance reduce upfront cash requirements for clinical-stage companies. This shift concentrates most visibly in Boston and San Francisco where venture-funded startups prioritize balance-sheet flexibility over asset ownership.
Global Fermenters Market Segmentation
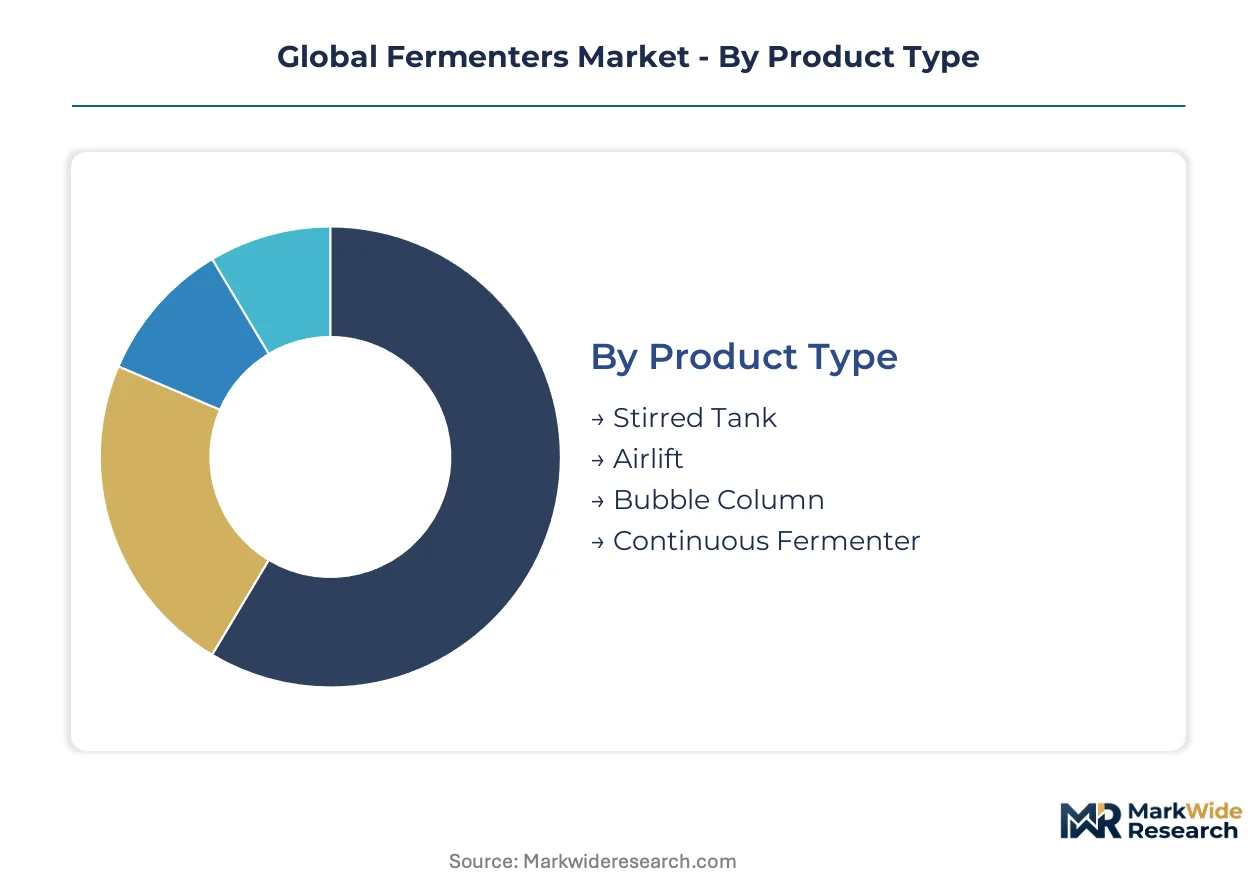
Fermenter segmentation reveals how equipment specifications diverge across therapeutic modalities, production volumes, and regulatory environments. Understanding these divisions enables targeted capacity planning and vendor selection aligned to specific bioprocess requirements.
Product Type:
Standardized stirred-tank platforms dominate high-volume manufacturing, while specialized configurations address shear-sensitive applications where customization commands premium positioning.
- Stirred Tank:Mechanical agitation systems with impeller-based mixing deliver proven oxygen transfer efficiency across mammalian cell and microbial cultures. Contract manufacturers in Germany and Massachusetts concentrate procurement here for antibody commercialization, driven by FDA process validation requirements for established platform technologies.
- Airlift:Bubble-driven circulation eliminates mechanical shear through pneumatic mixing, preserving viability in viral vector and stem cell applications. Singapore-based cell therapy CDMOs are scaling airlift capacity fastest, pulled by EMA GMP Annex 1 contamination control mandates favoring closed-system designs.
- Bubble Column:Simplified pneumatic reactors without internal moving parts suit high-density microbial fermentations in enzyme and organic acid production.
- Continuous Fermenter:Steady-state perfusion configurations compress cycle times for integrated continuous bioprocessing architectures in next-generation facility designs.
Leading the category by volume: Stirred Tank. Expanding most quickly: Airlift.
Application:
Application-driven segmentation traces capital allocation from mature bulk chemical markets toward precision biologics with steeper qualification burdens and longer equipment replacement cycles.
- Pharmaceuticals:GMP-compliant systems for monoclonal antibody, vaccine, and recombinant protein production require 316L stainless steel construction, automated clean-in-place protocols, and extensive IQ/OQ/PQ documentation. FDA and EMA inspection intensity in Puerto Rico and Ireland sustains replacement demand for legacy open-system vessels.
- Food Production:Industrial-scale systems for enzyme, amino acid, and fermented ingredient manufacturing prioritize throughput over sterile containment, with 10,000+ liter vessels common in citric acid and yeast extract facilities.
- Biofuels:Cellulosic ethanol and advanced biofuel applications drive demand for robust, corrosion-resistant designs handling lignocellulosic hydrolysates and C5/C6 sugar mixtures.
- Wastewater Treatment:Anaerobic digestion systems for industrial effluent and biogas recovery operate under less stringent material specifications, with concrete or coated steel construction dominating.
Capturing highest equipment margins: Pharmaceuticals. Steepest expansion trajectory: Biofuels, as renewable fuel mandates tighten across the European Union and United States.
End User:
End user categories separate capital-intensive industrial deployments from flexible laboratory systems where rapid reconfiguration outweighs unit economics.
- Industries:Commercial manufacturing facilities operate stainless-steel trains at 2,000-20,000 liter working volumes with integrated distributed control systems and SCADA layers for batch record automation.
- Laboratories:Bench-top and pilot-scale glass or single-use systems enable process development, clone selection, and small-batch clinical material supply with minimal facility infrastructure.
- Research Institutions:University and government laboratory procurement emphasizes modularity and multi-purpose capability across microbial, mammalian, and insect cell platforms.
- Agriculture:Silage inoculant and biocontrol agent producers utilize mid-scale fermenters with simplified automation for agricultural microbiome products.
Commanding largest capital deployment: Industries. Gaining share fastest: Laboratories, as decentralized biologics manufacturing and single-use technology adoption accelerate.
Size:
Scale segmentation maps the progression from discovery-phase screening through commercial manufacturing, with intermediate pilot systems capturing disproportionate strategic attention for their flexibility bridge function.
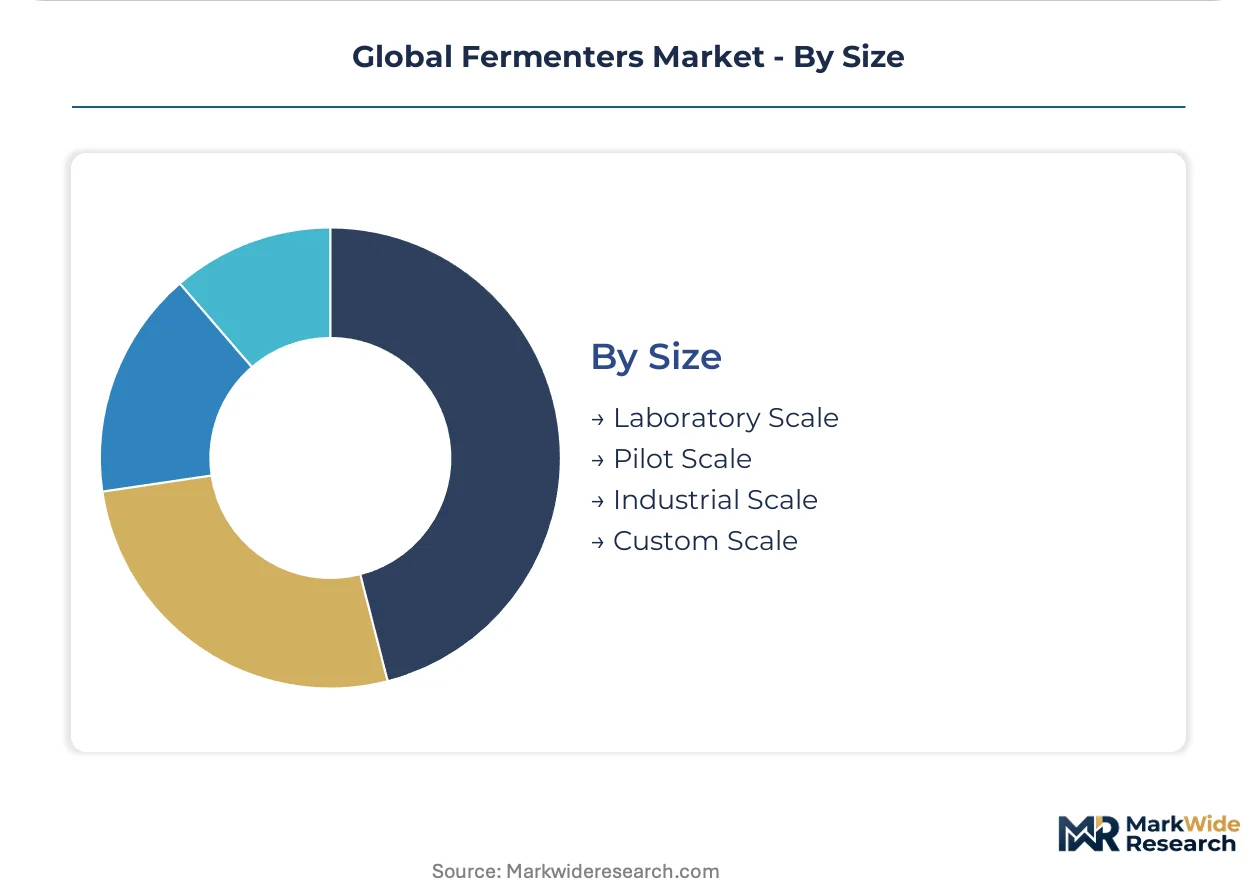
- Pilot Scale:50-500 liter working volume systems enable process characterization, engineering runs, and Phase I/II clinical material supply without full industrial capital commitment. CDMOs in Bangalore and Hyderabad under India's PLI scheme concentrate investment here to serve international sponsor demand with rapid scale-up pathways.
- Industrial Scale:2,000-50,000+ liter production trains anchor commercial antibody and vaccine supply, with Lonza's Visp facility and Samsung Biologics' Songdo campus representing installed base benchmarks.
- Laboratory Scale:1-20 liter vessels support media optimization, strain engineering, and early-stage cell line development in discovery-phase biopharma.
- Custom Scale:Bespoke configurations for continuous processing, solid-state fermentation, or extreme operating conditions address niche metabolite production requirements.
Leading by installed base value: Industrial Scale. Climbing the fastest: Pilot Scale, as contract manufacturers prioritize flexible capacity bridging clinical and commercial production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade stainless steel and Japanese electropolished alloys anchor the fermenter supply base, while demand clusters concentrate in biopharma manufacturing corridors across five countries.
United States
FDA process validation guidance and EMA-aligned GMP upgrades drive replacement cycles for legacy open-system vessels. EPA bioprocess waste-stream monitoring mandates tighten effluent controls at Puerto Rico and North Carolina bulk API facilities. Boston and San Francisco biotech clusters accelerate equipment-as-a-service adoption among venture-funded startups prioritizing balance-sheet flexibility.
Germany
EMA GMP Annex 1 contamination control revisions accelerate closed-system fermenter procurement across European biologics facilities. Eppendorf AG and Sartorius AG anchor a dense supplier ecosystem serving CDMO demand. The Hamburg-Göttingen corridor concentrates membrane-aerated and single-use stirred-tank platform development for antibody commercialization.
China
NMPA biologics manufacturing inspections push domestic CDMOs toward automated clean-in-place systems and GMP-compliant capacity scaling. International sponsor demand concentrates orders for stainless-steel trains at Songdo-scale facilities. Shanghai and Suzhou biopharma parks attract greenfield investments targeting export-oriented antibody production.
India
PLI scheme incentives for biopharma manufacturing attract greenfield investments in Bangalore and Hyderabad pilot-scale flexible systems. CDMOs concentrate procurement on 50-500 liter working volume platforms bridging clinical and commercial production. The Bangalore-Hyderabad corridor serves international sponsor demand with rapid scale-up pathways.
Singapore
EMA-aligned regulatory infrastructure and proximity to Asian biopharma markets position the city-state for cell therapy CDMO expansion. Airlift fermenter configurations scale fastest among shear-sensitive viral vector producers. The Tuas Biomedical Park concentrates 2,000-liter disposable system deployments for commercial antibody manufacturing.
Global Fermenters Market Vendor Landscape
Global majors compete with regional champions across technology platforms and service density dimensions. The vendor base organizes around three tiers: integrated life science conglomerates with calibration networks, specialized bioprocess equipment pure-plays, and emerging precision fermentation technology providers. Consolidation pressure concentrates among stainless-steel incumbents defending installed base against single-use disruption. Strategic moves cluster on hybrid retrofit programs and equipment-as-a-service contracting models.
Within the integrated conglomerate tier, Thermo Fisher Scientific exemplifies global service density advantages, while Lonza Group AG occupies a position anchoring demand through CDMO footprint integration. Among German specialized fabricators, Eppendorf AG and Sartorius AG represent membrane-aerated and single-use platform leadership. These three entities sit within distinct competitive archetypes: service-network scale, vertical demand integration, and technology specialization respectively.
| Leading Market Players |
|---|
| Eppendorf AG |
| Lonza Group AG |
| Sartorius AG |
| PBS Biotech |
| Cytiva |
| Merck KGaA |
| Applikon Biotechnology |
| Solaris Biotech |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
EMA GMP Annex 1 contamination control mandates are forcing European biologics facilities toward closed-system fermenter retrofits, compelling suppliers to absorb qualification documentation costs while passing alloy-grade premiums through to buyers. This specification-driven procurement shift concentrates pricing power with German and Japanese metallurgical vendors capable of pharmaceutical-grade 316L electropolished finishes.
Pricing Analysis
Extended warranty and validation service bundling now separates premium-tier suppliers from standard equipment vendors, with IQ/OQ/PQ documentation packages and multi-year calibration contracts commanding 15-25% price premiums over bare hardware transactions. Price differentiation hinges on FDA process validation readiness and single-use film-grade polymer traceability, with certification-grade stainless steel facing cost compression from hybrid retrofit programs while disposable bioreactor bags absorb petrochemical feedstock volatility. Clinical-stage biotech sponsors in Boston and San Francisco exhibit highest price sensitivity, prioritizing equipment-as-a-service leasing over capital purchase.
Supply Chain Analysis
Pharmaceutical-grade 316L stainless steel supply rests on German metallurgical producers and Japanese electropolishing specialists, with silicone tubing and film-grade polyethylene drawing from petrochemical complexes in South Korea and the United States. Single-source dependency on electropolished vessel fabrication creates vulnerability to lead time volatility when order books saturate. Distribution runs through authorized service networks requiring factory-trained validation engineers, privileging incumbents with dense calibration footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy supply concentration and qualified fermentation scientist scarcity constrain capacity expansion, propping equipment pricing across GMP-compliant system tiers. This supply-constrained structure rewards early positioning in qualification-heavy market segments.
For Market Incumbents: Acquire single-use film manufacturing capabilities to defend against polymer cost volatility and capture margin pools from disposable bioreactor growth. Hybrid retrofit programs for legacy stainless-steel installed base, combined with backward integration into electropolished vessel fabrication, counter emerging pure-play single-use challengers. For New Entrants and Emerging Players: India's PLI scheme for biopharma manufacturing opens a window for pilot-scale flexible system penetration among Bangalore and Hyderabad CDMOs. Precision fermentation platforms for alternative protein applications represent the most penetrable white space, with novel metabolite-optimized configurations enabling differentiated positioning beyond pharmaceutical incumbency. For Investors and Strategic Acquirers: Re-rating potential sits with equipment-as-a-service platform providers given balance-sheet flexibility preferences among venture-funded biotech sponsors. Long-term viability over a 5-10 year window favors vendors with dense validation engineer networks and recurring revenue streams. Watch FDA process analytical technology enforcement intensity as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Retrofit Program | Extends stainless-steel incumbent relevance against single-use disruption by upgrading legacy vessels with closed-system sampling and modern SCADA layers. |
| Equipment-as-a-Service Contracting | Reduces upfront capital barriers for clinical-stage biotech sponsors while concentrating recurring revenue with validation-bundled maintenance. |
| Single-Use Film Manufacturing Integration | Captures polymer margin pools and insulates against petrochemical feedstock volatility compressing disposable bioreactor bag economics. |
| Digital Twin Platform Development | Enables remote qualification and predictive process control, reducing on-site validation labor for multi-product CDMO facilities. |
| Precision Fermentation Technology Partnership | Opens alternative protein white space beyond traditional pharmaceutical applications through metabolite-optimized platform configurations. |
Methodological Framework
Multi-period observation of FDA warning letter trends, EMA inspection deficiency patterns, and CDMO capital expenditure disclosures anchored the trend analysis, supplemented by interviews with fermentation scientists, GMP validation engineers, biopharma procurement directors, and equipment service technicians. Secondary validation drew from FDA 483 observation databases, EMA GMP inspection reports, ISO 14644 cleanroom certification records, and SEC filings of listed CDMOs. Bottom-up equipment procurement tracking triangulated against top-down biologics manufacturing capacity estimates.
Input-output matrices modeled fermenter demand across product type, application, end user, and size dimensions, with therapeutic modality and regional regulatory cluster as cross-cutting segmentation variables. CAGRs were derived from installed base replacement cycles, pipeline expansion trajectories, and greenfield facility announcements. Forecast inputs incorporated single-use technology adoption curves, stainless-steel hybrid retrofit penetration rates, and precision fermentation capacity buildouts.
The model assumes a particular technology adoption path; alternative pathways for continuous bioprocessing architectures would alter the outlook if perfusion-based systems displace traditional fed-batch dominance faster than projected. Regulatory divergence between FDA risk-based inspection frameworks and EMA tightened environmental monitoring rules, alongside specialized alloy supply disruptions, constitute revision triggers. A small set of named triggers—NMPA inspection intensity, PLI scheme disbursement velocity, and EPA bioprocess effluent enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market