
 Freeze Dried Vegetables Market | 2026-2036
Freeze Dried Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Vegetables Market Analysis
Advanced vacuum microwave drying is reconfiguring energy throughput and nutrient retention benchmarks across freeze dried vegetable production lines. OFD Foods leverages proprietary low-temperature processing infrastructure to sustain premium positioning in emergency preparedness channels. Van Drunen Farms anchors North American supply through backward integration into raw vegetable sourcing. Ajinomoto Co. competes on umami-enhanced seasoning blends that incorporate freeze dried vegetables into Asian convenience food formulations.
Freeze dried vegetables retain 97-99% of original nutritional content through sublimation-based moisture removal at pressures below 610 pascals, yielding lightweight products with 12-24 month ambient stability for commercial and consumer applications. The product type dimension shows carrots and peas occupying mature volume positions while spinach and bell peppers capture expanding margins in meal kit and clean-label snacking formulations. Distribution through online retail and specialty stores is accelerating fastest as direct-to-consumer brands bypass conventional wholesale markups, though supermarkets still control the majority of household purchase volume.
The FDA enforces Hazard Analysis and Risk-Based Preventive Controls under FSMA for domestic freeze dried vegetable facilities, while the USDA monitors organic certification claims across product lines. The EPA regulates wastewater discharge and energy consumption thresholds for large-scale lyophilization operations, particularly in California and Washington processing clusters. Stakeholders must monitor evolving state-level extended producer responsibility legislation for food packaging and assess whether captive drying capacity or contract manufacturing delivers superior unit economics at current scale.
Market Dynamics
Meal kit services and emergency preparedness channels are pulling freeze dried vegetable demand toward premium, long-shelf-life formats while FDA preventive control mandates under FSMA force capital upgrades across domestic lyophilization infrastructure.
Growth Catalysts
- FSMA Hazard Analysis Requirements:The FDA's updated preventive controls mandate facility upgrades that filter smaller producers and consolidate volume among compliant operators, tightening supply quality.
- Meal Kit Channel Expansion:Direct-to-consumer recipe box services specify freeze dried vegetables for portion precision and 12-month ambient stability, locking in multi-year procurement contracts.
- Vacuum Microwave Drying Adoption:Advanced sublimation equipment cuts energy throughput by one-third versus conventional lyophilization while preserving 97% nutrient retention, reshaping unit economics at scale.
Market Restraints
- Energy Cost Volatility:Natural gas and electricity price spikes in California and Washington processing clusters compress margins on batch lyophilization cycles that run 20-40 hours per load.
- Organic Vegetable Supply Concentration:Certified organic raw material sourcing concentrates in the Pacific Northwest and Central Valley, creating single-region dependency for premium product lines.
- Retort Pouch Substitution:Wet-packed vegetables in shelf-stable pouches compete on lower per-serving cost for institutional feeding and military applications where rehydration time is less critical.
Strategic Opportunities
- Clean-Label Snacking Formulations:Bell pepper and spinach crisps in resealable pouches target health-conscious millennials through specialty retail and online subscription models.
- USDA Organic Certification Tailwinds:Federal procurement preferences and retailer slotting fee reductions for certified organic products open institutional and foodservice channels.
- Hybrid Drying Technology Convergence:Combining vacuum microwave with atmospheric freeze drying reduces capital intensity for mid-scale entrants while maintaining premium quality thresholds.
Industry Challenges
- Lyophilization Technician Shortage:Specialized operators who can monitor sublimation endpoints and troubleshoot vacuum seal integrity command 40% wage premiums in tight labor markets.
- FSMA Compliance Timeline Compression:Smaller facilities face 18-24 month validation cycles for preventive control plans and supply chain documentation, delaying revenue recognition.
- Packaging EPR Integration Complexity:California and Washington extended producer responsibility laws require reverse logistics infrastructure that legacy distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Vegetables Market |
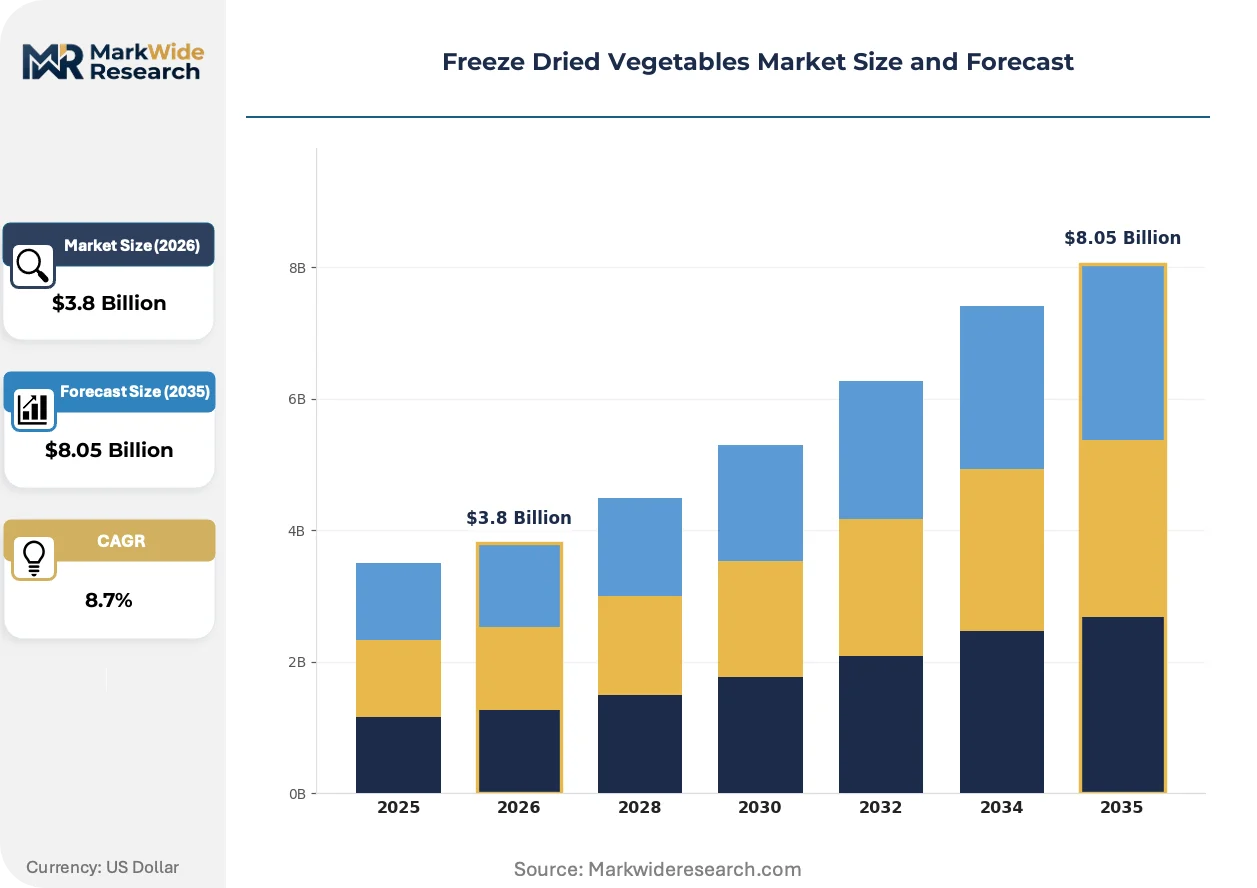
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrots, Peas, Spinach, Bell Peppers End User: Households, Food Manufacturers, Restaurants, Meal Kit Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Snacking, Cooking, Baking, Emergency Preparedness |
| Companies Covered | Nestle S.A., The Kraft Heinz Company, OFD Foods, The J M Smucker Company, Van Drunen Farms, Mercer Foods, European Freeze Dry, Olam International, Ajinomoto Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Vegetables Market Emerging Trajectories
Processing technology, regulatory stringency, and channel disintermediation are converging to restructure competitive advantage around energy efficiency, compliance automation, and direct consumer relationships.
Vacuum microwave drying systems are hybridizing conventional lyophilization workflows by integrating microwave energy delivery with sublimation chambers, cutting cycle times from 24 hours to 8 hours for diced carrots and peas. Meal kit formulators and emergency food suppliers are adopting these hybrid lines fastest, prioritizing throughput over absolute nutrient retention for mid-tier product tiers. The technology is hybridizing capital deployment patterns, enabling mid-cap processors to compete on volume without replicating industrial-scale freeze drying footprints.
The EPA's wastewater discharge thresholds for large-scale lyophilization operations in California processing clusters are forcing zero-liquid-discharge system installations and real-time effluent monitoring. Facilities exceeding 100,000 gallons daily processed volume must retrofit closed-loop cooling and solids recovery infrastructure by 2027. Washington and Oregon facilities are accelerating pre-compliance investments to avoid seasonal discharge moratoriums that interrupt peak harvest processing windows.
Direct-to-consumer brands are bypassing conventional wholesale markups through specialty retail placement and subscription box integration, capturing margin that previously flowed to distributor networks. Clean-label positioning and transparent sourcing narratives are displacing price-driven supermarket procurement for premium vegetable blends. This channel rotation is most visible in United States coastal metro markets where specialty grocers and online platforms command 35% of freeze dried vegetable household purchases.
Freeze Dried Vegetables Market Segmentation
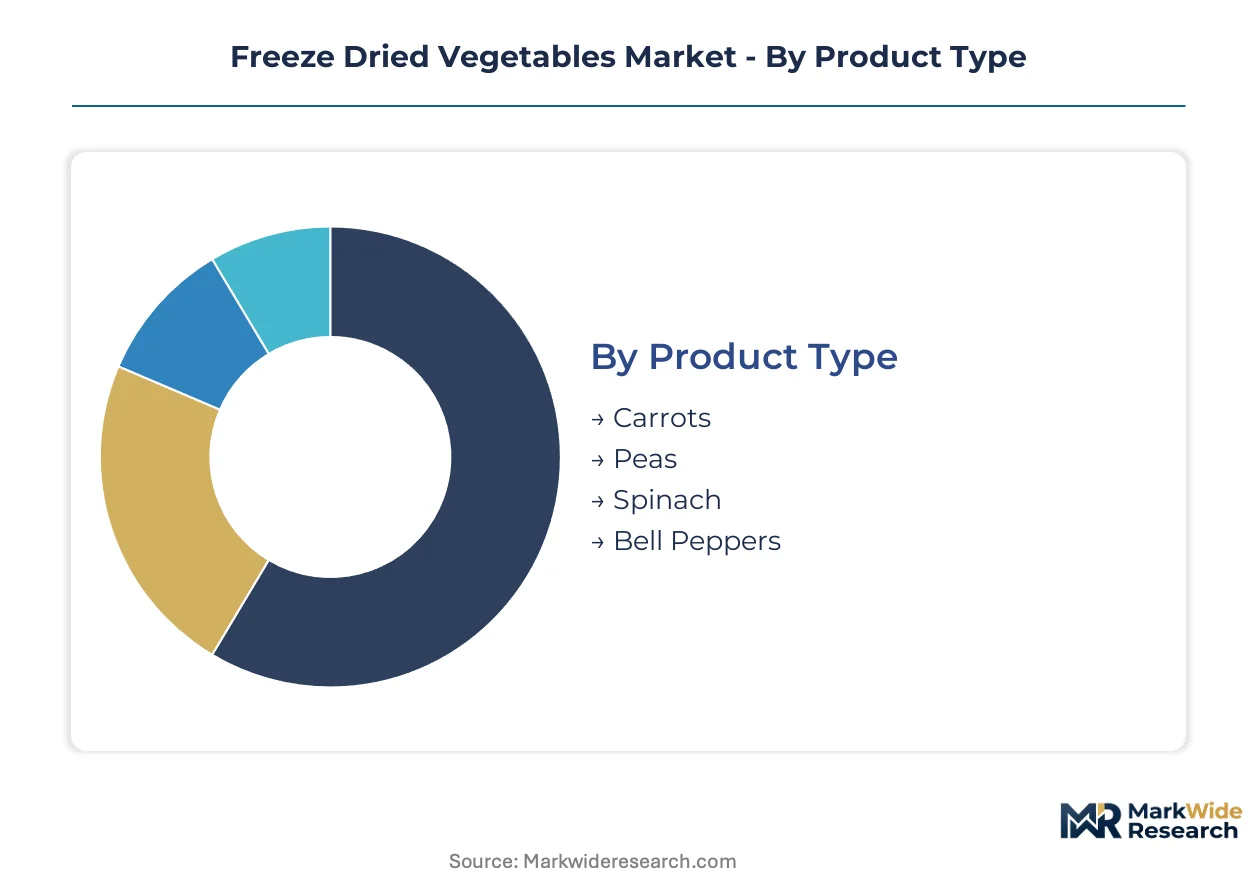
Freeze dried vegetables serve divergent functional requirements across emergency stockpiling, precision cooking, and clean-label snacking. Segmentation reveals how processing specifications, shelf-life demands, and channel economics allocate volume and margin across distinct buyer categories.
Product Type:
Root vegetables, legumes, leafy greens, and capsicum variants each command different lyophilization parameters and rehydration performance profiles.
- Carrots:Diced and sliced formats dominate institutional procurement for their uniform rehydration and beta-carotene stability through sublimation. United States meal kit services specify carrot blends for color consistency and 12-month ambient shelf requirements in recipe box formulations.
- Peas:Whole green peas retain cellular structure through controlled freezing rates, yielding intact texture upon reconstitution. Emergency preparedness channels in the United States pull premium volumes for lightweight, high-protein storage formats with 24-month stability.
- Spinach:Leafy structure demands gentler vacuum protocols to prevent cellular collapse; clean-label snacking applications in specialty retail favor crisped spinach for nutrient density positioning.
- Bell Peppers:Red, yellow, and green variants require precise moisture removal to preserve volatile compounds; hybrid drying adoption is climbing fastest for pepper strips targeting gourmet cooking segments.
The dominant share belongs to carrots, while bell peppers are closing the gap fastest.
End User:
Buyer sophistication spans household convenience seekers through industrial-scale formulators with specification-grade procurement protocols.
- Households:Direct consumers prioritize resealable packaging and single-serve formats for pantry stocking and camping applications; United States coastal metro markets show strongest uptake through subscription and specialty retail channels.
- Food Manufacturers:Industrial buyers integrate freeze dried vegetables into soup bases, seasoning blends, and instant noodle formulations where precise moisture content and particle size distribution govern downstream processing yields.
- Restaurants:High-end culinary operations source premium vegetable blends for garnish and texture contrast; rehydration speed and visual integrity drive supplier selection for à la carte plating.
- Meal Kit Services:Direct-to-consumer recipe box operators lock in multi-year procurement contracts for portion-controlled, ambient-stable ingredients that eliminate cold-chain complexity in last-mile fulfillment.
Volume concentrates among food manufacturers, though meal kit services are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture, brand control, and access to specification-driven versus price-sensitive demand pools.
- Online Retail:Direct-to-consumer platforms enable transparent sourcing narratives and subscription bundling; specialty blends and emergency preparedness kits command premium positioning outside conventional wholesale markups.
- Supermarkets:Mass retail controls the majority of household purchase volume through private-label and branded shelf placements; slotting fees and promotional calendars favor established suppliers with scale logistics.
- Specialty Stores:Natural grocers and outdoor retailers curate premium organic and clean-label assortments; United States coastal markets allocate 35% of freeze dried vegetable purchases through this channel.
- Wholesale:Institutional distributors serve foodservice, military, and humanitarian procurement with bulk formats; FSMA-compliant documentation and lot traceability are non-negotiable entry requirements.
Supermarkets retain volume leadership, while online retail is gaining share fastest.
Application:
Functional use cases impose distinct technical specifications on moisture content, rehydration ratios, and packaging formats.
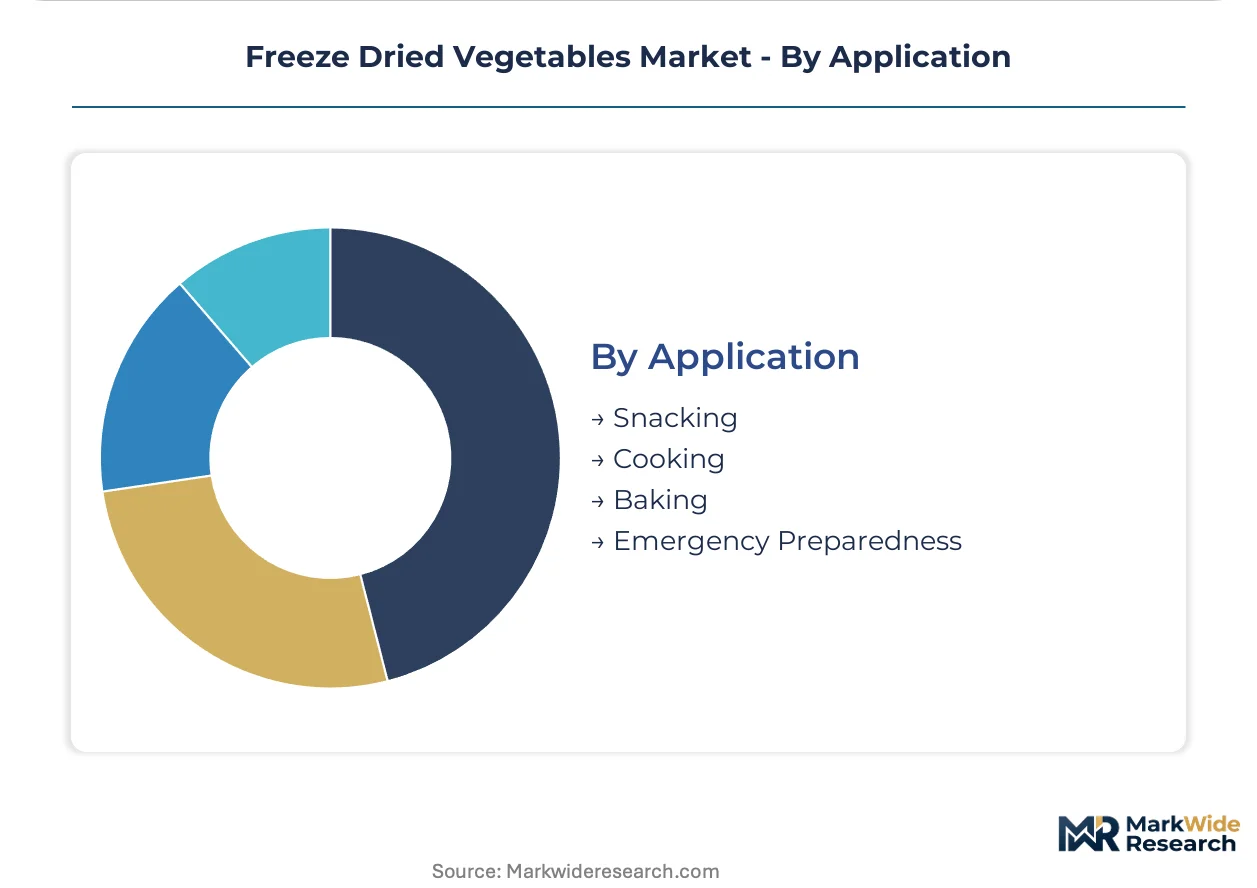
- Snacking:Crisped vegetable formats in resealable pouches target health-conscious millennials; spinach and bell pepper crisps dominate clean-label positioning through specialty retail and subscription models.
- Cooking:Home chefs and meal kit subscribers value rapid rehydration and flavor intensity; carrot and pea blends integrate into one-pot recipes where water absorption timing affects final dish consistency.
- Baking:Powdered and finely diced vegetables incorporate into bread, cracker, and pasta formulations for natural coloring and nutrient fortification; particle size distribution governs dough handling properties.
- Emergency Preparedness:Long-duration storage requirements drive demand for nitrogen-flushed cans and mylar pouches with 25-year stability claims; OFD Foods and legacy suppliers anchor this channel through certified shelf-life testing.
Cooking applications hold the largest share, while emergency preparedness is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meal kit subscribers and emergency preparedness buyers concentrate disproportionately in the United States, where health-conscious consumption and disaster readiness trends intersect with premium pricing tolerance.
United States
Direct-to-consumer meal kit services and outdoor recreation enthusiasts drive freeze dried vegetable uptake through specialty retail and subscription channels. The FDA enforces Hazard Analysis and Risk-Based Preventive Controls under FSMA, requiring domestic lyophilization facilities to validate preventive control plans. California processing clusters face EPA wastewater discharge thresholds that mandate zero-liquid-discharge retrofits by 2027.
Canada
Remote community feeding programs and military procurement specifications sustain demand for lightweight, long-shelf-life vegetable formats. Health Canada monitors food safety compliance through the Safe Food for Canadians Regulations, with particular attention to imported lyophilized products. British Columbia and Alberta host emerging processing capacity serving Pacific Northwest cross-border supply chains.
Germany
Organic-certified product lines gain traction through German retail chains prioritizing clean-label positioning and transparent sourcing narratives. The EU Green Deal's Farm to Fork strategy tightens sustainability documentation requirements for processed vegetable imports. Bavaria and Baden-Württemberg concentrate food technology R&D facilities advancing hybrid drying process optimization.
Japan
Convenience food manufacturers integrate freeze dried vegetables into instant noodle and seasoning formulations where umami enhancement and rapid rehydration prove critical. METI promotes energy-efficient processing equipment adoption through subsidy programs targeting small and medium enterprises. The Kanto region around Tokyo anchors demand from dense urban populations with limited fresh storage space.
Australia
Bushfire preparedness campaigns and remote mining camp catering sustain institutional procurement of extended-shelf-life vegetable products. FSANZ regulates maximum residue limits and labeling requirements for imported and domestically processed freeze dried lines. Victoria and New South Wales processing facilities serve Asia-Pacific export markets with stringent quality certification.
Freeze Dried Vegetables Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: multinational food conglomerates with diversified ingredient portfolios, regional processors with captive agricultural supply relationships, and technology-focused specialists leveraging proprietary drying infrastructure. Consolidation pressure intensifies as FSMA compliance costs filter sub-scale operators while vacuum microwave adoption enables mid-cap challengers to contest volume segments. Dominant competitive moves include backward integration into organic vegetable sourcing and hybrid drying technology licensing to compress capital deployment timelines.
Among North American specialists, OFD Foods and Van Drunen Farms exemplify contrasting positioning strategies. OFD Foods occupies the emergency preparedness channel through certified shelf-life testing protocols, while Van Drunen Farms anchors supply security through upstream agricultural control. Ajinomoto Co. represents the Asian convenience food integration archetype, embedding freeze dried vegetables into seasoning and instant formulation supply chains. These three entities illustrate how geographic origin and channel focus shape competitive differentiation without requiring scale parity with multinational conglomerates.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Kraft Heinz Company |
| OFD Foods |
| The J M Smucker Company |
| Van Drunen Farms |
| Mercer Foods |
| European Freeze Dry |
| Olam International |
| Ajinomoto Co. |
| Others |
Supply Flow & Price Mechanics
Intermodal freight corridors linking Pacific Northwest processing clusters to Midwest distribution hubs transmit volatile diesel and chassis availability costs directly into landed pricing, amplifying margin compression for organic-certified lines while reinforcing tiered pricing separation between captive-sourced and spot-market vegetable inputs.
Pricing Analysis
Cost-plus contracts indexed to California natural gas benchmarks dominate procurement between meal kit services and large-scale lyophilization facilities. Three-tier pricing structure across premium organic, conventional FSMA-compliant, and economy-grade non-certified levels reflects certification investment and energy throughput differentials. Pricing pressure stems from electricity rate spikes in Washington processing zones compressing batch-cycle margins. Food manufacturers exhibit highest price sensitivity due to specification-grade volume procurement, while emergency preparedness channels absorb premiums for certified shelf-life protocols.
Supply Chain Analysis
Supply-chain finance facilities extending 90-120 day payment terms from institutional distributors to mid-scale processors are tightening working capital constraints across the vendor base. Raw material sourcing concentrates in the United States Pacific Northwest and Central Valley for organic vegetables, with Mexico supplementing conventional lines during seasonal gaps. Lyophilization equipment and nitrogen-flushed packaging materials draw from specialized German and Japanese suppliers. Single-region dependency for certified organic feedstock creates structural vulnerability to climate-driven harvest disruption. Distribution runs through wholesale institutional networks for bulk formats, with direct-to-consumer platforms capturing fastest channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze dried vegetables sit in early-cycle expansion as meal kit penetration accelerates and emergency preparedness adoption deepens beyond traditional outdoor recreation demographics.
For Market Incumbents: Harden compliance automation investments to compress FSMA validation cycles below competitor timelines, while securing captive organic acreage in Washington and Oregon to insulate against Pacific Northwest supply concentration risk. Vacuum microwave technology licensing offers defensive positioning against mid-cap challengers contesting volume segments. For New Entrants and Emerging Players: Build out hybrid drying capacity serving clean-label snacking formulations in United States coastal metro markets, where specialty retail slotting fees remain negotiable for differentiated crisped vegetable products. Direct-to-consumer subscription bundling provides the most penetrable go-to-market angle against entrenched supermarket distribution. For Investors and Strategic Acquirers: Technology-focused specialists with proprietary low-temperature infrastructure and validated shelf-life testing protocols represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on energy efficiency differentiation and regulatory compliance moats widening across the projection horizon. Watch for inflection signals in state-level extended producer responsibility enforcement triggering packaging infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Drying Technology Licensing | Reduces capital barriers for mid-scale entrants while preserving FSMA-compliant quality thresholds. |
| Backward Integration into Organic Sourcing | Secures Pacific Northwest acreage against climate-driven supply disruption and certification bottlenecks. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale markups in United States coastal markets where subscription bundling captures premium positioning. |
| Zero-Liquid-Discharge Retrofit Investment | Preempts California EPA enforcement moratoriums interrupting peak harvest processing windows. |
| Clean-Label Snacking Line Extension | Targets health-conscious millennials through spinach and bell pepper crisps in resealable pouch formats. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with lyophilization facility operators, meal kit procurement directors, organic certification auditors, and specialty retail category buyers; and secondary validation against FDA FSMA guidance documents, USDA organic certification databases, EPA discharge permit filings, and California agricultural trade statistics. Bottom-up volume estimates from processing facility throughput were triangulated against top-down demand aggregation across end-use segments.
Forecast inputs spanned vacuum microwave adoption curves, natural gas price trajectories, and meal kit subscriber expansion patterns across the projection horizon. Segmentation dimensions modeled included product type, end user archetype, distribution channel, and application use case. CAGRs were derived from slope-intercept fitting to segment-level volume and value trajectories. Energy efficiency thresholds and regulatory compliance timelines served as industry-specific forecast modifiers.
Stress conditions across electricity cost volatility, organic feedstock availability, and FSMA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology diffusion rates and channel migration patterns. Macroeconomic contraction, regulatory acceleration, or breakthrough drying technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
United States Frozen Yogurt Market