
 Non-Thermal Food Processing Market | 2026-2036
Non-Thermal Food Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Thermal Food Processing Market Outlook
Ready-to-eat meal production is restructuring procurement priorities across commercial kitchens and central commissaries. Hiperbaric leverages its installed base of high-pressure processing systems to anchor demand from premium protein processors. JBT Corporation competes through integrated line solutions that extend from raw intake to sealed packaging. Elea Technology specializes in pulsed electric field equipment for solid and semi-solid food matrices, occupying a distinct technology tier.
Non-thermal food processing encompasses physical preservation methods that inactivate microorganisms and enzymes without exceeding temperatures that degrade sensory or nutritional quality, typically operating below 45°C for high-pressure systems or using pulsed electric fields at 10-80 kV/cm for microseconds. The primary industrial purpose centers on delivering clean-label shelf stability while retaining fresh-like flavor profiles and vitamin content. High Pressure Processing leads value generation due to capital intensity and established validation across juices and guacamole, while Pulsed Electric Fields represents the fastest-growing technology segment as equipment costs decline and throughput rises. Application demand concentrates in juices and sauces where premium positioning justifies unit economics, though ready-to-eat meals are emerging as the next margin pool.
The FDA governs non-thermal processes through juice HACCP and food additive petition pathways, while the EU's EFSA novel food assessment and CE marking requirements shape transatlantic equipment deployment. India's FSSAI is developing specific standards for high-pressure treated products under its food safety modernization push. Stakeholders must monitor how regulatory harmonization between FDA and EFSA validation protocols affects equipment amortization timelines and cross-border technology licensing.
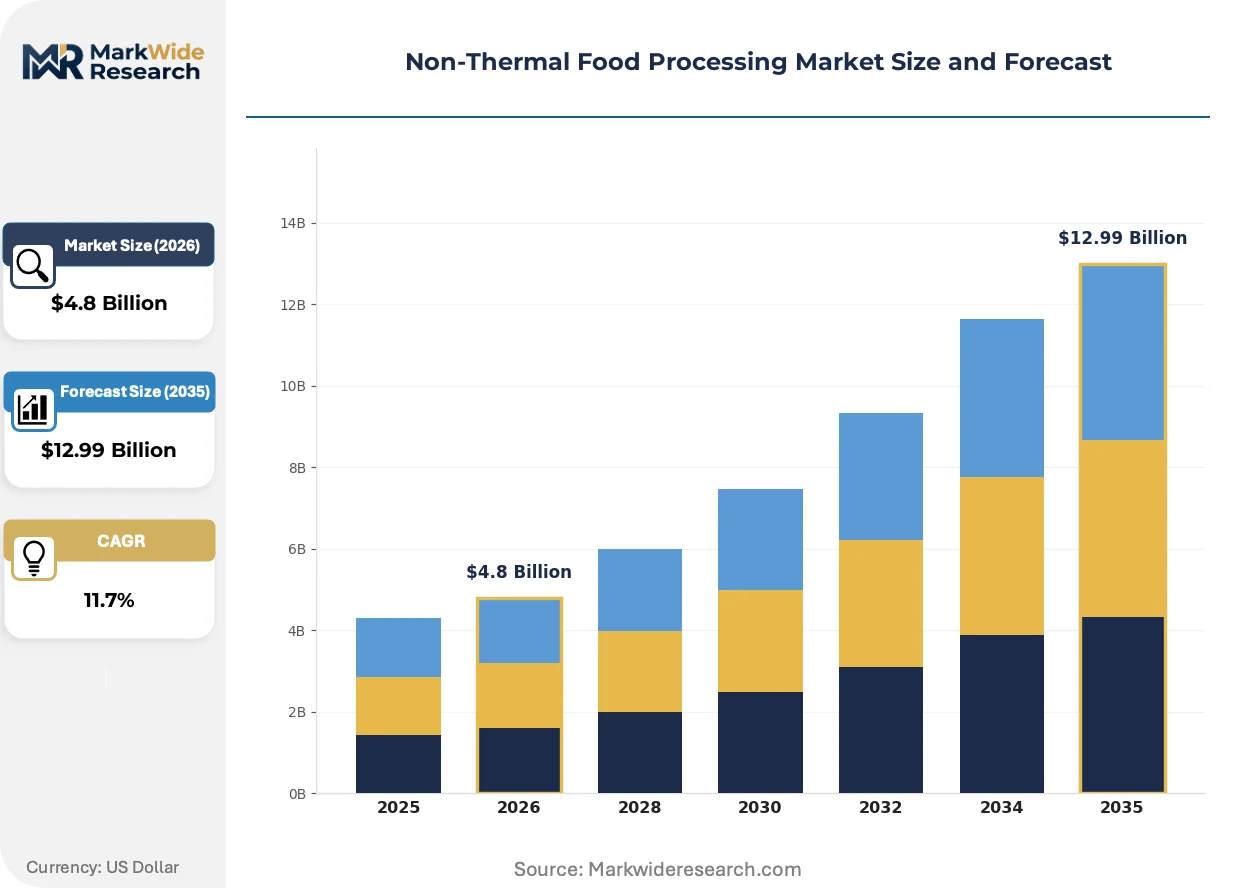
Market Dynamics
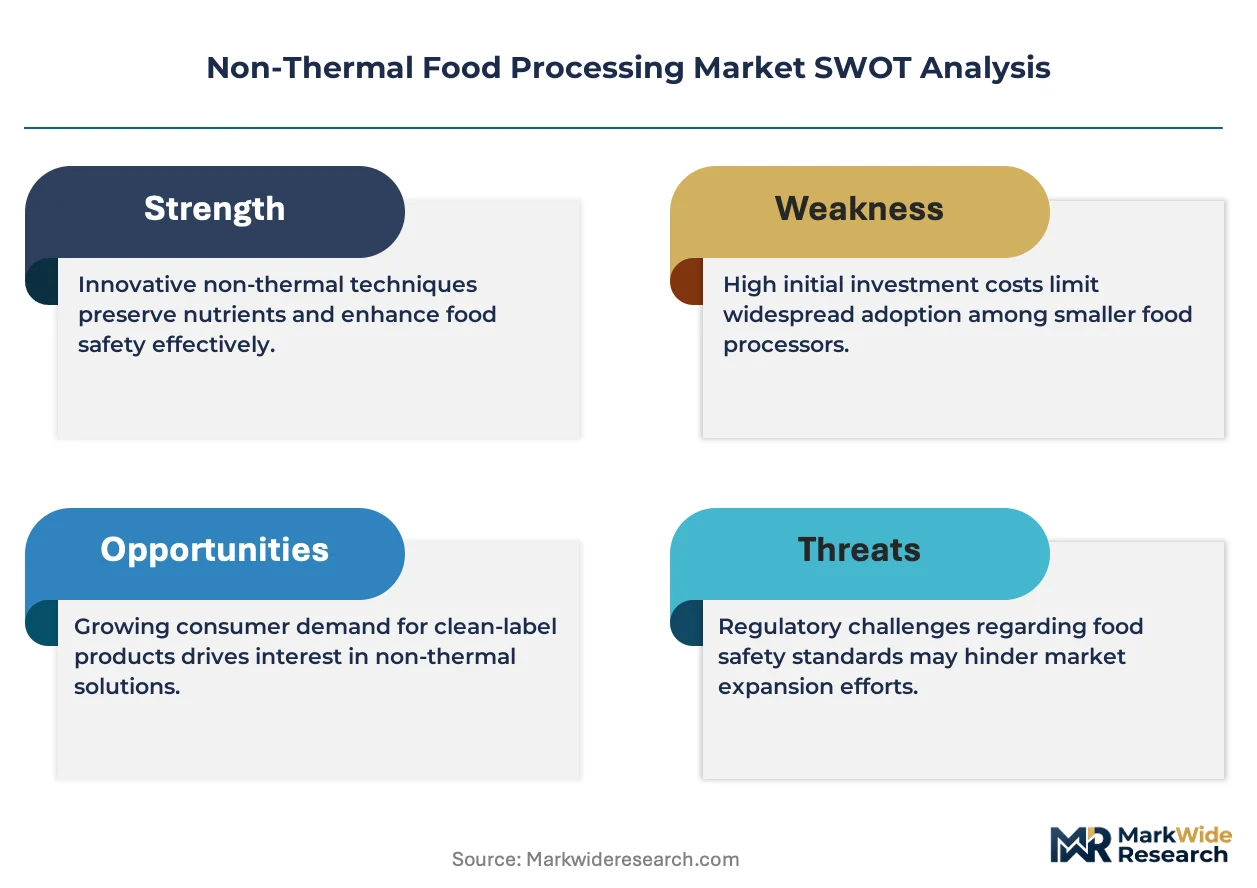
Capital intensity in high-pressure processing equipment is compressing vendor margins while simultaneously raising barriers to entry for new equipment manufacturers, creating a bifurcation between turnkey system providers and component specialists.
Growth Catalysts
- EU Novel Food Framework:EFSA validation pathways for pulsed electric field-treated products are accelerating market authorization timelines for clean-label shelf-stable juices and plant-based beverages across member states.
- Ready-to-eat meal processors:Central commissaries serving foodservice chains are retrofitting cold-pasteurization lines to replace thermal tunnels, preserving vitamin C and fresh flavor in refrigerated prepared foods.
- High-pressure processing:Equipment throughput improvements are reducing per-unit processing costs, enabling adoption in mid-tier protein processors previously priced out of the category.
Market Restraints
- Stainless steel and high-grade alloys:Input cost volatility for pressure vessel materials is squeezing equipment manufacturer margins and extending quote-to-delivery timelines by 8-14 weeks.
- German equipment concentration:Hiperbaric and Elea Technology anchor European supply, creating geographic concentration risk for North American and Asian buyers seeking localized service networks.
- Validation burden:FDA juice HACCP and EFSA novel food assessments require 18-36 month timelines, freezing capital deployment until regulatory clearance is secured.
Strategic Opportunities
- India FSSAI standards development:Emerging regulatory clarity for high-pressure treated products under food safety modernization is opening import substitution opportunities for domestic equipment assembly.
- Pulsed electric field plus ultrasound:Convergent non-thermal technologies are enabling processing of viscous semi-solids previously incompatible with single-mode systems.
- Direct-to-retail channel:E-commerce fresh meal platforms are contracting dedicated HPP capacity, bypassing traditional co-packer networks and capturing margin previously lost to intermediaries.
Industry Challenges
- Process engineering talent:Scarcity of specialists combining food microbiology with high-pressure hydraulics is delaying commissioning timelines and inflating service contract premiums.
- Legacy thermal line integration:Retrofitting cold-pasteurization into existing pasteurization workflows requires custom material handling and controls architecture, multiplying project complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Thermal Food Processing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High Pressure Processing, Pulsed Electric Fields, Microwave, Ultrasound Application: Juices, Sauces, Ready-to-Eat Meals, Dairy Products End User: Food Manufacturers, Retailers, Restaurants, Catering Services Packaging Type: Flexible Packaging, Rigid Packaging, Vacuum Packaging, Modified Atmosphere Packaging |
| Companies Covered | Hiperbaric, JBT Corporation, Tetra Pak, Thyssenkrupp, Nordion, Dukane, Symbios Technologies, Elea Technology, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Thermal Food Processing Market Strategic Shifts
Equipment architecture is fragmenting into modular subsystems, enabling processors to scale capacity incrementally rather than committing to monolithic turnkey installations. This shift is compressing payback periods and expanding addressable buyer segments.
Modular high-pressure processing skid systems are modularizing from 55-liter to 320-liter vessel configurations, allowing protein processors to match capacity to seasonal demand curves without stranded capital. Mid-size co-packers in the United States are adopting this architecture to serve multiple brand accounts with staggered production schedules. The approach is compressing minimum efficient scale thresholds and enabling regional processors to compete with centralized facilities.
EFSA's updated guidance on novel food equivalence assessments is streamlining authorization for pulsed electric field variants of established product categories, reducing documentation requirements for processors demonstrating substantial equivalence to thermally treated references. Juice and smoothie manufacturers in the Netherlands and Spain are leveraging this pathway to accelerate product launches. The regulatory efficiency is redirecting R&D investment toward formulation innovation rather than compliance documentation.
Foodservice procurement teams are consolidating supplier relationships around integrated preservation-plus-packaging contracts, unbundling legacy equipment-lease arrangements in favor of per-unit processing fees. Casino and airline catering operators in Nevada and Singapore are piloting this model with HPP service providers. The shift transfers capital risk to equipment owners while locking in volume commitments from high-throughput accounts.
Non-Thermal Food Processing Market Segmentation
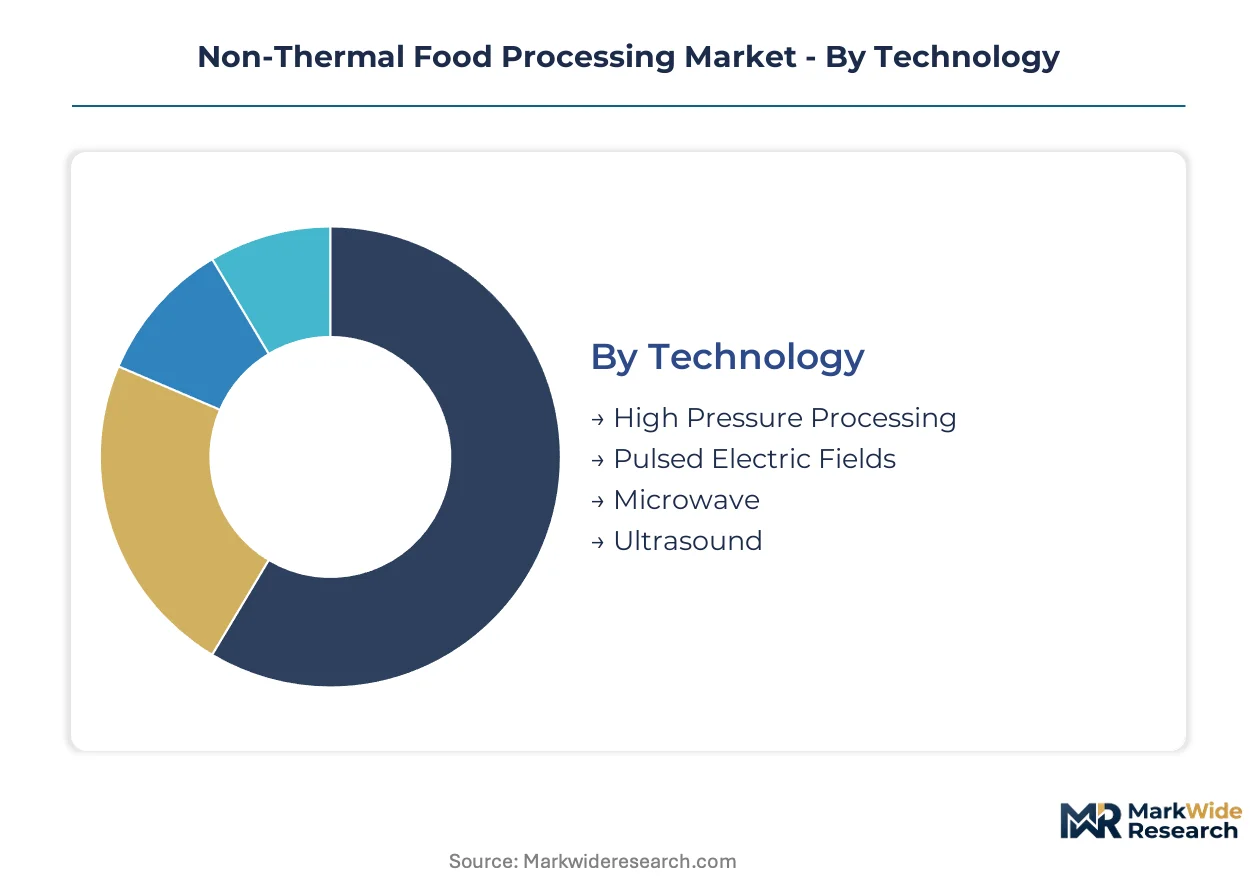
Non-thermal food processing segments diverge sharply in regulatory validation burden and capital intensity. Technology choice determines FDA petition pathways, while application segments dictate EFSA novel food documentation requirements.
Technology:
High-pressure systems require ASME pressure vessel certification and FDA juice HACCP validation, while pulsed electric field equipment faces lighter CE marking obligations in Europe.
- High Pressure Processing:Deploys isostatic pressure between 400-600 MPa at ambient temperature to inactivate vegetative pathogens. Protein processors in Germany anchor demand as per-unit costs decline with larger vessel formats.
- Pulsed Electric Fields:Applies 10-80 kV/cm electric pulses for microseconds to disrupt microbial membranes. Juice manufacturers in the Netherlands are scaling adoption as EFSA equivalence assessments streamline authorization timelines.
- Microwave:Non-ionizing radiation heats water molecules selectively for pasteurization.
- Ultrasound:Acoustic cavitation generates localized heat and mechanical stress for microbial reduction.
High Pressure Processing sits at the top of the volume ranking, with Pulsed Electric Fields climbing the fastest.
Application:
Cost tier separation runs from premium-positioned juices to commodity dairy, with margin structure determining technology adoption feasibility.
- Juices:Cold-pressed and HPP-treated variants command shelf price premiums of 40-60% over thermally pasteurized alternatives. Clean-label positioning drives procurement at central commissaries serving airline and casino catering.
- Sauces:High-acid formulations suit pulsed electric field treatment, preserving volatile aromatic compounds lost in thermal processing. Spanish manufacturers are retrofitting lines to supply private-label retail contracts.
- Ready-to-Eat Meals:Refrigerated prepared foods benefit from extended shelf life without nutrient degradation.
- Dairy Products:Yogurt and fresh cheese applications remain limited by protein denaturation thresholds.
Juices capture the largest installed base, with Ready-to-Eat Meals expanding most quickly.
End User:
Customer type determines contract structure, from capital purchase by food manufacturers to per-unit processing fees at retailer-operated facilities.
- Food Manufacturers:Integrated processors deploy captive HPP capacity for guacamole and protein lines, amortizing equipment across high-throughput SKUs.
- Retailers:Supermarket chains in Singapore are contracting dedicated toll processing capacity, bypassing co-packer intermediaries to capture margin.
- Restaurants:Limited adoption due to space constraints and batch size requirements.
- Catering Services:Casino and airline operators pilot integrated preservation-plus-packaging contracts.
Food Manufacturers dominate capital deployment, with Retailers gaining share fastest.
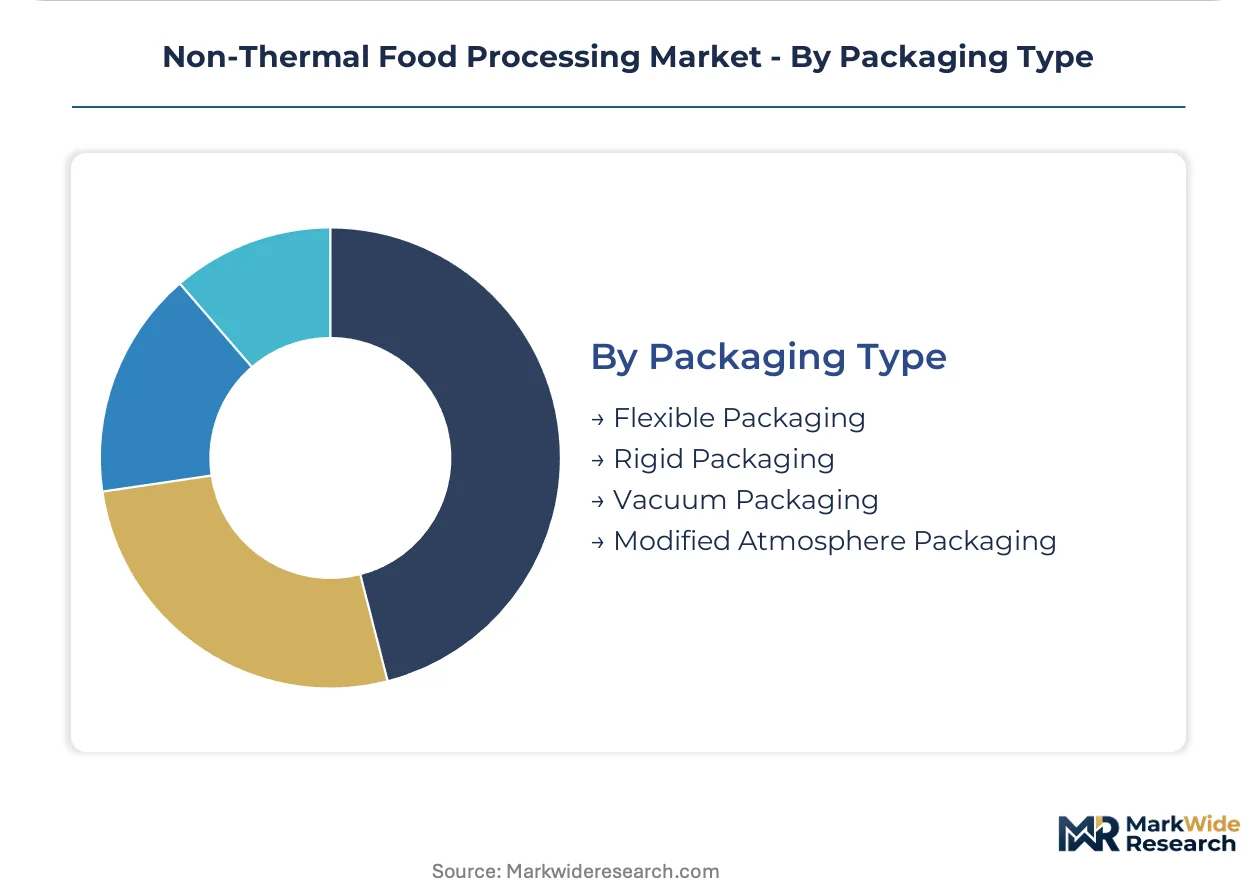
Packaging Type:
Supply concentration in flexible film extrusion shapes equipment compatibility requirements across technology platforms.
- Flexible Packaging:Vacuum-sealed pouches dominate HPP applications, withstanding isostatic pressure without seal failure. Multilayer barrier structures preserve oxygen-sensitive nutrients through distribution.
- Vacuum Packaging:Essential for high-pressure processing, removing headspace to prevent package deformation.
- Rigid Packaging:Bottles and trays suit microwave and ultrasound applications with lower pressure exposure.
- Modified Atmosphere Packaging:Gas-flushed headspace extends shelf life for refrigerated distribution.
Flexible Packaging leads volume, with Vacuum Packaging tied to HPP expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting equipment procurement toward jurisdictions where FDA juice HACCP validation and EFSA novel food assessments create divergent cost-of-compliance timelines. German and Dutch processors exploit EFSA equivalence pathways to compress authorization cycles, while US manufacturers absorb longer FDA petition timelines to access premium retail channels.
Germany
Protein processors in Quakenbrück and Baden-Württemberg anchor European HPP demand as per-unit costs decline with larger vessel formats. The EU Novel Food Framework enables streamlined EFSA assessments for pulsed electric field variants, reducing documentation burdens. Elea Technology and Hiperbaric concentrate pilot installations in Lower Saxony, validating cold-pasteurization lines for export-ready meat products.
United States
Mid-size co-packers in California and Texas adopt modular HPP skid systems to serve multiple brand accounts with staggered production schedules. FDA juice HACCP regulations mandate 18-36 month validation timelines, freezing capital deployment until clearance is secured. Casino and airline catering operators in Nevada pilot integrated preservation-plus-packaging contracts, transferring capital risk to equipment owners.
Netherlands
Juice and smoothie manufacturers in Rotterdam and Eindhoven leverage EFSA equivalence assessments to accelerate product launches for clean-label shelf-stable beverages. CE marking obligations for pulsed electric field equipment remain lighter than FDA counterparts. Dutch processors redirect R&D investment toward formulation innovation rather than compliance documentation.
India
FSSAI standards development for high-pressure treated products under food safety modernization is opening import substitution opportunities for domestic equipment assembly. Protein processors in Maharashtra and Gujarat retrofit cold-pasteurization lines to replace thermal tunnels. Central commissaries in Delhi-NCR contract dedicated toll processing capacity to capture margin previously lost to intermediaries.
Spain
High-acid sauce manufacturers in Barcelona and Valencia retrofit pulsed electric field lines to supply private-label retail contracts. Spanish processors exploit EFSA novel food pathways to preserve volatile aromatic compounds lost in thermal processing. Andalusian juice producers scale adoption as equipment costs decline and throughput rises.
Non-Thermal Food Processing Market Competitive Environment
Capacity expansion dominates the current landscape as equipment manufacturers scale modular architectures to compress payback periods and expand addressable buyer segments. The vendor base concentrates around turnkey system providers and component specialists, creating a bifurcated structure where capital intensity raises barriers for new entrants. Three strategic archetypes emerge: integrated line solution providers, pulsed electric field specialists, and high-pressure processing equipment fabricators. Competitive moves center on geographic licensing agreements and backward integration into pressure vessel manufacturing to offset stainless steel cost volatility.
Among European equipment fabricators, Hiperbaric and Elea Technology exemplify the technology-specialist archetype, occupying distinct tiers within the non-thermal processing ecosystem. Hiperbaric anchors demand from premium protein processors through its installed base of high-pressure systems. Elea Technology represents the pulsed electric field tier, focusing on solid and semi-solid food matrices. JBT Corporation competes as an integrated line solution provider, extending from raw intake to sealed packaging. These three companies illustrate the competitive segmentation between specialized technology vendors and full-system integrators.
| Leading Market Players |
|---|
| Hiperbaric |
| JBT Corporation |
| Tetra Pak |
| Thyssenkrupp |
| Nordion |
| Dukane |
| Symbios Technologies |
| Elea Technology |
| Bühler Group |
| Others |
Value Chain & Pricing Dynamics
Equipment certification tiers separate turnkey system providers from component specialists, with ASME-certified pressure vessel fabricators commanding 40-60% price premiums over CE-marked alternatives while concentrating procurement relationships around German and Spanish engineering clusters. This bifurcation channels margin toward validated fabricators and strands mid-tier buyers in extended quote-to-delivery cycles.
Pricing Analysis
Retailer markup layers inflate delivered equipment costs by 15-25% for North American buyers sourcing European systems, compressing vendor margins at the manufacturing tier. Pricing stratifies across premium turnkey installations, standard modular skids, and economy component packages, with stainless steel input volatility driving cost compression in mid-tier configurations. Food manufacturers exhibit lowest price sensitivity due to amortization across high-throughput SKUs, while regional co-packers face acute margin pressure from extended validation timelines.
Supply Chain Analysis
High-grade stainless steel supply rests on German, Austrian, and Japanese specialty metal producers, with pressure vessel-grade alloys drawing from concentrated European forging capacity. Critical dependencies include nickel-chromium-molybdenum alloys, precision hydraulic seals, and high-voltage pulse generators. Single-source vulnerability concentrates in ASME-certified forging shops, with distribution running through equipment OEMs and regional service integrators rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EFSA novel food equivalence assessments and FDA juice HACCP pathways accelerating capital deployment timelines for validated equipment configurations.
For Market Incumbents: Cement installed-base advantages through captive aftermarket service networks and backward integration into pressure vessel manufacturing, offsetting stainless steel cost volatility. Prioritize certification maintenance for FDA and EFSA pathways to defend against modular skid entrants. Capacity expansion in India captures FSSAI standards development tailwinds before import substitution matures. For New Entrants and Emerging Players: FSSAI standards development in India opens a window for domestic equipment assembly partnerships, bypassing German supply concentration. Target mid-size co-packers in the United States with lease-to-own modular architectures, exploiting stranded capital sensitivity among staggered-production operators. Lead with per-unit processing fee models to transfer validation risk from buyers. For Investors and Strategic Acquirers: Asymmetric upside sits with pulsed electric field specialists possessing EFSA equivalence assessment track records and solid-matrix processing IP. Long-term viability centers on regulatory validation velocity rather than pure manufacturing scale. Watch EFSA-FDA harmonization progress as the inflection signal for cross-border technology licensing multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Vessel Manufacturing | Captive supply of ASME-certified components insulates Hiperbaric and Elea Technology from nickel alloy price swings. |
| Modular Skid System Launch | 55-liter to 320-liter configurations enable California co-packers to match capacity to seasonal protein demand curves. |
| EFSA Novel Food Equivalence Assessment | Streamlined authorization redirects Dutch juice manufacturers toward formulation R&D rather than compliance documentation. |
| Per-Unit Processing Fee Contracts | Nevada casino operators transfer capital risk to equipment owners while locking in volume commitments. |
| India FSSAI Standards Alignment | Maharashtra protein processors capture import substitution opportunities as domestic assembly capacity scales. |
Study Parameters
Coverage spans Germany, the United States, the Netherlands, India, and Spain, with primary inputs from each market cluster triangulated against secondary validation. Interviews with equipment engineering directors, food safety compliance officers at central commissaries, procurement leads at protein processors, and aftermarket service managers informed demand-side assumptions. Secondary sources include FDA juice HACCP guidance documents, EFSA novel food assessment registers, FSSAI draft standards notifications, and customs records for pressure vessel imports. Bottom-up equipment shipment data reconciled with top-down food manufacturer capex surveys.
Rate-of-change decomposition isolates technology adoption curves, regulatory authorization timelines, and input cost trajectories across the projection horizon. Segmentation dimensions span technology platform, application matrix, end-user archetype, and regional regulatory cluster. CAGRs derive from equipment shipment velocity indexed to processed food volume growth and validation pipeline clearance rates. Industry-specific inputs include stainless steel price indices and EFSA equivalence assessment throughput.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged FDA petition delays or abrupt FSSAI standard revisions. Assumptions reflect current regulatory trajectories and equipment cost curves. A small set of named triggers warrants ongoing watch: EFSA-FDA harmonization protocols, India domestic content requirements, and nickel alloy supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Coconut Crushers Market