
 Chewing Gum Machine Market | 2026-2036
Chewing Gum Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Chewing Gum Machine Market Outlook
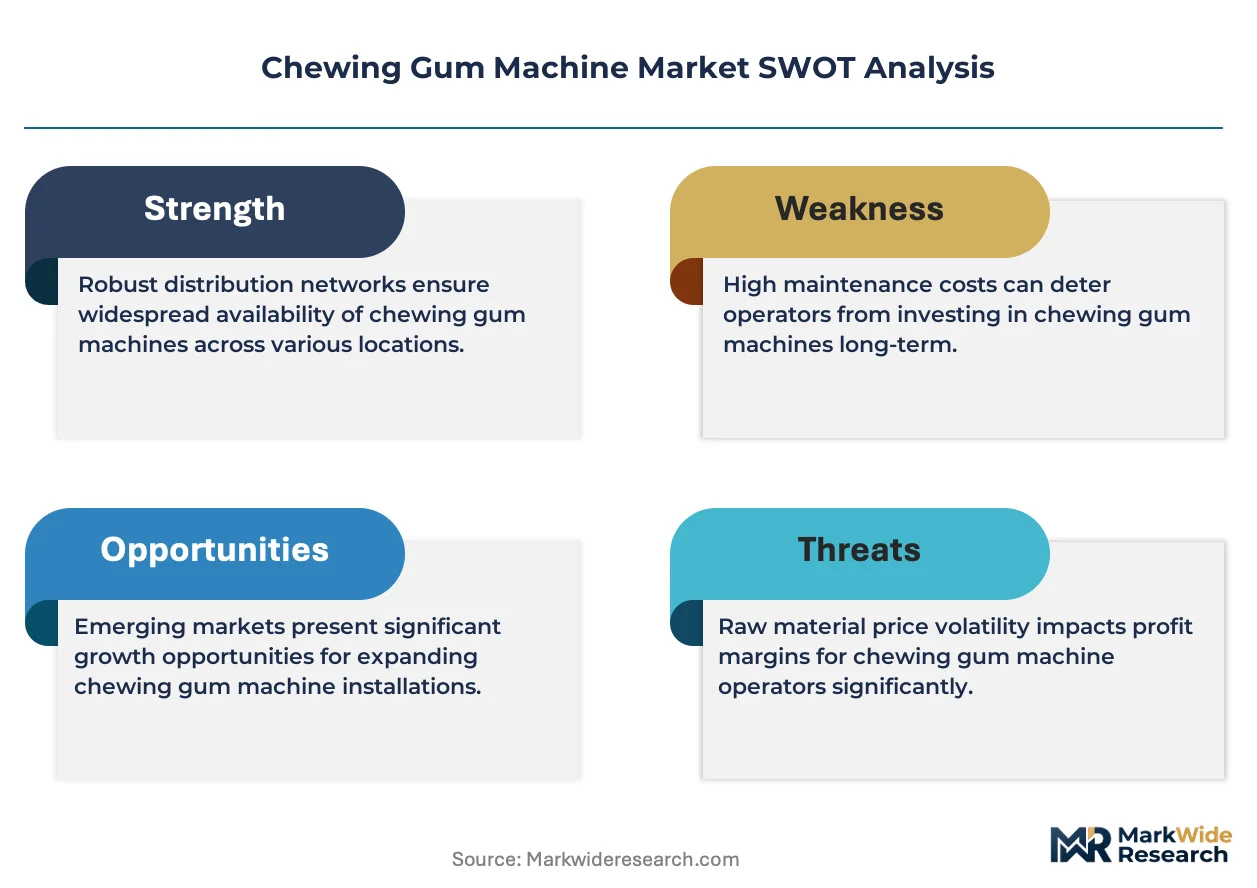
China's Zhejiang and Jiangsu provinces is tilting the competitive map as domestic metalworking and electronics assembly clusters expand capacity for automated confectionery equipment. Latini-Hohberger Dhimantec leverages integrated casting and machining operations to sustain cost leadership in mechanical dispenser components. Tishma Technologies anchors its position through precision servo-motor integration for electronic vending platforms. Ford Gum competes on brand heritage and captive placement networks across North American retail channels.
A chewing gum machine is an electromechanical or purely mechanical device designed to store, meter, and dispense individual units of chewing gum or bubble gum upon activation by a consumer, typically incorporating a coin or cashless payment mechanism, a product storage hopper, and a rotating spiral or auger delivery system with dispensing accuracy measured in single-unit increments. These machines serve commercial operators seeking low-labor revenue streams in high-foot-traffic environments. Vending machines with electronic payment modules command premium placement in shopping malls where transaction speed determines throughput. IoT-enabled units represent the fastest-expanding technology segment as remote inventory monitoring reduces service-cycle costs for distributed fleets. Mechanical bulk dispensers remain the mature workhorse segment in schools and budget retail settings where capital constraints limit technology investment.
FDA guidelines on confectionery labeling and the Consumer Product Safety Commission's small-parts standards shape product design requirements for machines accessible to children. Municipal vending ordinances in Chicago, New York, and Los Angeles regulate placement density and nutritional disclosure, creating compliance complexity for national operators. The EU's RoHS and REACH directives constrain material selection for electronics-heavy models exported to European retail chains. Stakeholders must monitor evolving cashless payment certification standards and decide whether to internalize IoT development or partner with specialized telemetry providers.
Market Dynamics
IoT-enabled telemetry is compressing service-cycle economics for distributed vending fleets, forcing operators to choose between internalizing connected-device development or ceding data ownership to specialized telemetry providers. This technology shift is redrawing competitive boundaries between mechanical-component specialists and electronics-integrated platform vendors.
Growth Catalysts
- Entertainment venue automation:Movie theaters and family fun centers in the United States are expanding automated confectionery deployment to reduce labor costs and capture impulse purchases during dwell-time intervals.
- Cashless payment certification:Municipal vending ordinances in Chicago, New York, and Los Angeles are accelerating certification requirements for electronic payment modules, creating replacement demand for legacy coin-only units.
- Eastern China manufacturing scale:Zhejiang and Jiangsu provinces have developed integrated metalworking and electronics assembly clusters that OEMs leverage for cost-efficient export production.
Market Restraints
- Stainless steel input volatility:Hopper and chassis fabrication depends on commodity-grade stainless steel pricing, exposing manufacturers to raw-material cost swings without pass-through mechanisms in fixed-price municipal contracts.
- Electronics supply concentration:Servo-motor controllers and payment-terminal chipsets concentrate among a limited set of East Asian semiconductor fabricators, creating single-source vulnerability for electronic vending platforms.
- REACH substance restrictions:The EU's REACH directives constrain polymer selection for food-contact components and cable insulation, forcing design revisions for machines exported to European retail chains.
Strategic Opportunities
- Underpenetrated Indian retail:Organized retail expansion in tier-2 Indian cities offers first-mover positioning for automated confectionery before local vending infrastructure matures.
- Telemetry-as-a-service models:Fleet operators can monetize consumption-pattern data by partnering with confectionery brands seeking real-time demand signals for promotional timing.
- Green procurement mandates:The EU Green Deal's public-procurement criteria favor energy-efficient vending equipment, creating preference premiums for LED-lit, low-standby-power designs in European municipal bids.
Industry Challenges
- Embedded systems talent scarcity:Mechanical heritage manufacturers face recruitment friction for firmware engineers capable of integrating payment security protocols with legacy auger-drive architectures.
- Multi-jurisdiction compliance timelines:Operators serving national retail chains must sequence FDA confectionery-labeling guidelines, CPSC small-parts standards, and municipal nutrition-disclosure rules across divergent implementation calendars.
- Legacy fleet retrofit complexity:Coin-mechanical units in schools and budget retail settings resist cost-effective upgrade paths to cashless or IoT-enabled configurations, fragmenting service infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chewing Gum Machine Market |
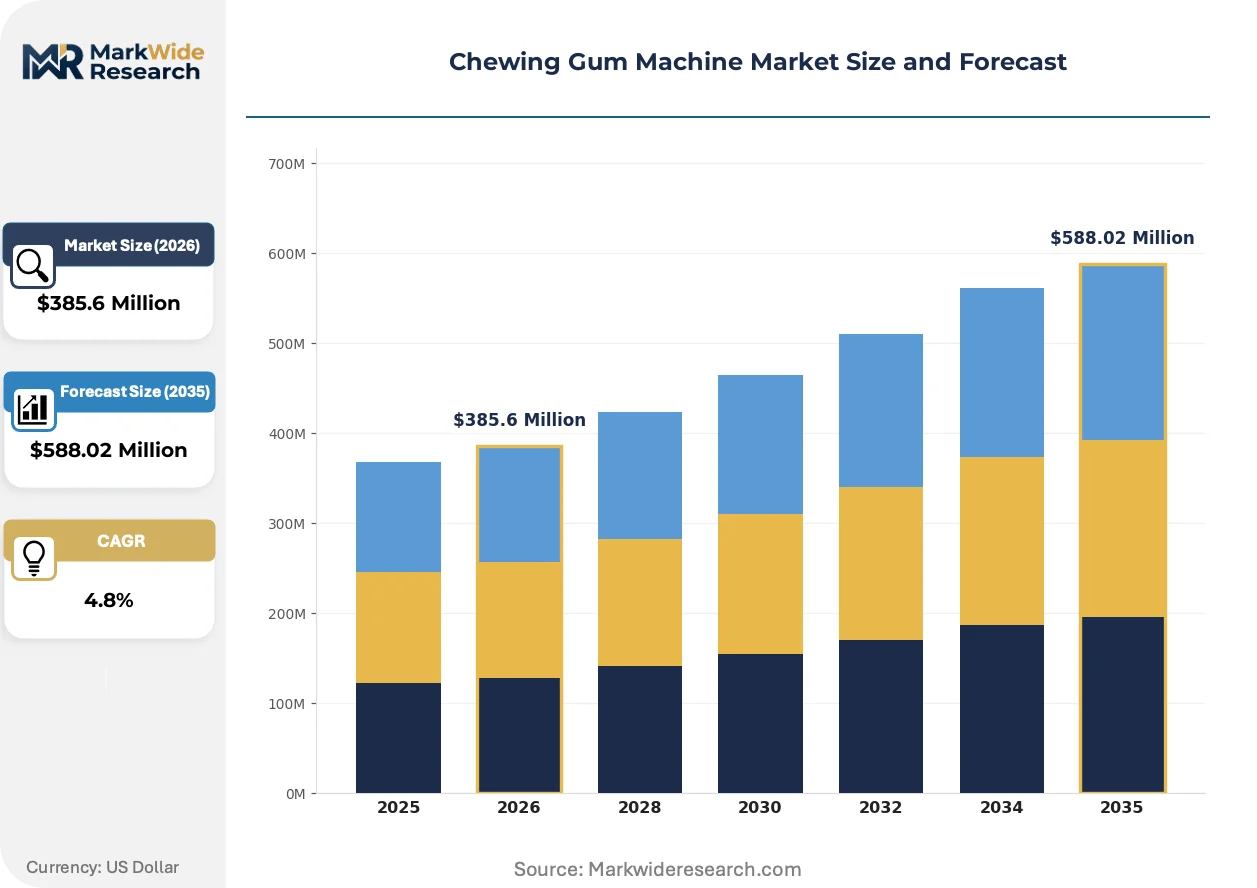
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Dispenser, Vending Machine, Tabletop Unit, Customized Unit Technology: Mechanical, Electronic, Hybrid, IoT-Enabled End User: Retails Stores, Shopping Malls, Movie Theaters, Schools Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Latini USA, Ford Gum, Tishma Technologies, American Gumball Company, Accio, Nantong Wealth Machinery, Latini-Hohberger Dhimantec, Dubble Bubble, TGMachine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chewing Gum Machine Market Strategic Shifts
Connected vending infrastructure is rewriting operator economics by collapsing inventory-monitoring labor costs and enabling dynamic pricing algorithms tied to foot-traffic sensors. This shift favors vendors with software-development capabilities over pure hardware fabricators.
Near-field communication and QR-code payment modules are digitizing transaction workflows in shopping-mall deployments where throughput speed determines revenue per square meter. Operators in high-rent locations are adopting these modules fastest, compressing the payback period for electronics-heavy capital investments against mechanical alternatives. The technology is digitizing competitive advantage toward data-analytics capabilities and away from casting and machining scale.
The EU's RoHS directive continues tightening allowable concentrations of lead and cadmium in electronics assemblies, forcing redesigns of motor-driver printed-circuit boards and power-supply components. Manufacturers serving European retail chains must maintain dual bill-of-materials configurations or absorb compliance-testing costs for unified designs. Electronic-heavy platforms with integrated payment terminals face the steepest certification burden and timeline risk.
Buying committees at cinema chains and family entertainment centers are unbundling equipment procurement from service contracts, treating vending machines as capital assets rather than bundled revenue-share arrangements. This compresses vendor margins on installation and maintenance while shifting lifecycle value toward spare-parts availability and remote diagnostics responsiveness. The pattern is most visible in North American multiplex operators seeking balance-sheet clarity on depreciation schedules.
Chewing Gum Machine Market Segmentation
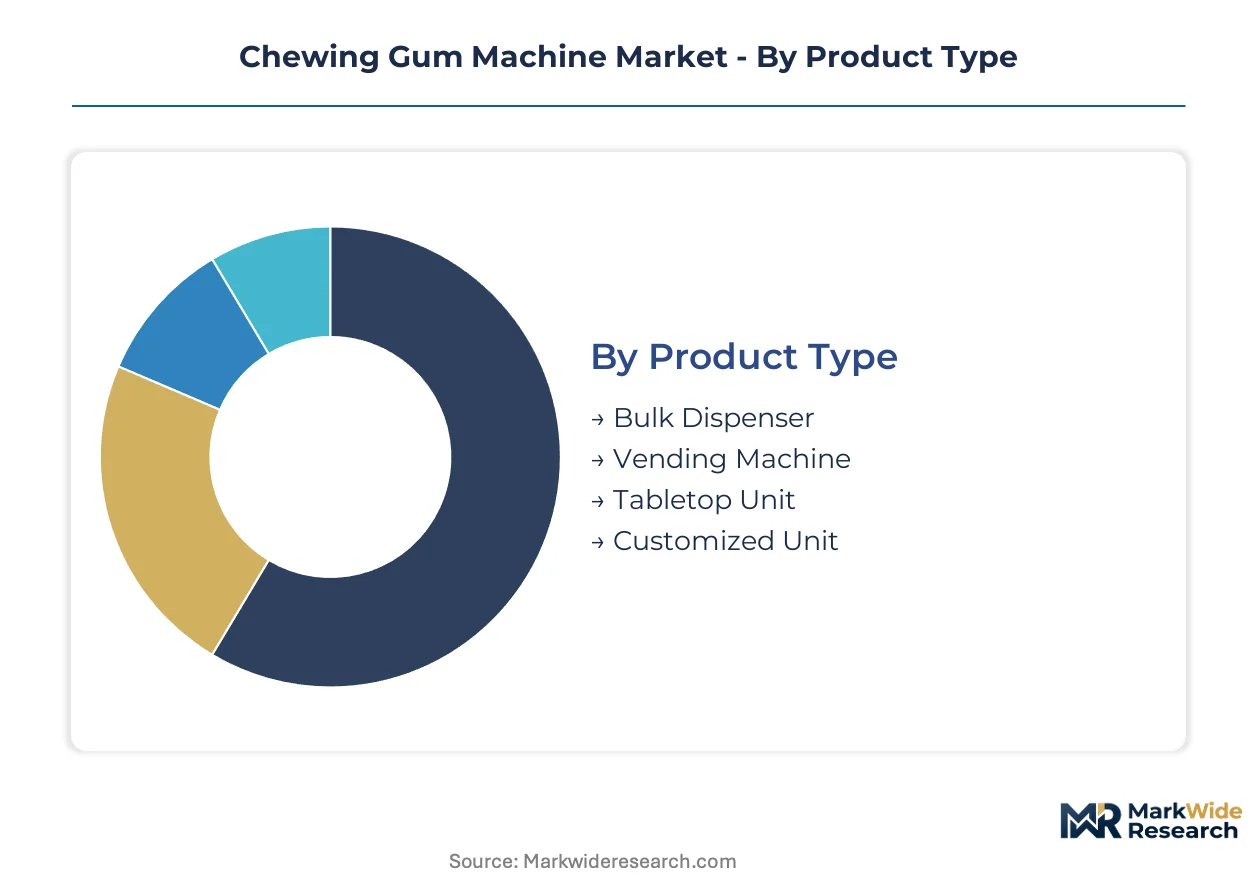
Segmentation in the chewing gum machine market reveals how deployment context shapes equipment specifications. Payment integration requirements, foot-traffic density, and regulatory exposure vary sharply across use cases, fragmenting demand into distinct technical tiers.
Product Type:
Equipment configurations span from low-capacity countertop units to high-volume floor-standing systems, with cost-per-unit and service intensity defining the selection logic for operators.
- Bulk Dispenser:Mechanical gravity-fed hoppers with rotating dispensing wheels handle high-volume, low-margin placements in schools and budget retail. Stainless steel construction resists vandalism in unsupervised environments.
- Vending Machine:Freestanding electromechanical platforms integrate coin mechanisms or cashless readers for shopping malls and transit hubs. These units command the highest capital investment but generate superior revenue per square meter in premium locations.
- Tabletop Unit:Compact battery or AC-powered dispensers suit limited-space concessions and temporary event setups. Operators favor these for seasonal deployments where permanent installation is uneconomical.
- Customized Unit:Branded exterior cladding and proprietary dispensing mechanics serve franchise chains and licensed property tie-ins. Design revisions extend procurement cycles but lock in multi-year placement contracts.
Established volume favors bulk dispensers in institutional channels; emerging adoption favors customized units in experience-driven retail.
Technology:
Technology tiers reflect a capital-labor tradeoff curve, with sophistication levels mapping directly to operator fleet scale and service infrastructure.
- Mechanical:Purely mechanical coin acceptance and auger drives minimize power consumption and field-service complexity. These systems dominate rural and budget-constrained deployments where electronics reliability is uncertain.
- Electronic:Microprocessor-controlled motors and multi-coin validators enable precise portion control and expanded price-point flexibility. Shopping mall operators in the United States specify these for throughput optimization.
- Hybrid:Mechanical dispensing married to basic electronic payment modules bridges legacy infrastructure with cashless mandates. Municipal vending contracts in Chicago and New York accelerate replacement demand for this intermediate tier.
- IoT-Enabled:Cellular-connected inventory sensors and remote diagnostic capabilities compress service-cycle costs for distributed fleets. These units are expanding most quickly in cinema chains seeking real-time consumption analytics.
Mechanical systems anchor installed base economics; IoT-enabled platforms are climbing the fastest as telemetry-as-a-service models mature.
End User:
End-use concentration determines equipment durability specifications, payment modality requirements, and compliance exposure to child-safety regulations.
- Retail Stores:Checkout-lane impulse placements favor compact, low-maintenance mechanical units with minimal power draw. C-store chains prioritize reliability over telemetry integration.
- Shopping Malls:High-rent common areas demand electronic payment speed and aesthetic customization to match landlord design standards. Foot-traffic sensors increasingly drive dynamic pricing algorithms.
- Movie Theaters:Concession-integrated placements emphasize throughput during intermission rushes. Multiplex operators unbundle equipment ownership from service contracts, treating machines as depreciable capital assets.
- Schools:Budget procurement and vandalism exposure sustain demand for mechanical bulk dispensers with minimal electronics. FDA confectionery-labeling guidelines and CPSC small-parts standards constrain product selection in these placements.
Schools and retail stores sustain mechanical segment volume; movie theaters and shopping malls drive electronics upgrade cycles.
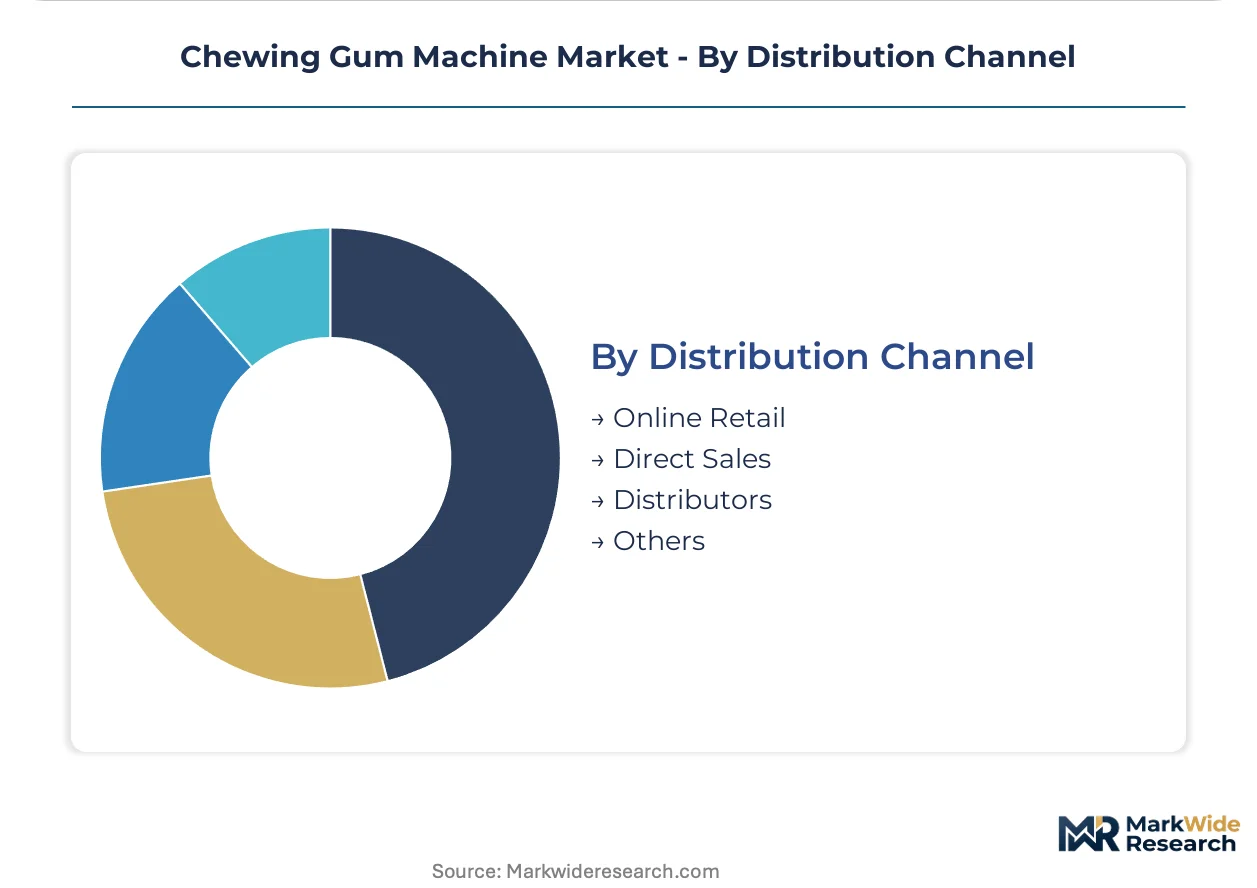
Distribution Channel:
Channel structure reflects customer scale and technical support requirements, with direct relationships dominating fleet operators and intermediaries serving fragmented accounts.
- Online Retail:E-commerce platforms serve small operators and replacement-part procurement with standardized SKUs and limited technical support. Transaction friction is lowest for tabletop and mechanical bulk units.
- Direct Sales:Manufacturer field teams handle specification, installation, and service contracting for cinema chains and national retail operators. These relationships capture lifecycle value through spare-parts availability and remote diagnostics responsiveness.
- Distributors:Regional vending equipment wholesalers maintain local inventory and service networks for independent operators. Geographic coverage gaps persist in tier-2 Indian cities where organized retail infrastructure is nascent.
- Others:Revenue-share arrangements and equipment-leasing programs serve capital-constrained entrants, though cinema chains are shifting toward outright purchase for balance-sheet clarity.
Direct sales concentrate value in national accounts; distributor networks retain relevance in geographically fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA confectionery-labeling guidelines and CPSC small-parts standards anchor United States demand, while municipal vending ordinances in Chicago, New York, and Los Angeles create compliance complexity for national operators. Zhejiang and Jiangsu provinces in China concentrate OEM manufacturing for export brands. The EU's RoHS and REACH directives constrain material selection for electronics-heavy models bound for European retail chains.
United States
Entertainment venues including movie theaters and family fun centers are expanding automated confectionery deployment to capture impulse purchases during dwell-time intervals. Municipal vending ordinances in Chicago, New York, and Los Angeles regulate placement density and nutritional disclosure, accelerating replacement demand for legacy coin-only units. Ford Gum leverages brand heritage and captive placement networks across North American retail channels.
China
Zhejiang and Jiangsu provinces have developed integrated metalworking and electronics assembly clusters that OEMs leverage for cost-efficient export production. The country's dual carbon goals and MIIT efficiency standards shape procurement criteria for domestic vending infrastructure. Nantong Wealth Machinery anchors production capacity in these eastern manufacturing provinces.
Germany
Precision engineering traditions sustain demand for high-durability mechanical dispenser components in institutional and retail channels. REACH substance restrictions constrain polymer selection for food-contact components and cable insulation, forcing design revisions for machines exported from German retail chains. Bavaria and Baden-Württemberg host machining specialists serving pan-European vending equipment supply chains.
India
Organized retail expansion in tier-2 cities offers first-mover positioning for automated confectionery before local vending infrastructure matures. FSSAI labeling requirements and BIS safety standards create compliance entry barriers for imported equipment. Maharashtra and Gujarat concentrate early deployment trials among domestic retail chains testing concession automation.
United Kingdom
Shopping mall operators specify electronic payment speed and aesthetic customization to match landlord design standards in high-rent common areas. The EU Green Deal's public-procurement criteria favor energy-efficient vending equipment, creating preference premiums for LED-lit designs in municipal bids. London and the Southeast concentrate premium placement demand among cinema chains and transit hub concessions.
Chewing Gum Machine Market Competitive Environment
Capability concentration sits with electromechanical integration specialists; scale advantage sits with metalworking and casting operations serving global OEM demand. The vendor base spans three tiers: heritage confectionery brands with captive placement networks, precision machining specialists with integrated foundry operations, and electronics-integrated platform vendors with servo-motor expertise. Strategic moves concentrate on telemetry-as-a-service partnerships and dual bill-of-materials configurations for REACH-compliant European export.
Among heritage-brand operators, Ford Gum and Dubble Bubble occupy positions anchored in North American retail channel relationships and licensed property tie-ins. Latini-Hohberger Dhimantec represents the precision-machining archetype with integrated casting operations sustaining cost leadership in mechanical dispenser components. Tishma Technologies exemplifies the electronics-integrated tier through precision servo-motor integration for electronic vending platforms. Latini USA and American Gumball Company sit within the mid-scale fabrication segment serving regional operators and replacement-part demand.
| Leading Market Players |
|---|
| Latini USA |
| Ford Gum |
| Tishma Technologies |
| American Gumball Company |
| Accio |
| Nantong Wealth Machinery |
| Latini-Hohberger Dhimantec |
| Dubble Bubble |
| TGMachine |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu provinces in eastern China concentrate stainless steel fabrication and electronics assembly capacity, granting OEMs cost leverage that compresses margins for mechanical dispenser producers elsewhere while enabling aggressive export pricing for IoT-enabled platforms.
Pricing Analysis
Price spreads between electronic vending platforms and mechanical bulk dispensers widen as servo-motor controllers and payment-terminal chipsets concentrate among East Asian semiconductor fabricators. Pricing stratifies across premium IoT-enabled, standard electronic, and economy mechanical tiers, with certification grade for FDA confectionery-labeling and CPSC small-parts standards driving differentiation. Cost compression in the mechanical segment intensifies because fixed-price municipal contracts lack pass-through mechanisms for stainless steel volatility. Schools and budget retail operators exhibit highest price sensitivity; cinema chains and shopping mall landlords show lowest sensitivity due to throughput-speed requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronics-heavy vending platforms. Manufacturing concentrates in China, Germany, and the United States, with precision machining anchored in Bavaria and Baden-Württemberg serving pan-European demand. Raw material dependencies center on commodity-grade stainless steel for hopper fabrication, servo-motor controllers for electronic dispensing, and polymer compounds constrained by REACH substance restrictions. Single-source vulnerability for payment-terminal chipsets creates procurement fragility. Distribution runs through direct sales teams for national cinema chains, regional distributors for independent operators, and online retail for replacement parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chewing gum machine demand sits in early-cycle expansion as entertainment venue automation and cashless payment mandates drive replacement waves across North American and European installed bases.
For Market Incumbents: Harden telemetry-as-a-service capabilities to defend against specialized IoT providers capturing fleet data ownership. Deepen backward integration into stainless steel casting operations to buffer commodity volatility that erodes fixed-contract margins. Prioritize dual bill-of-materials configurations for REACH-compliant European export to preempt regulatory redesign costs. For New Entrants and Emerging Players: Tier-2 Indian cities represent the most penetrable entry point before organized retail vending infrastructure matures. Municipal vending contracts in Chicago, New York, and Los Angeles offer replacement demand acceleration as cashless certification deadlines approach. Partner with established telemetry providers rather than internalizing firmware development to compress time-to-market. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mechanical heritage manufacturers face embedded systems talent scarcity that electronics-integrated platform vendors can exploit. Target precision-machining specialists with integrated foundry operations serving global OEM demand. Watch cinema chain unbundling of equipment procurement from service contracts as the signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-as-a-Service Partnership | Remote inventory monitoring reduces service-cycle costs for distributed cinema and mall fleets. |
| Dual Bill-of-Materials Configuration | REACH-compliant designs secure European retail chain procurement against regulatory exclusion. |
| Backward Integration into Casting | Integrated foundry operations buffer stainless steel volatility eroding fixed municipal contract margins. |
| Cashless Payment Module Certification | Municipal ordinances in Chicago, New York, and Los Angeles accelerate replacement demand cycles. |
| Tier-2 India Geographic Expansion | Organized retail growth in Maharashtra and Gujarat offers first-mover positioning before local vending matures. |
Study Parameters
A spread of perspectives from vending machine operators, cinema chain procurement directors, municipal vending contract administrators, and confectionery brand fleet managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings of disclosed equipment vendors, and municipal ordinance databases. Bottom-up unit economics for mechanical, electronic, and IoT-enabled platforms were triangulated against top-down spending estimates from entertainment venue capital expenditure disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and distribution channel structure. CAGRs were derived from installed base replacement cycles, entertainment venue expansion pipelines, and cashless payment mandate timelines. Industry-specific forecast inputs incorporated stainless steel price trajectories and semiconductor lead time assumptions for servo-motor controller procurement.
Practitioners should monitor REACH substance restriction amendments, municipal nutrition disclosure rule expansions, and East Asian semiconductor supply disruptions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Deaeration Machine Market