
 Ice Cream Freezer Market | 2026-2036
Ice Cream Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Freezer Market Foresight
Multi-sourced component procurement is repositioning how freezer manufacturers manage compressor and insulation supply chains. Hussmann Corporation leverages captive distribution networks to sustain its North American service footprint. Electrolux Professional anchors European commercial kitchen specifications through deep refrigeration heritage. Haier Group dominates Asian volume tiers with manufacturing scale across multiple capacity bands.
An ice cream freezer is a thermally insulated cabinet engineered to maintain temperatures between minus 18 degrees Celsius and minus 25 degrees Celsius, utilizing vapor-compression cycles with hydrocarbon or HFO refrigerants to preserve frozen dessert texture and prevent crystallization. Horizontal freezers lead supermarket layouts due to wide-opening access and bulk-display economics, while blast freezers represent the fastest-growing product type as artisanal producers adopt rapid-churn protocols to control ice crystal formation. Dynamic cooling technology commands premium positioning in restaurant chains where uniform temperature distribution protects gelato consistency during service hours.
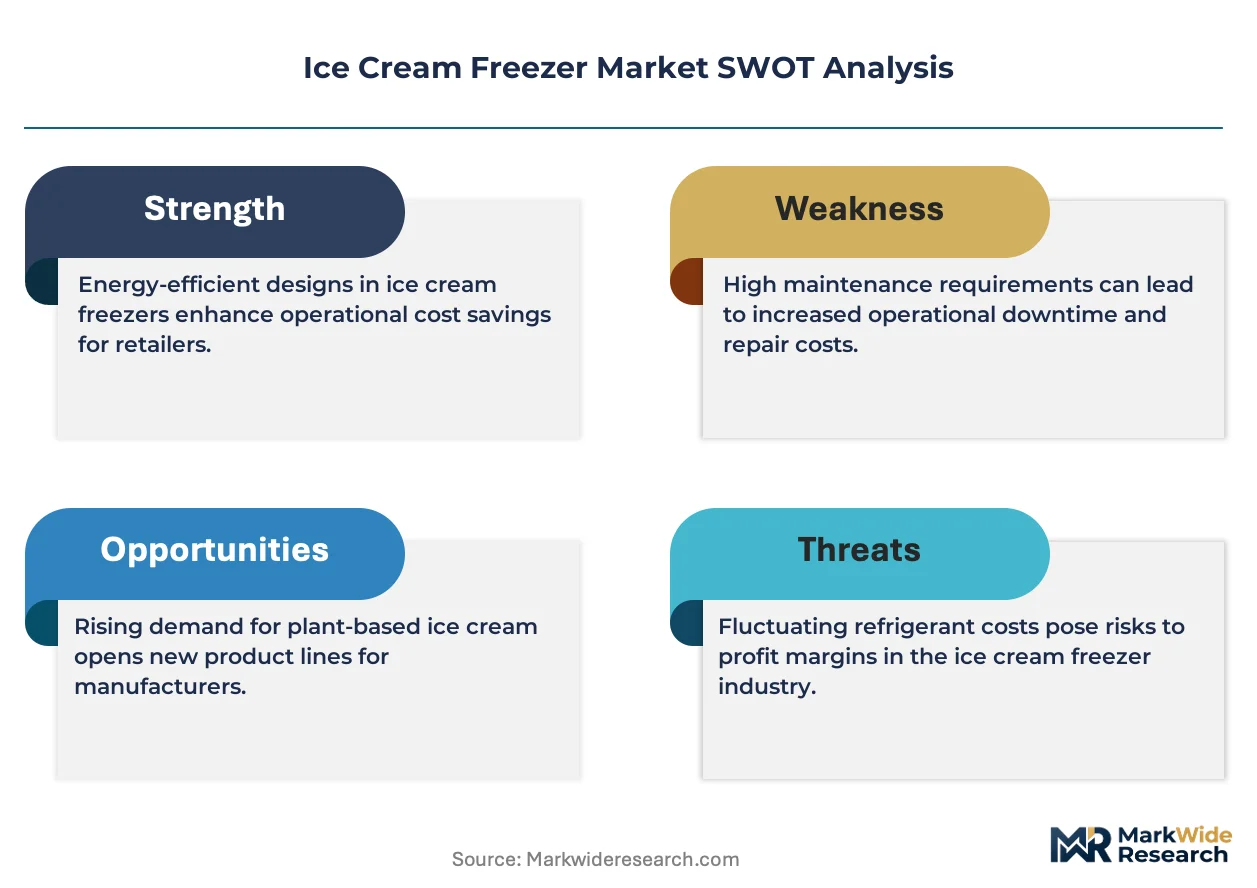
The US EPA SNAP program and the EU F-Gas Regulation are tightening refrigerant phase-down schedules, compelling manufacturers to redesign compressor architectures and recalibrate energy-performance testing protocols. ISO 22000 and national food safety codes in target markets mandate hygienic interior surfaces and temperature logging capabilities that add cost but create compliance barriers for unqualified suppliers. Stakeholders must monitor refrigerant patent cliffs and regional energy-label upgrades to time platform refreshes before regulatory deadlines strand existing inventories.
Market Dynamics
The US EPA SNAP refrigerant phase-down is forcing compressor architecture redesigns across the installed base, while Brazilian street-vendor replacement cycles and European energy-label upgrades create asynchronous demand pulses that manufacturers must synchronize.
Growth Catalysts
- F-Gas Regulation:The EU mandate accelerates HFO and hydrocarbon adoption, opening upgrade revenue streams for compliant cabinet architectures.
- Convenience store freezer fleet expansion:Grab-and-go frozen dessert formats drive compact display unit procurement across North American retail chains.
- Artisanal producer rapid-churn protocols:Small-batch gelato makers invest in blast freezer capacity to control ice crystal formation and differentiate texture quality.
Market Restraints
- Copper and steel input volatility:Compressor housings and cabinet frames face margin compression from commodity price swings.
- Refrigerant patent concentration:HFO formulations remain controlled by limited chemical suppliers, creating supply bottleneck risk.
- High-GWP inventory stranding:Existing R-404A and R-507A units face accelerated depreciation as national phase-down schedules tighten.
Strategic Opportunities
- Dynamic cooling retrofits:Restaurant chains seek uniform temperature distribution systems to protect gelato consistency during extended service hours.
- ISO 22000-compliant hygienic surfaces:Food safety code convergence creates premium positioning for stainless-steel interior platforms with integrated temperature logging.
- India organized retail expansion:Modern trade penetration in tier-2 cities drives first-time freezer procurement for frozen dessert distribution.
Industry Challenges
- Refrigerant transition certification timelines:EPA SNAP and EU F-Gas recertification cycles compress product development windows.
- Legacy control system integration:IoT-enabled temperature monitoring must interface with existing supermarket building management systems.
- Technician training gaps:Hydrocarbon and HFO handling protocols require specialized field service capabilities that remain scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Freezer Market |
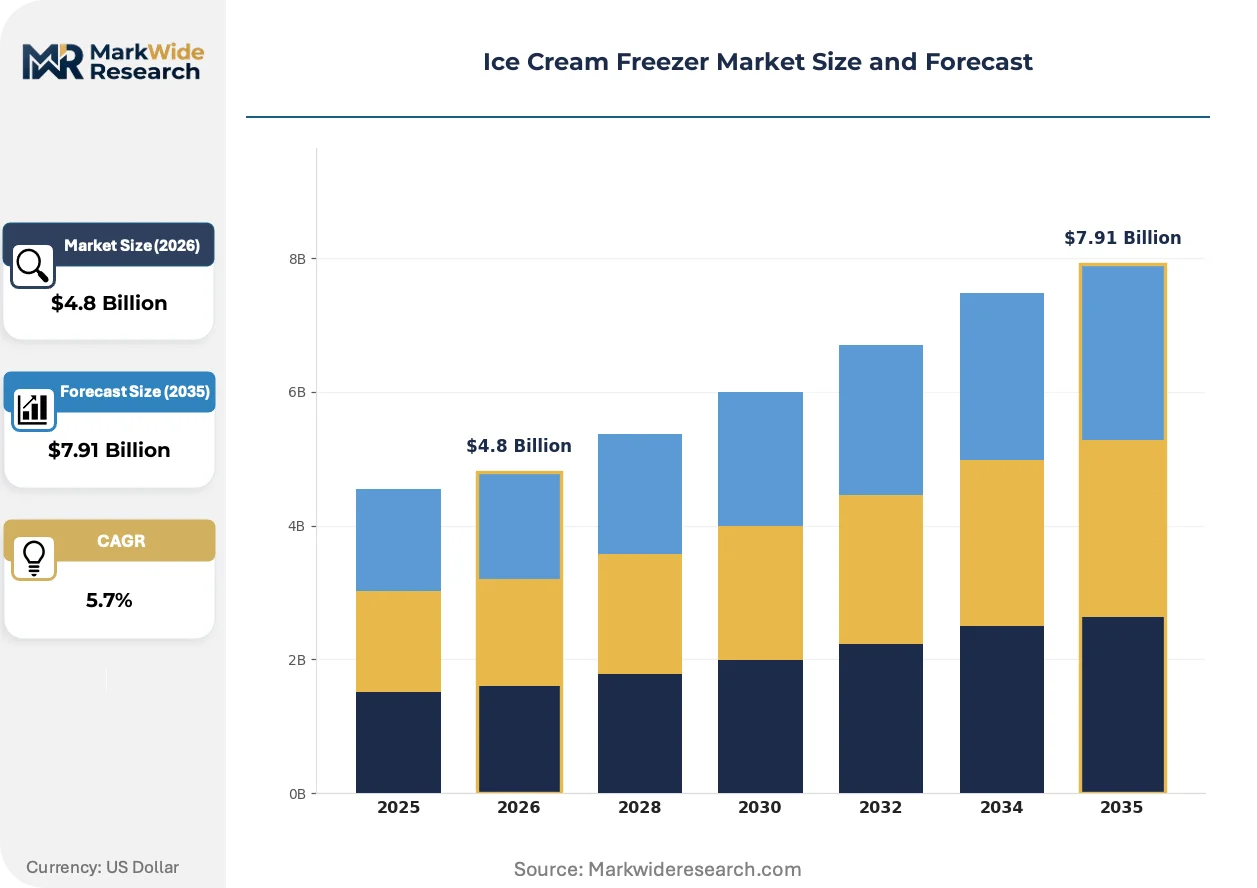
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Freezers, Vertical Freezers, Blast Freezers, Tabletop Freezers End User: Restaurants, Supermarkets, Convenience Stores, Food Trucks Technology: Static Cooling, Dynamic Cooling, Air Cooling, Water Cooling Capacity: 10-20 Liters, 21-50 Liters, 51-100 Liters, Above 100 Liters |
| Companies Covered | Hussmann Corporation, Beverage-Air, True Manufacturing Co., Inc., Electrolux Professional, Ali Group (Carpigiani), Taylor Company, Hoshizaki Corporation, Haier Group, Carrier Commercial Refrigeration, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Freezer Market Shifts & Advancements
Refrigeration technology is bifurcating between efficiency-maximizing compressor architectures and connectivity-enabled operational intelligence, with regulatory deadlines acting as the forcing function for adoption speed.
Variable-speed scroll compressors with permanent magnet motors are electrifying the mid-capacity segment, replacing fixed-speed reciprocating units in supermarket horizontal freezer banks. European retail chains specify these systems to meet EU energy label A+++ thresholds. The technology is electrifying demand for integrated inverter drives that modulate capacity against thermal load rather than cycling on-off.
The EU F-Gas Regulation's stepped reduction in HFC quotas is compressing refrigerant choice sets for original equipment manufacturers. Equipment redesigns now prioritize R-290 propane and R-1234yf in low-charge architectures. Artisanal producers and small-format retailers face the steepest compliance cost curves as their unit volumes resist amortization of platform redevelopment.
After-sales service unbundling is fragmenting traditional manufacturer-distributor relationships. Independent service contractors now capture temperature monitoring and preventive maintenance contracts previously held by OEM captive networks. Brazil and India exhibit the most pronounced channel restructuring as third-party cold-chain specialists expand technical capabilities.
Ice Cream Freezer Market Segmentation
Equipment specification choices in ice cream freezers cascade through energy compliance, service intervals, and merchandising effectiveness. Buyers balance thermal performance against footprint constraints and refrigerant migration timelines.
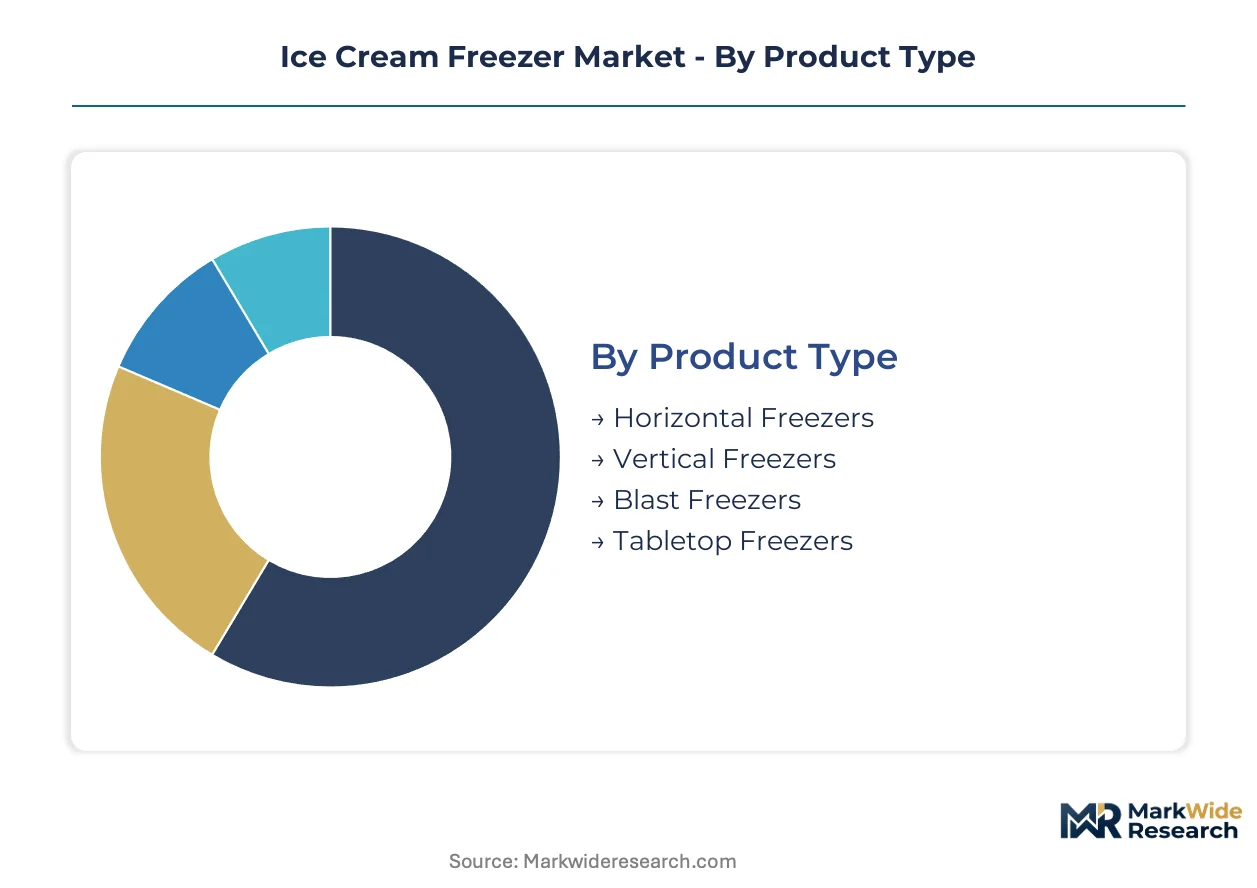
Product Type:
Retail format and inventory velocity dictate cabinet orientation and access design.
- Horizontal Freezers:Wide-opening chest configurations with sliding glass lids or solid covers enable bulk display economics and minimize cold air spillage during high-traffic periods. Supermarket chains in the United States specify these units for frozen dessert aisles where self-service volume drives throughput requirements.
- Blast Freezers:Rapid-churn cabinets deploy forced-air convection to pull product core temperatures from minus 12 to minus 25 degrees Celsius within four hours, arresting ice crystal growth. Artisanal gelato producers in Italy and small-batch operators in Brazil invest in this capacity to differentiate texture quality and extend distribution radius.
- Vertical Freezers:Upright reach-in designs with hinged doors suit back-of-house storage and compact retail footprints where floor space commands premium lease rates.
- Tabletop Freezers:Countertop units with minimal charge volumes serve food trucks and mobile vendors requiring portability and generator-compatible power draws.
Horizontal freezers lead on scale; blast freezers lead on momentum.
End User:
Operational intensity and service-hour duration shape reliability specifications and maintenance contract structures.
- Supermarkets:Multi-deck horizontal banks with integrated lighting and temperature logging face extended runtimes exceeding 18 hours daily. Chains prioritize EU energy label A+++ compliance and IoT-enabled monitoring to protect frozen dessert margins against electricity tariff volatility.
- Convenience Stores:Compact display units with grab-and-go access dominate frozen dessert procurement as formats shrink footprints and expand beverage-plus-treat bundling. North American c-store operators are expanding freezer fleets to capture impulse purchase occasions.
- Restaurants:Front-of-house gelato cases with curved glass and dynamic cooling systems require uniform temperature distribution during service rushes.
- Food Trucks:Vibration-resistant compressors and battery-compatible inverters address mobile power constraints and road shock exposure.
Supermarkets anchor volume procurement; convenience stores are climbing the fastest.
Technology:
Thermal management approach determines energy intensity, defrost frequency, and product surface quality.
- Dynamic Cooling:Forced-air circulation with variable-speed fans maintains cabinet temperature within one-degree Celsius variance, preventing gelato surface hardening during extended service. Restaurant chains in France and Germany specify these systems to protect premium dessert presentation.
- Static Cooling:Natural convection with finned evaporators suits low-traffic storage applications where minimal air movement reduces product dehydration.
- Air Cooling:Direct expansion systems with ambient heat rejection dominate standard commercial installations.
- Water Cooling:Condenser heat exchange through closed-loop water circuits serves high-humidity climates where air-cooled efficiency degrades.
Dynamic cooling commands premium positioning; static cooling retains installed base dominance.
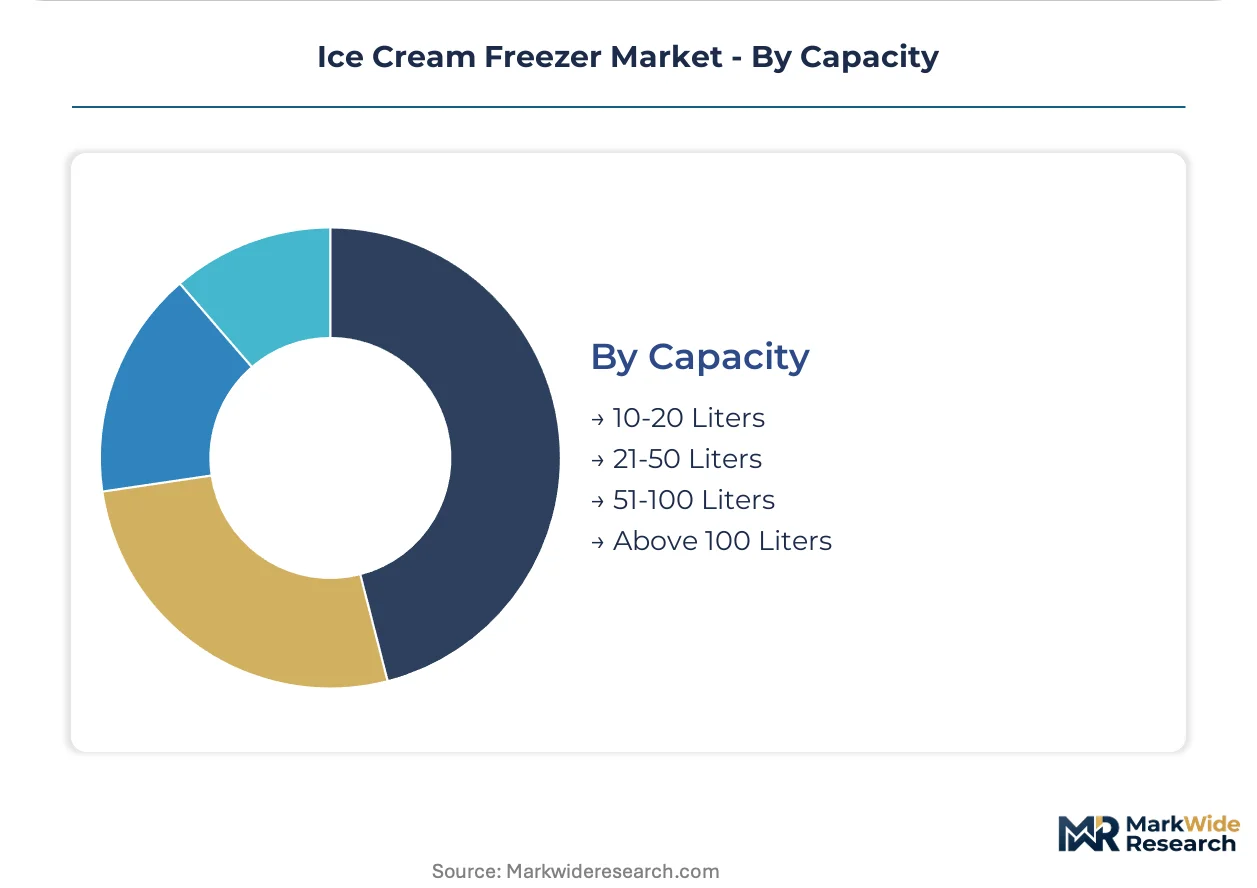
Capacity:
Throughput requirements and replenishment frequency determine liter-band selection.
- 21-50 Liters:Mid-capacity cabinets with inverter-driven compressors balance holding volume against footprint efficiency. Convenience stores and small-format supermarkets in India specify this band for tier-2 city expansion where frozen dessert distribution infrastructure is building out.
- Above 100 Liters:High-capacity horizontal banks with dual compressors and segmented temperature zones support high-velocity SKUs and seasonal promotional surges. Brazilian supermarket operators deploy these units for beach-season inventory builds.
- 10-20 Liters:Compact undercounter designs serve food trucks and kiosk operators with constrained floor plates.
- 51-100 Liters:Intermediate upright or chest configurations bridge specialty retailer and mid-market restaurant requirements.
Above-100-liter units dominate supermarket procurement; 21-50-liter units gain share fastest in emerging format expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's street-vendor culture and ice cream parlor density drive replacement cycles for compact display units, anchoring Latin American demand patterns for the ice cream freezer market.
United States
Convenience store chains are expanding freezer fleets to support grab-and-go frozen dessert formats. The EPA's SNAP program is phasing down high-GWP refrigerants, forcing equipment upgrades across installed bases. Supermarket operators in Texas and Florida are deploying high-capacity horizontal banks for seasonal promotional surges.
Brazil
Street-vendor replacement cycles and beach-season inventory builds concentrate demand for compact and above-100-liter units. ANVISA food safety codes mandate hygienic interior surfaces and temperature logging capabilities. São Paulo's dense ice cream parlor network sustains rapid turnover of display freezers.
Germany
Restaurant chains specify dynamic cooling systems to protect gelato consistency during extended service hours. The EU F-Gas Regulation accelerates HFO and hydrocarbon adoption, opening upgrade revenue streams. Equipment fabricators in Bavaria anchor European commercial kitchen specifications through deep refrigeration heritage.
India
Modern trade penetration in tier-2 cities drives first-time freezer procurement for frozen dessert distribution. FSSAI national food safety codes create compliance barriers for unqualified suppliers. Convenience store operators in Maharashtra and Gujarat are expanding 21-50 liter capacity bands.
China
Manufacturing scale across multiple capacity bands supports volume tier dominance in Asian markets. GB standards and dual carbon goals compress refrigerant choice sets for original equipment manufacturers. Yangtze River Delta production clusters supply inverter-driven compressor architectures.
Ice Cream Freezer Market Competitive Landscape
Global majors compete with regional champions across distribution network depth and refrigerant compliance capabilities. The vendor base stratifies between captive service networks and independent contractor models. Three archetypes dominate: integrated refrigeration conglomerates with full-stack manufacturing, specialized frozen dessert equipment fabricators, and diversified appliance groups leveraging consumer-brand recognition. Competitive moves concentrate on M&A for regional service footprint expansion and strategic partnerships for hydrocarbon refrigerant technology licensing.
Within the integrated refrigeration tier, Hussmann Corporation and Carrier Commercial Refrigeration occupy positions anchored by North American service infrastructure. Among diversified appliance groups, Haier Group exemplifies scale-driven manufacturing across multiple capacity bands. Electrolux Professional represents European heritage positioning in commercial kitchen specifications.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Beverage-Air |
| True Manufacturing Co., Inc. |
| Electrolux Professional |
| Ali Group (Carpigiani) |
| Taylor Company |
| Hoshizaki Corporation |
| Haier Group |
| Carrier Commercial Refrigeration |
| Others |
Supply & Pricing Matrix
Copper and steel price indices cascade through compressor housing and cabinet frame costs, compressing margins for manufacturers who cannot pass through commodity volatility to supermarket chains locked into annual procurement contracts. This input-cost pressure stratifies the market into three pricing tiers: premium dynamic-cooling platforms with ISO 22000 certification, standard static-cooling units for convenience stores, and economy tabletop configurations for mobile vendors.
Pricing Analysis
Input-cost pass-through operates asymmetrically across buyer archetypes, with supermarket chains resisting price escalation through volume leverage while artisanal producers absorb premium positioning for blast freezer capacity. Price differentiation hinges on EU energy label tier and refrigerant compliance status, with A+++ certified units commanding substantial premiums over legacy R-404A inventory. Cost compression in the standard tier intensifies as Brazilian street-vendor replacement cycles concentrate demand for compact units. Convenience store operators exhibit highest price sensitivity due to thin frozen dessert margins, whereas restaurant chains prioritize texture consistency over capital expenditure.
Supply Chain Analysis
Reverse-logistics flows for compressor refurbishment and refrigerant recovery are expanding as EPA SNAP phase-downs strand high-GWP installed bases, creating secondary parts markets and certified reclamation channels. Manufacturing gravity centers on China for inverter-driven compressor architectures, Germany for precision evaporator fabrication, and Brazil for compact display unit assembly serving Latin American replacement cycles. Supply chains draw from copper Chilean mines, Korean steel mills, and Japanese permanent magnet suppliers. Single-source vulnerability concentrates in HFO refrigerant formulations controlled by limited chemical suppliers. Distribution runs through captive OEM service networks in North America and fragmented independent contractors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA SNAP and EU F-Gas milestones force synchronized equipment replacement across asynchronous national phase-down schedules, converting compliance deadlines into predictable demand pulses.
For Market Incumbents: Acquire regional service contractor networks to defend aftermarket revenue streams against independent temperature-monitoring specialists capturing preventive maintenance contracts. Compressor architecture redesign capabilities must deepen to offset refrigerant patent concentration risk from limited chemical suppliers. Capacity rationalization in high-GWP legacy platforms should accelerate before inventory stranding accelerates depreciation. For New Entrants and Emerging Players: Hydrocarbon refrigerant technology licensing represents the most penetrable wedge for mid-cap specialists lacking captive chemical partnerships. Target India's tier-2 city modern trade expansion where first-time freezer procurement lacks entrenched supplier relationships. Position through FSSAI-compliant hygienic surface platforms with integrated temperature logging as a bundled compliance solution. For Investors and Strategic Acquirers: Asymmetric upside sits with diversified appliance groups possessing manufacturing scale across multiple capacity bands and existing refrigerant transition R&D pipelines. Long-term viability favors acquirers who can amortize platform redevelopment across global volume tiers rather than single-region specialists. Monitor EPA SNAP recertification timeline compression as the inflection signal for manufacturer margin stress versus upgrade revenue capture.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant Platform Migration | R-290 propane architectures unlock EU F-Gas compliance and A+++ energy label positioning. |
| Independent Service Network Acquisition | Captive aftermarket contracts protect margin pools from third-party cold-chain specialists. |
| Dynamic Cooling Technology Licensing | Restaurant chain specifications in France and Germany create premium tier access. |
| ISO 22000-Certified Surface Platform Launch | ANVISA and FSSAI convergence creates compliance barrier against unqualified competitors. |
| Inverter-Drive Compressor Integration | Variable-speed scroll electrification meets EU energy label thresholds and electricity tariff volatility protection. |
Research Methodology
Multiple input streams — regulatory filing analysis, equipment shipment databases, and channel partner interviews — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged refrigeration equipment procurement managers at supermarket chains, aftermarket service directors at OEM captive networks, and technical compliance officers at compressor manufacturers. Secondary validation drew from EPA SNAP submissions, EU F-Gas quota registries, ANVISA equipment certification records, and trade flow data from refrigeration component customs classifications.
Historical volume trajectories were cross-referenced against expert panel assessments of refrigerant transition timelines and energy-label upgrade adoption curves across the projection horizon. Segmentation modeling incorporated product type orientation, capacity band distribution, end-user operational intensity, and regional regulatory cluster dynamics. CAGRs were derived from slope-consistency checks against replacement cycle frequencies and phase-down deadline clustering. Forecast inputs included artisanal producer blast freezer penetration rates and convenience store format expansion trajectories.
The model holds under steady regulatory phase-down schedules and commodity price bands; deviation in refrigerant patent litigation outcomes or copper tariff escalations would shift replacement timing and manufacturer margin structures. Forecasts embed assumptions regarding technician training pipeline expansion for hydrocarbon handling protocols. Periodic stress-testing of base assumptions is recommended against EPA SNAP recertification backlog scenarios and emerging market cold-chain infrastructure buildout velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Smart Food Machine Market