
 Smart Bread Machine Market | 2026-2036
Smart Bread Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bread Machine Market Analytics
Stainless steel is hardening its position as the dominant chassis material in premium smart bread machines, displacing lower-grade plastics and extending product lifespans. Panasonic Corporation leverages captive metallurgy partnerships to control input costs across its Osaka production footprint. Zojirushi Corporation anchors its North American position through specialized thermal engineering that sustains repeat purchase rates among serious home bakers. Breville Group Limited differentiates via in-house firmware development that tightens integration with third-party recipe platforms.
A smart bread machine is an electric countertop appliance that automates dough mixing, kneading, proofing, and baking through microprocessor-controlled thermal cycles and programmable crust settings, typically operating at 550–850 watts with integrated sensors for ambient temperature compensation. Its primary commercial purpose is to reduce manual labor and skill barriers in consistent bread production for households and small food service operations. Fully automatic units with IoT-enabled technology command the dominant revenue share, while programmable models represent the fastest-expanding segment as consumers seek sourdough and gluten-free customization. Digital controls remain the baseline expectation, but Wi-Fi connectivity is shifting from premium novelty toward standard configuration as recipe libraries migrate to subscription cloud services.
The EU Ecodesign Directive and REACH compliance frameworks in Europe, alongside FCC equipment authorization requirements in the United States, are elevating compliance costs for connectivity modules and surface coatings while simultaneously creating market access barriers for unbranded imports. Japan's METI energy efficiency labeling program shapes consumer preference hierarchies in a market where electricity consumption ranks among top three purchase criteria. Stakeholders must monitor whether emerging food-contact material restrictions in major economies force reformulation of non-stick coatings before the next product refresh cycle locks in supplier commitments.
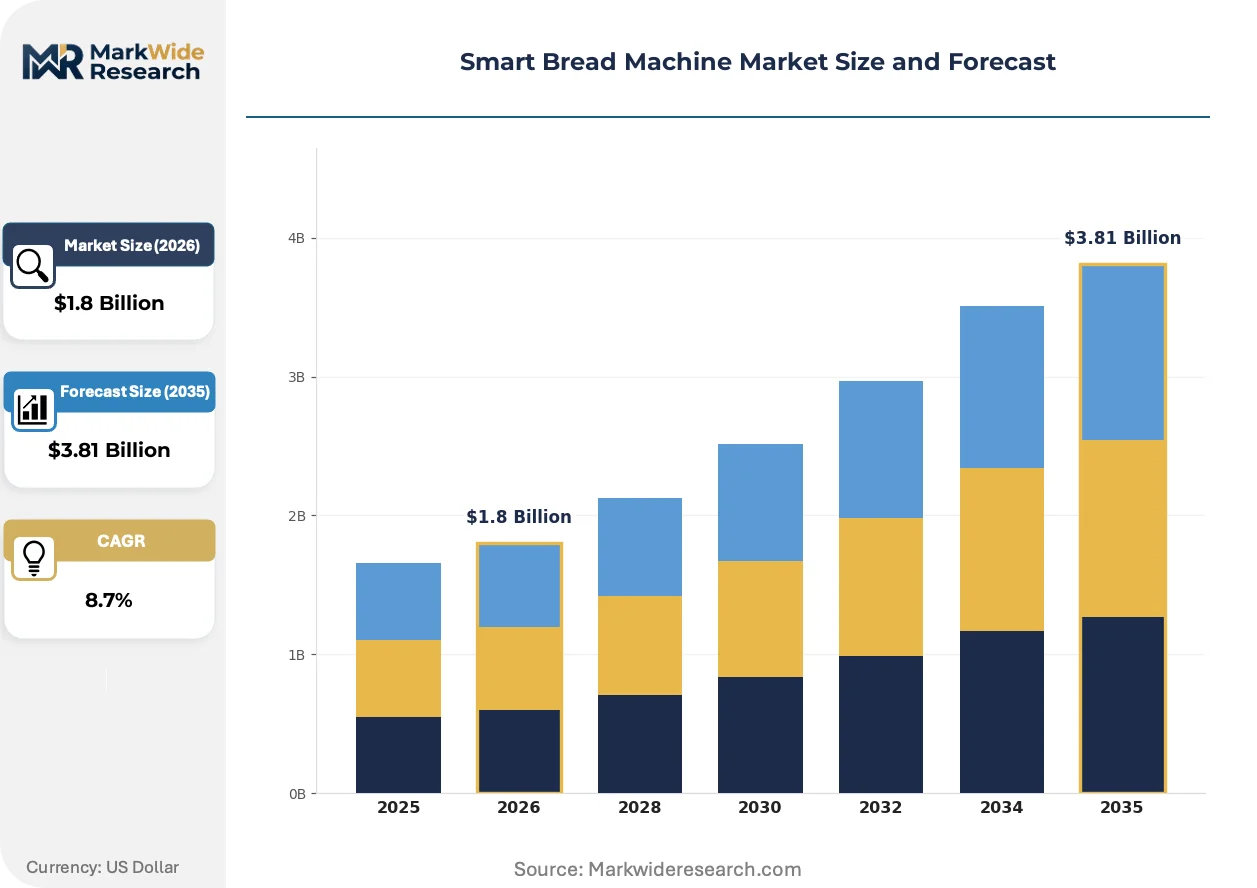
Market Dynamics
The EU Ecodesign Directive's tightening standby power limits are forcing manufacturers to redesign thermal management systems and connectivity modules, compressing margins for mid-tier producers while rewarding those with captive firmware development capabilities.
Growth Catalysts
- Connected Kitchen Ecosystem Maturation:Residential households in Germany and Japan are integrating smart bread machines into unified appliance networks controlled through centralized home automation platforms.
- REACH Compliance Framework:European surface coating standards are accelerating the shift from fluoropolymer-based non-stick surfaces to ceramic and silicone alternatives in premium units.
- Sourdough and Gluten-Free Programmability:Specialized fermentation cycles with ambient temperature compensation sensors are attracting serious home bakers seeking artisanal output consistency.
Market Restraints
- East Asian Manufacturing Concentration:Premium programmable units with IoT integration depend heavily on component clusters in Osaka and Shenzhen, creating single-source vulnerability for European and North American brands.
- Stainless Steel Input Volatility:Captive metallurgy partnerships control chassis material costs for incumbents, but spot market exposure punishes smaller assemblers during nickel price spikes.
- FCC Equipment Authorization Friction:Wi-Fi module certification timelines for the United States market delay product launches by four to six months compared to CE-marked equivalents.
Strategic Opportunities
- Subscription Cloud Recipe Services:Third-party recipe platforms are migrating from one-time app purchases to recurring revenue models, creating attach-rate potential for firmware-integrated hardware vendors.
- METI Energy Efficiency Labeling:Japan's electricity consumption disclosure requirements favor inverter-driven motor systems, opening differentiation space for thermal engineering specialists.
- Small Food Service Penetration:Micro-bakeries and café chains in urban Japan are adopting compact automatic units for overnight production, expanding addressable demand beyond residential households.
Industry Challenges
- Embedded Firmware Talent Scarcity:Microprocessor-controlled thermal cycle optimization requires rare combinations of food science and real-time systems engineering, constraining product refresh cadence.
- Coating Supplier Lock-in:Next product refresh cycles risk premature non-stick formulation commitments before emerging food-contact material restrictions in major economies crystallize.
- Legacy Analog Control Integration:Entry-level programmable models still rely on mechanical timers that conflict with digital ecosystem connectivity expectations, forcing parallel SKU maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bread Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Programmable, Manual Technology: Wi-Fi, Bluetooth, IoT-Enabled, Digital Controls End User: Households, Bakeries, Restaurants, Food Service Providers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Panasonic Corporation, Zojirushi Corporation, Cuisinart, Breville Group Limited, Midea Group, Electrolux AB, JVCKenwood Corporation, Koninklijke Philips N.V., Oloey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bread Machine Market Evolving Landscape
Wi-Fi connectivity is absorbing functions once reserved for premium tiers, while regulatory pressure on standby power and surface materials compresses design freedom. Recipe platform economics and thermal sensor precision are emerging as the primary axes of competitive differentiation.
Precision infrared temperature sensors paired with ambient compensation algorithms are absorbing the role of experienced baker intuition in crust development and crumb structure optimization. Serious home bakers in Japan and Germany are adopting these sensor-augmented units within eighteen-month replacement cycles. This sensor integration is absorbing margin from traditional timer-based mid-tier products and consolidating demand around firmware-differentiated premium lines.
The EU Ecodesign Directive's 2025 standby power thresholds are forcing module suppliers to redesign Wi-Fi chipsets and display controllers for sub-one-watt idle consumption. Compliance engineering now consumes fifteen to twenty percent of R&D budgets for connectivity-enabled models. European market entry for unbranded imports is constricting as notified body certification costs exceed ten thousand euros per SKU variant.
Recipe platform unbundling is fragmenting the traditional bundled-content model that shipped with fixed internal program libraries. Cloud-subscription access with weekly artisanal recipe drops is replacing static onboard memory in North American and Japanese premium segments. This shift concentrates value capture with firmware-integrated vendors while marginalizing hardware-only assemblers dependent on third-party app compatibility.
Smart Bread Machine Market Segmentation
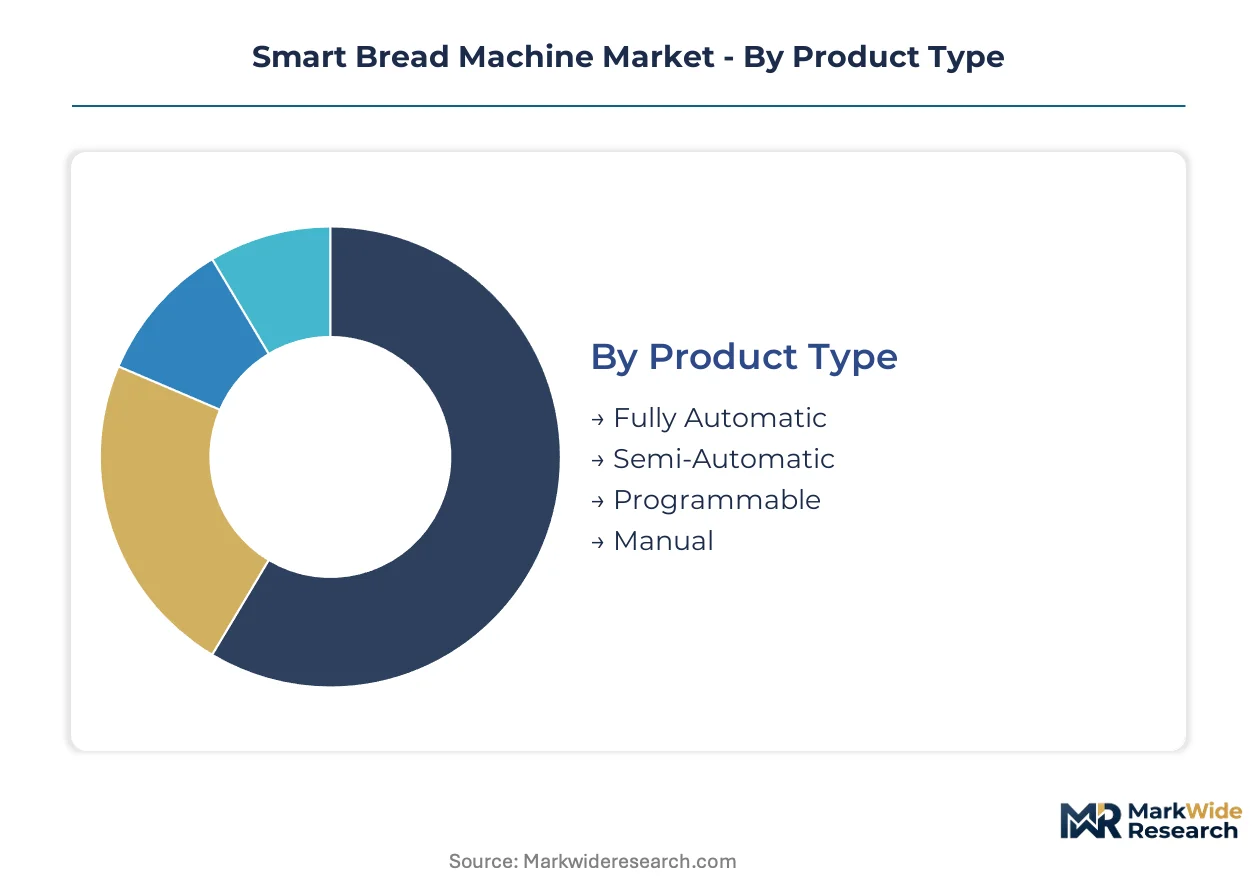
Segmentation in the smart bread machine market reveals how automation intensity, connectivity sophistication, and procurement channel economics partition value capture. Manufacturers configure thermal management firmware and sensor arrays differently across these divides, directly affecting margin structures and replacement cycle timing.
Product Type:
Fully automatic units command premium positioning through complete workflow automation, while programmable models attract customization-focused buyers seeking sourdough and gluten-free cycles.
- Fully Automatic:Microprocessor-controlled systems execute mixing, kneading, proofing, and baking without intervention, typically embedding dual temperature sensors for ambient compensation. Demand concentrates in German and Japanese residential households where connected kitchen ecosystems reduce cognitive load through centralized automation platforms.
- Programmable:User-defined fermentation timelines and crust algorithms accommodate artisanal recipes beyond factory presets, requiring more sophisticated thermal engineering. Serious home bakers in Osaka and Tokyo drive replacement cycles as sensor-augmented precision displaces timer-based intuition.
- Semi-Automatic:Hybrid units automate mixing and kneading while requiring manual shaping or oven transfer, occupying mid-tier price bands.
- Manual:Basic motorized kneaders without integrated baking chambers serve entry-level experimentation and developing markets.
Today's leader: Fully Automatic. Tomorrow's challenger: Programmable.
Technology:
Connectivity modules now absorb fifteen to twenty percent of R&D budgets as regulatory pressure on standby power reshapes chipset selection.
- Wi-Fi:Cloud-integrated units enable subscription recipe services and remote cycle monitoring, demanding sub-one-watt idle consumption to satisfy EU Ecodesign Directive thresholds. North American firmware-integrated vendors capture attach-rate economics as third-party platforms migrate from one-time purchases to recurring models.
- IoT-Enabled:Full ecosystem integration with home automation platforms and predictive maintenance algorithms differentiates premium tiers in Japanese and German markets. FCC equipment authorization timelines delay United States launches by four to six months compared to CE-marked equivalents.
- Bluetooth:Local device pairing without internet dependency serves privacy-conscious European households and connectivity-constrained environments.
- Digital Controls:Touchpad or button interfaces with LCD feedback remain baseline expectations even in mid-tier units, though mechanical timer conflicts complicate ecosystem integration.
Digital Controls anchor volume shipments. IoT-Enabled climbs fastest as METI energy efficiency labeling rewards inverter-driven precision.
End User:
Residential procurement dominates unit economics, though micro-bakery adoption in urban Japan expands addressable demand beyond traditional household boundaries.
- Households:Primary demand source across all geographies, with replacement cycles compressing to eighteen months in sensor-augmented premium segments.
- Bakeries:Compact automatic units enable overnight production in Japanese micro-bakeries and café chains where real estate constraints prohibit full-scale equipment.
- Restaurants:Front-of-house bread programs in European fine dining drive small-batch programmable unit procurement.
- Food Service Providers:Institutional procurement emphasizes durability and standardized output over customization features.
Households generate current margin pools. Bakeries represent the steepest expansion trajectory as urban food service models evolve.
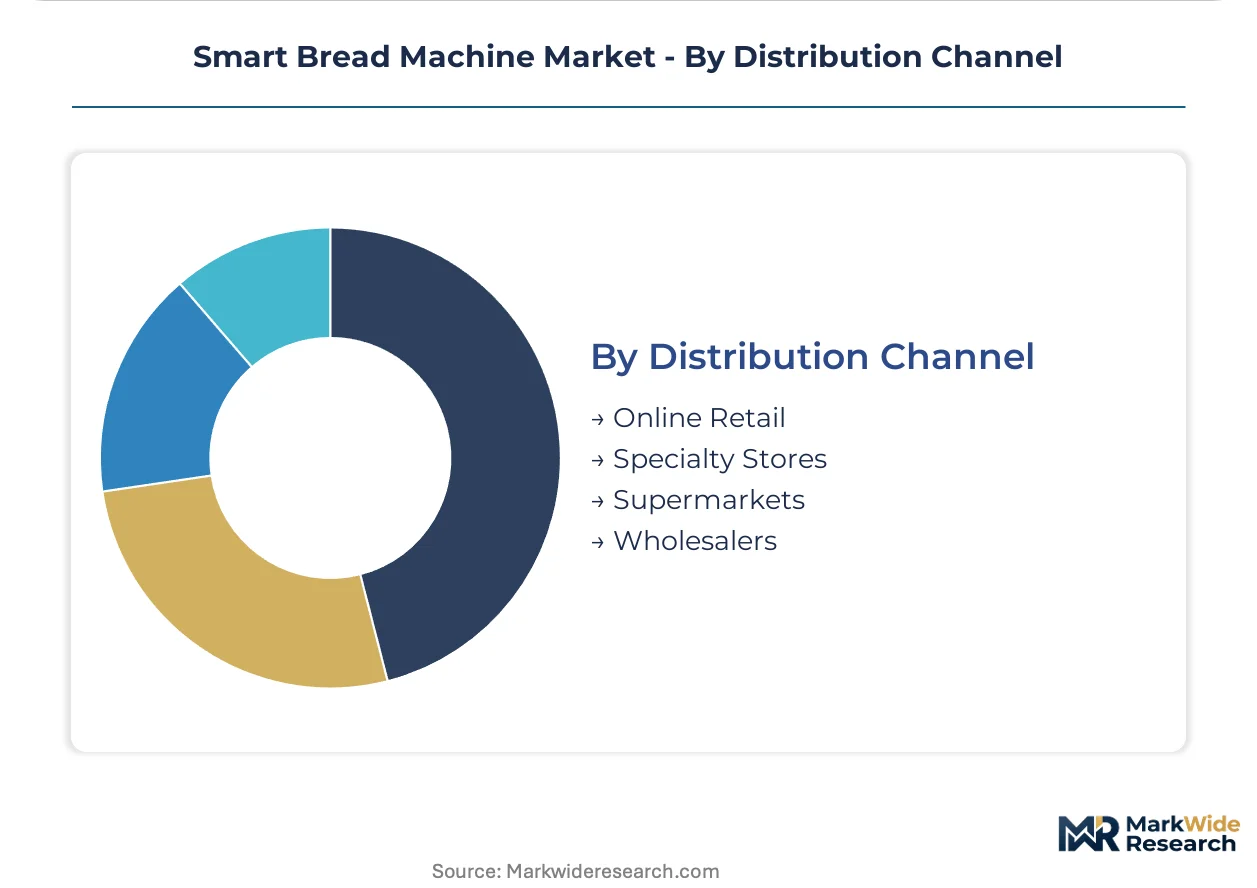
Distribution Channel:
Channel selection determines warranty servicing economics and consumer education requirements, with online retail capturing firmware-integrated premium sales.
- Online Retail:Direct-to-consumer platforms dominate Wi-Fi-enabled and IoT-integrated unit sales, enabling subscription attach rates and cloud service onboarding.
- Specialty Stores:Hands-on demonstration of thermal sensor precision and crust algorithm outcomes supports premium positioning in Japanese and German urban centers.
- Supermarkets:Mass-market digital control and semi-automatic units move through high-frequency retail with limited technical consultation.
- Wholesalers:Food service and bakery channel procurement runs through regional distributors with repair network coverage.
Specialty Stores defend premium positioning. Online Retail scales fastest as recipe platform unbundling concentrates value with firmware-integrated vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka anchors global manufacturing concentration for precision thermal engineering components, while German and Japanese residential markets drive premium adoption through connected kitchen ecosystem integration.
United States
FCC equipment authorization timelines delay Wi-Fi-enabled product launches by four to six months compared to CE-marked equivalents, compressing margin recovery windows for connectivity-focused vendors. The EPA's appliance energy efficiency guidelines shape procurement criteria for institutional food service buyers. California's tech-forward households concentrate early adoption of subscription-integrated recipe platforms.
Germany
EU Ecodesign Directive standby power thresholds below one watt force thermal management redesigns across mid-tier product lines. REACH compliance frameworks accelerate ceramic non-stick coating transitions in premium units. Bavaria's industrial automation clusters supply precision motor systems for inverter-driven bread machines.
Japan
METI energy efficiency labeling programs elevate electricity consumption disclosure to a top-three purchase criterion among residential buyers. Osaka's captive metallurgy partnerships control stainless steel chassis input costs for incumbent manufacturers. Tokyo's micro-bakery sector adopts compact automatic units for overnight production in real-estate-constrained urban environments.
China
Shenzhen's component clusters dominate IoT module supply for premium programmable units, creating single-source vulnerability for European and North American brands. The country's national quality standards regulator enforces electromagnetic compatibility testing for connectivity-enabled appliances. Yangtze River Delta manufacturing hubs produce digital control systems for mid-tier export markets.
Smart Bread Machine Market Competitive Landscape
Strategic partnerships dominate the current landscape as firmware-integrated vendors secure exclusive cloud recipe platform access. The vendor base clusters around three tiers: multinational appliance conglomerates with captive supply chains, specialized thermal engineering houses with metallurgy partnerships, and contract assemblers dependent on spot-market component procurement. Two strategic archetypes have emerged: ecosystem-integrated premium players capturing subscription attach rates, and scale-driven manufacturers defending volume through retail channel density. Competitive moves concentrate on M&A for connectivity talent and backward integration into sensor module production.
Among Japanese specialists, Zojirushi Corporation and Panasonic Corporation exemplify the thermal engineering archetype through metallurgy-controlled production footprints. Breville Group Limited occupies a position within the firmware-differentiated tier, representing vendors that anchor value capture through in-house software development rather than hardware scale. These three companies illustrate how geographic origin and corporate structure correlate with strategic positioning: Osaka-based corporations leverage captive industrial partnerships, while Australian-listed entities prioritize platform integration over manufacturing ownership.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Zojirushi Corporation |
| Cuisinart |
| Breville Group Limited |
| Midea Group |
| Electrolux AB |
| JVCKenwood Corporation |
| Koninklijke Philips N.V. |
| Oloey |
| Others |
Value Network & Pricing Analysis
The EU Ecodesign Directive's sub-one-watt standby power mandate gates qualified supply for premium-tier Wi-Fi-enabled units, compressing margins for assemblers lacking captive firmware development while rewarding Osaka-based incumbents with metallurgy-controlled cost structures. Panasonic Corporation and Zojirushi Corporation leverage backward integration into sensor modules and stainless steel chassis production to defend pricing power against spot-market nickel volatility.
Pricing Analysis
Input-cost pass-through from nickel price spikes and REACH-compliant ceramic coating transitions concentrates pricing pressure on mid-tier digital control units lacking captive supply chains. Three-tier pricing structure across premium, standard, and economy levels separates IoT-integrated firmware-differentiated lines from timer-based mechanical models. Cost compression in semi-automatic segments is intensifying because Shenzhen component clusters favor volume procurement by scale manufacturers. Food service providers exhibit highest price sensitivity due to durability-over-features procurement criteria, while serious home bakers in Tokyo and Munich demonstrate lowest sensitivity to sensor-augmented premium positioning.
Supply Chain Analysis
CE marking and FCC equipment authorization requirements gate component qualification, extending procurement timelines for connectivity modules by four to six months in North American markets versus European equivalents. Manufacturing gravity centers on Japan, China, and Germany, with Osaka and Shenzhen anchoring precision thermal engineering and IoT module production respectively. Raw material dependencies span nickel-alloy stainless steel chassis, ceramic non-stick coatings, and sub-one-watt Wi-Fi chipsets. Single-source vulnerability concentrates in East Asian component clusters serving European and North American brands lacking captive metallurgy partnerships. Distribution runs through online retail platforms for firmware-integrated premium units and regional wholesalers for food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where METI energy efficiency labeling in Japan and EU Ecodesign standby power thresholds create divergent compliance cost structures, rewarding manufacturers with dual-certification capabilities.
For Market Incumbents: Anticipate coating supplier lock-in risks by accelerating ceramic non-stick formulation commitments ahead of emerging food-contact material restrictions. Defend margin position through captive sensor module production and exclusive cloud recipe platform partnerships that marginalize hardware-only assemblers. Prioritize inverter-driven motor system R&D to capture METI labeling differentiation in Japanese residential replacement cycles. For New Entrants and Emerging Players: Begin with micro-bakery penetration in urban Japan where real estate constraints and overnight production needs create white-space demand beyond residential household saturation. Target Bluetooth-enabled privacy-conscious European segments underserved by cloud-dependent Wi-Fi architectures. Pursue direct-to-specialty-store distribution with hands-on thermal sensor demonstration to bypass incumbent online retail dominance. For Investors and Strategic Acquirers: Valuations sit cheapest among contract assemblers dependent on spot-market component procurement and lacking firmware integration capabilities. Long-term viability over the next decade hinges on subscription attach-rate economics rather than hardware shipment volumes. Watch for inflection signals in FCC equipment authorization timeline compression or EU notified body certification cost reductions that would erode incumbent regulatory moats.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Integrated Cloud Recipe Platform | Captures recurring revenue attach rates as third-party platforms abandon one-time app purchases. |
| Captive Sensor Module Production | Reduces single-source vulnerability to Shenzhen component clusters and accelerates product refresh cadence. |
| Ceramic Non-Stick Coating Transition | Anticipates REACH compliance acceleration while avoiding fluoropolymer reformulation risks. |
| Inverter-Driven Motor System Investment | Aligns with METI energy efficiency labeling criteria that shape Japanese consumer preference hierarchies. |
| Micro-Bakery Channel Expansion | Extends addressable demand beyond residential households into real-estate-constrained urban food service. |
Research Methodology
Direct dialogue with thermal engineering directors, connected appliance product managers, ceramic coating procurement leads, and specialty kitchen retailer category buyers grounded qualitative assessment of firmware differentiation value capture. Secondary validation drew from EU Ecodesign Directive implementation documents, METI energy efficiency labeling databases, FCC equipment authorization filings, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up shipment modeling across product type, connectivity technology, and end-user segments was triangulated against top-down macroeconomic consumption indicators.
Top-down macroeconomic filtering established boundary conditions for residential appliance expenditure elasticity, while bottom-up unit economics modeled replacement cycle compression in sensor-augmented premium segments. Segmentation dimensions spanned automation intensity, connectivity sophistication, and procurement channel economics. CAGRs were derived from regression analysis of historical adoption curves in German and Japanese connected kitchen ecosystems, incorporating regulatory compliance cost trajectories and nickel price volatility assumptions. Forecast inputs included METI labeling program expansion scenarios and REACH coating transition timelines.
Caveats apply where EU food-contact material restriction crystallization or FCC certification timeline compression could materially shift the outlook for connectivity-enabled unit economics. Forecasts reflect documented assumptions regarding firmware talent scarcity persistence and cloud recipe platform subscription conversion rates. A model refresh is warranted upon material change in East Asian component cluster concentration or standby power threshold regulatory amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market