
 Blast Chillers Market | 2026-2036
Blast Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Blast Chillers Market Analysis
European commercial refrigeration manufacturing is pivoting toward energy-efficient blast chiller platforms to align with EU Green Deal mandates. Electrolux Group leverages its Nordic engineering heritage to dominate premium floor-standing installations across institutional kitchens. IRINOX S.p.A. anchors its competitive position through specialized rapid-chilling technology developed for high-volume catering operations. Williams Refrigeration sustains UK market presence with robust after-sales service networks and modular capacity configurations.
A blast chiller is a forced-air refrigeration appliance engineered to reduce cooked food temperatures from above 70°C to below 3°C within 90 minutes, thereby inhibiting bacterial proliferation and preserving nutritional integrity. Floor-standing units accommodate tray-based batch processing in central production kitchens, while countertop configurations serve space-constrained restaurants requiring point-of-use chilling. Air-cooled technology leads installed base volumes due to lower infrastructure requirements, though water-cooled and hybrid systems capture margin pools in regions with strict energy efficiency codes. Eco-friendly refrigerant platforms represent the fastest-expanding technology segment as operators preempt regulatory phase-downs of high-GWP compounds.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant selection and mandate minimum energy performance thresholds for commercial refrigeration equipment sold in member states. FDA Food Code provisions in the United States enforce two-stage cooling protocols that effectively mandate blast chilling for large-volume foodservice establishments. Stakeholders must monitor refrigerant transition timelines and regional efficiency standard revisions to align product portfolios with compliance windows and avoid stranded inventory positions.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant transitions across commercial refrigeration, compelling manufacturers to reengineer compressor systems and thermal exchange architectures ahead of mandated phase-down deadlines.
Growth Catalysts
- HACCP Protocol Mandates:Food safety frameworks in the United States enforce rapid cooling standards for high-volume foodservice, institutionalizing blast chiller deployment in hospital cafeterias and hotel central kitchens.
- EU Green Deal Decarbonization:Energy efficiency benchmarks for commercial refrigeration accelerate replacement cycles in Germany and France, pulling forward demand for next-generation units.
- Central Production Kitchen Expansion:Contract catering operators across Italy are scaling tray-based batch processing capacity, driving floor-standing unit procurement for off-site meal preparation facilities.
Market Restraints
- Copper and Aluminum Input Volatility:Thermal exchange coil manufacturing faces raw material price swings that compress fabrication margins and destabilize quoted project pricing.
- Refrigerant Supply Concentration:Low-GWP hydrofluoroolefin production clusters with a limited set of chemical suppliers, creating bottleneck risk during regulatory transition windows.
- Water-Cooled Infrastructure Requirements:Hybrid and water-cooled blast chillers demand building-level plumbing retrofits that many aged European foodservice properties cannot accommodate without structural modification.
Strategic Opportunities
- India Foodservice Modernization:FSSAI safety code enforcement in metropolitan hotel and hospital sectors creates first-mover positioning for rapid-chilling equipment suppliers.
- Refrigerant-as-a-Service Models:Leasing structures that bundle equipment, maintenance, and compliance-managed refrigerant handling address buyer capex constraints in mid-scale restaurant chains.
- IoT-Enabled Predictive Maintenance:Sensor-integrated blast chillers that flag compressor degradation before failure are capturing preference among institutional buyers with zero-downtime requirements.
Industry Challenges
- Refrigerant Handling Certification Shortage:Qualified technicians for low-GWP system installation and servicing remain scarce in secondary European markets, extending deployment timelines.
- Legacy Control System Integration:Kitchens with embedded building management protocols face protocol mismatch when connecting new blast chillers to centralized monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blast Chillers Market |
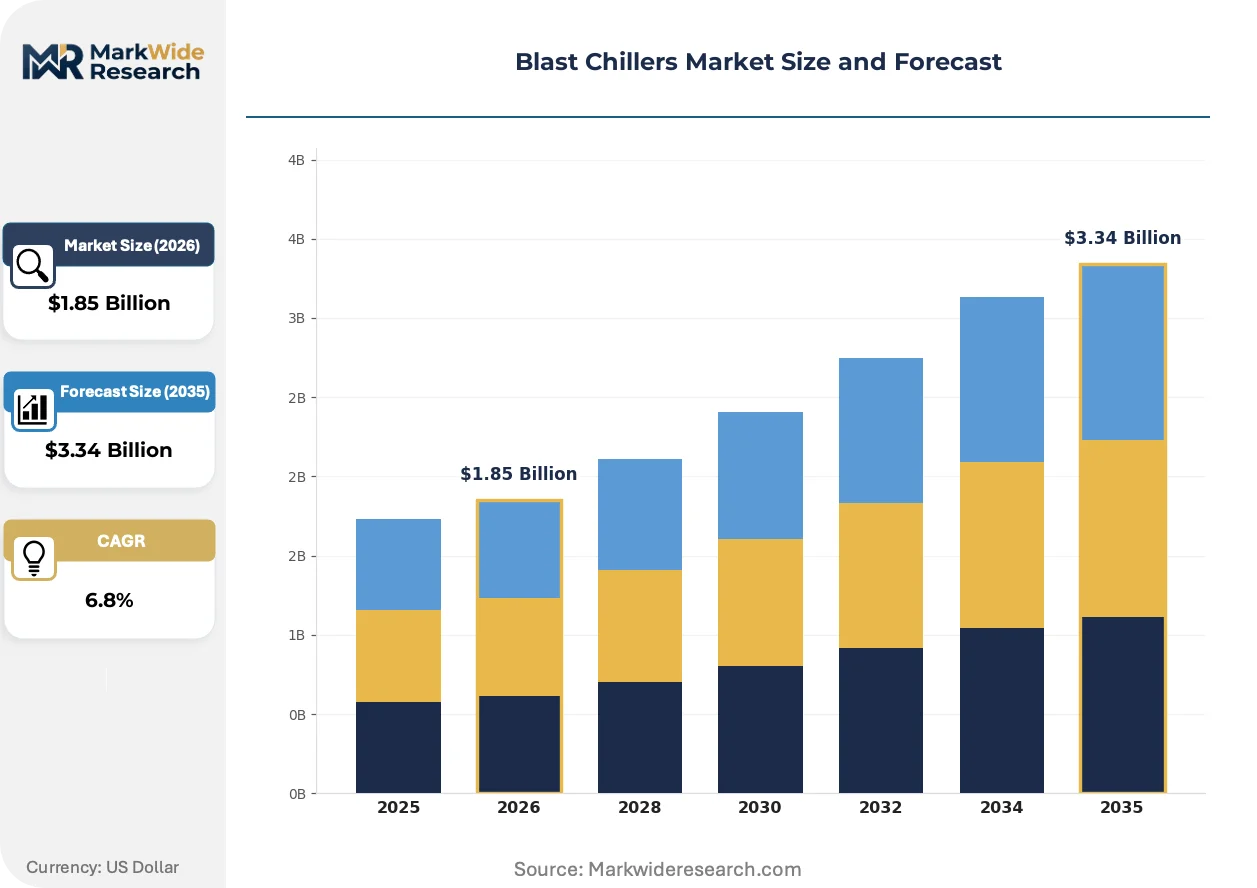
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-Standing, Built-In, Blast Freezers End User: Restaurants, Supermarkets, Catering Services, Industrial Kitchens Technology: Air-Cooled, Water-Cooled, Eco-Friendly, Hybrid Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Electrolux Group, IRINOX S.p.A., Williams Refrigeration, SMEG S.p.A., Hoshizaki Corporation, Alto-Shaam, Inc., Foster Refrigerator, Ali Group, Victory Refrigeration LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blast Chillers Market Emerging Trajectories
Electrification of thermal management and connected equipment architectures are compressing operational decision cycles and reshaping how foodservice operators evaluate lifecycle costs against upfront capital outlays.
Natural refrigerant platforms utilizing propane and carbon dioxide are rewriting efficiency benchmarks for commercial blast chilling. High-volume institutional kitchens in Scandinavia and the Netherlands are specifying these systems for new-build central production facilities. The technology is compressing total cost of ownership calculations by reducing energy draw and eliminating synthetic refrigerant compliance exposure.
The EU F-Gas Regulation mandates progressive reduction in hydrofluorocarbon availability, forcing equipment manufacturers to certify alternative refrigerant architectures before 2030 phase-down milestones. Commercial kitchen operators in Germany and France are preemptively retiring aging units to avoid stranded asset risk. The policy is accelerating replacement demand for compliant platforms ahead of statutory deadlines.
Central procurement consortia among multi-site restaurant operators are consolidating vendor relationships and unbundling after-sales service from equipment acquisition. Large-scale contract caterers in the United Kingdom are negotiating direct maintenance agreements with regional service networks rather than OEM-affiliated channels. The restructuring is visible across hotel group purchasing organizations seeking standardized fleet management across dispersed properties.
Blast Chillers Market Segmentation
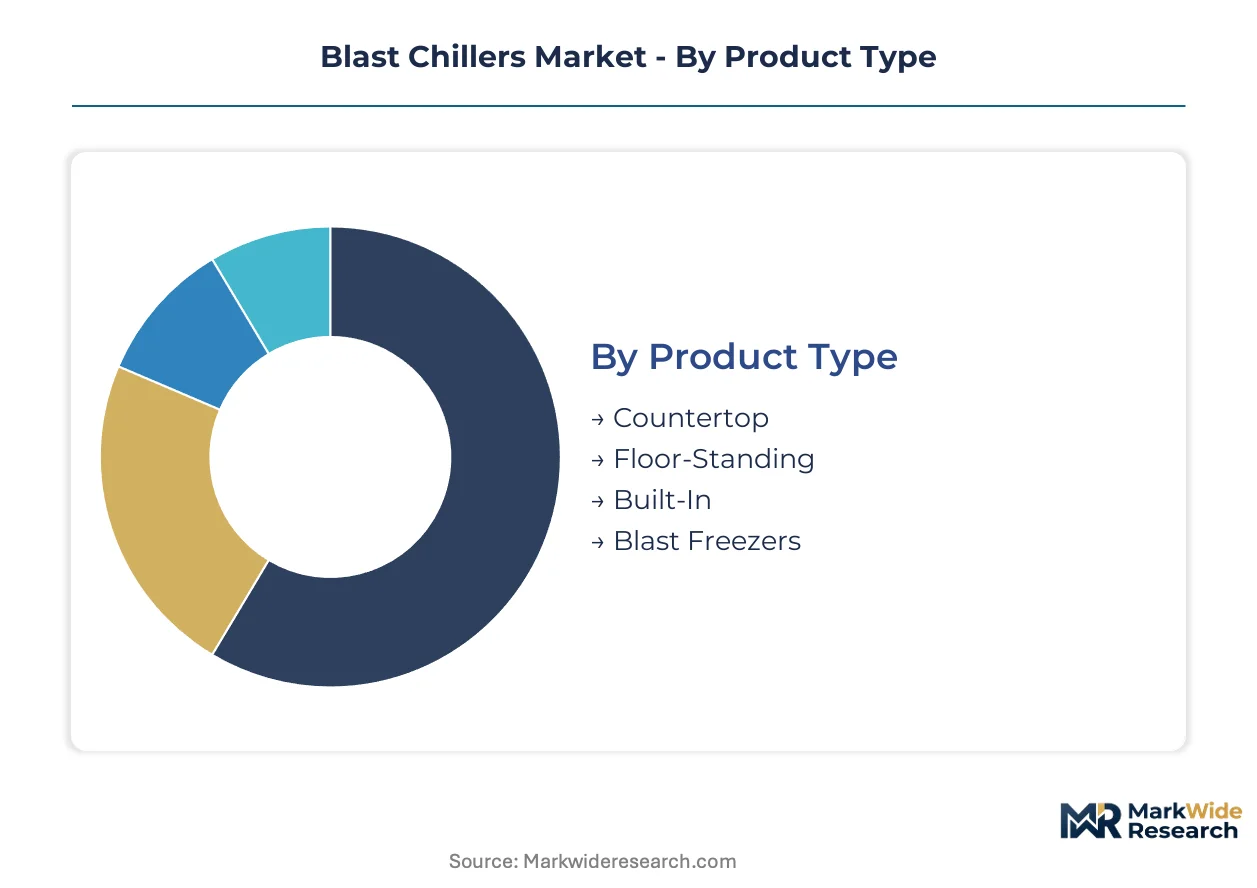
Blast chiller procurement patterns diverge sharply between standalone installations and embedded kitchen systems. Understanding these integration pathways clarifies where manufacturers must configure for modular flexibility versus fixed infrastructure.
Product Type:
Standalone units dominate procurement volumes in renovation scenarios, while built-in configurations anchor new-build central production facilities requiring seamless kitchen line integration.
- Floor-Standing:These tray-based batch processing units accommodate 20-40 GN 1/1 containers per cycle, serving hospital cafeterias and hotel central kitchens across Germany and France. Demand concentrates in institutional settings where HACCP compliance mandates rapid chilling of high-volume cook-chill operations.
- Countertop:Compact units with 3-8 kg capacity per cycle fit space-constrained restaurants requiring point-of-use chilling without dedicated utility rooms. Italian trattorias and bistros in Milan and Rome favor these configurations for à la carte service models.
- Built-In:Seamlessly integrated into kitchen line architecture, these units require custom cabinetry and dedicated ventilation during construction phase.
- Blast Freezers:Dual-function platforms achieving -18°C core temperatures for frozen storage applications in large-scale catering.
Volume placements concentrate in Floor-Standing; the faster expansion belongs to Countertop as urban restaurant footprints shrink.
End User:
Cost tier stratification separates capital-rich institutional buyers from price-sensitive independent operators, with procurement authority increasingly centralizing across multi-site portfolios.
- Restaurants:Independent operators and chain affiliates drive replacement demand as EU F-Gas Regulation deadlines approach, with premium segments prioritizing energy efficiency over first cost.
- Industrial Kitchens:Central production facilities processing 5,000+ meals daily specify heavy-duty floor-standing platforms with redundant compressor systems. German contract caterers like Sodexo and Compass Group affiliates in Frankfurt and Munich anchor this segment's procurement volumes.
- Catering Services:Off-site event operators and mobile foodservice providers favor portable or semi-portable configurations with rapid deployment capabilities.
- Supermarkets:Prepared food counters and in-store bakery operations in French hypermarkets drive demand for compact units with display-friendly aesthetics.
Industrial Kitchens command the highest per-unit expenditure; Catering Services are climbing the fastest as event-based foodservice rebounds.
Technology:
Application context dictates thermal exchange architecture selection, with water access and ambient temperature profiles filtering viable options for each installation.
- Air-Cooled:Self-contained condenser units requiring no plumbing infrastructure dominate retrofit installations across aged European foodservice properties. Lower capital cost and installation flexibility sustain this technology's installed base leadership despite efficiency penalties in high-ambient environments.
- Eco-Friendly:Natural refrigerant platforms utilizing propane and carbon dioxide achieve efficiency benchmarks exceeding synthetic alternatives. Scandinavian institutional kitchens in Stockholm and Copenhagen specify these systems for new-build central production facilities, eliminating synthetic refrigerant compliance exposure entirely.
- Water-Cooled:Building-level plumbing requirements restrict deployment to purpose-built facilities with adequate infrastructure.
- Hybrid:Dual-mode systems switching between air and water cooling optimize energy draw across seasonal load variations.
Air-Cooled retains volume leadership; Eco-Friendly platforms are gaining share fastest ahead of F-Gas phase-down milestones.
Capacity:
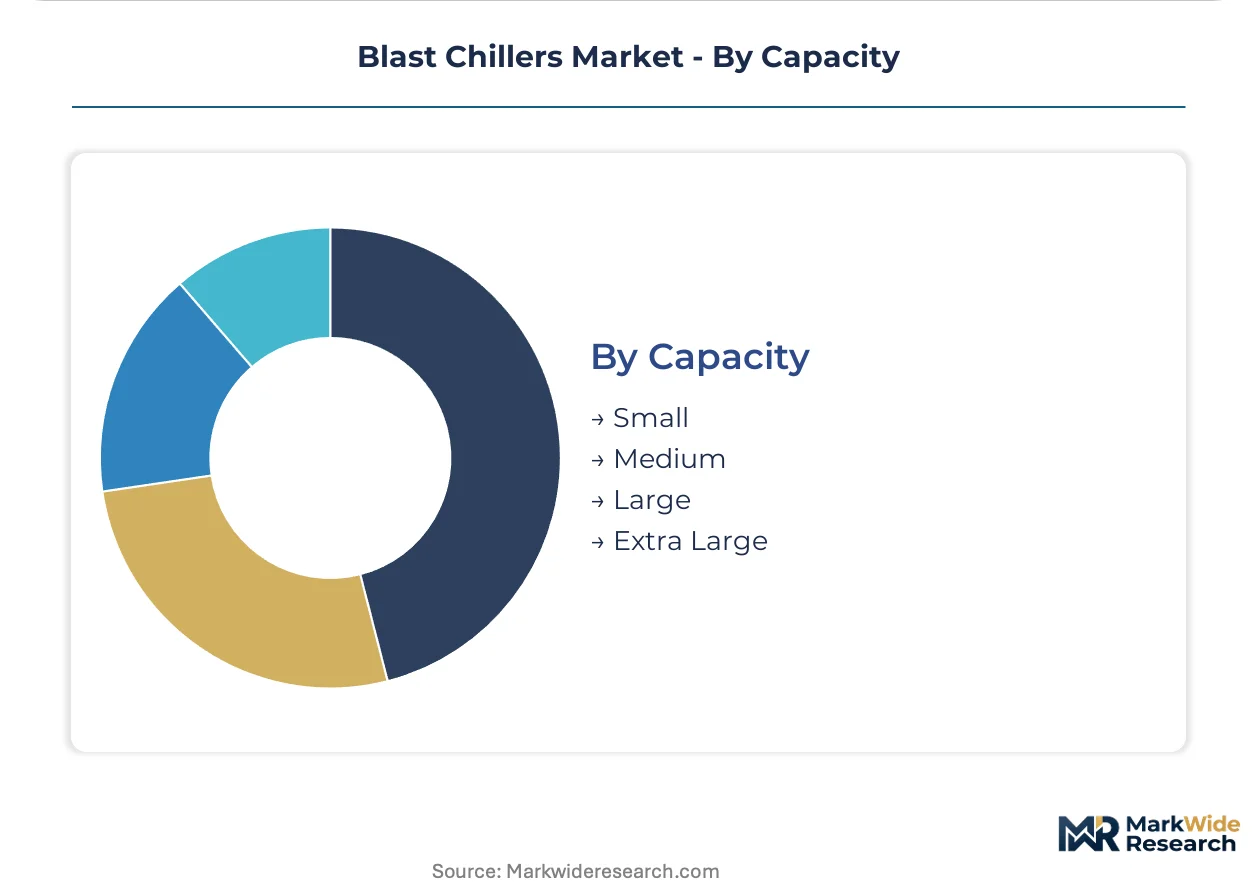
Customer type and throughput requirements segment procurement into four discrete tiers, with medium and large units capturing the majority of commercial foodservice demand.
- Large:Processing 50-100 kg per cycle, these units serve central production kitchens and high-volume hotel operations. French hospital networks in Paris and Lyon specify this tier for cook-chill meal distribution to satellite facilities.
- Medium:20-50 kg capacity balances throughput with footprint efficiency for mid-scale restaurants and catering operations. Italian independent restaurants in Bologna and Florence favor this tier for flexible batch sizing.
- Small:Under 20 kg capacity addresses boutique bakeries and specialty food producers with limited daily volumes.
- Extra Large:Exceeding 100 kg per cycle, these industrial platforms serve airline catering and military commissary operations with extreme throughput requirements.
Medium capacity commands placement volume; Large units show the steepest expansion trajectory as central kitchen consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and copper coil fabrication clusters in northern Italy anchor European blast chiller manufacturing capacity. Component supply chains radiate from these metalworking centers toward assembly plants in Germany and France. Demand patterns diverge sharply between mature Western European replacement cycles and emerging market first-time procurement.
Germany
Industrial kitchen operators in Frankfurt and Munich drive floor-standing unit procurement for central production facilities serving 5,000-plus daily meals. The EU F-Gas Regulation accelerates equipment replacement ahead of synthetic refrigerant phase-down deadlines. Baden-Württemberg hosts precision compressor engineering clusters supplying thermal exchange systems across the continent.
France
Hospital networks in Paris and Lyon specify large-capacity blast chillers for cook-chill meal distribution to satellite healthcare facilities. The EU Green Deal mandates energy efficiency benchmarks that pull forward demand for next-generation platforms. Île-de-France concentrates procurement authority among centralized purchasing consortia for multi-site foodservice operations.
Italy
Independent trattorias and bistros in Milan and Rome favor countertop configurations for space-constrained à la carte service models. F-Gas Regulation compliance windows prompt independent restaurant operators to retire aging air-cooled units. Emilia-Romagna's metalworking districts supply thermal exchange coils to domestic and export markets.
United States
FDA Food Code enforcement institutionalizes blast chiller deployment in hospital cafeterias and hotel central kitchens across metropolitan corridors. Two-stage cooling protocols effectively mandate rapid-chilling equipment for large-volume foodservice establishments. Chicago and New York City anchor procurement volumes for institutional kitchen renovation programs.
India
FSSAI safety code enforcement in metropolitan hotel and hospital sectors creates first-mover positioning for rapid-chilling equipment suppliers. Maharashtra and Karnataka concentrate commercial foodservice infrastructure investment in Mumbai and Bangalore. Central production kitchen expansion among contract caterers drives initial equipment procurement in tier-one cities.
Blast Chillers Market Vendor Landscape
Global majors compete with regional champions across refrigerant technology and after-sales service networks. The vendor base stratifies into three tiers: premium engineering specialists with Nordic or Italian heritage, mid-scale fabricators serving price-sensitive renovation demand, and diversified refrigeration conglomerates leveraging cross-product bundling. Dominant competitive moves include refrigerant platform recertification ahead of regulatory deadlines and unbundling of maintenance contracts from equipment sales.
Within the premium engineering tier, Electrolux Group and IRINOX S.p.A. exemplify divergent geographic anchoring strategies. Electrolux leverages Swedish corporate heritage to position across institutional kitchen specifications in Northern Europe. IRINOX occupies a specialist position rooted in Italian rapid-chilling technology development. Williams Refrigeration represents UK-based regional champion archetype, sustaining market presence through modular capacity configurations and service network density rather than pan-European manufacturing scale.
| Leading Market Players |
|---|
| Electrolux Group |
| IRINOX S.p.A. |
| Williams Refrigeration |
| SMEG S.p.A. |
| Hoshizaki Corporation |
| Alto-Shaam, Inc. |
| Foster Refrigerator |
| Ali Group |
| Victory Refrigeration LLC |
| Others |
Supply Flow & Price Mechanics
Natural refrigerant platform transitions simultaneously compress manufacturing cost structures and redistribute component sourcing toward specialized compressor engineering clusters in Germany and Scandinavia. Electrolux Group and IRINOX S.p.A. capture pricing power through captive thermal exchange design capabilities while mid-tier fabricators face margin erosion from copper coil volatility and F-Gas Regulation compliance investments.
Pricing Analysis
Warranty and aftermarket service bundling separates premium OEM pricing from unbundled equipment-only transactions common among independent restaurant operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic service network density. Price erosion runs through the economy tier as Asian manufacturers enter European renovation demand with stripped-down air-cooled configurations. Industrial kitchen operators demonstrate lowest price sensitivity due to zero-downtime requirements and HACCP compliance liability exposure.
Supply Chain Analysis
Freight cost volatility from northern Italian metalworking districts to German assembly plants compresses margin buffers for coil-dependent fabricators. Component sourcing concentrates in Italy, Germany, and China for thermal exchange systems, compressor assemblies, and electronic control modules. Supply chain risk hinges on single-source vulnerability for low-GWP hydrofluoroolefin refrigerants during EU phase-down windows. Distribution runs through OEM-affiliated service networks and independent commercial refrigeration dealers serving renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance deadlines and refrigerant handling certification shortages are forcing consolidation among undercapitalized mid-tier fabricators unable to fund platform recertification investments.
For Market Incumbents: To counter refrigerant technology disruption from natural refrigerant specialists, Electrolux Group and IRINOX S.p.A. should deepen backward integration into compressor engineering clusters in Baden-Württemberg and Emilia-Romagna while acquiring regional service networks to lock in aftermarket revenue streams from installed base expansion. For New Entrants and Emerging Players: The price-point gap between premium Nordic-engineered platforms and economy-tier Asian imports creates white-space positioning for mid-market rapid-chilling specialists targeting Italian independent restaurants and UK contract catering operators with certified eco-friendly configurations and flexible leasing structures. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified refrigeration conglomerates seeking refrigerant platform capabilities and installed base access. Long-term viability favors targets with captive compressor technology and dense regional service networks. Watch F-Gas phase-down milestone enforcement as the inflection signal for stranded asset risk realization.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Recertification | EU F-Gas Regulation mandates compressor system reengineering ahead of synthetic refrigerant phase-down deadlines. |
| Aftermarket Service Network Acquisition | Consolidating regional maintenance providers captures recurring revenue from institutional kitchen installed bases. |
| Natural Refrigerant Manufacturing Scale-Up | Propane and carbon dioxide platforms eliminate synthetic refrigerant compliance exposure in Scandinavian new-build facilities. |
| IoT Sensor Integration Partnership | Predictive maintenance capabilities address zero-downtime requirements among hospital and hotel central kitchen operators. |
| Leasing and Refrigerant-as-a-Service Launch | Subscription models reduce capex barriers for mid-scale restaurant chains facing F-Gas compliance replacement cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this blast chillers market analysis. Primary interviews with commercial kitchen equipment procurement directors, refrigeration service technicians, contract catering operations managers, and HVAC engineering consultants validated demand patterns and technology transition timelines. Secondary sources included EU F-Gas Regulation implementation reports, FDA Food Code enforcement guidance, and commercial foodservice infrastructure investment databases. Bottom-up unit placement modeling triangulated against top-down market value estimates derived from manufacturer revenue disclosures.
Granularity-level modeling disaggregated volume and value projections across product type, end user, technology, capacity tier, and geographic market cluster. The analytical framework captured replacement cycle dynamics, regulatory compliance windows, and central production kitchen expansion patterns throughout the projection horizon. CAGRs were derived from fitted growth curves applied to segment-level base values, with cross-validation against macroeconomic indicators and foodservice capital expenditure surveys.
Inputs from refrigeration OEMs and commercial kitchen operators were available through the study window; gaps in real-time pricing data from independent fabricators introduce uncertainty bands around economy-tier market value estimates. Forecasts reflect assumptions regarding F-Gas phase-down enforcement consistency and refrigerant supply availability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Industrial Food Slicers Market