
 Food Slicer and Dicer Market | 2026-2036
Food Slicer and Dicer Market Size, Share, and Industry Trends Forecast 2026-2036
Food Slicer and Dicer Market Foresight
Stainless steel is broadening its share against coated aluminum in commercial-grade cutting assemblies, improving corrosion resistance and extending service intervals in high-volume operations. Urschel leverages captive foundry capacity to control blade alloy specifications across its industrial slicer portfolio. Hobart Corporation anchors North American supply through extensive distributor networks serving institutional kitchens. Weber Maschinenbau GmbH differentiates with precision-machined rotary systems for protein processing lines.
Food slicers and dicers comprise electromechanical and manually operated equipment designed to reduce solid foodstuffs into uniform sections or particles through shearing, rotary cutting, or reciprocating blade action, with commercial units typically rated for continuous operation at motor outputs exceeding 250 watts and blade speeds calibrated to specific food densities. Electric slicers dominate revenue contribution due to replacement cycles in deli operations and central commissaries, while combination units represent the fastest-expanding product category as multi-function designs reduce floor space requirements in constrained kitchen layouts. Blade type technology leads installed base metrics, though laser-guided positioning systems are gaining traction in high-throughput food manufacturing where portion consistency directly affects yield calculations.
NSF International standards govern food equipment sanitation design in the United States, while the EU Machinery Directive 2006/42/EC mandates CE conformity for slicer and dicer installations across member states. BSI certification requirements in the United Kingdom create parallel compliance obligations for manufacturers maintaining dual-market product lines. Stakeholders must monitor evolving energy efficiency thresholds and material traceability rules that will determine which equipment configurations qualify for institutional procurement tenders.
Market Dynamics
Quick-service restaurant chains are consolidating procurement around automated prep equipment fleets, compressing replacement cycles and forcing manufacturers to certify simultaneously under NSF International standards and EU Machinery Directive 2006/42/EC to maintain tender eligibility.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:CE conformity mandates are filtering out uncertified suppliers, concentrating demand among compliant manufacturers serving Central European processing plants.
- Stainless steel blade alloys:Precision engineering clusters in Germany are extending service intervals through corrosion-resistant cutting assemblies that reduce downtime in high-volume operations.
- Quick-service restaurant central commissaries:Chains are standardizing on combination units that reduce floor space requirements in constrained kitchen layouts.
Market Restraints
- Nickel and chromium price volatility:Stainless steel input costs fluctuate with commodity markets, squeezing margin stability for blade alloy specifications.
- Dual-market certification burden:Manufacturers serving both US and EU markets face parallel compliance costs from NSF International sanitation standards and BSI certification requirements in the United Kingdom.
- Manual slicer substitution:Small delis and independent operators continue relying on lower-capital manual units for intermittent prep volumes.
Strategic Opportunities
- Laser-guided positioning systems:Protein processing lines are adopting vision-guided portion control to improve yield calculations in high-throughput manufacturing.
- Energy efficiency thresholds:Institutional procurement tenders are beginning to weight motor performance ratings, creating preference for equipment exceeding baseline wattage efficiency.
- Aftermarket blade services:Independent service networks are capturing replacement blade revenue streams previously held by original equipment channels.
Industry Challenges
- Precision machining talent scarcity:Rotary system manufacturers face shortages of technicians capable of calibrating blade tolerances to protein density specifications.
- Legacy equipment integration:Multi-function units must interface with existing kitchen workflows designed around single-purpose machines, complicating installation timelines.
- Material traceability documentation:Supply chains for food-contact alloys lack standardized chain-of-custody records required by tightening institutional procurement rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Slicer and Dicer Market |
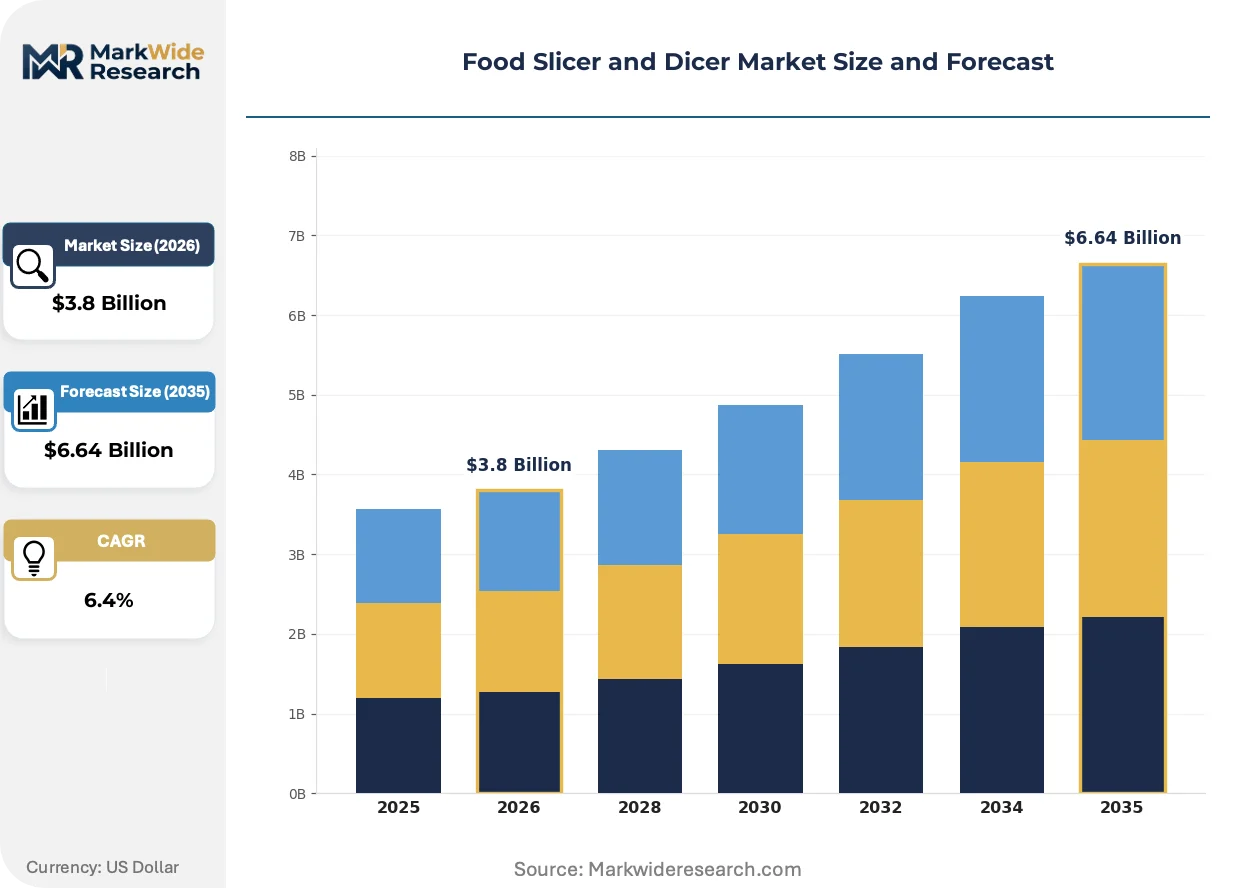
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Slicers, Electric Slicers, Vegetable Dicers, Fruit Choppers, Combination Units Technology: Blade Type, Rotary, Guillotine, Magnetic, Laser Guided Application: Commercial Kitchens, Food Processing Plants, Catering Services, Household Usage, Institutional Facilities End User: Restaurants, Food Manufacturing, Hotels, Cafeterias, Food Retailers |
| Companies Covered | Victorinox AG, Urschel, Bizerba, Hobart Corporation, Robot Coupe, Zwilling J.A. Henckels AG, Weber Maschinenbau GmbH, Friedr. Dick GmbH & Co. KG, MAGURIT Gefrierschneider GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Slicer and Dicer Market Shifts & Advancements
Equipment intelligence and sanitation automation are redefining competitive differentiation, with manufacturers racing to embed predictive maintenance and self-cleaning cycles into commercial-grade platforms before procurement specifications codify these as baseline requirements.
Modular blade cartridge systems are decentralizing maintenance authority from factory technicians to on-site kitchen staff. Deli operators and institutional foodservice directors are adopting swap-out blade units at accelerating pace. This architecture is decentralizing service revenue models and compressing response times for edge damage or contamination events.
REACH substance restrictions are tightening compliance obligations for coatings and lubricants used in food-contact assemblies. Manufacturers reformulating blade surface treatments face reformulation timelines that lag regulatory enforcement dates. Protein processing equipment with extended duty cycles encounters the steepest certification bottlenecks as lubricant migration risks receive heightened scrutiny.
Buyer committees at multi-unit restaurant chains are consolidating vendor relationships around single-source equipment frameworks. Regional distributors serving independent operators are losing share to direct manufacturer contracts that bundle installation, training, and preventive maintenance. This consolidation is most visible in Germany, where precision engineering clusters leverage proximity to anchor long-term supply agreements with expanding QSR networks.
Food Slicer and Dicer Market Segmentation
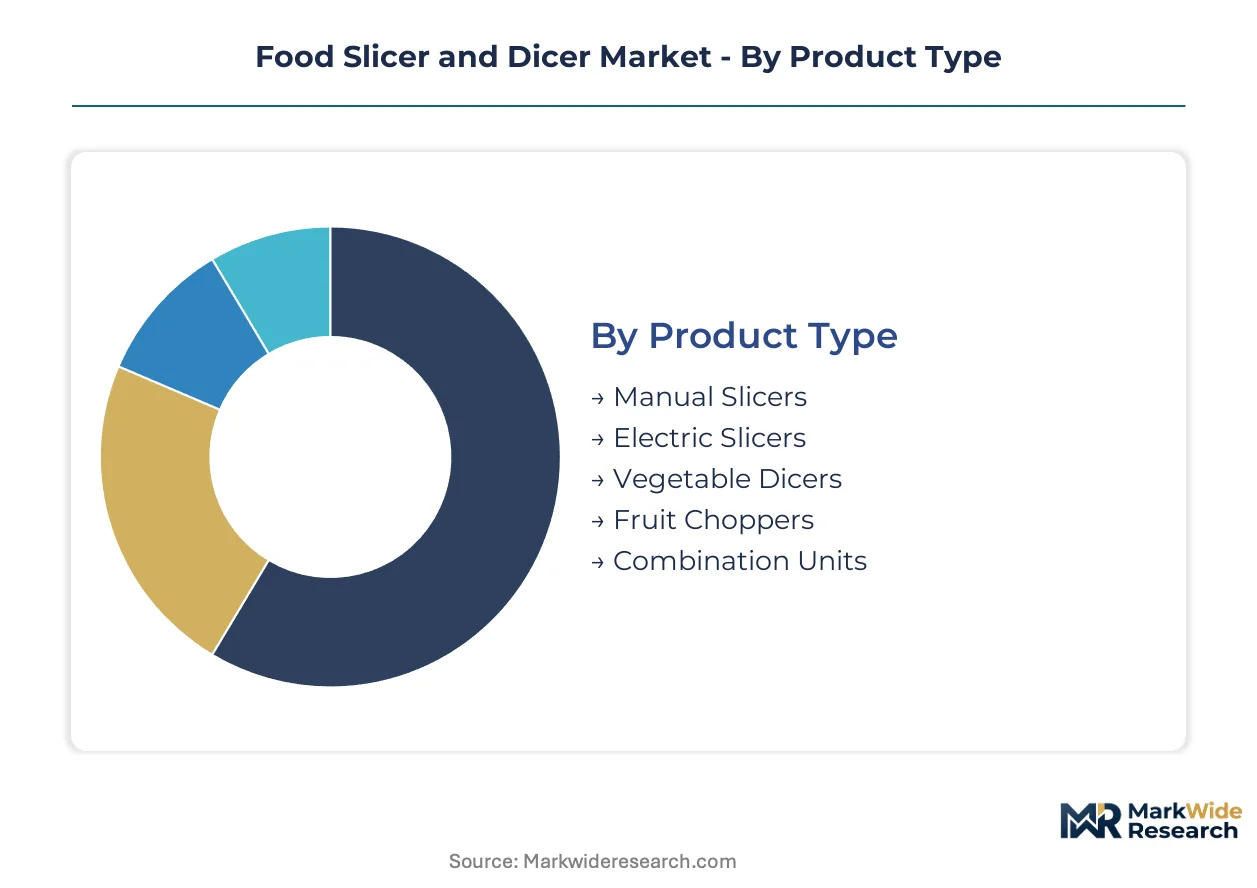
Equipment specification varies sharply across operating environments, with motor ratings, blade materials, and sanitation architectures calibrated to duty cycles and regulatory exposure. Procurement committees weight different performance attributes depending on whether units deploy in intermittent deli service or continuous protein processing lines.
Product Type:
Blade actuation mechanisms and power systems define the core specification axis, determining throughput ceilings and operator skill requirements.
- Electric Slicers:Electromechanical units rated for continuous operation at motor outputs exceeding 250 watts dominate deli operations and central commissaries. Quick-service restaurant chains in Germany are consolidating procurement around automated fleets that compress replacement cycles and demand simultaneous NSF International and EU Machinery Directive certification.
- Combination Units:Multi-function designs integrating slicing, dicing, and chopping capabilities reduce floor space requirements in constrained kitchen layouts. Food retailers and institutional cafeterias in Central Europe are adopting these at the fastest pace as facility footprints shrink.
- Manual Slicers:Hand-cranked units serve small delis and independent operators with intermittent prep volumes where capital constraints outweigh labor costs.
- Vegetable Dicers:Specialized grid-blade assemblies process root vegetables and alliums into uniform cubes for soup manufacturers and prepared salad suppliers.
- Fruit Choppers:Corrosion-resistant coatings handle acidic substrates in juice bars and commercial bakeries requiring precise portion control.
Electric slicers lead on scale; combination units lead on momentum.
Technology:
Cutting kinematics and positioning precision separate commodity equipment from premium-tier installations in high-yield manufacturing environments.
- Blade Type:Reciprocating and rotary blade systems constitute the installed base majority, with stainless steel alloys displacing coated aluminum in commercial-grade cutting assemblies. Precision engineering clusters in Germany supply processing plants throughout Central Europe with corrosion-resistant specifications that extend service intervals.
- Laser Guided:Vision-guided positioning systems are gaining traction in protein processing lines where portion consistency directly affects yield calculations. Food manufacturing facilities in the United States are piloting these for automated quality control integration.
- Rotary:Continuous-feed drum cutters handle high-volume cheese and meat processing with minimal operator intervention.
- Guillotine:Vertical blade action suits dense produce and frozen protein blocks in institutional kitchens requiring simple maintenance protocols.
- Magnetic:Rare-earth retention systems enable rapid blade swaps without tooling, supporting modular cartridge architectures.
Blade type technology anchors volume; laser-guided systems are climbing the fastest.
Application:
Operating intensity and regulatory scrutiny scale with production volume and public health exposure.
- Commercial Kitchens:Quick-service restaurant chains and hotel properties require NSF International-certified sanitation designs with automated cleaning cycles. Equipment intelligence features are becoming baseline expectations in United States institutional tenders.
- Food Processing Plants:Continuous-duty installations face EU Machinery Directive 2006/42/EC conformity mandates and REACH substance restrictions on coatings and lubricants. Protein processing equipment with extended duty cycles encounters the steepest certification bottlenecks.
- Catering Services:Mobile and event-based operations prioritize compact footprint and rapid sanitation turnaround between service periods.
- Household Usage:Consumer-grade units emphasize safety interlocks and simplified blade removal for domestic maintenance capabilities.
- Institutional Facilities:School and healthcare cafeterias balance procurement cost constraints with energy efficiency thresholds in tender specifications.
Commercial kitchens command the largest installed base; food processing plants show the steepest expansion trajectory.
End User:
Buyer sophistication and procurement centralization determine specification complexity and vendor relationship structures.
- Restaurants:Multi-unit chains are consolidating vendor relationships around single-source equipment frameworks that bundle installation, training, and preventive maintenance. Regional distributors serving independent operators are losing share to direct manufacturer contracts.
- Food Manufacturing:Protein processors demand precision-machined rotary systems with blade tolerances calibrated to specific food densities. Talent scarcity for calibration technicians constrains capacity expansion in this segment.
- Hotels:Full-service properties require versatile equipment handling diverse menu requirements across banquet, restaurant, and room service operations.
- Cafeterias:Institutional foodservice directors prioritize modular blade cartridge systems that decentralize maintenance authority to on-site kitchen staff.
- Food Retailers:Deli counters and prepared food sections emphasize portion consistency and visual presentation standards for case-ready merchandising.
Restaurants represent the deepest buyer concentration; food manufacturing demands the highest specification tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor equipment supply for Central European processing plants, with certification requirements tightening across multiple jurisdictions simultaneously.
Germany
Quick-service restaurant chains consolidate procurement around automated prep equipment fleets. EU Machinery Directive 2006/42/EC mandates CE conformity for slicer installations, filtering uncertified suppliers from tender processes. Baden-Württemberg engineering clusters supply corrosion-resistant blade specifications that extend service intervals in high-volume operations.
United States
Deli operations and central commissaries drive replacement cycles for electric slicers rated above 250 watts. NSF International sanitation standards govern food equipment design, creating compliance obligations for dual-market manufacturers. Chicago-based distributor networks serve institutional kitchens with bundled installation and preventive maintenance contracts.
France
Commercial bakeries and juice bars demand corrosion-resistant coatings for acidic fruit processing. ANSM and DGCCRF enforce food-contact material regulations parallel to EU-wide REACH substance restrictions. Lyon-area equipment distributors are losing share to direct manufacturer relationships as multi-unit chains centralize vendor frameworks.
United Kingdom
Institutional cafeterias prioritize modular blade cartridge systems for on-site maintenance authority. BSI certification requirements create parallel compliance costs alongside retained EU Machinery Directive obligations post-Brexit. Midlands manufacturing facilities face margin pressure from nickel and chromium price volatility in stainless steel inputs.
China
Food manufacturing facilities pilot laser-guided positioning systems for automated quality control integration. SAMR and GB standards govern machinery safety and food-contact material specifications. Yangtze River Delta processing plants are adopting combination units to reduce floor space in constrained facility layouts.
Food Slicer and Dicer Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers race to embed predictive maintenance and self-cleaning cycles before procurement specifications codify these as baseline requirements. The vendor base organizes around three tiers: precision-engineered specialists serving protein processing lines, scale-driven fabricators with captive foundry capacity, and diversified kitchen equipment conglomerates with extensive distributor networks. Two strategic archetypes define competitive positioning: modular blade cartridge innovators decentralizing maintenance authority, and integrated solution providers bundling installation with long-term service agreements. Geographic expansion and technology licensing represent the dominant competitive moves, with manufacturers leveraging proximity to anchor supply agreements in expanding QSR networks.
Among German-based precision engineers, Weber Maschinenbau GmbH and MAGURIT Gefrierschneider GmbH occupy positions within the specialized protein processing tier, exemplifying the rotary system expertise concentrated in Central European manufacturing clusters. Urschel represents the scale-driven archetype with captive foundry capacity controlling blade alloy specifications. These three anchors illustrate how competitive positioning stratifies between precision-machined specialists and vertically integrated fabricators capable of dictating material standards across industrial portfolios.
| Leading Market Players |
|---|
| Victorinox AG |
| Urschel |
| Bizerba |
| Hobart Corporation |
| Robot Coupe |
| Zwilling J.A. Henckels AG |
| Weber Maschinenbau GmbH |
| Friedr. Dick GmbH & Co. KG |
| MAGURIT Gefrierschneider GmbH |
| Others |
Supply & Pricing Matrix
Modular blade cartridge architectures are compressing maintenance response times while simultaneously fragmenting service revenue across decentralized networks, forcing manufacturers to recalibrate cost structures around swap-out economics rather than factory technician dispatch. This production-method transition concentrates margin pressure on original equipment channels as independent service networks capture replacement blade streams previously held by captive distribution.
Pricing Analysis
Input-cost pass-through from nickel and chromium volatility in stainless steel alloys is squeezing margin stability for blade specifications across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates NSF International-certified installations from basic commercial units and entry-level manual equipment. Cost compression in mid-range electric slicers is intensifying because commodity metal fluctuations resist contractual hedging. Small delis and independent operators exhibit highest price sensitivity, while multi-unit restaurant chains prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for equipment fulfillment and aftermarket parts. Manufacturing draws from precision engineering clusters in Baden-Württemberg, stainless steel foundries in the American Midwest, and machining facilities in the Yangtze River Delta. Single-source vulnerability concentrates in German rotary system specialists where calibration technician scarcity constrains capacity expansion. Distribution runs through direct manufacturer contracts with QSR chains alongside traditional distributor networks serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Slicer and Dicer Market functions as a regulatory compounder where tightening EU Machinery Directive 2006/42/EC enforcement and NSF International sanitation standards are accelerating replacement cycles among institutional buyers.
For Market Incumbents: Cement certification dual-track investments to maintain tender eligibility across US and EU procurement channels simultaneously. Deepen captive foundry control over blade alloy specifications to buffer nickel and chromium price volatility. Threat exposure centers on independent service networks capturing aftermarket blade revenue through modular cartridge architectures. For New Entrants and Emerging Players: Begin with laser-guided positioning system integration for protein processing lines where yield calculation precision commands premium positioning. White-space concentrates in automated quality control pilot programs at food manufacturing facilities seeking vision-guided portion consistency. Go-to-market leverage rests on energy efficiency threshold compliance for institutional procurement weighting. For Investors and Strategic Acquirers: Valuations sit cheapest among precision-machined rotary system specialists facing technician calibration bottlenecks. Long-term viability favors manufacturers embedding predictive maintenance and self-cleaning cycles before procurement specifications codify these as baseline requirements. Watch for REACH substance restriction enforcement timelines as inflection indicators for coating and lubricant reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Dual-Track Investment | Simultaneous NSF International and EU Machinery Directive compliance secures tender eligibility across institutional procurement channels. |
| Modular Blade Cartridge Development | Swap-out architectures decentralize maintenance authority from factory technicians to on-site kitchen staff, compressing response times. |
| Laser-Guided System Integration | Vision-guided portion control improves yield calculations in protein processing lines where consistency directly affects manufacturing margins. |
| Predictive Maintenance Embedding | Equipment intelligence features anticipate edge damage and contamination events before procurement specifications mandate baseline inclusion. |
| Captive Foundry Capacity Expansion | In-house blade alloy specification control buffers margin stability against nickel and chromium commodity price volatility. |
Research Methodology
Bottom-up commercial kitchen and food processing plant modeling reconciled against top-down precision engineering cluster tracking forms the analytical core of this study. Primary interviews with maintenance directors at multi-unit restaurant chains, plant engineers at protein processing facilities, OEM procurement teams, and aftermarket service heads combine with secondary validation from EU Machinery Directive compliance databases, NSF International certification registries, customs trade records for stainless steel inputs, and SEC filings from diversified kitchen equipment manufacturers. Triangulation across these sources ensures segment-level outputs align with observable supply-side capacity and demand-side procurement patterns.
Historical trendline analysis of equipment replacement cycles and certification adoption rates informs the projection framework across the analysis window. Segmentation dimensions include blade actuation mechanism, cutting kinematics technology, operating environment application, and buyer sophistication tier. CAGRs derive from installed base turnover velocity and penetration rates for combination units and laser-guided systems. Industry-specific forecast inputs incorporate REACH substance restriction timelines and energy efficiency threshold evolution in institutional tenders.
Caveats apply where nickel and chromium price spikes, REACH enforcement acceleration, or technician calibration capacity constraints could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Destemmer Market