
 Optical Sorter Market | 2026-2036
Optical Sorter Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Sorter Market Analysis
Food-grade detection sensitivity is unwinding replacement cycles across the optical sorter landscape. TOMRA Systems ASA sustains technology leadership through deep hyperspectral imaging portfolios. Bühler leverages captive sensor-development capabilities to lock in premium grain-processing contracts. STEINERT anchors European recycling demand with laser-induced fluorescence systems for e-waste streams.
An optical sorter deploys electromagnetic sensors—visible CCD arrays, near-infrared spectrometers, and laser diodes—to classify objects by color, chemical composition, or structural density at throughput rates exceeding 20 tons per hour. Its primary purpose is automated quality control and material recovery in high-volume processing environments. Color sorters dominate agricultural applications where defect removal drives throughput economics, while hyperspectral platforms command the fastest expansion in food safety lines demanding contaminant detection below 1 millimeter. Near-infrared technology occupies mature positions in nut and seed processing where moisture and oil-content sorting determine commodity grading.
The EU Green Deal and REACH frameworks tighten material-traceability requirements, forcing recycling operators to verify polymer purity at input gates. FDA hazard-analysis mandates in the United States compel food manufacturers to validate foreign-object detection protocols under preventive-controls rules. Stakeholders must weigh sensor-modularity investments against the risk of stranded hardware as regulatory detection thresholds tighten without predictable cadence.
Market Dynamics
Food-grade detection thresholds are compressing replacement cycles as hyperspectral imaging capabilities redefine minimum viable performance standards across processing lines.
Growth Catalysts
- EU Green Deal waste-diversion mandates:Binding plastic-recovery quotas in Germany are forcing packaging-sorting facilities to retrofit lines with laser-capable detection systems.
- Near-infrared spectrometry:Nut and seed processors deploy moisture and oil-content sorting to capture commodity grading premiums in high-volume agricultural throughput environments.
- Food safety automation:FDA hazard-analysis mandates under preventive-controls rules compel manufacturers to validate foreign-object detection protocols at input gates.
Market Restraints
- Sensor hardware cost concentration:Visible CCD arrays and laser diodes remain concentrated among Asian component suppliers, exposing buyers to input cost volatility and lead-time uncertainty.
- Regulatory threshold unpredictability:REACH material-traceability requirements tighten without predictable cadence, risking stranded hardware investments for operators who standardize on current-generation platforms.
- Technical detection floor:Contaminant detection below 1 millimeter in high-speed bulk flows remains technically constrained, limiting hyperspectral platform penetration in ultra-fine sorting applications.
Strategic Opportunities
- India food processing expansion:FSSAI enforcement of stricter contamination standards in grain and spice processing creates first-mover advantage for hyperspectral system deployers.
- China dual carbon goals:Municipal recycling operators in Shanghai and Shenzhen face binding waste-diversion targets, accelerating demand for laser-induced fluorescence e-waste sorting systems.
- Technology convergence:Integration of artificial intelligence inference engines with electromagnetic sensor arrays is enabling real-time classification model updates without hardware replacement cycles.
Industry Challenges
- Hyperspectral imaging expertise scarcity:Deployment and calibration of multi-band spectrometer systems requires specialized optical engineering talent that remains concentrated among incumbent equipment vendors.
- Legacy line integration friction:Retrofitting automated inspection systems into existing grain and recycling processing infrastructure demands custom mechanical engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Sorter Market |
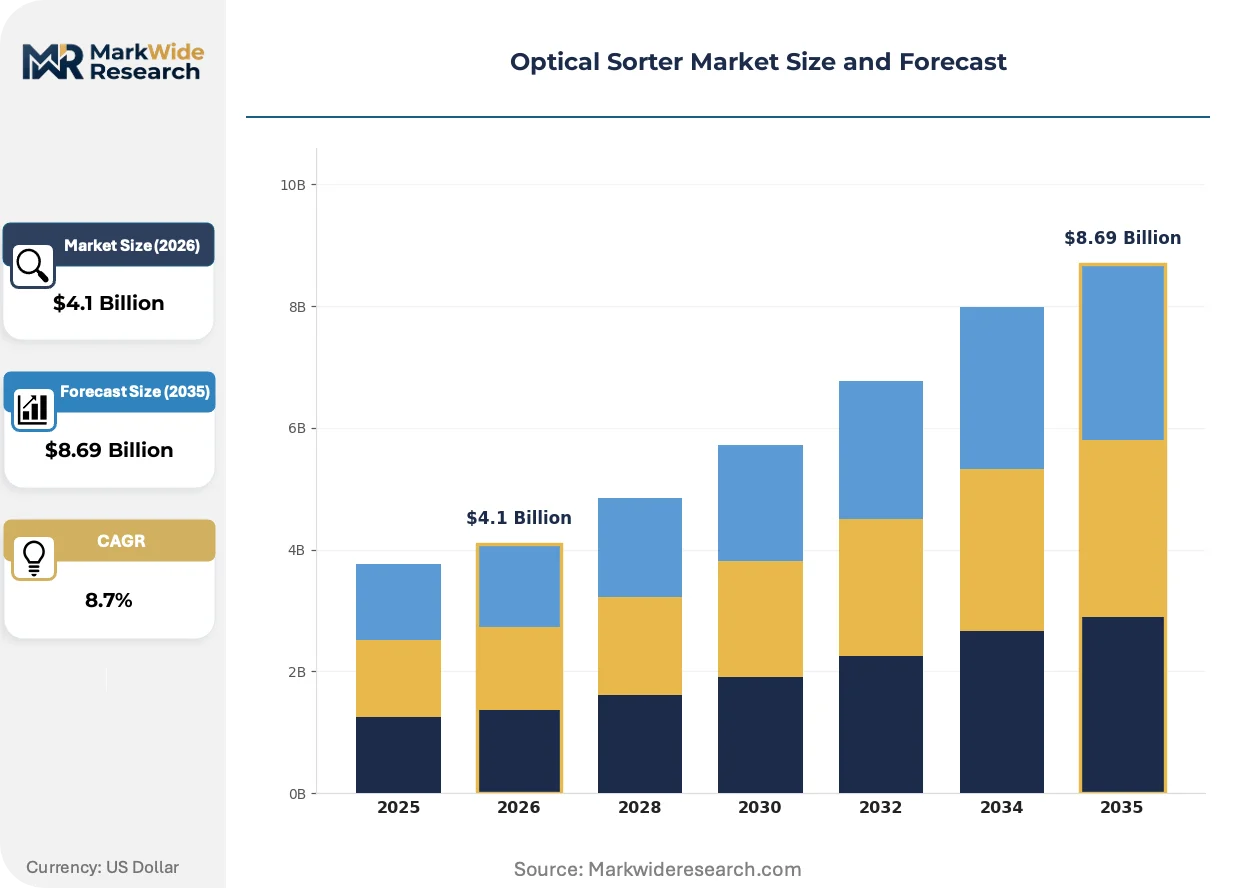
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Sorters, Laser Sorters, 3D Sorters, Hybrid Sorters Technology: Visible Spectrum, Near-Infrared, Fluorescence, Hyperspectral Application: Agriculture, Food Processing, Recycling, Mining End User: Agricultural Producers, Food Manufacturers, Waste Management, Mining Companies |
| Companies Covered | Satake Corporation, STEINERT, TOMRA Systems ASA, Sesotec, Aweta, Bühler, Hefei Meyer Optoelectronic Technology, Bühler-SORTEX, Key Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Sorter Market Emerging Trajectories
Detection sensitivity thresholds are ratcheting upward across food safety and recycling applications, compressing the functional lifespan of installed sensor hardware and accelerating platform refresh cycles.
Hyperspectral imaging arrays spanning visible through short-wave infrared bands are supplanting monochrome CCD color sorters in premium food processing lines. Nut, seed, and grain processors in North American and European facilities are adopting these platforms at replacement-cycle velocity. The technology is enabling detection of chemical composition anomalies invisible to legacy color-based systems, compressing acceptable defect thresholds and forcing competitive parity upgrades.
REACH polymer-traceability verification requirements are tightening input-gate documentation standards for European recycling operators. Industrial consequence includes mandatory laser-induced fluorescence validation of polymer purity before batch acceptance. German packaging-sorting facilities face the most acute compliance pressure, responding with accelerated capital deployment into multi-sensor verification architectures.
Service contract unbundling is fragmenting traditional bundled maintenance relationships between equipment vendors and processing operators. Large food manufacturers in the United States are negotiating separate sensor-calibration and software-update agreements, displacing all-inclusive service packages. This pattern is most visible among FDA-regulated facilities where validation documentation requirements demand specialized third-party certification support.
Optical Sorter Market Segmentation
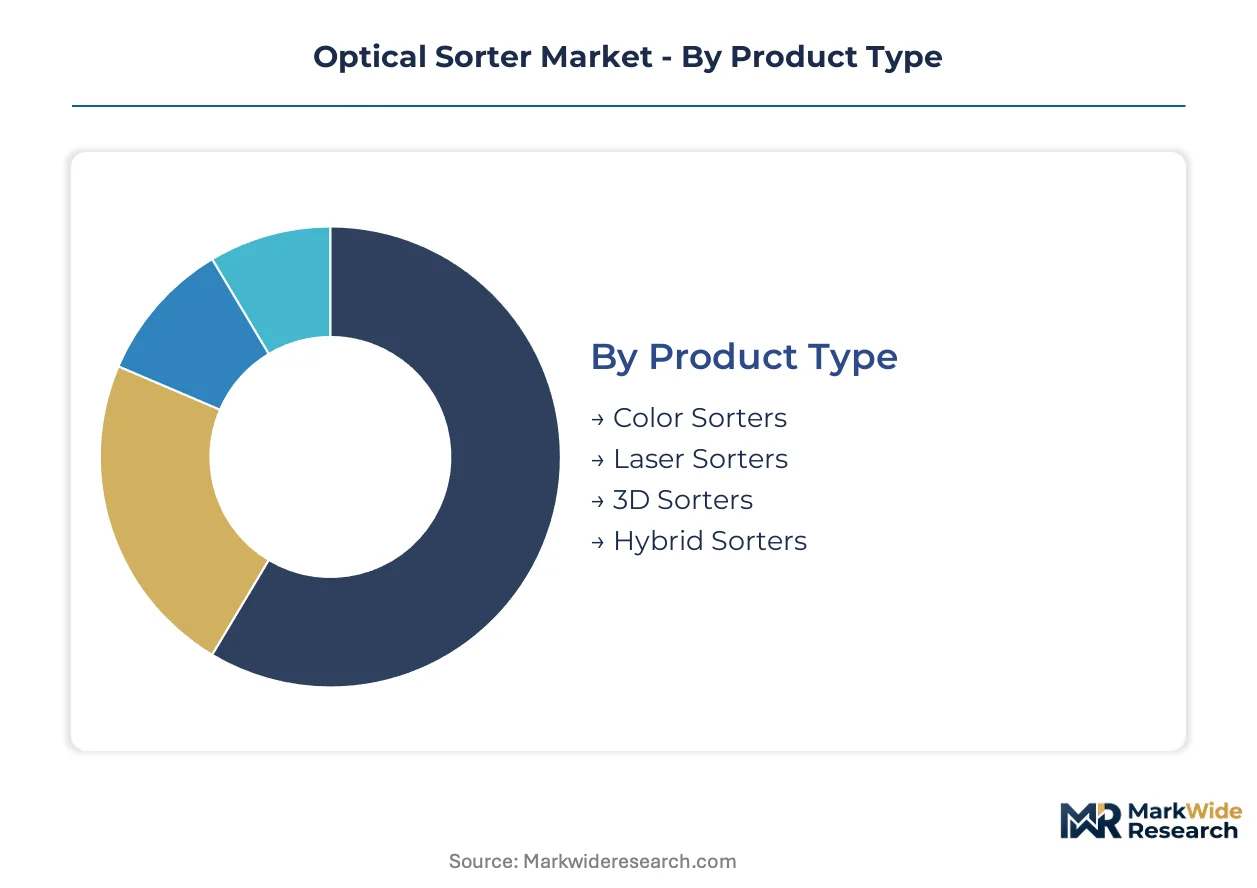
Optical sorter segmentation reveals divergent technology economics across regulatory regimes. FDA preventive-controls enforcement and EU Green Deal mandates are fragmenting equipment specifications by end-use compliance burden.
Product Type:
REACH polymer-traceability rules and FDA hazard-analysis mandates are forcing divergent hardware specifications across food and recycling lines.
- Color Sorters:Monochrome CCD arrays classify objects by surface reflectance in visible wavelengths. Agricultural producers in grain-defect removal applications dominate installed base economics, though hyperspectral displacement is accelerating in premium nut and seed processing.
- Laser Sorters:Laser-induced fluorescence systems detect structural density and chemical composition anomalies at throughput rates exceeding 20 tons per hour. German packaging-sorting facilities facing binding plastic-recovery quotas under EU Green Deal mandates are retrofitting lines with these systems fastest.
- 3D Sorters:Stereoscopic imaging arrays measure object volume and shape for density-based classification in mining applications.
- Hybrid Sorters:Multi-sensor architectures combining visible, near-infrared, and laser modalities command premium pricing in food safety lines demanding sub-millimeter contaminant detection.
Established volume favors Color Sorters; emerging adoption favors Laser Sorters.
Technology:
Cost tier stratification separates mature sensor platforms from premium hyperspectral deployments in contaminant-sensitive processing environments.
- Visible Spectrum:Standard CCD arrays operating in 400-700nm wavelengths deliver cost-effective color classification. Nut and seed processors in North American facilities leverage these systems for commodity grading where oil-content precision demands less than chemical-composition analysis.
- Near-Infrared:Spectrometers measuring 700-2500nm absorption bands quantify moisture, protein, and fat content. Agricultural throughput economics in grain and seed processing anchor demand concentration, with moisture-sorting premiums driving replacement cycles in high-volume facilities.
- Fluorescence:Ultraviolet-excited emission detection identifies polymer purity and surface contamination in recycling streams.
- Hyperspectral:Contiguous spectral imaging across visible through short-wave infrared bands enables chemical fingerprinting at sub-millimeter resolution. Food manufacturers facing FDA foreign-object detection mandates are deploying these platforms despite 3-4x hardware cost premiums.
Near-Infrared claims the deepest installed base; Hyperspectral is climbing the fastest.
Application:
Customer type concentration varies sharply by margin structure and regulatory exposure intensity.
- Agriculture:Grain, seed, and nut defect removal at harvest and primary processing stages. Volume concentration in North American and European facilities with established commodity grading infrastructure.
- Food Processing:Foreign-object detection and quality verification in packaged and bulk food lines. FDA preventive-controls rule enforcement is compressing acceptable detection thresholds and accelerating hyperspectral platform penetration.
- Recycling:Polymer purity verification and e-waste component recovery. EU Green Deal waste-diversion mandates are forcing capital deployment into laser-capable detection architectures across member state facilities.
- Mining:Ore grade classification and gangue rejection at extraction and processing stages. Structural density sorting in high-throughput bulk material flows.
Agriculture holds the largest equipment base; Recycling is gaining share fastest.
End User:
Procurement sophistication separates validation-intensive FDA-regulated facilities from price-sensitive agricultural operators.
- Agricultural Producers:Primary grain, seed, and nut processors optimizing commodity grading premiums. Near-infrared moisture-sorting systems dominate capital allocation in high-volume throughput environments.
- Food Manufacturers:Packaged and bulk food processors subject to FDA hazard-analysis and preventive-controls mandates. These operators negotiate unbundled sensor-calibration and software-update agreements, displacing traditional bundled maintenance relationships.
- Waste Management:Municipal and private recycling operators facing binding diversion targets. German facilities under acute plastic-recovery quota pressure are deploying multi-sensor verification architectures.
- Mining Companies:Extractive and processing operations leveraging density-based sorting for ore grade optimization.
Agricultural Producers represent the most price-sensitive volume; Food Manufacturers command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in agricultural sectors display acute price sensitivity to hardware premiums, while food safety and recycling operators absorb steeper costs to satisfy tightening regulatory thresholds. This demand-elasticity contrast shapes capital deployment patterns across major national markets.
Germany
Packaging-sorting facilities face binding plastic-recovery quotas under EU Green Deal mandates. REACH polymer-traceability rules force verification of input-gate purity documentation. Industrial clusters in North Rhine-Westphalia and Bavaria are retrofitting lines with laser-capable detection architectures fastest.
United States
Food manufacturers scale automated inspection lines to meet FDA preventive-controls enforcement. Hazard-analysis mandates compel validation of foreign-object detection protocols at throughput gates. California and Midwest grain-processing corridors anchor near-infrared moisture-sorting system deployment.
China
Municipal recycling operators in Shanghai and Shenzhen confront binding waste-diversion targets under dual carbon goals. Laser-induced fluorescence demand accelerates for e-waste component recovery. Yangtze River Delta electronics dismantling clusters drive multi-sensor verification architecture procurement.
India
FSSAI enforcement of stricter contamination standards in grain and spice processing creates first-mover openings for hyperspectral deployers. Food-grade detection threshold compression lags advanced economies by three to five years. Maharashtra and Gujarat processing corridors concentrate agricultural sorting equipment demand.
Japan
Grain and seed processors maintain premium commodity grading infrastructure with established near-infrared moisture-sorting economics. METI industrial efficiency guidelines encourage automation retrofit cycles. Kansai and Chubu manufacturing belts sustain replacement-driven platform refresh demand.
Optical Sorter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the optical sorter landscape. The vendor base concentrates among three tiers: integrated processing technology conglomerates with captive sensor development, specialized electromagnetic detection pure-plays, and regional machinery fabricators serving price-sensitive agricultural volume. Strategic moves center on sensor-modularity investments to mitigate stranded hardware risk, and unbundled service contract structures that displace traditional bundled maintenance relationships.
Among European-anchored detection technology specialists, STEINERT and TOMRA Systems ASA occupy positions within the premium-tier hyperspectral and laser-systems segment, while Bühler exemplifies the integrated conglomerate archetype with in-house sensor development capabilities. These three represent contrasting strategic postures: pure-play specialization versus vertical integration into upstream component control.
| Leading Market Players |
|---|
| Satake Corporation |
| STEINERT |
| TOMRA Systems ASA |
| Sesotec |
| Aweta |
| Bühler |
| Hefei Meyer Optoelectronic Technology |
| Bühler-SORTEX |
| Key Technology |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Asian component foundries directly shapes both sensor hardware price floors and buyer negotiation leverage across optical sorter procurement cycles. German packaging-sorting facilities facing EU Green Deal plastic-recovery quotas absorb premium pricing for laser-capable systems, while Indian grain processors drive commoditization pressure on visible CCD color sorters.
Pricing Analysis
EU Green Deal waste-diversion mandates dictate the pricing tier structure across European recycling deployments, separating polymer-traceability-certified laser systems from standard color sorters. FDA preventive-controls enforcement in the United States creates a parallel premium tier for hyperspectral platforms with validation documentation. Cost compression in visible CCD arrays is intensifying because Chinese component suppliers are expanding monochrome sensor foundry capacity. Agricultural producers in grain-defect removal applications represent the most price-sensitive volume, while food manufacturers under FDA hazard-analysis mandates show the least sensitivity to hardware premiums.
Supply Chain Analysis
Strait of Malacca transit routes underpin critical laser diode and near-infrared spectrometer component flows from East Asian fabrication hubs to European and North American assembly facilities. China, Japan, and South Korea anchor visible CCD array and laser diode manufacturing concentration. Optical sorter production draws from indium gallium arsenide photodiodes, precision optical filters, and high-speed signal processing chipsets. Single-source vulnerability concentrates in indium supply chains tethered to Chinese refining capacity. Distribution runs through OEM direct sales for large food manufacturers and regional machinery distributors serving price-sensitive agricultural operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU Green Deal, and FSSAI jurisdictions is fragmenting equipment specifications and creating specialist vendor niches that generalist manufacturers cannot fill.
For Market Incumbents: Consolidate hyperspectral imaging expertise through targeted acquisition of optical engineering talent pools concentrated in German and Swiss research clusters. Lock in premium food processing contracts by offering unbundled sensor-calibration agreements that displace traditional bundled maintenance relationships. Capacity addition in Maharashtra and Gujarat processing corridors captures Indian FSSAI enforcement-driven replacement cycles before regional fabricators scale. For New Entrants and Emerging Players: Unbundled validation documentation services represent the most penetrable service-layer gap, as FDA-regulated facilities demand specialized third-party certification support that incumbent vendors under-provide. Target municipal recycling operators in Shanghai and Shenzhen facing binding dual carbon waste-diversion targets with laser-induced fluorescence systems for e-waste streams. Position through technology licensing partnerships with established electromagnetic sensor developers rather than captive R&D buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play hyperspectral specialists with installed base concentration in FDA-regulated food safety lines. Long-term viability over the next decade hinges on sensor-modularity architectures that mitigate stranded hardware risk from tightening detection thresholds. Watch REACH polymer-traceability threshold announcements as the inflection indicator for accelerated capital deployment into multi-sensor verification systems.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Modularity Architecture Development | REACH threshold unpredictability makes hardware upgradeability essential for European recycling operators. |
| Unbundled Service Contract Structuring | FDA validation documentation requirements drive food manufacturers toward separate calibration agreements. |
| Hyperspectral Imaging Talent Acquisition | Deployment expertise scarcity concentrates among incumbent vendors, creating defensive moats. |
| India Food Processing Market Entry | FSSAI enforcement lag creates three-to-five-year window for hyperspectral first-mover positioning. |
| Laser-Induced Fluorescence Platform Expansion | EU Green Deal plastic-recovery quotas force German packaging-sorting facilities into retrofit cycles. |
Methodological Framework
Operator-level perspectives from plant engineers at grain processing facilities, maintenance directors at packaging-sorting plants, and procurement leads at food manufacturers anchored the qualitative base. Primary interviews combined with secondary validation from SEC equipment vendor filings, EU ETS compliance databases, and FSSAI enforcement circulars. Bottom-up equipment shipment tracking and top-down regulatory mandate sizing were triangulated to cross-verify demand estimates.
Sensitivity analysis across technology adoption curves, regulatory enforcement timelines, and component cost trajectories shaped the projection framework. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user procurement sophistication across the analysis window. CAGRs were derived from installed base replacement velocity and greenfield capacity addition patterns. Forecast inputs incorporated EU Green Deal implementation schedules and FDA preventive-controls inspection frequency data.
Material uncertainties — unannounced REACH detection threshold revisions, indium supply disruptions, and FSSAI enforcement acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory cadence and component supply stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Used Commercial Freezer Market