
 Small Continuous Fryer Market | 2026-2036
Small Continuous Fryer Market Size, Share, and Industry Trends Forecast 2026-2036
Small Continuous Fryer Market Analytics
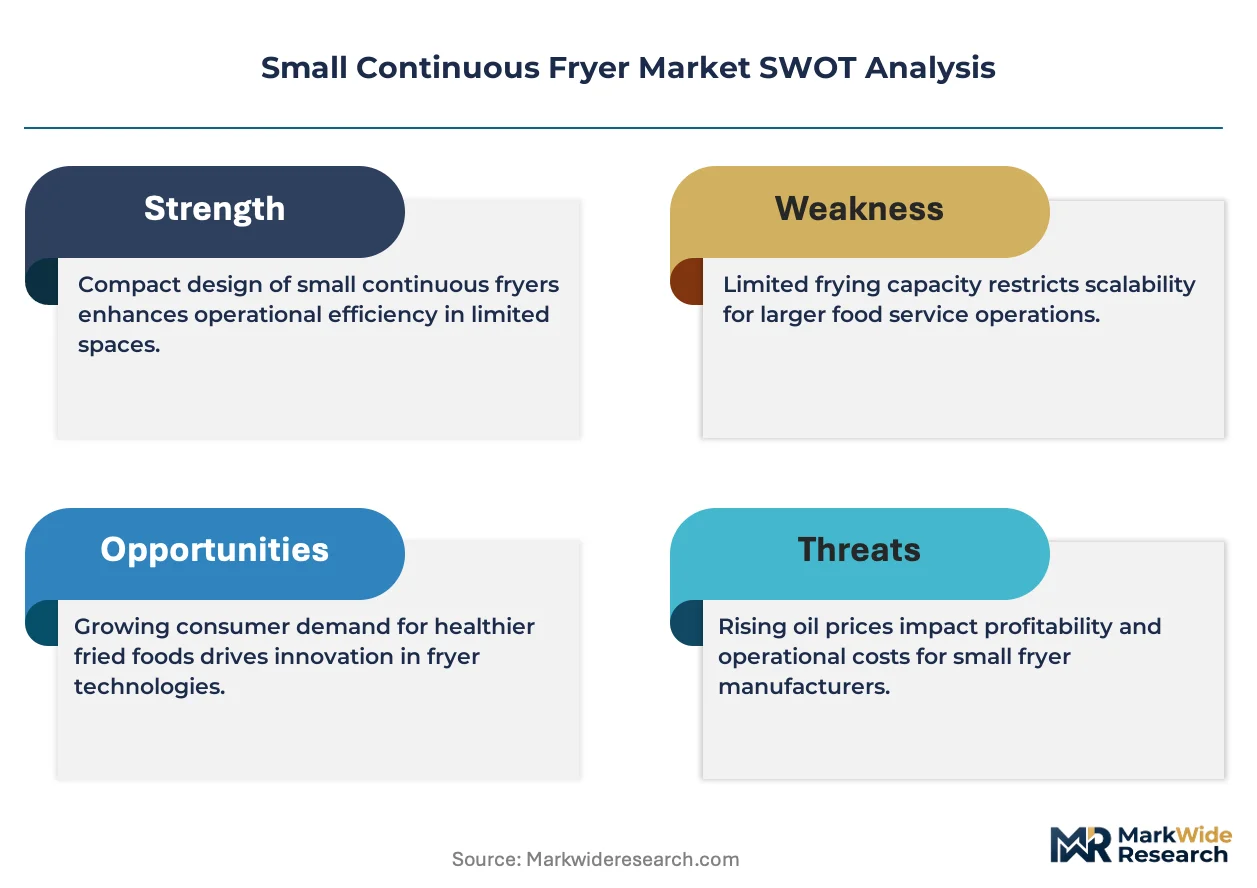
Preventive maintenance contracts and oil-management subscriptions is decoupling hardware margins from recurring revenue streams in the small continuous fryer space. Heat and Control leverages its vertical integration into thermal-system components to sustain pricing power across North American food-processing accounts. EMA Europe anchors its position through specialized European aftermarket service networks. Tecnofryer differentiates on compact electric architectures for urban restaurant footprints with constrained kitchen layouts.
A small continuous fryer is a mechanized cooking apparatus employing a conveyor belt to transport food products through a heated oil reservoir at controlled temperatures, typically operating between 160°C and 190°C with oil turnover rates engineered to preserve product consistency and extend frying-medium life. Electric fryer configurations lead in European commercial installations where grid-connected kitchens face stricter carbon-intensity benchmarks, while gas fryer variants retain cost advantages in North American operations with lower natural-gas tariffs. Floor-standing installations dominate high-volume quick-service environments, whereas countertop units capture expanding demand from food trucks and mobile catering operators seeking equipment mobility without exhaust-duct dependencies.
OSHA guidelines in the United States govern worker-safety protocols around hot-oil exposure and ventilation requirements, while EU F-Gas Regulation constrains refrigerant-based oil-cooling ancillary systems in certain member-state configurations. CE marking mandates under the EU Machinery Directive shape product-access requirements for European manufacturers and importers. Stakeholders must weigh regulatory compliance investments against the operational-efficiency gains from next-generation oil-filtration and energy-recovery subsystems.
Market Dynamics
Energy-efficiency mandates across commercial kitchens are forcing equipment replacement cycles shorter than historical ten-year baselines, with electric architectures displacing gas configurations in grid-connected European operations.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on refrigerant-based oil-cooling systems accelerate adoption of ambient heat-recovery subsystems in member-state food-processing facilities.
- Quick-service restaurants:Chain operators in Germany and the United Kingdom prioritize automated oil-management to reduce labor exposure and extend frying-medium life.
- Conveyor automation:Belt-speed precision controls enable product consistency across high-throughput lines without batch interruption.
Market Restraints
- Stainless steel input volatility:304-grade sheet metal price swings compress fabrication margins for European OEMs sourcing from Turkish mills.
- Supply concentration:Thermal-system component production clusters in southern China create single-source vulnerability for North American fryer assemblers.
- Technical ceiling:Oil degradation sensors lack real-time particulate measurement accuracy below 50-micron thresholds, limiting predictive maintenance efficacy.
Strategic Opportunities
- Urban restaurant footprints:Compact electric architectures serve constrained kitchen layouts in London and Paris where exhaust-duct installation is structurally prohibitive.
- Mobile catering channels:Food trucks and festival operators drive countertop unit demand for equipment mobility without ventilation dependencies.
- CE marking alignment:EU Machinery Directive harmonization creates pathway for standardized aftermarket service networks across Benelux and Nordic markets.
Industry Challenges
- Certification timelines:OSHA hot-oil exposure compliance documentation extends new product introduction cycles by eight to fourteen months for US-bound equipment.
- Legacy system integration:Existing kitchen management software lacks API compatibility with next-generation fryer telemetry, forcing middleware development costs onto operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Continuous Fryer Market |
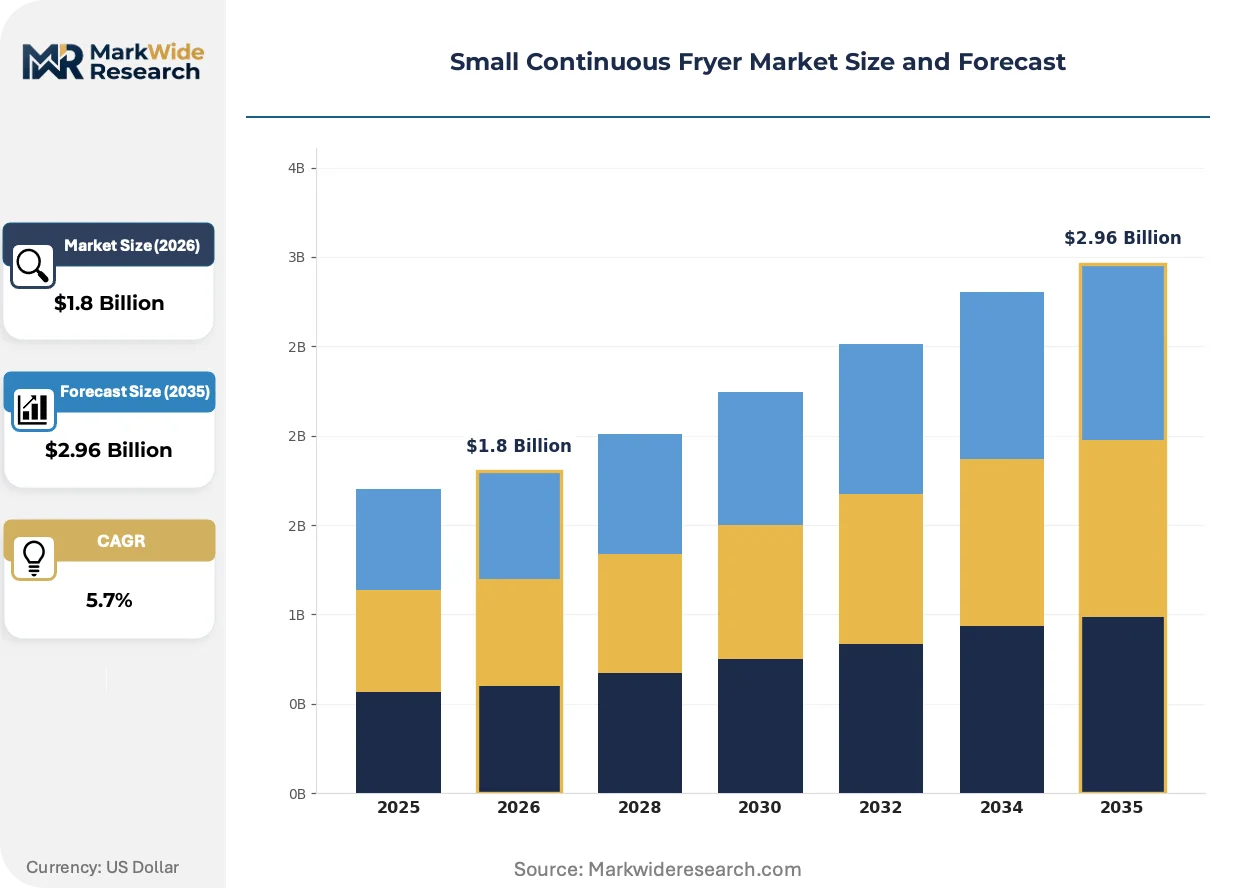
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fryer, Gas Fryer, Conveyor Fryer, Mini Fryer End User: Restaurants, Catering Services, Food Trucks, Snack Bars Installation: Countertop, Floor-Standing, Built-in, Portable Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Heat and Control, EMA Europe, Tecnofryer, SunMax, TJF, Pacific, M.Serra, FMT, PSG Dallas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Continuous Fryer Market Evolving Landscape
Automation and thermal engineering are converging to compress operational labor requirements while extending equipment service intervals through predictive subsystems.
Induction heating elements are modularizing fryer architecture, allowing kitchen operators to swap thermal modules without full equipment replacement. High-volume quick-service chains in the Netherlands pilot these configurations to reduce downtime during peak service windows. The shift is compressing capital expenditure cycles from monolithic replacement toward component-level refresh strategies.
EU F-Gas Regulation constraints on refrigerant-based ancillary systems are redirecting R&D investment toward passive oil-cooling designs. Manufacturers serving French and Italian markets accelerate heat-exchanger development to maintain export eligibility. The policy is elevating electric fryer competitiveness against gas alternatives in carbon-intensity benchmarking schemes.
Service unbundling is separating hardware procurement from oil-management subscriptions across North American food-processing accounts. Operators in Texas and California now contract filtration and disposal separately from capital equipment, compressing upfront outlays while locking in recurring revenue for vendors. The model is most visible in multi-unit restaurant groups with centralized procurement functions.
Small Continuous Fryer Market Segmentation
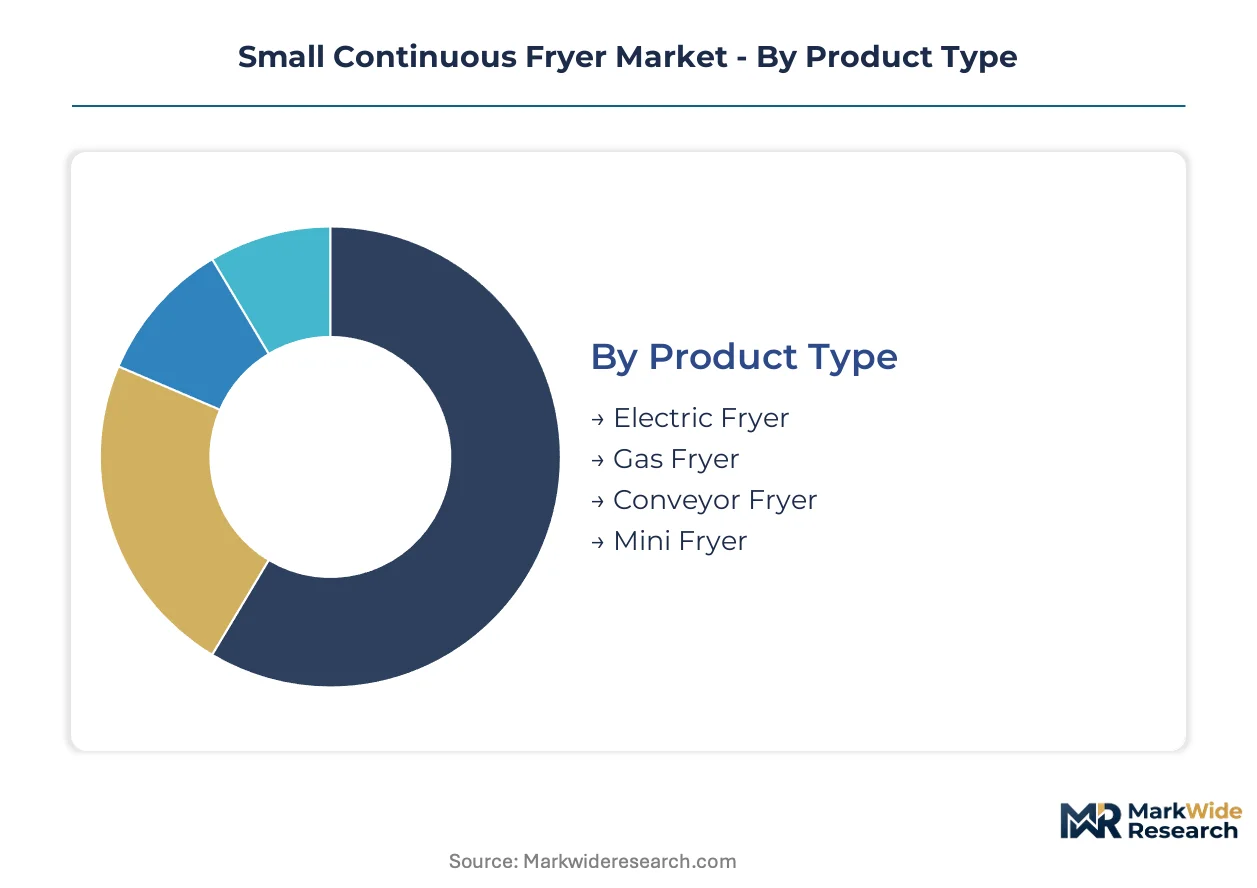
Small continuous fryer segmentation reveals how thermal architecture, deployment constraints, and procurement channels reshape vendor strategies. Equipment specifications vary sharply across electric and gas configurations, while installation type determines access to urban commercial kitchens versus mobile foodservice operations.
Product Type:
Thermal-system design defines operational economics and regulatory compliance trajectories across commercial kitchen deployments.
- Electric Fryer:Grid-connected heating elements deliver precise temperature control between 160°C and 190°C with lower ventilation requirements. Demand concentrates in Germany and the United Kingdom where carbon-intensity benchmarks favor electric architectures over fossil-fuel alternatives.
- Gas Fryer:Natural-gas or propane burners achieve faster heat recovery rates for high-throughput operations. North American quick-service chains in Texas and California retain cost advantages where utility tariffs favor gas over grid electricity.
- Conveyor Fryer:Belt-driven continuous processing systems automate product throughput without batch interruption.
- Mini Fryer:Compact footprints below 400mm width serve constrained kitchen layouts and mobile catering setups.
Mature deployment sits with gas fryers in established North American quick-service infrastructure. Newer deployment is concentrated in electric configurations across European commercial kitchens facing tightening energy-efficiency mandates.
End User:
Volume requirements and labor availability differentiate procurement priorities across foodservice operator categories.
- Restaurants:Full-service and quick-service establishments drive equipment replacement cycles as energy-efficiency mandates compress historical ten-year baselines. German and UK chain operators prioritize automated oil-management to reduce labor exposure.
- Catering Services:Event-based food production demands equipment mobility and rapid setup capabilities without permanent ventilation infrastructure.
- Food Trucks:Mobile operators require countertop configurations with minimal exhaust-duct dependencies for festival and street-service deployment.
- Snack Bars:Limited kitchen footprints in urban retail locations favor compact electric architectures where structural constraints prohibit gas-line installation.
High-volume procurement dominates quick-service restaurant chains with centralized purchasing functions. Emerging deployment clusters in food trucks and mobile catering operators seeking equipment flexibility without permanent installation requirements.
Installation:
Physical deployment constraints determine ventilation requirements, mobility options, and kitchen layout compatibility.
- Countertop:Surface-mounted units below 600mm height eliminate floor-space requirements and exhaust-duct dependencies. Food trucks and festival operators in France and Italy drive demand for configurations operable without permanent ventilation infrastructure.
- Floor-Standing:Vertical architectures accommodate larger oil reservoirs and higher throughput capacities for high-volume quick-service environments. Chain operators in the Netherlands and Belgium deploy these configurations for centralized production lines.
- Built-in:Custom-integrated installations align with architectural specifications in premium hospitality settings.
- Portable:Castor-mounted or modular designs enable repositioning across kitchen zones or temporary event setups.
Established deployment concentrates in floor-standing configurations across high-throughput quick-service infrastructure. Expanding deployment is visible in countertop units serving urban restaurant footprints with constrained kitchen layouts.
Distribution Channel:
Procurement pathway selection reflects operator scale, technical support requirements, and capital expenditure preferences.
- Online Retail:Direct-to-operator digital platforms compress procurement timelines for standardized configurations. Independent restaurants and small catering operators in Spain and Portugal leverage price transparency and rapid delivery for replacement equipment.
- Specialty Stores:Physical showrooms with technical consultation support complex specification decisions for first-time buyers.
- Supermarkets:Mass-market retail channels serve entry-level residential and light-commercial segments with limited after-sales support.
- Wholesale:Volume procurement agreements serve multi-unit restaurant groups and foodservice distributors with consolidated logistics.
Traditional procurement flows through specialty stores and wholesale channels for commercial-grade equipment. Digital migration is accelerating in online retail as smaller operators prioritize price transparency and reduced procurement friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for precision thermal equipment, with Baden-Württemberg's industrial corridor driving automated fryer deployment across food-processing clusters. Equipment specifications diverge sharply between carbon-intensity benchmarking regimes in European capitals and tariff-driven fuel economics in North American quick-service hubs.
Germany
Quick-service chains in Berlin and Hamburg prioritize electric fryer architectures to meet federal carbon-reduction benchmarks for commercial kitchens. The EU F-Gas Regulation constrains refrigerant-based oil-cooling systems in Bavarian food-processing facilities. Stuttgart's manufacturing corridor hosts thermal-system component suppliers serving automated oil-management integration.
United States
Texas and California quick-service operators retain gas fryer cost advantages where utility tariffs favor natural gas over grid electricity. OSHA hot-oil exposure guidelines extend equipment certification timelines by eight to fourteen months for domestic-bound manufacturers. Dallas-Fort Worth procurement clusters drive centralized purchasing for multi-unit restaurant groups seeking service unbundling.
United Kingdom
London's constrained urban restaurant footprints favor compact electric configurations where exhaust-duct installation faces structural prohibitions. Carbon-intensity benchmarking for grid-connected kitchens accelerates displacement of gas alternatives in Greater Manchester and Birmingham foodservice operations. CE marking alignment under the EU Machinery Directive shapes aftermarket service standardization for cross-border equipment.
France
Parisian snack bars and urban retail kitchens drive countertop unit demand for mobility without permanent ventilation infrastructure. EU F-Gas Regulation redirects R&D investment toward passive oil-cooling heat-exchanger designs in Lyon and Marseille manufacturing zones. French regulatory pressure elevates electric fryer competitiveness in national carbon-accounting schemes.
Netherlands
High-volume quick-service chains in Amsterdam and Rotterdam pilot modular induction heating elements to compress downtime during peak service windows. Belt-speed precision controls enable product consistency across centralized production lines in Eindhoven's food-tech corridor. The shift from monolithic replacement toward component-level refresh strategies concentrates vendor relationships in Randstad procurement clusters.
Small Continuous Fryer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the small continuous fryer space, with integrated thermal-system manufacturers holding pricing power against modular assemblers sourcing from southern China. The vendor base stratifies into three archetypes: vertically integrated thermal-component producers, specialized European aftermarket service networks, and compact-electric architects for urban footprints. Dominant competitive moves include backward integration into thermal subsystems and geographic expansion through CE marking harmonization for standardized service networks.
Within the integrated-manufacturing tier, Heat and Control and EMA Europe occupy positions reflecting divergent regional anchoring. Heat and Control exemplifies North American vertical integration into thermal-system components, while EMA Europe represents specialized European aftermarket service network concentration. Tecnofryer sits within the compact-electric specialization vector, serving constrained kitchen layouts through urban-focused architectural differentiation.
| Leading Market Players |
|---|
| Heat and Control |
| EMA Europe |
| Tecnofryer |
| SunMax |
| TJF |
| Pacific |
| M.Serra |
| FMT |
| PSG Dallas |
| Others |
Value Network & Pricing Analysis
Multi-unit quick-service restaurant groups with centralized procurement functions dictate contract structures that bundle hardware capital expenditure with recurring oil-management subscriptions. Their consolidated purchasing power compresses upfront equipment margins while locking vendors into long-term service revenue streams.
Pricing Analysis
Value-based pricing anchored to throughput uptime and frying-medium yield preservation dominates commercial-grade equipment contracts. Three-tier pricing structure across premium, standard, and economy levels separates automated oil-filtration systems from basic thermal configurations from entry-level countertop units. Price differentiation rests on CE certification grade and after-sales service bundling intensity. Cost compression in standard-tier electric architectures is intensifying because stainless steel input volatility from Turkish mills squeezes fabrication margins. Independent restaurants and food trucks exhibit highest price sensitivity, while industrial food-processing accounts prioritize yield consistency over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Netherlands and Belgium quick-service chains, while specialty distributors serve fragmented independent restaurant accounts across Southern Europe. Thermal-system component production clusters in southern China, Germany, and Italy create geographic concentration for heating elements, conveyor mechanisms, and control systems. Raw material dependencies on 304-grade stainless steel, copper windings for electric elements, and precision bearings for belt drives expose assemblers to commodity price swings. Single-source vulnerability from southern Chinese thermal-component suppliers presents structural risk for North American fryer assemblers lacking dual-sourcing alternatives. Distribution runs through wholesale agreements for multi-unit groups and online retail platforms for smaller operators seeking price transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric fryer architectures are displacing gas configurations across European commercial kitchens, creating a technology-transition phase as grid-connected operations face tightening carbon-intensity benchmarks.
For Market Incumbents: Extend backward integration into thermal-system components to defend margin position against modular assemblers sourcing from southern China. Captive production of heating elements and conveyor mechanisms insulates pricing power from input volatility. Incumbents must accelerate CE marking alignment for standardized aftermarket service networks across Benelux and Nordic markets before regulatory harmonization closes competitive windows. For New Entrants and Emerging Players: Enter via compact electric architectures targeting London and Paris urban restaurant footprints where structural constraints prohibit exhaust-duct installation and gas-line penetration. Food trucks and mobile catering operators in France and Italy represent the most penetrable segment, with countertop configurations operable without permanent ventilation infrastructure. A direct-to-operator digital platform with rapid delivery logistics offers the strongest go-to-market angle against established wholesale channels. For Investors and Strategic Acquirers: The window for entry favors specialized European aftermarket service networks with CE marking capabilities and localized technical support infrastructure. Long-term viability hinges on recurring revenue attachment rates from oil-management subscriptions rather than hardware margins alone. Watch induction heating element modularity adoption in Netherlands quick-service pilot programs as the inflection signal for component-level refresh strategies displacing monolithic replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Components | Captive supply of heating elements insulates Heat and Control from stainless steel price volatility in Turkish mills. |
| CE Marking Harmonization for Service Networks | Standardized aftermarket protocols enable EMA Europe to scale cross-border maintenance contracts across Benelux markets. |
| Compact Electric Architecture Development | Tecnofryer's urban-focused designs penetrate London snack bars where exhaust-duct installation faces structural prohibitions. |
| Induction Heating Element Modularity | Swappable thermal modules compress downtime for Netherlands quick-service chains during peak service windows. |
| Service Unbundling and Subscription Models | Separated filtration contracts lock recurring revenue from Texas multi-unit restaurant groups with centralized procurement. |
Research Methodology
Independent corroboration across equipment OEM technical directors, quick-service restaurant procurement heads, and commercial kitchen maintenance contractors underwrites the qualitative findings. Primary interviews with thermal-system component suppliers, foodservice distribution channel managers, and aftermarket service network operators combined with secondary validation from EU Machinery Directive documentation, OSHA compliance filings, and customs trade data for stainless steel imports. Bottom-up equipment shipment analysis and top-down commercial kitchen capital expenditure estimates provide triangulation checks across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across electric and gas thermal architectures, floor-standing and countertop installation types, and wholesale versus online retail distribution channels. Segmentation modeling incorporates product type, end-user category, installation configuration, and procurement channel dimensions throughout the forecast period. CAGRs derive from fitted growth curves against historical replacement cycle compression and regulatory mandate acceleration timelines. Oil-degradation sensor accuracy thresholds and F-Gas Regulation compliance cost trajectories serve as industry-specific forecast inputs.
Revisions become necessary when EU carbon-intensity benchmarking tightens beyond current trajectories, southern Chinese supply disruptions materialize, or oil-filtration technology breakthroughs displace predictive maintenance efficacy assumptions. Forecasts reflect documented assumptions regarding equipment replacement cycle elasticity and subscription service attachment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market